
 Europe Carbon Fiber Market | 2026-2036
Europe Carbon Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Carbon Fiber Market Foresight
Wind energy OEMs is redrawing procurement priorities across the Europe carbon fiber landscape. SGL Carbon dominates precursor supply for onshore turbine blades manufactured in Germany and Portugal. Solvay leverages its thermoplastic composite expertise to serve aerospace tier suppliers in France and Belgium. Hexcel Corporation anchors its European position through specialized prepreg formulations for defense and satellite programs.
Carbon fiber consists of filaments 5–10 micrometers in diameter composed primarily of carbon atoms, produced through controlled pyrolysis of polyacrylonitrile (PAN) or pitch precursors at temperatures exceeding 1,000°C to achieve high tensile strength-to-weight ratios for structural reinforcement. Prepregs lead margin capture due to their value-added resin integration and refrigerated supply chain requirements. Pan-based technology occupies the volume majority across European manufacturing, while bio-based alternatives compete on sustainability credentials for automotive interior applications. Continuous form sustains premium positioning in aerospace primary structures, whereas chopped fiber extends into injection-molded automotive brackets and consumer electronics housings.
The EU Green Deal and REACH framework mandate lifecycle emissions transparency for carbon fiber production, pushing manufacturers toward renewable energy-powered oxidation and carbonization lines. ECHA substance restrictions on acrylonitrile handling are elevating capital requirements for new precursor facilities in Eastern Europe. CSRD disclosure rules will force tier-two composite fabricators to document Scope 3 embedded carbon. Stakeholders must decide whether to backward integrate into precursor production or lock long-term offtake agreements with low-carbon verified suppliers before regulatory thresholds tighten further.
Market Dynamics
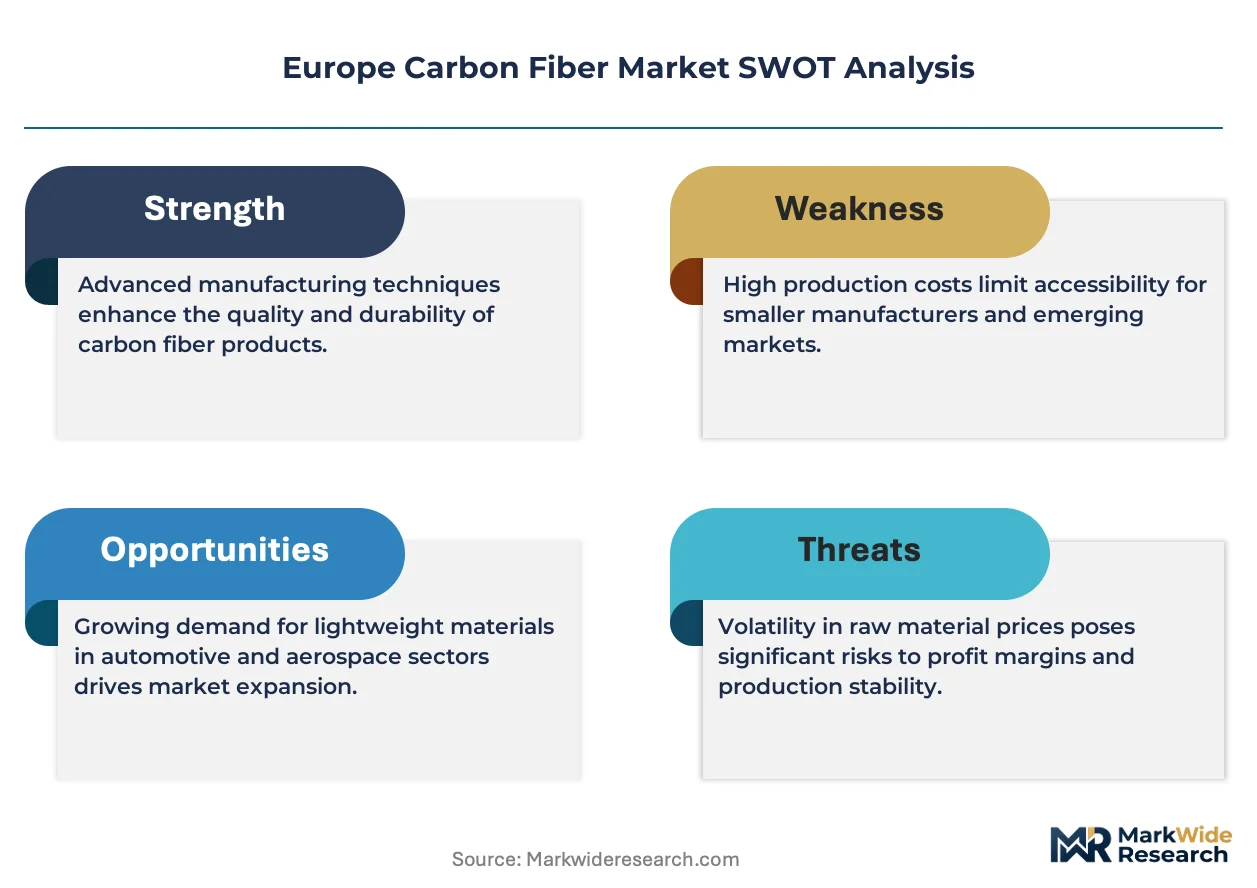
The EU Green Deal and REACH compliance mandates are compressing the acceptable emissions envelope for carbon fiber production, forcing manufacturers to reconfigure oxidation and carbonization lines around renewable energy sourcing while documenting embedded carbon across Scope 3 supply chains.
Growth Catalysts
- Aerospace composite penetration:OEMs are expanding wing structures and fuselage programs that substitute aluminum with carbon fiber primary structures, tightening weight-to-strength specifications for next-generation narrow-body and wide-body platforms.
- REACH lifecycle transparency:The regulatory framework mandates cradle-to-gate emissions accounting for precursor production, creating competitive advantage for facilities with verified low-carbon oxidation processes and renewable electricity contracts.
- Wind turbine blade scaling:Onshore and offshore rotor diameters exceeding 150 meters require carbon fiber spar caps to manage tip deflection loads, concentrating procurement volumes in Germany and Portugal manufacturing clusters.
Market Restraints
- Acrylonitrile price volatility:PAN precursor production consumes petroleum-derived acrylonitrile monomer, exposing margin structures to naphtha-cracker feedstock fluctuations and ECHA substance-handling compliance costs.
- Precursor supply concentration:European carbonization capacity depends on imported PAN fiber from a limited supplier base, creating vulnerability to trade friction and energy-cost differentials in Asian precursor manufacturing.
- Thermoplastic substitution in automotive:Glass-fiber-reinforced polypropylene and recycled carbon fiber compounds compete for non-structural interior applications where crash-performance specifications permit lower modulus materials.
Strategic Opportunities
- Eastern European manufacturing expansion:Greenfield precursor facilities in Poland and Romania can access lower-cost renewable electricity and proximity to German automotive and wind OEM assembly plants.
- Thermoplastic composite welding:Induction and ultrasonic joining technologies enable out-of-autoclave processing for aerospace secondary structures, reducing cycle times and capital intensity versus thermoset autoclave curing.
- CSRD-driven Scope 3 verification:The Corporate Sustainability Reporting Directive creates premium pricing power for suppliers with ISO 14064-certified carbon accounting and blockchain-tracked material provenance systems.
Industry Challenges
- Pyrolysis engineering talent scarcity:Carbonization furnace operation and precursor quality control require specialized chemical engineering expertise concentrated at legacy acrylics manufacturers, constraining workforce scaling for new facilities.
- Qualification timeline compression:Aerospace OEM material allowables and automotive crash-homologation cycles demand 18-36 month validation periods that conflict with procurement urgency for lightweighting program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Carbon Fiber Market |
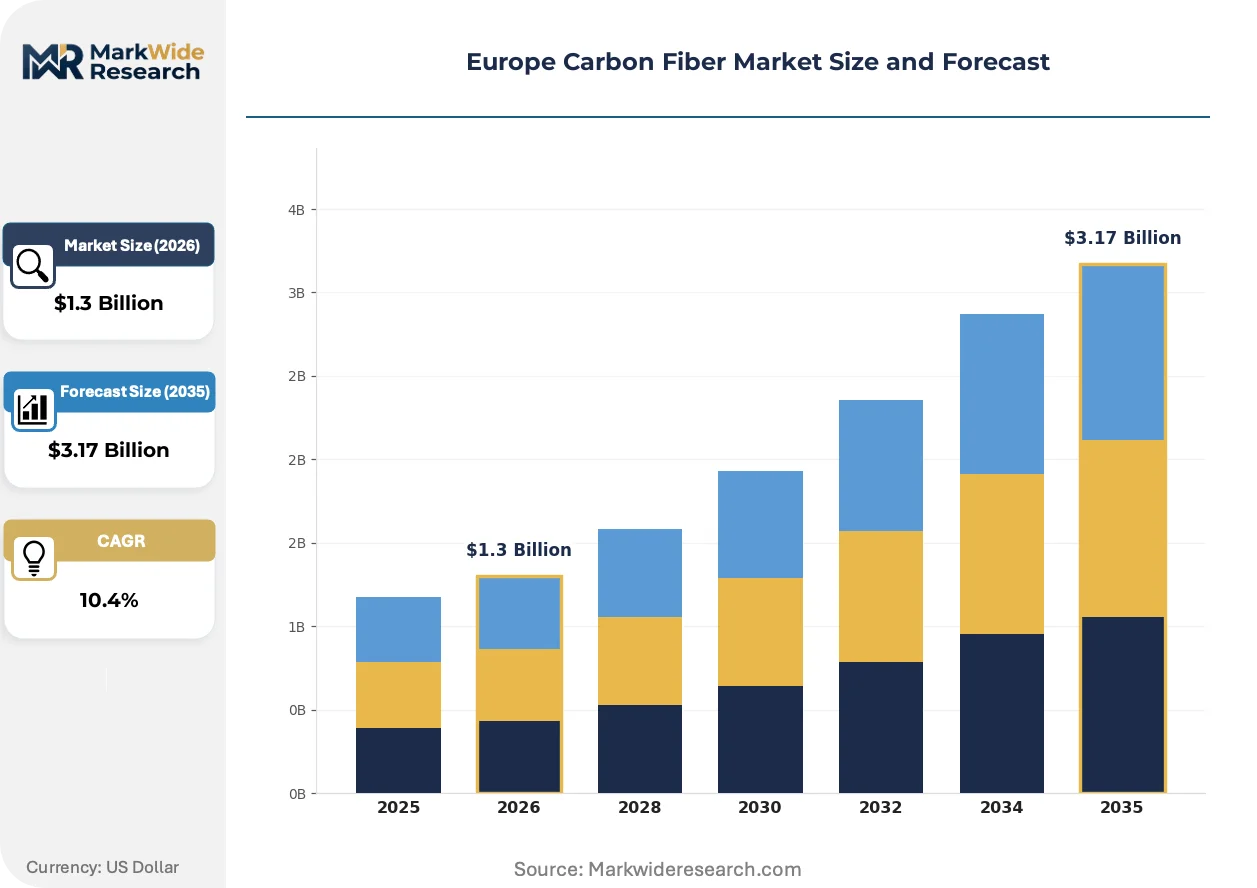
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $3.17 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tows, Sheets, Fabrics, Prepregs End User: Aerospace, Automotive, Wind Energy, Sporting Goods Form: Continuous, Chopped, Woven, Non-Woven Technology: Pan-Based, Pitch-Based, Bio-Based, Others |
| Companies Covered | Toray Industries, Mitsubishi Chemical, Solvay, Umatex Group, DowAksa, Hexcel Corporation, Teijin, Gen 2 Carbon, SGL Carbon, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Carbon Fiber Market Shifts & Advancements
European carbon fiber manufacturing is pivoting from commodity filament supply toward engineered prepreg systems with integrated resin formulations, while regulatory pressure on embedded emissions accelerates process electrification and bio-based precursor development.
Thermoplastic unidirectional tape is fragmenting the traditional thermoset prepreg dominance in aerospace secondary structures. Toray and Teijin are scaling PEEK and PPS matrix tape production for wing ribs and control surfaces. The shift enables automated fiber placement with in-situ consolidation, eliminating autoclave bottlenecks and reducing scrap rates in high-rate manufacturing environments.
CSRD disclosure rules are forcing tier-two composite fabricators to document embedded carbon across supply chains. The regulation requires audited Scope 3 emissions for carbon fiber-reinforced plastic components entering EU-assembled vehicles and aircraft. German automotive suppliers and French aerospace tiers are responding by mandating renewable-energy certificates from precursor and weaver subcontractors.
Long-term offtake contracting is displacing spot purchasing for PAN precursor and oxidized fiber intermediates. Wind turbine OEMs in Northern Germany and automotive tier suppliers in Southern Germany are locking five-to-seven-year supply agreements with fixed-volume, escalated-price structures. The pattern concentrates procurement leverage among buyers with balance-sheet capacity to underwrite supplier capital commitments for low-carbon production lines.
Europe Carbon Fiber Market Segmentation
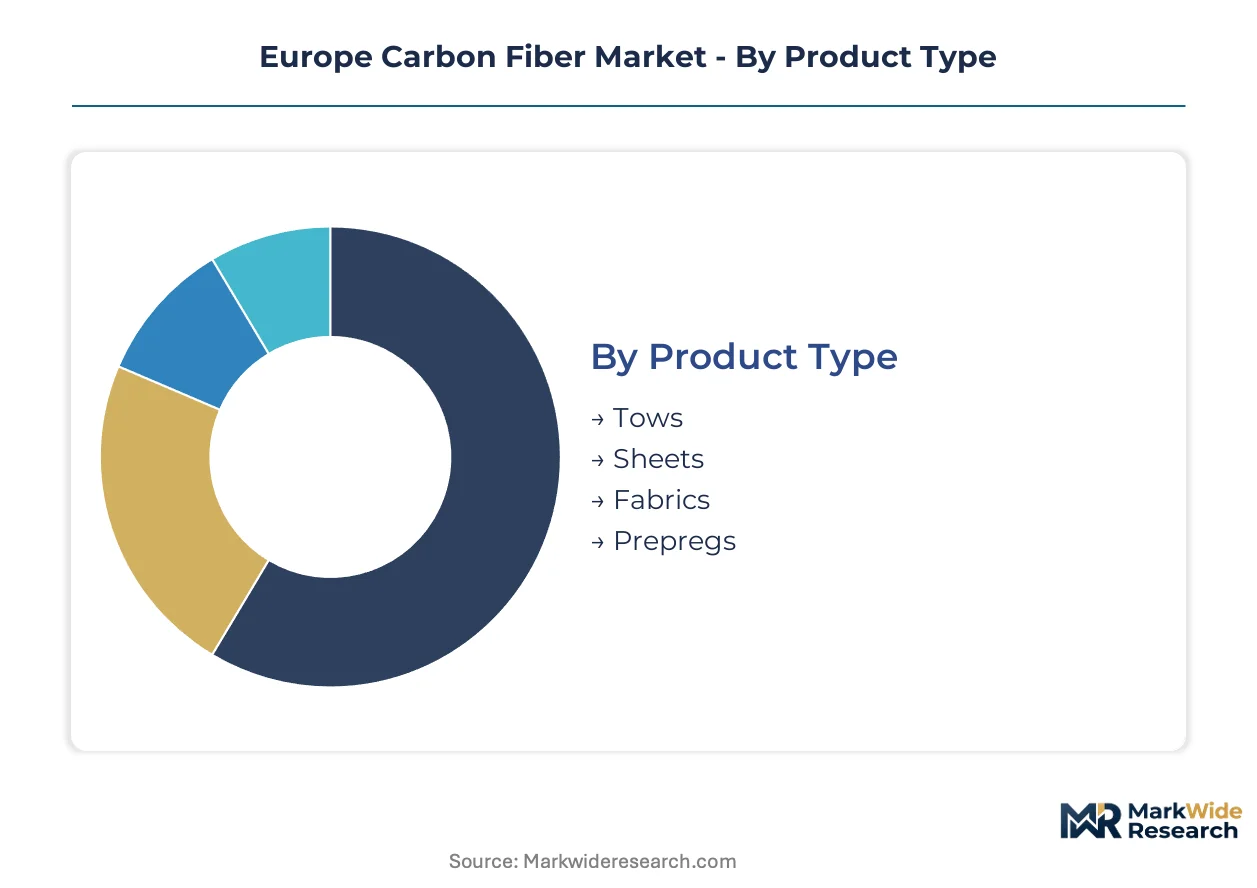
Carbon fiber segmentation in Europe reflects divergent supply chain economics across aerospace qualification cycles, automotive crash-homologation timelines, and wind energy blade scaling programs. Each product form and technology pathway commands distinct channel access, margin structures, and regulatory exposure under REACH and CSRD frameworks.
Product Type:
Tows and prepregs flow through specialized distributors serving aerospace tier suppliers, while sheets and fabrics reach automotive and wind OEMs via direct mill relationships with volume commitments.
- Tows:Bundles of untwisted continuous filaments serve as feedstock for weaving, pultrusion, and filament winding operations. German wind blade manufacturers in Bremen and Rostock anchor procurement volumes for spar cap infusion processes. By volume, tows lead. By growth pace, prepregs are ahead.
- Prepregs:Fiber pre-impregnated with catalyzed resin systems requiring frozen supply chains and controlled out-time tracking. French aerospace tiers in Toulouse and Nantes dominate demand for wing skin and control surface fabrication, with CSRD documentation mandates tightening supplier qualification.
- Sheets:Unidirectional or multidirectional layups for hot-press forming and autoclave curing. Italian automotive suppliers in Modena procure for structural battery enclosures in premium electric vehicle platforms.
- Fabrics:Woven architectures from plain to satin weaves for hand lay-up and resin transfer molding. Portuguese wind blade factories in Viana do Castelo specify heavy-tow fabrics for root section reinforcement.
Prepregs capture premium margin tiers through resin formulation IP and cold-chain logistics, while tows compete on carbonization yield rates and precursor energy sourcing.
End User:
Cost tier stratification separates aerospace qualification-heavy programs from automotive scale-driven procurement and wind energy capital-intensive blade manufacturing.
- Aerospace:Primary and secondary structural applications demand AS9100-certified material allowables with 18-36 month validation cycles. Airbus wing programs in Hamburg and Broughton concentrate European demand for intermediate-modulus tape and fabric systems.
- Wind Energy:Rotor blade spar caps and root inserts require high-modulus fiber to manage tip deflection loads across 150-meter-plus diameters. Northern German OEMs in Rostock and blade specialists in Portugal drive carbon fiber penetration as glass fiber reaches modulus limits.
- Automotive:Crash-critical structural members and non-structural body panels split between continuous fiber for B-pillars and chopped compounds for interior brackets. Bavarian premium OEMs specify thermoplastic composites for battery tray lightweighting.
- Sporting Goods:Bicycle frames, hockey sticks, and racing equipment prioritize aesthetic weave patterns and damped ride characteristics over structural certification. Italian manufacturers in Treviso and German specialists in Friedrichshafen sustain niche volume.
Aerospace commands the highest unit margins but slowest volume expansion; wind energy delivers the steepest demand trajectory as offshore turbine scaling accelerates.
Form:
Maturity gradients separate established continuous fiber supply from emerging chopped and non-woven formats competing for automotive cycle time reduction.
- Continuous:Uninterrupted filament lengths enabling directional strength optimization through lay-up orientation. Aerospace primary structures and wind spar caps in Germany and France sustain premium positioning through automated fiber placement qualification.
- Woven:Interlaced yarn architectures providing balanced in-plane properties and drapability for complex molds. Portuguese and Spanish blade manufacturers specify 5HS and 8HS weaves for aerodynamic shell fabrication.
- Chopped:Short fiber segments 3-50mm in length compounded with thermoplastic matrices for injection molding. German automotive tier suppliers in Stuttgart and Munich deploy for non-structural brackets where modulus requirements permit glass fiber substitution.
- Non-Woven:Random fiber orientation through carding and needle-punching for isotropic properties and rapid resin infusion. Emerging formats target automotive floor pans and battery protection plates with press-forming cycle times under 90 seconds.
Continuous fiber retains aerospace and wind energy dominance; chopped formats are expanding most quickly into automotive volume manufacturing.
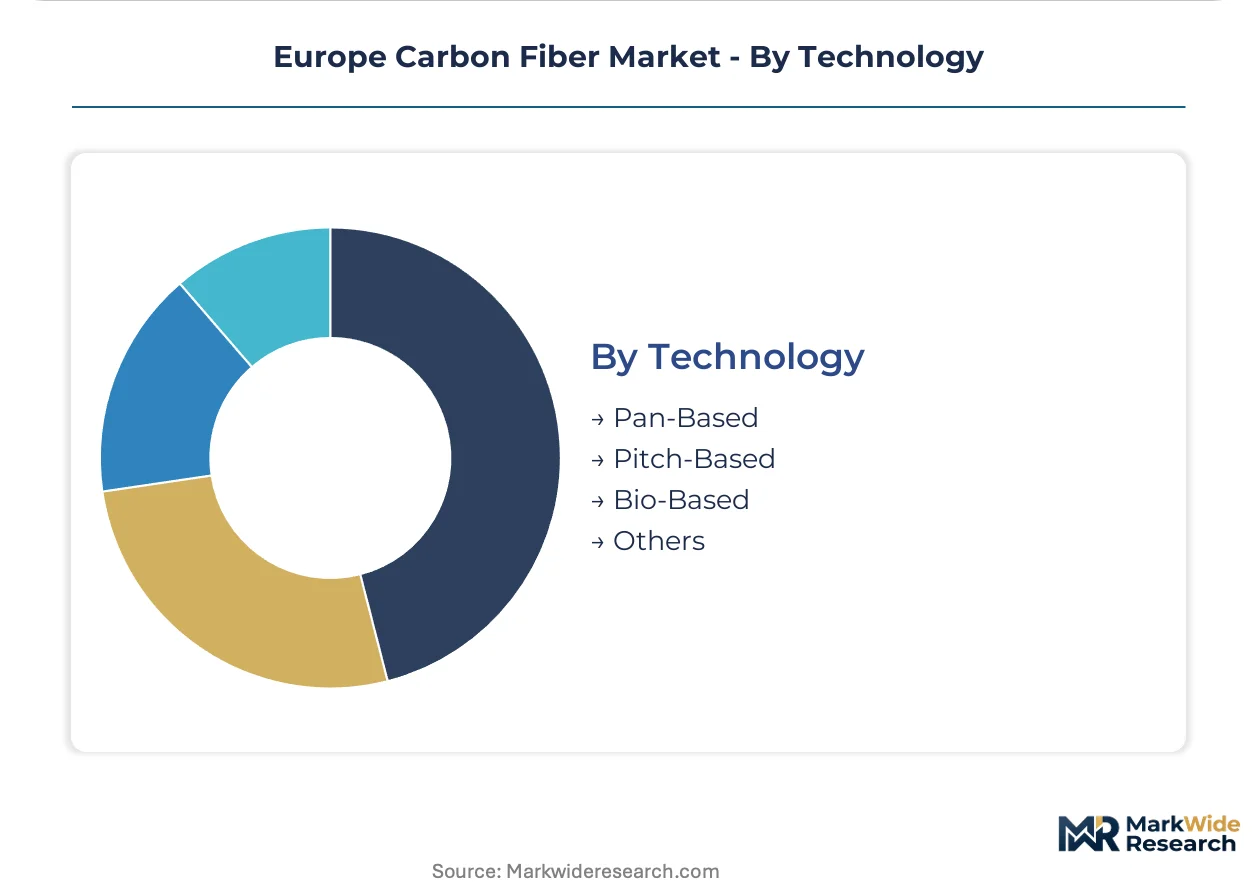
Technology:
Supply concentration for polyacrylonitrile precursor creates vulnerability exposure, while bio-based alternatives compete on EU Green Deal alignment for interior automotive applications.
- Pan-Based:Polyacrylonitrile precursor carbonization yields high-strength intermediate-modulus fiber for structural load-bearing. European carbonization capacity in Germany and Hungary depends on imported precursor, with ECHA acrylonitrile handling rules elevating Eastern European greenfield costs. Pitch-Based: Mesophase pitch precursor delivers ultra-high modulus for satellite structures and specialized aerospace applications. Limited to defense and space programs due to petroleum pitch feedstock scarcity and complex stabilization chemistry.
- Bio-Based:Lignin and cellulose precursors from forestry waste streams targeting automotive interior panels where structural modulus requirements are relaxed. Finnish and Swedish pilot facilities pursue EU Green Deal funding for commercial scale-up.
- Others:Experimental pathways including polyethylene and rayon precursors, plus recycled carbon fiber pyrolysis reclamation. French and German research consortia evaluate circular economy compliance for CSRD Scope 3 reduction.
Pan-based technology anchors volume manufacturing; bio-based alternatives are gaining share fastest on sustainability credential differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German carbon fiber exports flow primarily to French aerospace assembly plants and Portuguese wind blade factories, establishing a north-south trade corridor that concentrates procurement leverage in Hamburg and Bremen port zones.
Germany
Automotive lightweighting programs at BMW and Mercedes-Benz anchor industrial demand for thermoplastic composites, while Nordex and Siemens Gamesa blade factories in Rostock consume high-modulus fiber for offshore turbine spar caps. The EU Green Deal's embedded carbon reporting requirements through CSRD are forcing Bavarian tier suppliers to document Scope 3 emissions from precursor imports. Carbonization facilities in Bavaria and Lower Saxony are retrofitting oxidation lines to run on renewable electricity contracts verified under Guarantees of Origin.
France
Airbus wing assembly at Toulouse and Nantes drives qualification-heavy procurement of intermediate-modulus prepreg systems with 18-month material allowable cycles. REACH compliance mandates from ECHA are elevating documentation burdens for acrylonitrile handling in precursor supply chains feeding Châteauroux carbonization plants. The aerospace cluster around Bordeaux is expanding automated fiber placement capacity for A350 secondary structures.
Spain
Wind energy OEMs in Castilla-La Mancha and Galicia are scaling rotor blade manufacturing beyond 150-meter diameters, requiring carbon fiber spar caps to manage tip deflection loads. Spanish renewable energy auctions are accelerating demand for turbine components with domestic content requirements. Composite fabricators in Vitoria-Gasteiz are qualifying thermoplastic welding processes for automotive battery tray applications.
Portugal
Onshore wind blade factories in Viana do Castelo and Aveiro anchor Southern European carbon fiber consumption for spar cap infusion and root section reinforcement. The country's grid interconnection with Spain enables renewable electricity sourcing for composite curing operations. Portuguese industrial policy is channeling EU cohesion funds toward testing facilities for bio-based precursor validation.
Italy
Premium automotive suppliers in Modena and Emilia-Romagna procure carbon fiber sheets for structural battery enclosures in electric supercar platforms. The Italian National Recovery and Resilience Plan is allocating capital toward thermoplastic composite press-forming lines with sub-90-second cycle times. Sporting goods manufacturers in Treviso sustain niche demand for aesthetic weave patterns in bicycle frames and racing equipment.
Europe Carbon Fiber Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive precursor supply and specialized carbonization specialists serving aerospace qualification programs. Market structure concentrates around three tiers: PAN precursor producers with backward integration into carbonization, independent weavers and prepreg formulators dependent on imported fiber, and recycled fiber reclaimers targeting automotive circular economy mandates. Dominant competitive moves include long-term offtake contracting with wind OEMs and renewable electricity sourcing for oxidation line decarbonization.
Among Japanese-origin conglomerates, Toray Industries and Mitsubishi Chemical exemplify the integrated precursor-to-composite archetype with European carbonization assets. Solvay occupies a position within the specialty chemicals tier, leveraging thermoplastic matrix expertise for aerospace tier supply. SGL Carbon anchors the independent carbonization specialist segment with German manufacturing proximity to automotive and wind OEM clusters. These three archetypes represent the competitive vectors shaping procurement leverage and sustainability credential differentiation under CSRD disclosure rules.
| Leading Market Players |
|---|
| Toray Industries |
| Mitsubishi Chemical |
| Solvay |
| Umatex Group |
| DowAksa |
| Hexcel Corporation |
| Teijin |
| Gen 2 Carbon |
| SGL Carbon |
| Others |
Supply & Pricing Matrix
Eighteen-month qualification timelines for aerospace material allowables concentrate pricing power among incumbent suppliers with certified oxidation lines, while German automotive procurement teams exploit renewable electricity sourcing requirements to extract cost concessions from precursor importers.
Pricing Analysis
Pan-based carbonization technology commands a 15-20% premium over pitch-based alternatives for structural aerospace applications, while bio-based precursor development trails at economy-tier positioning for automotive interior panels. Pricing stratifies across premium, standard, and economy tiers based on modulus certification grade and volume commitment scale. Cost compression in standard-grade tows is intensifying because wind OEMs are consolidating procurement through five-year offtake agreements with fixed-escalation structures. Automotive tier suppliers exhibit the highest price sensitivity due to thermoplastic substitution threats, whereas satellite programs accept premium pricing for ultra-high modulus fiber.
Supply Chain Analysis
Germany and Hungary anchor European carbonization capacity, while Japan and South Korea control polyacrylonitrile precursor supply through integrated chemical conglomerates. European manufacturers draw from petroleum-derived acrylonitrile monomer, mesophase pitch feedstock, and experimental lignin precursors from Nordic forestry operations. Single-source vulnerability concentrates in imported PAN fiber supply, exposing margin structures to energy-cost differentials in Asian precursor manufacturing. Distribution runs through specialized prepreg distributors serving French aerospace tiers and direct mill relationships for German wind blade manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass-fiber-reinforced polypropylene and recycled carbon fiber compounds threaten structural market share in non-critical automotive applications, forcing incumbent carbon fiber suppliers to defend positioning through certification-heavy aerospace programs and renewable energy credentials.
For Market Incumbents: Secure long-term offtake agreements with Northern German wind OEMs before Eastern European greenfield capacity enters qualification cycles. Backward integration into precursor production or exclusive partnerships with low-carbon verified suppliers will defend margin structures against ECHA acrylonitrile handling cost escalations.
For New Entrants and Emerging Players: AS9100-D certification fast-track programs for aerospace tier supply offer the most penetrable entry vector against established Japanese conglomerates. Target Portuguese wind blade factories with bio-based precursor validation partnerships, leveraging EU cohesion funding for testing facility access.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermoplastic composite welding equipment and automated fiber placement systems. Five-to-ten-year viability favors acquisition of independent carbonization specialists with German manufacturing proximity and existing renewable electricity contracts. Watch for CSRD disclosure threshold tightening as the inflection signal for Scope 3 verification premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | ECHA acrylonitrile handling rules elevate captive supply economics for German carbonization facilities. |
| Long-term Supply Agreement with Wind OEMs | Nordex and Siemens Gamesa blade factories in Rostock lock volume commitments through 2030. |
| Renewable Electricity Sourcing Certification | Guarantees of Origin verification enables CSRD-compliant Scope 3 disclosure for French aerospace tiers. |
| Thermoplastic Composite Welding Scale-up | Induction joining technologies eliminate autoclave bottlenecks for Airbus A350 secondary structures. |
| Bio-based Precursor Pilot Validation | Finnish lignin facilities pursue EU Green Deal funding for automotive interior panel commercialization. |
Research Methodology
Desk research of ECHA substance restriction filings, EU customs trade data, and aerospace OEM material qualification databases preceded structured interviews with carbonization plant managers, wind blade procurement leads at German OEMs, prepreg distribution channel partners, and REACH compliance officers at French chemical conglomerates. Bottom-up volume estimates from individual facility capacity disclosures were triangulated against top-down demand projections from automotive lightweighting program announcements and wind turbine installation forecasts.
Variance decomposition across product type, end-use industry, form factor, and technology pathway enabled segment-level growth attribution throughout the forecast period. CAGRs were derived from regression analysis against carbon fiber content per vehicle trajectories, rotor blade scaling curves, and aerospace build-rate assumptions. Forecast inputs incorporated EU Green Deal implementation timelines, CSRD disclosure phase-in schedules, and renewable electricity contract penetration rates at oxidation facilities.
Decision-makers should treat outputs as directional under assumptions of sustained EU emissions benchmark tightening and no major trade friction in Asian precursor supply; material deviation would warrant model refresh. Recalibration cycles align with ECHA regulatory amendments and aerospace program launch delays.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Renewable Carbon Fibers Market
Fibers
Vinylon Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Global Nylon Monofilament Market
Fibers
Fiberglass Cloth Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Thermoformed Fiber Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Global Fiberglass Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Global Metal Fiber Market
Fibers
Global Fiberglass Mold Market
Fibers
Short Fiber Thermoplastics Market