
 PAN-Based Carbon Fibers Market | 2026-2036
PAN-Based Carbon Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
PAN-Based Carbon Fibers Market Outlook
Asset-light leasing models for carbon fiber precursor plants is fragmenting competitive entry barriers across the value chain. Toray Industries, Inc. leverages captive acrylonitrile supply to anchor cost positions in high-strength tow production. Hexcel Corporation specializes in aerospace-qualified prepregs and dominates narrow-body platform qualification programs. SGL Carbon extends vertical control from PAN polymerization through carbonization, sustaining margin capture across intermediate modulus grades.
PAN-based carbon fibers are synthetic fibers produced from polyacrylonitrile precursor through controlled oxidation and carbonization at temperatures exceeding 1000°C, yielding carbon content above 90% and tensile modulus ranging from 230 to 600 GPa depending on processing severity. These fibers primarily reinforce polymer matrix composites where stiffness-to-weight ratio governs structural performance. High Strength fibers lead volume shipments across wind energy blade spar caps and automotive structural members, while Ultra High Modulus grades command premium positioning in satellite bus structures and optical benches where dimensional stability under thermal cycling is paramount. Aerospace applications concentrate demand for Intermediate Modulus tows in primary flight control surfaces, with prepreg form factors capturing disproportionate value relative to raw fiber.
FAA airworthiness directives and EASA CS-25 certification standards govern carbon fiber composite structural integrity for commercial aviation, forcing precursor quality documentation and batch traceability through entire manufacturing records. EPA emissions frameworks and REACH substance restrictions shape acrylonitrile handling protocols and carbonization off-gas treatment investments at production facilities. Stakeholders must monitor evolving automotive crashworthiness regulations and wind turbine recyclability mandates to align product qualification roadmaps with end-of-life material recovery requirements.
Market Dynamics
Aerospace OEM qualification timelines and EU carbon-intensity mandates are compressing the viable supplier base to those with documented precursor traceability and low-emission carbonization assets.
Growth Catalysts
- EU Green Deal carbon benchmarks:Industrial end-users in Germany and France now specify low-carbon-intensity fiber grades, pulling investment toward electrified carbonization furnaces and renewable energy-powered production.
- Wind turbine blade scaling:Offshore platforms exceeding 15 MW capacity require longer spar caps that only high-strength PAN-based tows can reinforce cost-effectively.
- Automotive structural electrification:Battery enclosure manufacturers in South Korea and Japan are qualifying carbon fiber composites to offset EV platform weight penalties.
Market Restraints
- Acrylonitrile cost volatility:Propylene-ammonia feedstock price swings directly compress carbon fiber gross margins, with no viable chemical substitute for PAN precursor synthesis.
- Carbonization furnace concentration:High-temperature processing equipment suppliers cluster in Germany and Japan, creating single-source risk for capacity expansion.
- REACH substance documentation:ECHA registration requirements for modified PAN copolymers extend precursor qualification timelines by 18-24 months.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for advanced materials are attracting prepreg toll manufacturers to Gujarat and Tamil Nadu industrial corridors.
- Hydrogen storage pressure vessels:Type IV composite tank standards are converging with carbon fiber performance specifications, opening a new demand vertical.
- Digital fiber traceability:Blockchain-integrated batch records are enabling premium pricing for aerospace-qualified tows with immutable provenance documentation.
Industry Challenges
- Carbonization operator scarcity:Specialized furnace technicians with 1000°C+ process control expertise command wage premiums that inflate production costs.
- FAA/EASA dual certification:Parallel airworthiness documentation for new fiber grades extends time-to-revenue by 3-4 years for aerospace suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PAN-Based Carbon Fibers Market |
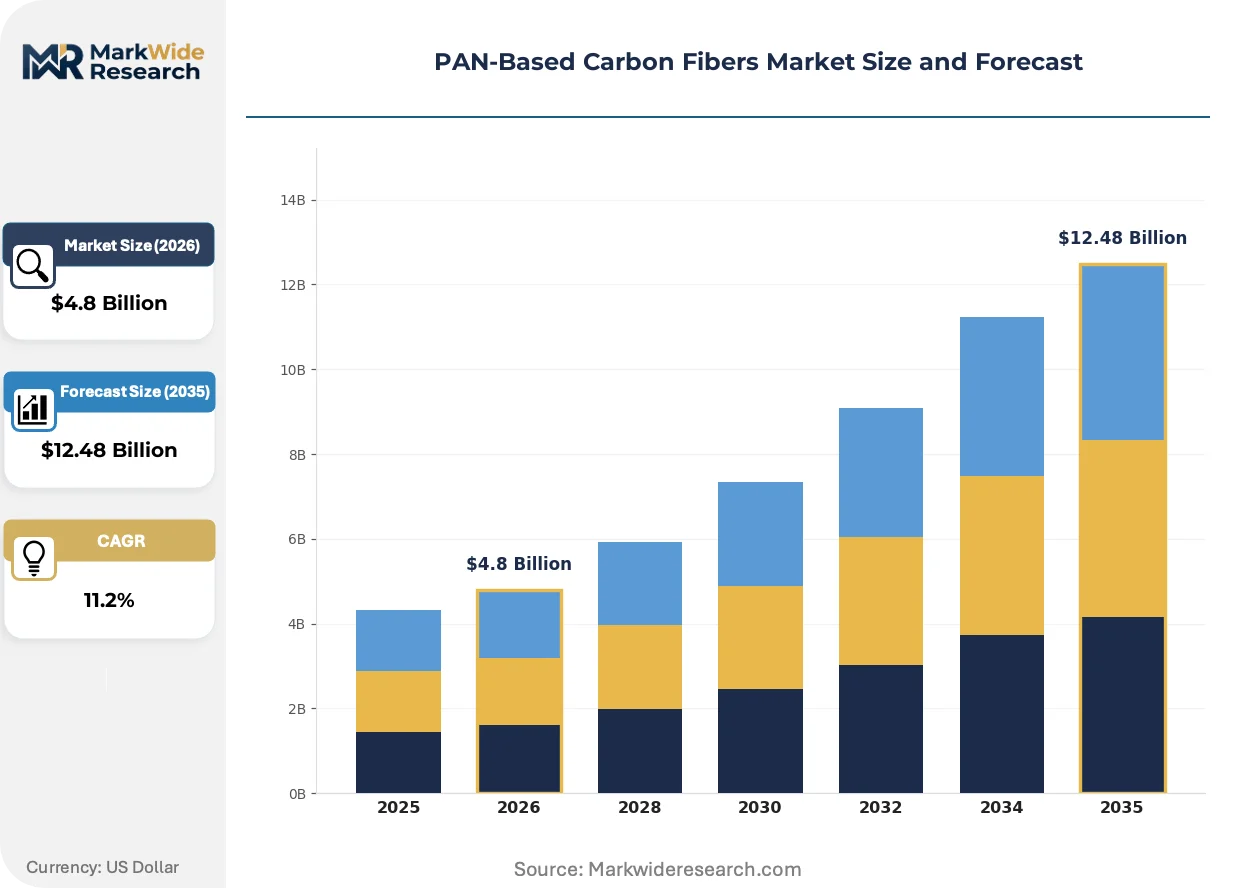
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Modulus, High Strength, Intermediate Modulus, Ultra High Modulus Application: Aerospace, Automotive, Sporting Goods, Wind Energy End User: Composite Manufacturing, Automotive OEMs, Aerospace Industry, Industrial Applications Form: Tows, Fabrics, Prepregs, Continuous Filaments |
| Companies Covered | SGL Carbon, Syensqo, Toray Industries, Inc., Zoltek Corporation, Hyosung Advanced Materials, Teijin Limited, Hexcel Corporation, Formosa Plastics Corporation, Mitsubishi Chemical Carbon Fiber and Composites, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PAN-Based Carbon Fibers Market Strategic Shifts
Process intensification and regulatory digitization are redrawing competitive boundaries between integrated precursor-to-fiber producers and specialized downstream converters.
Plasma-assisted oxidation technology is migrating from laboratory demonstration to pilot-scale deployment at Japanese and German facilities. Aerospace prepreg manufacturers are qualifying these lower-energy precursor stabilization routes to meet Scope 3 emissions targets. The shift is compressing energy intensity benchmarks and disqualifying conventional thermal oxidation assets from premium supply contracts.
REACH substance restriction amendments are tightening acrylonitrile handling protocols and mandating real-time emissions monitoring at carbonization facilities. ECHA enforcement is forcing capital allocation toward off-gas scrubbing and thermal oxidizer upgrades. German production sites face the steepest compliance costs, accelerating consolidation toward integrated chemical parks with shared waste treatment infrastructure.
Long-term offtake contracting is displacing spot purchasing for wind energy blade manufacturers. Vestas and Siemens Gamesa are locking 5-7 year fiber supply agreements with fixed volume floors and indexed pricing. This behavior concentrates procurement leverage among three European turbine OEMs and squeezes working capital flexibility for mid-sized fiber suppliers without balance sheet depth.
PAN-Based Carbon Fibers Market Segmentation
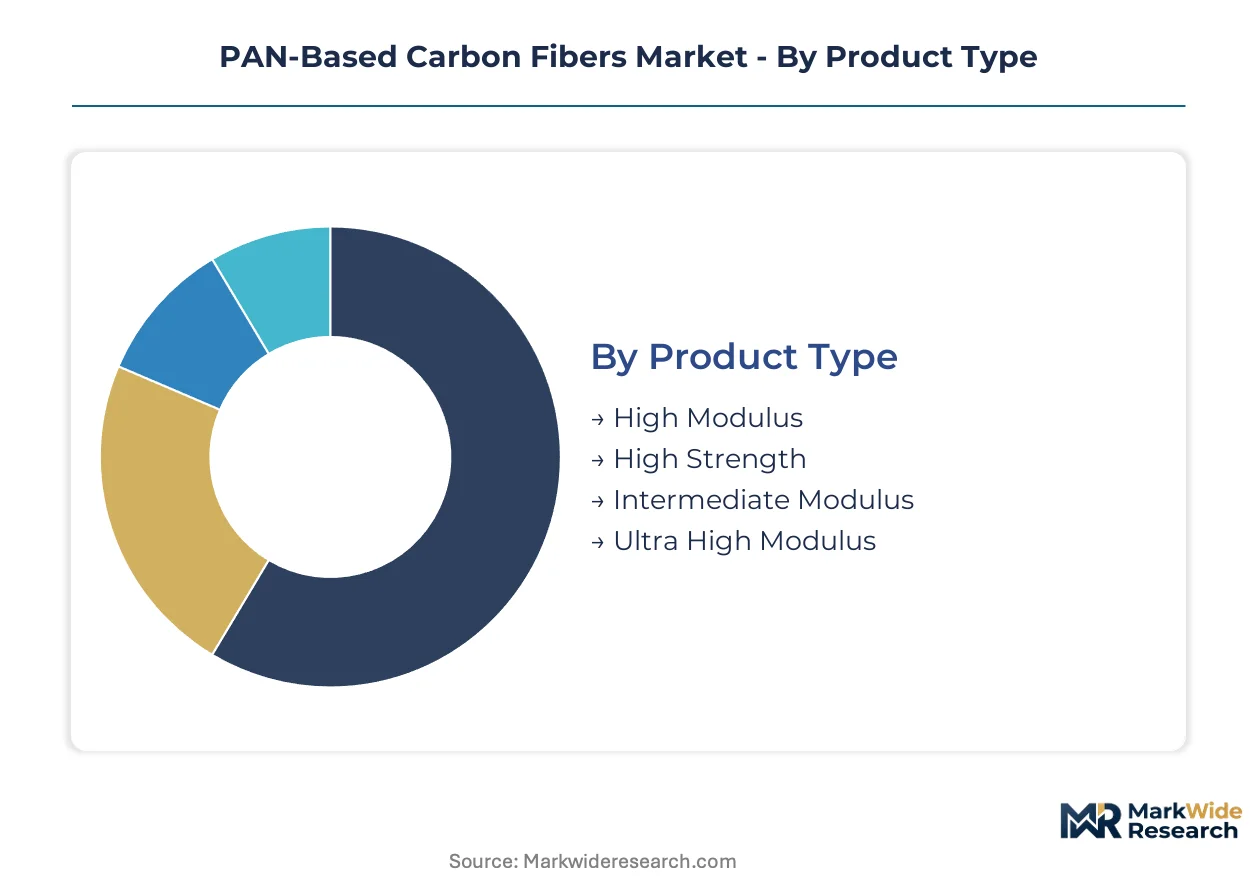
PAN-based carbon fiber segmentation reveals divergent inventory velocities across product grades, with aerospace-qualified materials cycling slowly through multi-year qualification pipelines while wind energy tows turn rapidly on annual procurement calendars. Understanding these rhythm differences shapes capacity planning and margin capture strategies for producers navigating volatile acrylonitrile input costs.
Product Type:
Cycle times stretch from months for standard industrial grades to decades for satellite-qualified ultra-modulus fibers, compressing working capital efficiency at the performance extremes.
- High Strength:Tensile strength exceeds 5.5 GPa with modulus near 230-250 GPa, optimized for wind turbine blade spar caps and automotive structural members where fatigue resistance governs design. Procurement cycles in Germany and Denmark run on 12-18 month horizons tied to turbine installation schedules. Vestas and Siemens Gamesa concentrate demand through long-term offtake agreements with fixed volume floors.
- Intermediate Modulus:Modulus ranges 280-350 GPa balancing stiffness and damage tolerance for primary flight control surfaces in commercial aviation. FAA airworthiness directives and EASA CS-25 certification standards enforce batch traceability through entire manufacturing records, stretching qualification timelines to 3-4 years for new fiber grades. Airbus and Boeing platform specifications dominate procurement concentration.
- High Modulus:Stiffness above 350 GPa serves satellite bus structures and optical benches demanding dimensional stability under thermal cycling. Japanese and European space agencies anchor demand through low-volume, decade-long program commitments.
- Ultra High Modulus:Modulus exceeding 450 GPa commands premium positioning in scientific instrumentation and specialized defense applications. Production volumes remain constrained by carbonization furnace scarcity and operator expertise limitations.
High Strength anchors the volume base while Intermediate Modulus gains share at the steepest rate as narrow-body platform production accelerates.
Application:
Cost tiers separate commodity reinforcement from certified structural materials, with aerospace commanding 8-12x pricing multiples over industrial grades despite similar precursor chemistry.
- Aerospace:Primary and secondary structural composites governed by FAA and EASA airworthiness mandates. Prepreg form factors capture disproportionate value relative to raw fiber through qualified material status.
- Wind Energy:Offshore platforms exceeding 15 MW capacity drive spar cap scaling demands. EU Green Deal carbon-intensity benchmarks now specify low-carbon-intensity fiber grades, pulling investment toward electrified carbonization.
- Automotive:Battery enclosure manufacturers in South Korea and Japan qualify carbon fiber composites to offset EV platform weight penalties. Crashworthiness regulations from NHTSA and KBA shape material specification roadmaps.
- Sporting Goods:Bicycle frames and golf shafts represent mature demand with limited growth trajectory. Asian contract manufacturers dominate finished goods production.
Aerospace commands the steepest pricing premiums while Wind Energy expands most quickly on gigawatt-scale offshore commitments.
End User:
Customer type determines specification intensity, with aerospace primes demanding full precursor traceability while industrial converters prioritize cost and availability.
- Composite Manufacturing:Specialized fabricators serving multi-industry demand clusters around German and Japanese industrial corridors. REACH compliance documentation requirements extend precursor qualification timelines by 18-24 months.
- Aerospace Industry:Boeing, Airbus, and tier-one suppliers lock supply agreements with integrated producers possessing documented carbonization asset provenance. Dual FAA/EASA certification extends time-to-revenue for new fiber entrants.
- Automotive OEMs:BMW and Mercedes-Benz structural programs in Germany specify recycled content mandates aligning with EU end-of-life vehicle directives. Volume scaling awaits cost parity with aluminum-intensive designs.
- Industrial Applications:Pressure vessels, robotics, and construction reinforcement represent fragmented demand with limited specification barriers. Price sensitivity drives procurement toward Asian supply sources.
Composite Manufacturing anchors the volume base while Aerospace Industry gains share at the steepest rate through platform-specific qualification lock-ins.
Form:
Supply concentration in high-temperature processing equipment shapes form factor availability, with carbonization furnace suppliers clustering in Germany and Japan.
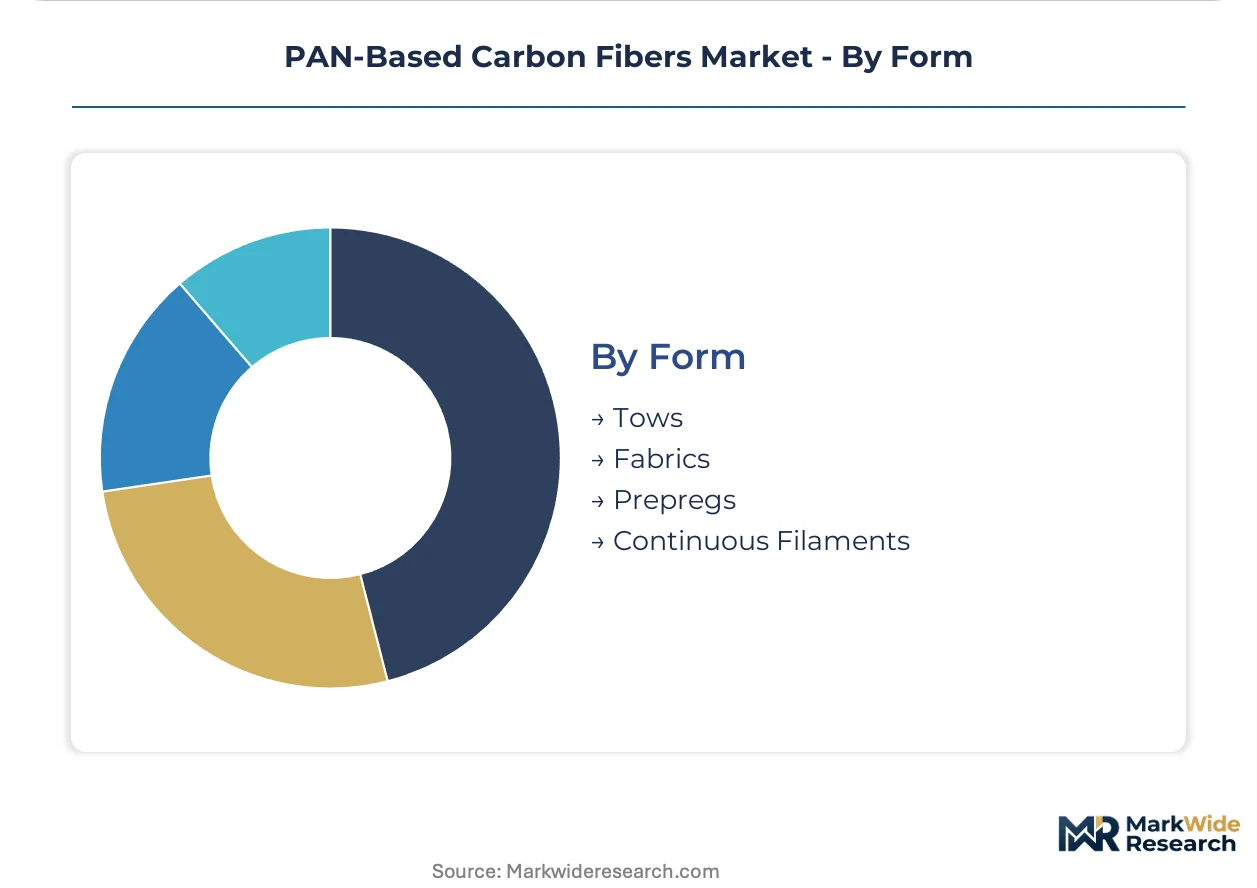
- Tows:Untwisted fiber bundles constitute the fundamental output form, with 12K and 24K deniers dominating wind energy and industrial applications. Direct melt impregnation technologies are displacing some prepreg demand in automotive programs.
- Prepregs:Resin-impregnated sheets command premium positioning through qualified material status in aerospace. Hexcel Corporation and Toray Industries dominate narrow-body platform qualification programs.
- Fabrics:Woven and non-crimp textiles serve marine and construction applications with lower specification barriers. Asian weaving operations concentrate on commodity-grade supply.
- Continuous Filaments:Specialized form for filament winding in pressure vessel and pipe applications. Hydrogen storage Type IV tank standards are converging with carbon fiber performance specifications.
Tows anchor the volume base while Prepregs gains share at the steepest rate as aerospace production rates recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon-intensity benchmarks are redirecting capacity investment toward electrified carbonization assets in Germany and France. Japan maintains furnace technology leadership through specialized equipment suppliers clustered around Nagoya. China's dual carbon goals are accelerating domestic precursor production scale-up in Jiangsu and Shandong provinces.
Germany
Automotive OEMs in Stuttgart and Munich are qualifying carbon fiber battery enclosures for EV platforms under KBA crashworthiness protocols. REACH substance documentation requirements extend precursor qualification timelines by 18-24 months. The Ruhr industrial corridor hosts integrated chemical parks with shared waste treatment infrastructure serving carbonization facilities.
United States
Boeing and Gulfstream airframe programs in Washington and Georgia concentrate demand for FAA-certified intermediate modulus tows. FAA airworthiness directives enforce batch traceability through entire manufacturing records. The Pacific Northwest composites cluster around Seattle maintains qualification pipelines for next-generation narrow-body platforms.
Japan
Satellite bus manufacturers in Tokyo and Nagoya anchor ultra-high-modulus fiber demand through decade-long program commitments. METI industrial policy supports plasma-assisted oxidation technology pilot deployment. The Chubu region around Nagoya concentrates carbonization furnace suppliers with 1000°C+ process control expertise.
China
Wind turbine blade producers in Jiangsu province are scaling spar cap fabrication for offshore platforms exceeding 15 MW capacity. MIIT standards and dual carbon goals are tightening emissions monitoring at carbonization facilities. The Yangtze River Delta hosts precursor polymerization capacity expansions serving domestic composite converters.
South Korea
Battery enclosure manufacturers for Hyundai and Kia EV platforms in Ulsan and Gyeonggi province are qualifying carbon fiber composites to offset platform weight penalties. MFDS and KBA alignment on automotive material standards shapes specification roadmaps. The Busan-Ulsan industrial corridor concentrates prepreg toll manufacturing capacity.
PAN-Based Carbon Fibers Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure consolidating around integrated precursor-to-fiber producers and qualified aerospace prepreg manufacturers. Three archetypes dominate: Japanese and German conglomerates with captive acrylonitrile supply, mid-sized European specialists with vertical control through carbonization, and Asian scale players serving industrial grade demand. Competitive moves concentrate on long-term offtake contracting with wind turbine OEMs and dual FAA/EASA certification lock-ins for narrow-body platforms.
Among Japanese conglomerates, Toray Industries, Inc. and Teijin Limited exemplify the integrated archetype with upstream precursor control. Hexcel Corporation represents the aerospace-qualified specialist tier with narrow-body platform positioning. SGL Carbon occupies a distinctive European position with backward integration from PAN polymerization through intermediate modulus carbonization stages.
| Leading Market Players |
|---|
| SGL Carbon |
| Syensqo |
| Toray Industries, Inc. |
| Zoltek Corporation |
| Hyosung Advanced Materials |
| Teijin Limited |
| Hexcel Corporation |
| Formosa Plastics Corporation |
| Mitsubishi Chemical Carbon Fiber and Composites, Inc. |
| Others |
Value Chain & Pricing Dynamics
Acrylonitrile cost volatility compresses carbon fiber gross margins and forces a three-tier pricing structure across premium, standard, and economy levels that tracks furnace technology vintage and precursor traceability depth. Propylene-ammonia feedstock swings determine baseline cost floors while EU carbon-intensity benchmarks pull premium spreads wider for electrified carbonization assets.
Pricing Analysis
Certification level creates the primary spread between aerospace-qualified intermediate modulus tows and industrial-grade high-strength bundles. Long-term offtake contracting with fixed volume floors and indexed pricing dominates wind energy procurement, insulating Vestas and Siemens Gamesa from spot volatility. Cost compression in standard grades intensifies because Asian scale players feed commodity reinforcement demand. Automotive battery enclosure manufacturers exhibit highest price sensitivity, while satellite bus programs accept decade-long premiums for ultra-high-modulus dimensional stability.
Supply Chain Analysis
Export-control restrictions on high-temperature furnace technology limit carbonization capacity expansion outside Germany and Japan. Production gravity centers on Nagoya equipment suppliers and Ruhr chemical parks with shared waste treatment infrastructure. Feedstock draws from propylene-ammonia crackers in Texas, Rotterdam, and Singapore. Single-source vulnerability concentrates in specialized furnace technicians commanding wage premiums. Distribution runs through qualified prepreg toll manufacturers clustered around Stuttgart, Nagoya, and Seattle.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-assisted oxidation technology pilot deployment signals a high-growth disruption as EU Green Deal carbon benchmarks compress viable supplier bases to low-emission asset owners.
For Market Incumbents: Insulate qualification pipelines through dual FAA/EASA certification lock-ins for narrow-body platforms. Deepen upstream control over acrylonitrile supply to anchor cost positions against propylene-ammonia volatility. Prioritize electrified carbonization furnace retrofits in German chemical parks to meet tightening ECHA emissions monitoring mandates.
For New Entrants and Emerging Players: India's PLI scheme incentives for advanced materials in Gujarat and Tamil Nadu corridors represent the most penetrable white-space target. Qualify prepreg toll manufacturing capacity for Hyundai and Kia battery enclosure programs in Ulsan. Pursue hydrogen storage Type IV tank certification as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: ECHA enforcement of REACH substance restriction amendments reshapes the acquisition landscape toward integrated chemical parks with shared scrubbing infrastructure. Five-to-ten-year viability favors backward-integrated specialists with documented precursor traceability. Monitor plasma-assisted oxidation scale-up signals as the inflection indicator for technology obsolescence risk in conventional thermal oxidation assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Carbonization Retrofit | ECHA emissions mandates force capital allocation toward thermal oxidizer upgrades at German production sites. |
| Long-term Offtake Contracting | Vestas and Siemens Gamesa lock five-to-seven-year fiber supply agreements with fixed volume floors. |
| Dual Certification Investment | Parallel FAA and EASA airworthiness documentation extends time-to-revenue for aerospace-qualified grades. |
| Plasma-Assisted Oxidation Scale-Up | METI-supported pilot deployment in Nagoya compresses energy intensity benchmarks for premium supply contracts. |
| Blockchain Traceability Integration | Immutable batch records enable premium pricing for aerospace tows with documented provenance. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, customs trade data, ECHA registration databases, and industry association reports covering ACC and Cefic. Plant managers at carbonization facilities, procurement leads at Boeing and Airbus tier-one suppliers, distribution channel partners in German composite hubs, and technical R&D directors at precursor polymerization sites provided operating data. Bottom-up capacity modeling triangulates against top-down demand aggregation across wind turbine OEMs and automotive platform specifications.
Forecast inputs include modulus grade tier, end-use application intensity, carbonization furnace technology vintage, and regional regulatory cluster stringency. Volume and value outputs across the analysis window derive from segment-specific CAGRs anchored to aerospace production rate recovery and offshore wind gigawatt commitments. Acrylonitrile feedstock cost curves and electrification capital expenditure trajectories inform cost-pass-through assumptions.
Macroeconomic conditions sit as an overlay; deviation in propylene pricing, renewable energy investment cycles, or trade policy enforcement would shift the trajectory. Forecasts reflect documented assumptions about qualification timeline compression and emissions compliance cost pass-through. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Electronic Fiberglass Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Fiber Intermediates Market
Fibers
Global Bicomponent Fiber Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Bleached Linter Cellulose Market
Fibers
Fiberglass Mat Market
Fibers
North America Carbon Fiber Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Polytetrahydrofuran Market
Fibers
Global Fiberglass Market
Fibers
Ceramic Fiber Market
Fibers
Microfibrillated Cellulose (MFC) Market