

4-Strand Fan-Shaped Strand Wire Rope Market Size, Share, and Industry Trends Forecast 2026-2036
4-Strand Fan-Shaped Strand Wire Rope Market Insights
Leasing-based equipment procurement for offshore construction fleets is reshaping how buyers source 4-strand fan-shaped strand wire rope, shifting volume commitments from ownership models to term-based supply agreements. WireCo World Group leverages its global manufacturing footprint to anchor long-term crane OEM contracts across multiple continents. Kiswire sustains R&D intensity in fatigue-resistant alloy formulations, differentiating its portfolio for deep-water mooring applications. PFEIFER dominates European structural lifting projects through specialized high-load capacity configurations.
The 4-strand fan-shaped strand wire rope consists of four helically laid strands arranged in a fan-shaped geometric profile around a fiber or steel core, manufactured through multi-stage cold drawing and rotary stranding processes that achieve precise lay lengths and strand compaction ratios for optimal load distribution. Its primary purpose centers on heavy-lift operations requiring high breaking strength combined with rotational stability under bending stress. Galvanized steel variants lead volume due to cost-performance balance in marine and construction exposure environments, while stainless steel segments command premium positioning in corrosive saltwater mooring applications where replacement access proves prohibitively expensive. Carbon steel configurations occupy mature demand channels in standard crane systems with predictable duty cycles and moderate environmental exposure.
ISO 4309 crane rope inspection standards and EU Machinery Directive compliance frameworks shape product certification requirements, forcing manufacturers to maintain documented fatigue-test traceability for European market access. China's SAMR enforces GB/T 20118 wire rope national standards that increasingly align with international fatigue-performance benchmarks, raising export qualification barriers for non-compliant producers. OSHA sling and rigging regulations in the United States mandate periodic inspection protocols that sustain aftermarket replacement demand across installed crane fleets. Stakeholders must monitor evolving carbon-border adjustment mechanisms and their downstream impact on steel-intensive wire rope input costs.
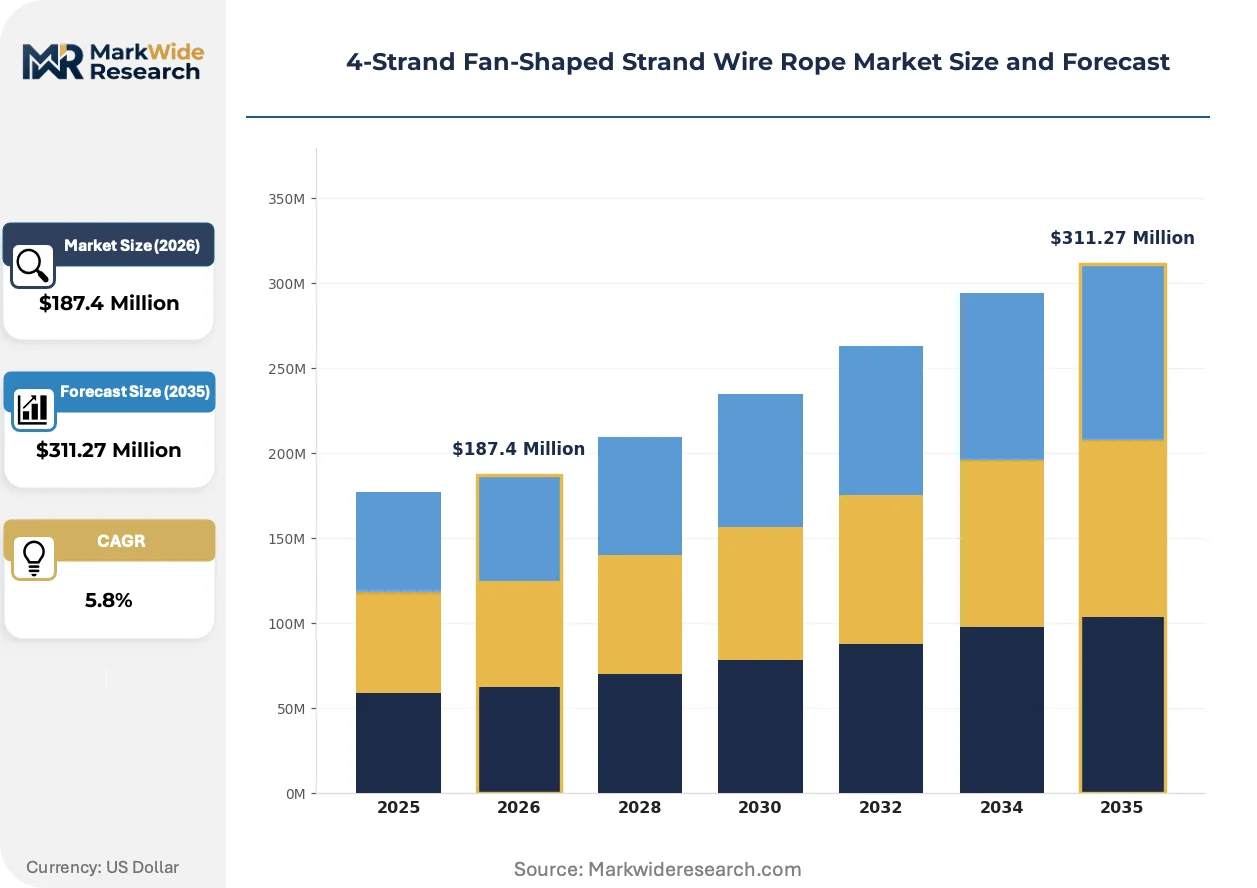
Market Dynamics
Leasing-based equipment procurement for offshore construction fleets is compressing traditional ownership cycles and forcing manufacturers toward term-based supply agreements with documented fatigue-test traceability.
Growth Catalysts
- EU Machinery Directive compliance:European crane OEMs now mandate certified fatigue-test documentation for fleet renewal contracts, accelerating replacement demand in port infrastructure corridors.
- Offshore wind turbine installation vessels:Jack-up vessel operators require rotational-stable heavy-lift configurations for turbine component handling in North Sea and Baltic Sea developments.
- China's GB/T 20118 alignment:SAMR enforcement of enhanced strand conformity standards is filtering non-compliant producers from export qualification pools.
Market Restraints
- High-grade steel alloy volatility:Carbon-border adjustment mechanisms in Europe and North America are transmitting input cost uncertainty directly to wire rope pricing structures.
- Supply concentration in galvanized steel:Marine-grade coating capacity clusters among a limited set of European and East Asian metallurgical processors.
- Polyester-synthetic mooring substitution:Deep-water floating offshore wind developers are piloting lightweight fiber alternatives for static seabed anchoring below 200-meter depths.
Strategic Opportunities
- German port infrastructure renewal:Hamburg and Bremerhaven modernization programs specify high-load capacity wire rope configurations for container crane fleet upgrades.
- Stainless steel saltwater mooring:North Sea offshore substation platforms require corrosion-resistant configurations where replacement access costs dwarf initial material premiums.
- ISO 4309 inspection protocol convergence:Harmonized crane rope inspection standards across European and Asia-Pacific jurisdictions are reducing certification fragmentation for multi-region suppliers.
Industry Challenges
- Fatigue-testing technician scarcity:Specialized non-destructive testing certification for wire rope inspection is concentrating among aging workforce cohorts in European industrial clusters.
- Multi-standard compliance timelines:Simultaneous GB, ISO, and OSHA qualification requirements are extending product launch cycles for export-oriented manufacturers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4-Strand Fan-Shaped Strand Wire Rope Market Trends and Innovations
Material science advances and procurement model restructuring are compressing traditional product lifecycles while elevating performance documentation requirements across marine and heavy-lift applications.
Plasma-nitrided carbon steel wire is hybridizing surface hardness with core ductility for deep-water mooring applications. North Sea offshore wind developers are specifying these configurations for dynamic positioning systems subject to cyclic bending stress. The technology is hybridizing traditional galvanized steel dominance with advanced metallurgical treatments that extend replacement intervals in corrosive environments.
China's SAMR has tightened GB/T 20118 fatigue-performance benchmarks to align with ISO 4309 crane rope inspection protocols. Export-oriented producers must now maintain documented test traceability for European market access. Stainless steel segments in saltwater mooring applications face the steepest compliance adjustment timelines.
Term-based supply agreements are displacing traditional equipment ownership models among offshore construction fleet operators. Leasing companies now bundle wire rope replacement schedules into vessel charter contracts. This pattern concentrates most acutely in German and Danish offshore wind installation corridors where jack-up vessel utilization rates drive uptime penalties.
4-Strand Fan-Shaped Strand Wire Rope Market Segmentation
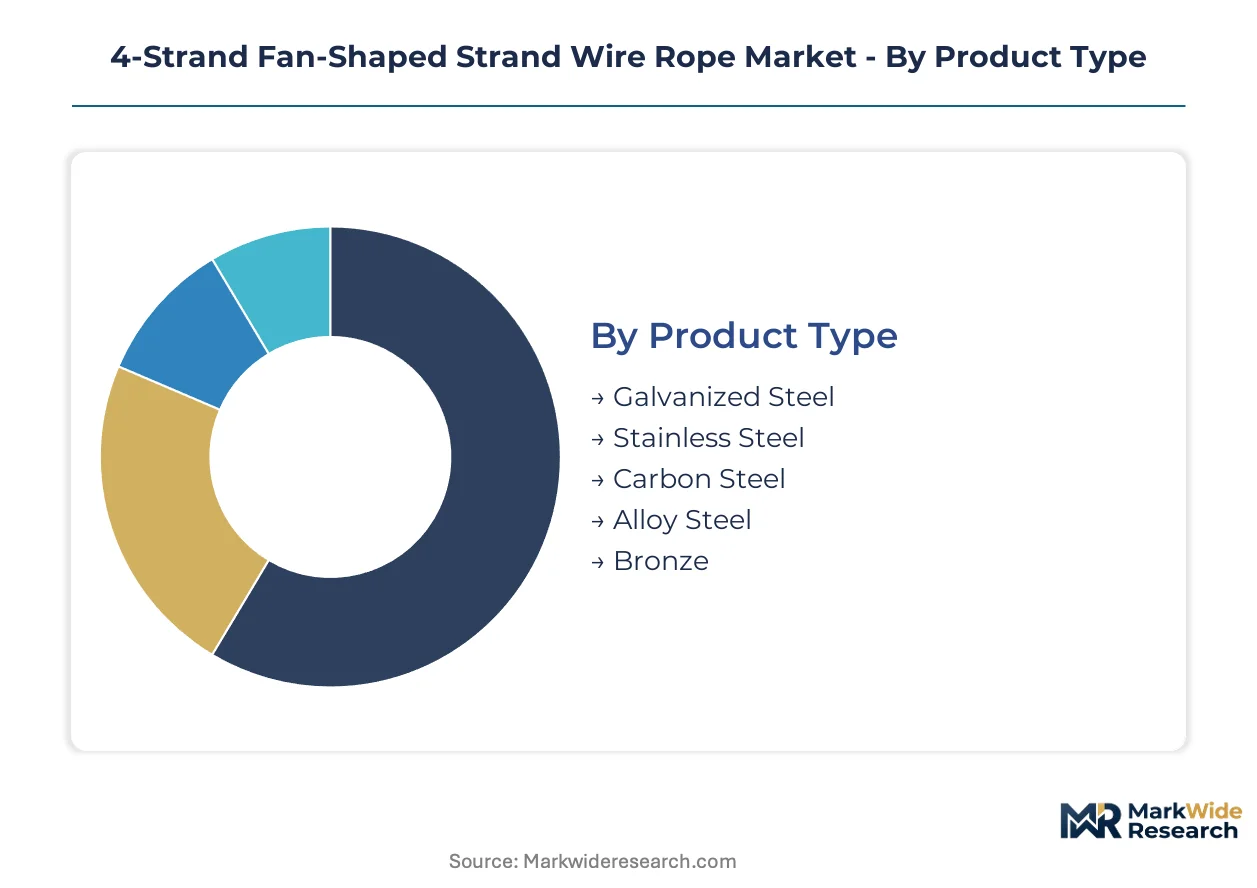
Segmentation in this market tracks how material specifications, duty-cycle intensity, and logistics requirements fragment procurement patterns. Buyers prioritize corrosion resistance, fatigue-test documentation, and handling efficiency across distinct operational environments. Manufacturers calibrate production runs against these dimensions to align inventory with replacement-cycle predictability.
Product Type:
After-sales service intensity varies sharply by metallurgical grade, with premium alloys demanding specialized inspection protocols and field-technical support.
- Galvanized Steel:Zinc-coated carbon wire delivers cost-performance balance for marine and construction exposure. Demand concentrates in German port infrastructure renewal corridors where container crane fleets require predictable replacement intervals under moderate corrosion stress.
- Stainless Steel:Chromium-nickel alloy configurations command premium positioning for saltwater mooring applications. North Sea offshore substation platforms specify these grades where replacement access costs dwarf initial material outlays.
- Carbon Steel:Standard uncoated configurations serve mature crane systems with predictable duty cycles and controlled environmental exposure.
- Alloy Steel:Plasma-nitrided variants hybridize surface hardness with core ductility for deep-water dynamic positioning systems.
- Bronze:Copper-tin formulations address specialized spark-resistant requirements in explosive atmosphere mining operations.
Galvanized steel holds the largest share; momentum sits with stainless steel for offshore wind mooring specifications.
Application:
Cost tier stratification separates high-frequency replacement cycles in crane systems from capital-intensive deep-water installations with extended service intervals.
- Cranes:Overhead and mobile lifting systems require rotational stability under bending stress. German and Danish port modernization programs drive specification upgrades for ISO 4309-compliant fatigue-test documentation.
- Marine Mooring:Static and dynamic anchoring configurations face substitution pressure from synthetic fiber alternatives below 200-meter depths. North Sea floating offshore wind developers pilot mixed-material approaches.
- Mining Hoists:Vertical shaft extraction systems demand high breaking strength with controlled elongation characteristics.
- Elevator Systems:Building transportation applications prioritize smooth flex performance and acoustic dampening over absolute load capacity.
- Structural Support:Bridge and stadium tensioning applications require documented modulus-of-elasticity consistency for engineered pre-tensioning.
Crane applications dominate procurement volume; marine mooring is climbing the fastest as jack-up vessel fleets expand.
End User Industry:
Customer type fragmentation separates project-based construction procurement from fleet-operational maritime buying patterns with diverging contract structures.
- Construction:General contractors and specialized rigging firms source standard configurations for temporary lifting operations with defined project horizons.
- Maritime Operations:Offshore vessel operators and port authorities negotiate term-based supply agreements bundling replacement schedules into charter contracts.
- Mining Companies:Underground and open-pit operators prioritize spark-resistant grades for explosive atmosphere compliance.
- Infrastructure Providers:State-owned port authorities and bridge maintenance agencies specify certified fatigue-test traceability for public tender compliance.
- Logistics Firms:Container terminal operators concentrate demand in Hamburg and Bremerhaven modernization corridors.
Maritime operations command premium pricing tiers; logistics firms are gaining share fastest through port automation investments.
Packaging Type:
Supply concentration in metallurgical processing shapes how finished rope reaches installation sites across fragmented distribution channels.
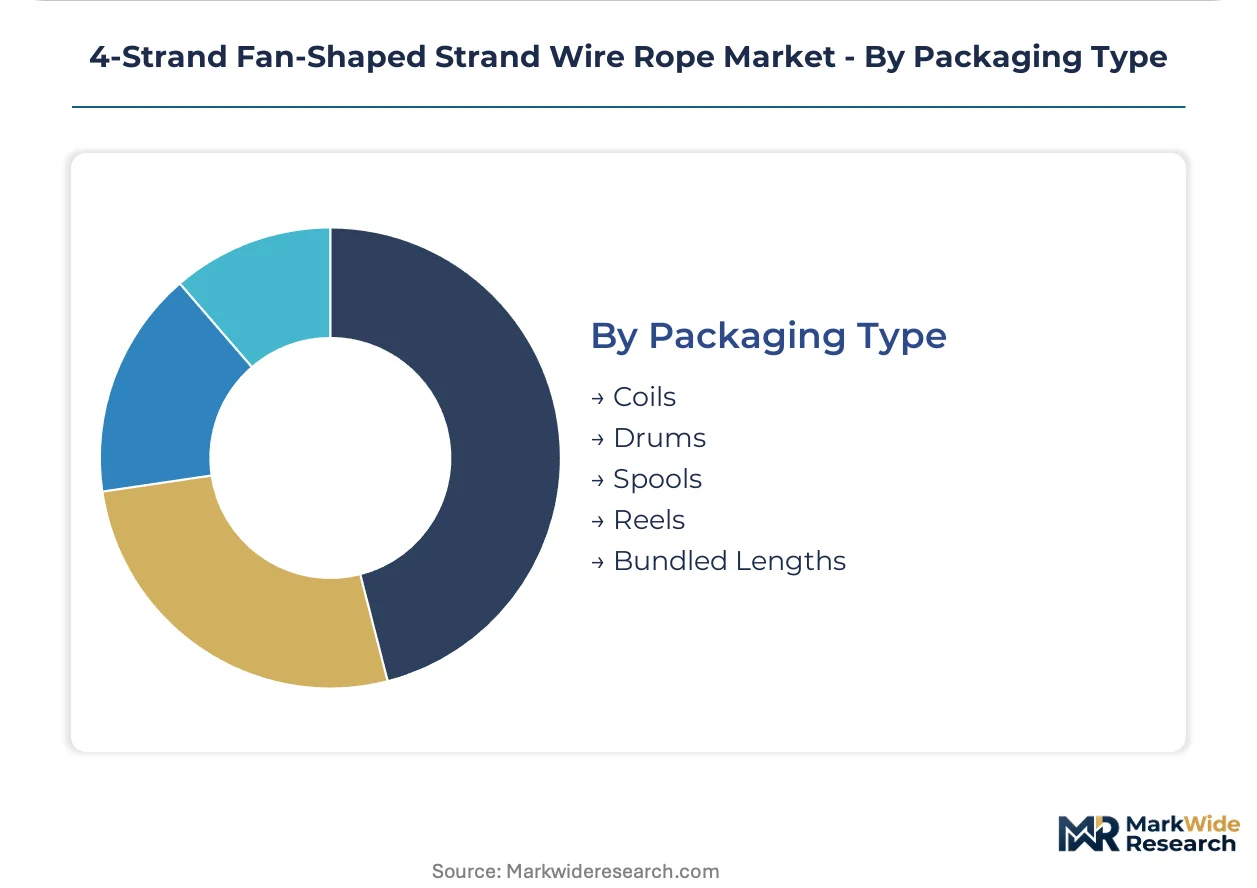
- Coils:Bulk wound configurations suit high-volume crane OEM integration with automated dereeling equipment.
- Drums:Heavy-capacity spooling enables direct deployment for offshore vessel winch integration without intermediate handling.
- Spools:Compact winding formats serve maintenance-repair-operations channels with space-constrained storage requirements.
- Reels:Flanged wooden or steel structures protect precision-laid rope during transport to remote construction sites.
- Bundled Lengths:Pre-cut segments address project-specific structural support installations with minimal field fabrication.
Drum packaging holds the largest share; bundled lengths are expanding most quickly for modular offshore construction workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German port authorities command premium pricing for certified fatigue-test documentation, while Chinese export-oriented producers absorb compliance-cost compression under tightened GB/T 20118 standards. This asymmetry concentrates procurement leverage in Hamburg-Bremerhaven corridors.
Germany
Hamburg and Bremerhaven port modernization programs drive specification upgrades for container crane fleet renewals. The EU Machinery Directive mandates certified fatigue-test documentation for European market access. North Rhine-Westphalia industrial clusters anchor heavy-lift equipment manufacturing with integrated wire rope supply chains.
China
SAMR enforcement of GB/T 20118 wire rope national standards filters non-compliant producers from export qualification pools. Enhanced strand conformity requirements align with ISO 4309 crane rope inspection protocols. Yangtze River Delta metallurgical processors concentrate marine-grade coating capacity for offshore wind applications.
United States
OSHA sling and rigging regulations sustain aftermarket replacement demand across installed crane fleets. Gulf Coast offshore construction corridors require rotational-stable heavy-lift configurations for jack-up vessel operations. Texas and Louisiana port authorities specify documented inspection protocols for public tender compliance.
Denmark
North Sea and Baltic Sea offshore wind developments drive demand for turbine installation vessel configurations. Term-based supply agreements bundle wire rope replacement schedules into vessel charter contracts. Copenhagen-Malmö logistics corridors concentrate jack-up vessel utilization with uptime penalty structures.
Japan
METI industrial standards shape fatigue-performance benchmarks for crane OEM integration. Osaka-Kobe port clusters specify high-load capacity configurations for automated container handling systems. JIS standards alignment with ISO protocols reduces certification fragmentation for multi-region suppliers.
4-Strand Fan-Shaped Strand Wire Rope Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying certified configurations to crane OEMs and offshore vessel operators. Market structure tilts toward consolidated metallurgical processing with fragmented downstream distribution. Three archetypes dominate: global rope conglomerates with multi-continent manufacturing footprints, regional specialists in fatigue-resistant alloy formulations, and European fabricators focused on high-load structural lifting projects. Capacity expansion and strategic partnerships represent the dominant competitive vectors as leasing-based procurement compresses traditional ownership cycles.
Among the named players, WireCo World Group, Kiswire, and PFEIFER exemplify distinct strategic positions within this structure. WireCo World Group represents the scale-driven global archetype with manufacturing presence across multiple continents. Kiswire occupies a position within the materials-specialist tier, with its name suggesting Korean industrial origins. PFEIFER anchors the European premium-fabricator segment, its Germanic naming convention aligning with structural lifting project concentration in Hamburg and Bremerhaven corridors. Gustav Wolf and Brugg Lifting represent additional European specialist formations, while Usha Martin and Jiangsu Langshan Wire Rope exemplify Asia-Pacific supply-side participants. Bridon-Bekaert The Ropes Group and Teufelberger occupy positions bridging global scale with regional application expertise.
| Leading Market Players |
|---|
| Bridon-Bekaert The Ropes Group |
| Kiswire |
| WireCo World Group |
| Usha Martin |
| Teufelberger |
| PFEIFER |
| Gustav Wolf |
| Brugg Lifting |
| Jiangsu Langshan Wire Rope |
| Others |
Pricing and Supply Chain Analysis
Hamburg-Bremerhaven freight corridors transmit carbon-border adjustment cost volatility directly into galvanized steel wire rope pricing tiers, compressing margins for export-oriented producers while elevating premium documentation fees for ISO 4309-certified configurations. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel saltwater mooring grades from galvanized marine variants and uncoated carbon steel crane configurations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with embedded replacement schedules, while price differentiation hinges on fatigue-test certification grade and volume scale commitments. Cost compression in standard carbon steel tiers is intensifying because Chinese GB/T 20118 compliance investments filter non-qualified suppliers from export pools. Fleet operators in maritime segments exhibit lowest price sensitivity due to uptime penalty structures, whereas general construction contractors maximize spot-market leverage.
Supply Chain Analysis
High-grade steel alloy feedstock draws from German, Chinese, and Japanese metallurgical processing clusters with concentrated marine-grade coating capacity. Raw material dependencies center on zinc ingot supply, chromium-nickel stainless billets, and plasma-nitriding gas treatments. Single-source vulnerability in European galvanizing capacity creates bottleneck exposure for North Sea offshore wind developers. Distribution runs through crane OEM direct integration and offshore vessel charter bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Leasing-based procurement restructuring fragments volume concentration across term-based supply agreements, creating specialized niches for fatigue-test documentation specialists and alloy formulation experts.
For Market Incumbents: Insulate long-term crane OEM relationships through captive GB/T 20118 certification investments that filter regional competitors from European port infrastructure tenders. Deepen backward integration into plasma-nitriding treatment capacity to defend margin position against synthetic fiber substitution threats in deep-water mooring applications. For New Entrants and Emerging Players: Southeast Asian port automation corridors offer underpenetrated demand for ISO 4309-compliant inspection services bundled with replacement scheduling. Target stainless steel saltwater mooring specifications for North Sea offshore substation platforms where replacement access economics favor premium-grade entrants with documented fatigue-test traceability. For Investors and Strategic Acquirers: Regional specialists in fatigue-resistant alloy formulations present consolidation targets with durable moats against commodity-grade competition. Watch synthetic fiber mooring pilot performance below 200-meter depths as inflection indicator for wire rope demand displacement risk. Cross-checking against offshore wind installation vessel order books is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plasma-Nitriding Capacity | Captures margin from deep-water dynamic positioning system specifications in North Sea developments. |
| GB/T 20118 Certification Investment | Unlocks European port infrastructure tenders under SAMR-aligned fatigue-performance benchmarks. |
| Long-term Supply Agreement with Jack-up Vessel Operators | Bundles replacement schedules into charter contracts with uptime penalty structures. |
| Joint Venture with Yangtze River Delta Metallurgical Processors | Secures marine-grade coating capacity for offshore wind export qualification pools. |
| Acquisition of Fatigue-Testing Specialist Firm | Addresses technician scarcity in European industrial clusters with aging workforce cohorts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, crane OEM procurement disclosures, offshore vessel charter contract registries, and SAMR regulatory filings. Interviews with maintenance directors at container terminal operators, OEM procurement teams for heavy-lift equipment, aftermarket service heads for installed crane fleets, and technical R&D directors at metallurgical processors inform demand-side calibration. Bottom-up volume triangulation against top-down steel consumption benchmarks validates segment-level outputs.
Forecast inputs include metallurgical grade tier, end-use application intensity, packaging format for deployment logistics, and regional regulatory compliance cluster across the analysis window. CAGRs derive from replacement cycle modeling for installed crane fleets and capacity expansion schedules for offshore wind installation vessels. Projected carbon-border adjustment mechanism impacts on steel input costs shape pricing trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by synthetic fiber mooring technology developers would shift outcomes for deep-water static anchoring segments. Cross-checking against offshore wind turbine installation vessel order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.