
 Natural Phytosphingosine Market | 2026-2036
Natural Phytosphingosine Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Phytosphingosine Market Insights
Multi-source procurement among Asian fermentation houses is repositioning supply security for European and North American formulators. BASF SE leverages its integrated biotechnology platform to sustain captive production of high-purity phytosphingosine. Evonik Industries AG anchors its position through specialized lipid chemistry expertise in Germany. Croda International Plc competes via botanical extraction capabilities tied to sustainable sourcing programs.
Natural phytosphingosine constitutes a long-chain sphingoid base (C18 amino alcohol) derived from yeast fermentation or plant sources, typically exceeding 95% purity for cosmetic-grade applications. The molecule functions primarily as a skin-identical lipid that reinforces stratum corneum barrier integrity and modulates inflammatory signaling. Powder formulations dominate current volume owing to stability advantages in anhydrous systems and extended shelf life. Liquid emulsions represent the fastest-expanding product category as Korean and Japanese brands favor ready-to-incorporate bases for serum and essence production. Pharmaceutical-grade specifications command premium positioning due to stringent endotoxin and heavy metal thresholds.
EU REACH registration requirements and the EU Cosmetics Regulation govern ingredient disclosure and safety dossier obligations for phytosphingosine suppliers accessing European formulation houses. FDA oversight through cosmetic ingredient review processes shapes U.S. market entry protocols, while China's NMPA filing requirements for imported cosmetic raw materials create additional compliance layers for international suppliers. South Korea's MFDS maintains distinct microbial and purity standards that filter supplier eligibility for K-beauty supply chains. Stakeholders must monitor evolving biotechnology-derived ingredient classifications under ECHA's ongoing nanomaterial and fermentation product guidance revisions.
Market Dynamics
EU REACH compliance tightening on cosmetic ingredient safety is forcing fermentation houses and botanical extractors to revalidate purity dossiers, compressing supplier eligibility for European formulation access and accelerating multi-source procurement among Asian producers.
Growth Catalysts
- K-Beauty Export Surge:South Korean cosmetics manufacturers are embedding phytosphingosine into premium barrier-repair essences for Southeast Asian and North American distribution, amplifying volume pull through Seoul-based formulators.
- Biotechnology Platform Maturation:Yeast fermentation yields for C18 sphingoid bases have improved substantially, reducing batch-to-batch variability and enabling cosmetic-grade specifications at pharmaceutical purity thresholds.
- Clean Beauty Mandates:EU Cosmetics Regulation disclosure requirements are favoring naturally derived lipids over petrochemical alternatives in stratum corneum repair formulations.
Market Restraints
- Feedstock Volatility:Fermentation substrate costs fluctuate with agricultural commodity markets, squeezing margin stability for yeast-derived phytosphingosine producers.
- Supplier Concentration Risk:Captive production at integrated German and South Korean chemical houses limits spot market liquidity for independent European and North American formulators.
- Substitution Pressure:Synthetic ceramide analogs and pseudoceramides compete on cost in mass-market moisturizing applications where barrier function claims are less clinically positioned.
Strategic Opportunities
- Pharmaceutical-Grade Expansion:Atopic dermatitis and barrier dysfunction therapeutics represent an emerging indication window beyond cosmetic cosmeceuticals, requiring endotoxin-controlled specifications.
- Ready-to-Incorporate Formats:Liquid emulsion bases are displacing powder handling in Japanese and Korean serum manufacturing, favoring suppliers with lipid chemistry formulation capabilities.
- Sustainable Sourcing Certification:RSPO-aligned botanical extraction and carbon-accounted fermentation processes are unlocking premium positioning in Northern European clean beauty supply chains.
Industry Challenges
- Analytical Methodology Standardization:Inconsistent HPLC and GC-MS protocols across contract laboratories delay batch release timelines and complicate multi-site manufacturing qualification.
- Cross-Contamination Controls:Fermentation facilities must segregate cosmetic and pharmaceutical production lines to meet MFDS microbial limits, requiring dedicated cleanroom capex.
- IP Licensing Complexity:Patent thickets around specific yeast strains and extraction solvents create freedom-to-operate uncertainty for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Phytosphingosine Market |
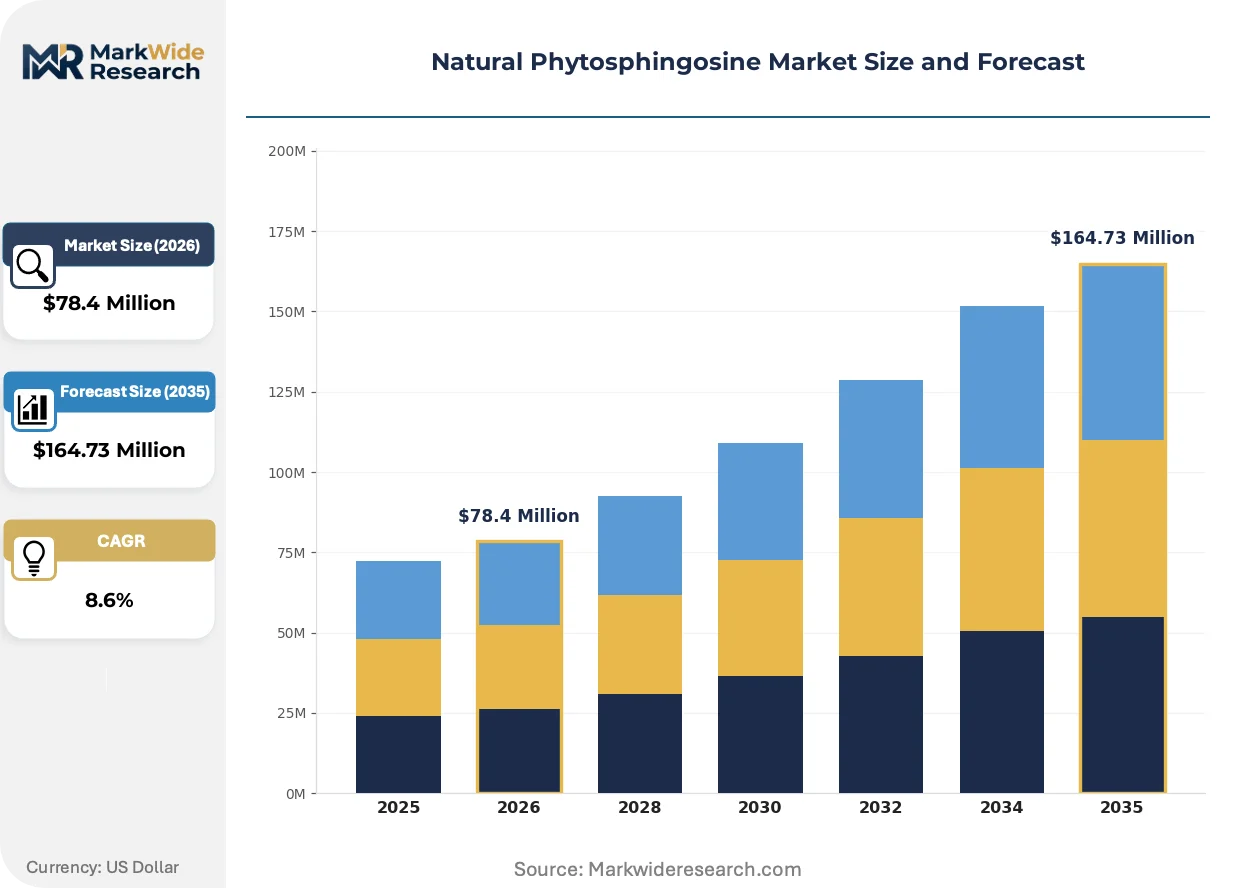
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $164.73 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Emulsion, Cream Application: Cosmetics, Personal Care, Pharmaceuticals, Nutraceuticals End User: Manufacturers, Retailers, Distributors, Consumers Form: Gel, Lotion, Serum, Balm |
| Companies Covered | BASF SE, Evonik Industries AG, Croda International Plc, Ashland Inc., Clariant AG, Stepan Company, Kao Corporation, Lonza Group Ltd., DSM Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Phytosphingosine Market Trends and Innovations
Continuous processing technologies and microbiome-targeted formulation science are reshaping how phytosphingosine integrates into next-generation skin barrier products, with implications for manufacturing scale and clinical positioning.
Precision fermentation using metabolically optimized yeast strains is electrifying the production economics of high-purity C18 sphingoid bases. Korean and Japanese cosmetics houses are accelerating adoption of these biomanufactured inputs for essence and serum lines. The technology is compressing lead times from strain engineering to commercial volume, enabling faster response to formulation house demand spikes.
ECHA's ongoing revision of guidance documents for biotechnology-derived ingredients under REACH is tightening substance identity requirements for fermentation products. This regulatory recalibration is forcing suppliers to enhance analytical characterization dossiers beyond standard cosmetic-grade specifications. European formulation houses are responding by pre-qualifying dual-source supply arrangements to mitigate registration-driven supply interruption risks.
Direct procurement relationships between fermentation houses and brand-owned laboratories are displacing traditional distributor intermediaries in East Asian supply chains. Seoul and Tokyo-based cosmetics manufacturers are establishing technical partnerships with producers for co-development of application-specific lipid formats. This channel restructuring is most visible in premium skin barrier repair segments where formulation performance claims require batch-level technical collaboration.
Natural Phytosphingosine Market Segmentation
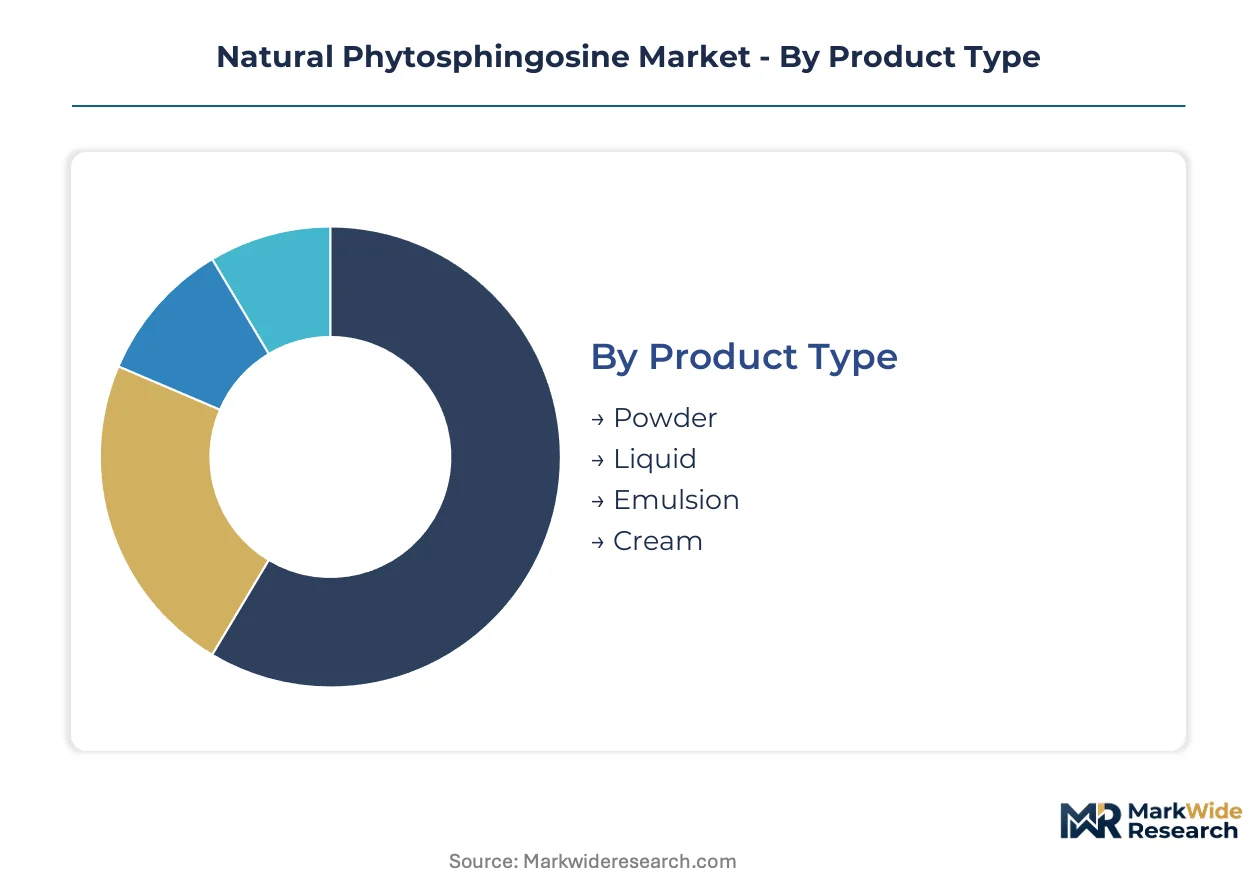
Segmentation in the Natural Phytosphingosine Market reveals how formulation physics and regulatory thresholds reshape commercial access. Powder and liquid formats diverge sharply in supply chain economics, while pharmaceutical-grade specifications impose distinct purity protocols that filter supplier eligibility.
Product Type:
Powder formats dominate current volume owing to stability in anhydrous systems, yet liquid emulsions command accelerating premium positioning as Korean and Japanese manufacturers streamline serum production workflows.
- Powder:Crystalline C18 amino alcohol exceeding 95% purity enables extended shelf life in moisture-sensitive formulations. Demand concentrates in European clean beauty supply chains where RSPO-aligned sourcing certification unlocks premium positioning. Stability advantages sustain powder's volume leadership despite handling complexity.
- Liquid:Pre-solubilized phytosphingosine in aqueous or lipid carriers eliminates reconstitution steps in Seoul-based essence manufacturing. Korean formulators favor ready-to-incorporate bases for barrier-repair serum lines, compressing batch preparation timelines and reducing contamination risk.
- Emulsion:Oil-in-water dispersions suit multifunctional moisturizer formulations requiring simultaneous lipid delivery and sensory elegance.
- Cream:High-viscosity semisolids target occlusive barrier-repair applications in pharmaceutical dermatology channels.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Application:
Cosmetic-grade specifications generate the dominant revenue stream, though pharmaceutical endotoxin thresholds are opening adjacent therapeutic indications for atopic dermatitis management.
- Cosmetics:Skin-identical lipid claims in premium K-beauty essences drive volume pull through Seoul and Tokyo formulation houses. Stratum corneum barrier integrity positioning commands price premiums in Southeast Asian export markets.
- Personal Care:Body lotions and cleansing formulations incorporate phytosphingosine at lower active concentrations for mass-market accessibility.
- Pharmaceuticals:Endotoxin-controlled specifications for barrier dysfunction therapeutics require segregated cleanroom production lines and dedicated batch release protocols.
- Nutraceuticals:Oral bioavailability challenges limit current adoption, though sphingolipid metabolic research is expanding indication exploration.
Cosmetics anchors present revenue. Pharmaceuticals represents the fastest-growing trajectory.
End User:
Direct technical partnerships between fermentation houses and brand laboratories are displacing traditional distributor intermediaries in East Asian procurement channels.
- Manufacturers:Integrated biotechnology platforms at German and South Korean chemical houses sustain captive production, limiting spot market liquidity for independent formulators.
- Retailers:Clean beauty specialty channels in Northern Europe demand batch-level traceability documentation for naturally derived lipid claims.
- Distributors:Traditional intermediaries retain relevance in fragmented North American and European mid-market access.
- Consumers:Direct-to-consumer serum brands in Japan and South Korea are establishing micro-batch procurement relationships with fermentation specialists.
Manufacturer dominance persists. Retailer influence climbs fastest on certification demands.
Form:
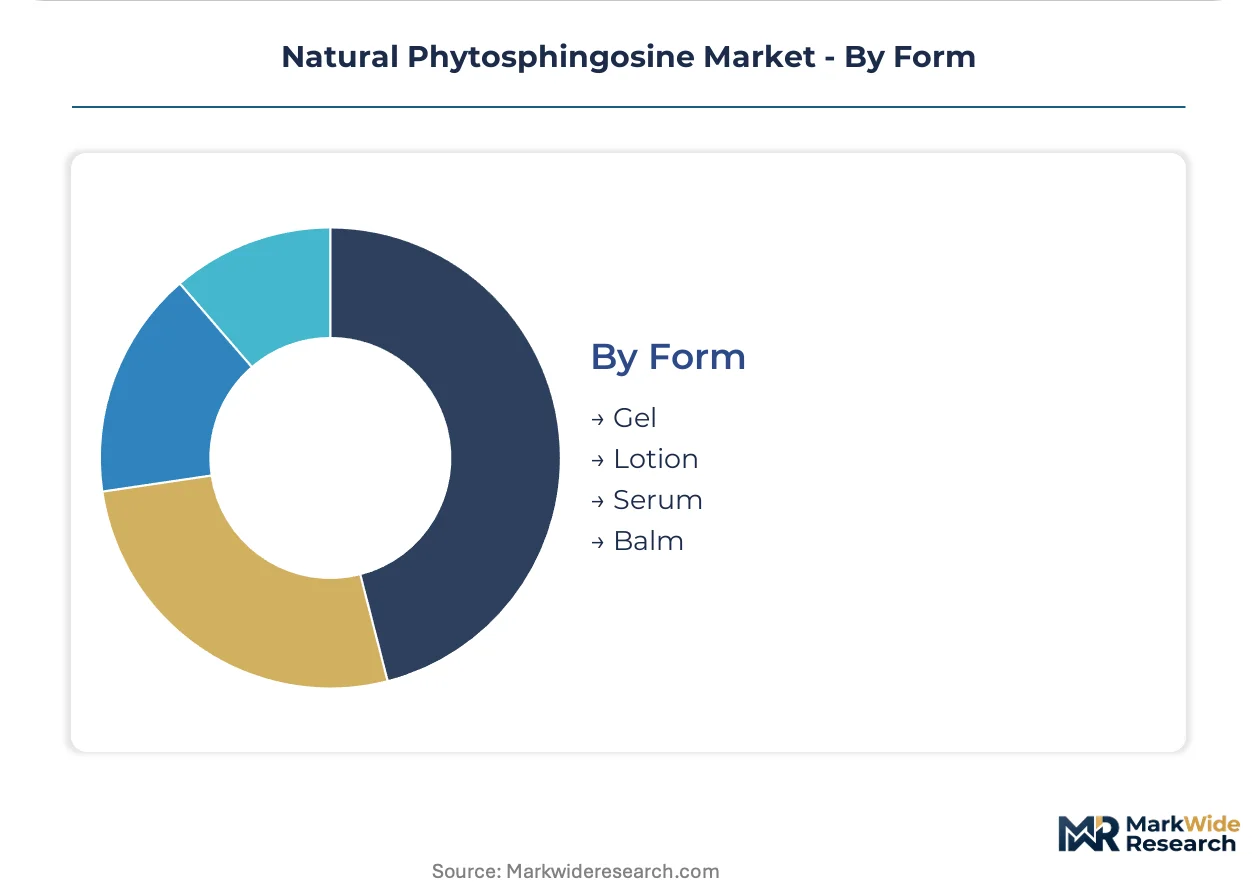
Serum and gel formats concentrate innovation investment as Korean and Japanese brands compete on sensorial elegance and rapid skin penetration claims.
- Gel:Water-based matrices suit oil-averse consumer segments in humid Southeast Asian climates.
- Lotion:Lower viscosity emulsions target body care applications where spreadability outweighs occlusion requirements.
- Serum:High-actives, low-viscosity vehicles dominate premium facial care positioning in Seoul and Tokyo brand portfolios. Lightweight textures align with essence layering rituals in K-beauty regimens.
- Balm:Occlusive w/o emulsions serve extreme barrier repair needs in pharmaceutical and professional aesthetic channels.
Serum leads premium positioning. Balm expands most quickly in therapeutic adjacencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the natural phytosphingosine trade, with South Korean cosmetics manufacturers driving volume through premium barrier-repair essences. Formulation houses in Tokyo and Osaka amplify demand for high-purity C18 sphingoid bases. European REACH compliance tightening filters supplier access, while North American formulators seek multi-source procurement security.
South Korea
K-beauty export engines in Seoul and Incheon embed phytosphingosine into barrier-repair serums for Southeast Asian and North American distribution. MFDS microbial and purity standards filter supplier eligibility for domestic supply chains. Seoul-based formulators establish direct technical partnerships with fermentation houses, displacing traditional distributor intermediaries.
Japan
Cosmetics laboratories in Tokyo and Osaka favor liquid emulsion formats for essence and serum manufacturing, compressing batch preparation timelines. METI oversees chemical substance management under the Chemical Substances Control Law, shaping import documentation requirements. Osaka's formulation clusters drive specification demands for ready-to-incorporate lipid bases.
Germany
Integrated biotechnology platforms sustain captive production for European formulation access. ECHA's REACH registration requirements govern substance identity dossiers for fermentation-derived ingredients. The Rhine-Ruhr chemical corridor anchors lipid chemistry expertise, with specialized houses serving Northern European clean beauty supply chains.
United States
FDA cosmetic ingredient review processes shape market entry protocols for phytosphingosine suppliers. New Jersey and California formulation clusters seek multi-source procurement arrangements to mitigate supply concentration risk. Independent formulators face limited spot market liquidity as integrated producers control captive supply.
China
NMPA filing requirements for imported cosmetic raw materials create compliance layers for international suppliers accessing domestic formulation houses. Shanghai and Guangzhou cosmetics manufacturers source phytosphingosine for premium skin barrier products targeting domestic and export markets. Dual carbon goals incentivize carbon-accounted fermentation processes among local biotechnology platforms.
Natural Phytosphingosine Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade specifications and sustainable sourcing certification. The vendor base concentrates around integrated biotechnology platforms and specialized lipid chemistry houses, with limited spot market liquidity for independent formulators. Three archetypes dominate: German chemical conglomerates with captive fermentation capacity, Asian fermentation houses serving K-beauty supply chains, and botanical extraction specialists with RSPO-aligned programs. Capacity expansion and strategic partnerships constitute the dominant competitive vectors, with players securing dual-source arrangements to mitigate registration-driven supply interruptions.
Among Germany-based integrated producers, BASF SE and Evonik Industries AG exemplify the biotechnology-platform archetype, anchoring supply security through in-house fermentation and lipid chemistry capabilities. Croda International Plc occupies a position within the botanical extraction tier, representing sustainable sourcing programs tied to premium positioning in European clean beauty channels. These three entities collectively illustrate the geographic and technological stratification shaping competitive access.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Croda International Plc |
| Ashland Inc. |
| Clariant AG |
| Stepan Company |
| Kao Corporation |
| Lonza Group Ltd. |
| DSM Nutritional Products |
| Others |
Pricing and Supply Chain Analysis
Captive fermentation capacity at integrated German and South Korean chemical houses anchors supply security and pricing power, compressing spot market liquidity for independent formulators while enabling premium positioning for endotoxin-controlled pharmaceutical grades.
Pricing Analysis
Fermentation substrate costs pass through directly to phytosphingosine pricing, with agricultural commodity volatility squeezing margin stability for yeast-derived producers. Pricing stratifies across pharmaceutical-grade, cosmetic-grade, and technical-grade tiers based on purity thresholds and endotoxin specifications. Cost compression in cosmetic-grade powder formats is intensifying as synthetic ceramide analogs compete on price in mass-market applications. Independent European formulators exhibit highest price sensitivity due to limited multi-source procurement options, while Seoul-based K-beauty houses prioritize batch-to-batch consistency over unit cost.
Supply Chain Analysis
Phytosphingosine supply rests on fermentation substrate streams from agricultural processors in Germany, South Korea, and China, with C18 sphingoid base production concentrated among integrated biotechnology platforms. Key inputs include glucose feedstocks, metabolically optimized yeast strains, and specialized lipid extraction solvents. Single-source vulnerability runs through captive production at BASF and Evonik facilities, creating supply interruption risks for non-integrated formulators. Distribution runs through direct technical partnerships between fermentation houses and brand laboratories in East Asia, displacing traditional distributor intermediaries in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in natural phytosphingosine is achievable through biotechnology platform maturation compressing production costs and pharmaceutical-grade tiering unlocking premium positioning.
For Market Incumbents: Deepen captive fermentation capacity in the Rhine-Ruhr corridor and Seoul-Incheon clusters to defend against emerging botanical extraction specialists. Secure dual-source supply arrangements with Asian fermentation houses to mitigate ECHA registration-driven supply interruptions. Invest in segregated cleanroom infrastructure for endotoxin-controlled pharmaceutical production lines. For New Entrants and Emerging Players: Enter via liquid emulsion format specialization targeting Japanese and Korean serum manufacturers seeking ready-to-incorporate lipid bases. White-space exists in RSPO-aligned botanical extraction for Northern European clean beauty supply chains. Pursue technical partnerships with direct-to-consumer serum brands in Tokyo and Seoul for micro-batch procurement relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap fermentation specialists with established MFDS compliance and K-beauty channel access because supplier concentration creates scarcity value for qualified production assets. Target acquisition archetypes include Asian fermentation houses with liquid emulsion formulation capabilities and European botanical extractors with sustainable sourcing certification. Watch ECHA guidance revisions for biotechnology-derived ingredients as inflection indicator for registration-driven supply restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Metabolically optimized yeast strains at Korean biotechnology platforms compress C18 sphingoid base production economics. |
| Pharmaceutical-Grade Certification | Endotoxin-controlled specifications unlock atopic dermatitis therapeutics beyond cosmetic cosmeceutical positioning. |
| Backward Integration into Feedstock Supply | Glucose substrate control at German chemical houses insulates margin stability from agricultural commodity volatility. |
| Direct Technical Partnership Model | Seoul-based formulators bypass distributor intermediaries through co-development relationships with fermentation specialists. |
| RSPO-Aligned Botanical Extraction | Sustainable sourcing certification unlocks premium positioning in Northern European clean beauty supply chains. |
Research Methodology
Direct dialogue with fermentation house technical directors, cosmetics formulation R&D leads, regulatory affairs specialists at ECHA and MFDS, and procurement managers at Seoul-based K-beauty manufacturers grounded qualitative insights. Secondary validation drew from REACH registration dossiers, MFDS microbial standards documentation, customs trade data for C18 sphingoid base imports, and SEC filings of integrated chemical producers. Bottom-up volume modeling triangulated against top-down market sizing across powder, liquid, and emulsion format segments.
Bottom-up modeling aggregated segment-level volume and value trajectories across cosmetic-grade, pharmaceutical-grade, and personal care application tiers, then cross-referenced against top-down macroeconomic indicators. Segmentation dimensions included product format physics, purity specification thresholds, regional regulatory clusters, and end-user procurement channel structure. CAGRs were derived from trend extrapolation of biotechnology platform yield improvements and K-beauty export volume patterns. Forecast inputs incorporated fermentation substrate cost indices and ECHA guidance revision timelines.
Inputs from primary interviews and regulatory documentation were available through the study window; gaps in real-time fermentation yield data and confidential contract pricing introduce uncertainty bands around volume projections. Forecasts reflect documented assumptions regarding biotechnology platform maturation rates and REACH compliance timelines. A small set of named triggers warrants ongoing watch: ECHA substance identity requirement revisions, MFDS microbial limit updates, and agricultural commodity price shocks affecting fermentation substrate economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
North America Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Affinity Chromatography Reagents Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Cellulose Ether Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Sodium Adipate Market
Specialty Chemicals
Multichannel Reagent Reservoir Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Global Specialty Fuel Additives Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Perms and Relaxants Market
Specialty Chemicals
Automotive Silicone Market
Specialty Chemicals
Superdisintegrants Market
Specialty Chemicals
Technical Aerosol Market