
 Global Bio Polyamide Market | 2026-2036
Global Bio Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio Polyamide Market Intelligence
New production capacity additions in China are fragmenting the established European-centric supplier base for bio polyamides. Arkema leverages its long-standing expertise in castor oil chemistry to maintain a premium position in high-performance grades. Meanwhile, Cathay Biotech specializes in the production of bio-based nylon intermediates, controlling a key part of the upstream value chain. DSM-Firmenich competes with a portfolio of engineered materials for specialized electronics and automotive applications.
Bio polyamides are polymers derived partially or fully from renewable feedstocks such as castor oil or other plant-based sources. They offer properties comparable to conventional nylons, including high mechanical strength and thermal stability, but with a reduced carbon footprint. Performance-driven applications in the automotive sector, particularly for under-the-hood components, constitute a major demand driver. Within product types, Bio-Based Nylon 610 and other long-chain variants command higher margins due to their specialized performance characteristics.
Regulatory frameworks like the European Union's REACH and its Green Deal directly influence material specification in consumer and industrial goods. Similarly, China's dual carbon goals encourage the use of bio-based materials to lower the environmental impact of its manufacturing sector. Securing a stable and cost-competitive supply of bio-based feedstocks remains a critical strategic consideration for all producers.
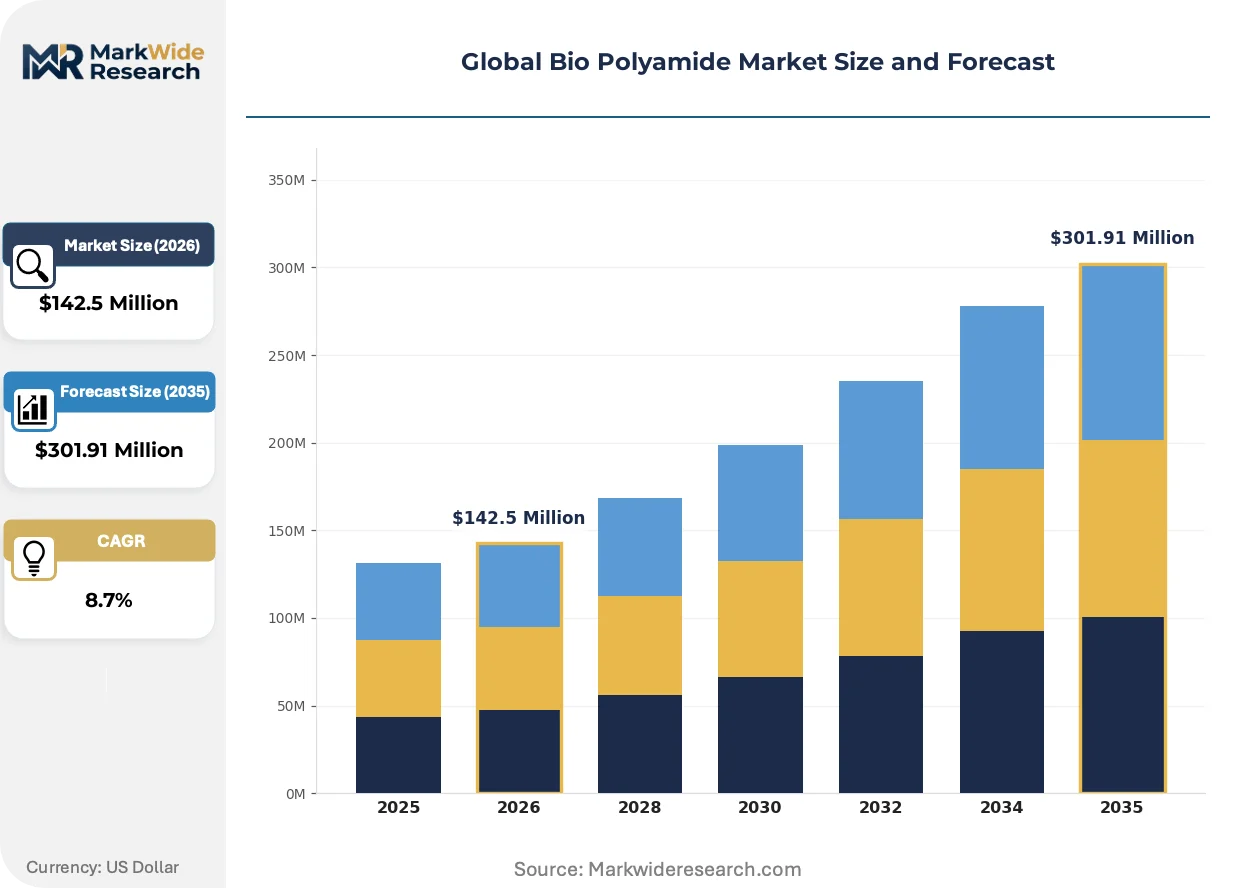
Market Dynamics
The central dynamic reshaping the bio polyamide market is the geographic fragmentation of its supply base. Historically concentrated in Europe, new large-scale production capacity in China is challenging established players and altering global trade flows for key intermediates and finished polymers.
Growth Catalysts
- Automotive Lightweighting:The automotive industry's push to reduce vehicle weight for improved fuel efficiency and electric vehicle range drives demand for high-strength, low-density bio polyamides in under-the-hood components and structural parts.
- Regulatory Mandates:Frameworks like the EU Green Deal and China's dual carbon goals create powerful incentives for manufacturers to incorporate materials with a lower carbon footprint, directly benefiting bio-based polymers.
- Performance Material Development:Advances in polymerization create specialized long-chain bio polyamides, such as Bio-Based PA 610, that offer superior thermal and chemical resistance, opening up high-margin applications inaccessible to standard grades.
Market Restraints
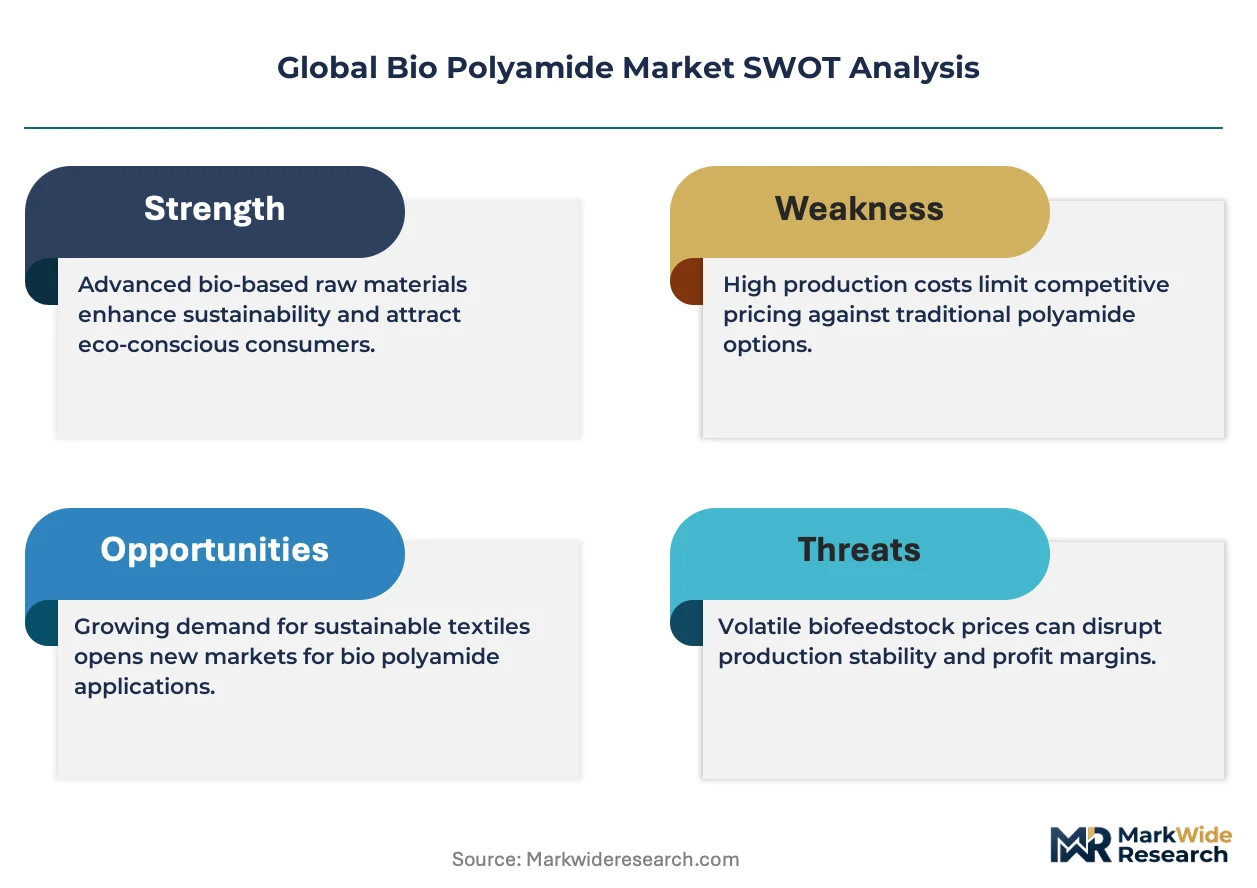
- Feedstock Price Volatility:The market's reliance on agricultural feedstocks like castor oil exposes producers to price fluctuations driven by crop yields, weather patterns, and competing demands from other industries.
- Performance Parity Gaps:While offering many comparable properties, some bio polyamide grades still exhibit limitations in extreme thermal stability or hydrolysis resistance compared to specific high-performance petroleum-based nylons.
- Substitution from Conventional Polymers:In cost-sensitive applications, conventional petroleum-derived polyamides like Nylon 6 and Nylon 66 remain a significant substitution threat due to their established production scale and lower price points.
Strategic Opportunities
- Consumer Electronics Casings:Penetrating the market for durable and aesthetically pleasing casings for smartphones, laptops, and other electronic devices offers a high-volume opportunity where sustainability is a key purchasing differentiator.
- North American Market Development:Stricter emissions standards from the EPA and a growing corporate focus on sustainability create an opening for bio polyamide adoption in the US and Canadian automotive and consumer goods sectors.
- Textile and Fiber Applications:Developing bio polyamide fibers for performance apparel and technical textiles presents a significant growth vector, leveraging the material's durability and potential for a circular economy model.
Industry Challenges
- Feedstock Supply Chain Security:Securing a consistent, cost-effective, and sustainably certified supply of raw materials like castor oil or other bio-based monomers is a critical operational hurdle for producers.
- Capital Investment Cycles:The construction of new bio-fermentation and polymerization facilities is highly capital-intensive, which can slow the industry's ability to respond quickly to demand surges and creates high barriers to entry.
- Standardization and Certification:A lack of globally harmonized standards for bio-content verification and end-of-life processing creates complexity for suppliers and can lead to confusion for end-users, hindering material specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio Polyamide Market |
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $301.91 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Based Nylon 6, Bio-Based Nylon 66, Bio-Based Nylon 610, Bio-Based Nylon 12 Application: Textiles, Automotive Components, Electrical Insulation, Packaging Materials End User: Apparel Industry, Consumer Goods, Automotive Sector, Electronics Form: Filament, Granule, Sheet, Fiber |
| Companies Covered | Arkema, Cathay Biotech, DSM-Firmenich, Solvay, LANXESS, Evonik Industries, Avient Corporation, Domo Chemicals, Ascend Performance Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio Polyamide Market Strategic Shifts & Innovations
Material science is advancing on two parallel fronts, with computational design accelerating the discovery of novel bio-polymers while stringent sustainability reporting reshapes procurement criteria. This dual evolution is creating a market where performance and environmental accountability are intrinsically linked.
Computational chemistry platforms are enabling the rapid design of new bio polyamide structures with tailored properties. R&D teams in the automotive and electronics sectors are adopting these tools to screen thousands of potential monomer combinations and predict performance before synthesis. This acceleration is virtualizing the traditional, trial-and-error polymer development cycle, reducing time-to-market for new formulations.
The United States Inflation Reduction Act (IRA) provides significant tax credits and incentives for domestic manufacturing of clean energy technologies and sustainable materials. This policy directly encourages investment in US-based production of bio polyamides and their precursor feedstocks. The automotive supply chain is responding by exploring localized sourcing for components to meet domestic content requirements for EV tax credits.
A definitive shift in OEM purchasing behavior requires suppliers to provide extensive life cycle assessment (LCA) data and third-party certifications. This displaces older procurement models based on simple technical data sheets, integrating sustainability metrics as a core decision criterion. This trend is most pronounced in the European automotive sector, where compliance with the Corporate Sustainability Reporting Directive (CSRD) is mandatory.
Global Bio Polyamide Market Segmentation
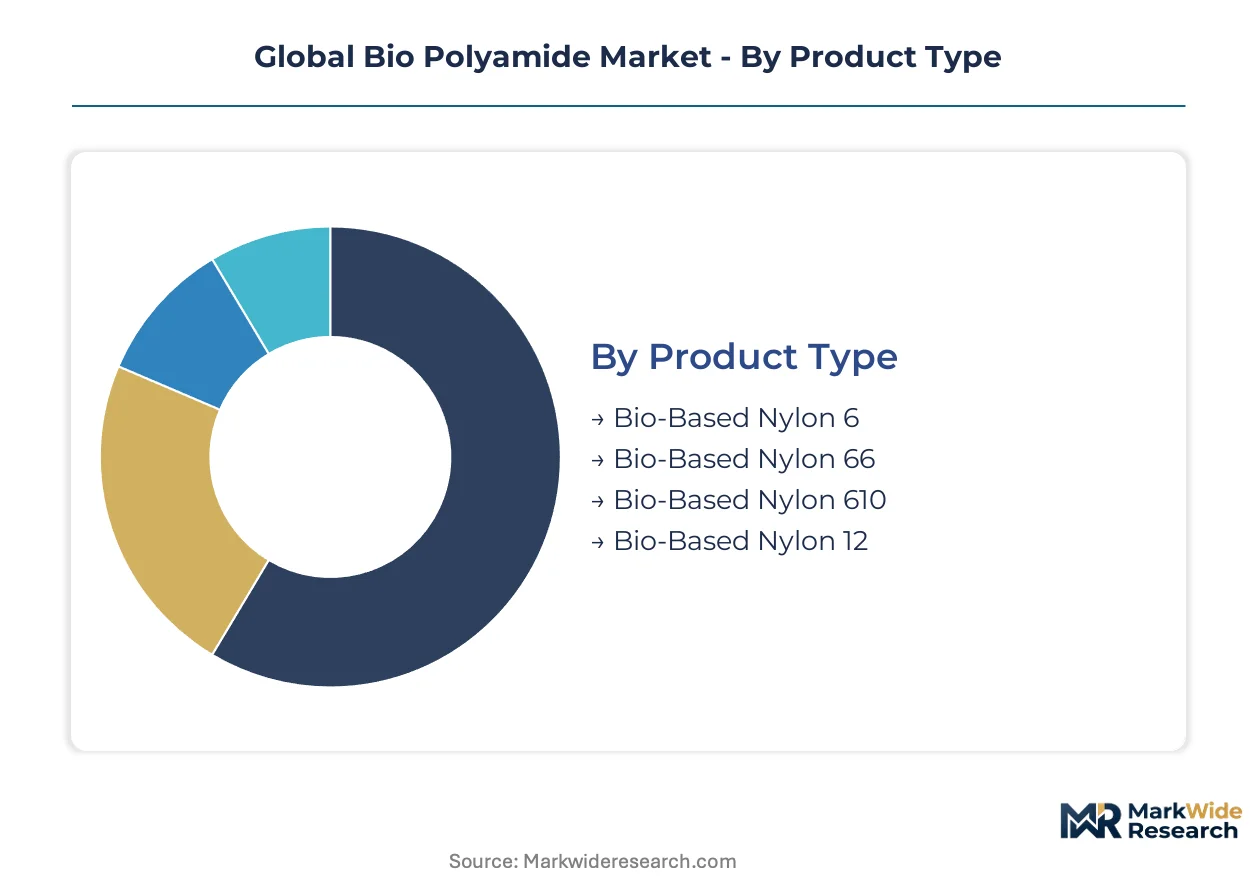
Understanding the segmentation of the global bio polyamide market is crucial for identifying precise demand pockets and strategic investment areas. This detailed breakdown illuminates where specific material properties and end-use requirements converge, driving value across the bio-based polymer landscape.
Product Type:
The after-sales service intensity for bio polyamide product types varies significantly, influenced by material complexity and end-use application demands.
- Bio-Based Nylon 610:This long-chain bio polyamide is typically derived from castor oil, offering superior thermal stability and chemical resistance compared to shorter chain nylons. Demand concentrates in high-performance automotive parts, where its durability and reduced environmental footprint are critical for lightweighting initiatives.
- Bio-Based Nylon 12:A high-performance bio polyamide known for its low moisture absorption, excellent chemical resistance, and dimensional stability, often produced from castor oil. This grade finds significant demand in specialized electronics and precision automotive components, driven by stringent performance requirements and sustainability goals.
- Bio-Based Nylon 6:This bio-based variant provides a balance of mechanical strength and processability for general engineering applications.
- Bio-Based Nylon 66:Offering good rigidity and heat resistance, this bio-based polymer is suitable for structural components in various industries.
By volume, Bio-Based Nylon 6 leads due to its versatility. By growth pace, Bio-Based Nylon 610 is ahead, driven by specialized performance requirements.
Application:
Cost tier differentiation is evident across bio polyamide applications, with specialized uses commanding higher material specifications and pricing.
- Automotive Components:Bio polyamides are engineered for under-the-hood components, interior parts, and structural elements, leveraging their lightweight properties and high strength. Demand is concentrated in Germany and China, where stringent emission standards and EV production targets necessitate sustainable material solutions.
- Textiles:Bio polyamide fibers offer durability, comfort, and a reduced environmental impact for performance apparel, sportswear, and technical textiles. The European market drives demand, with consumers increasingly prioritizing sustainable fashion choices and circular economy models.
- Electrical Insulation:Bio polyamides provide reliable dielectric strength and heat resistance for various electronic and electrical system components.
- Packaging Materials:These bio-based polymers are utilized in flexible and rigid packaging solutions, offering barrier properties and improved sustainability profiles.
Automotive Components hold the largest market share due to consistent demand for lightweighting. Packaging Materials are gaining market share, reflecting consumer and regulatory shifts towards sustainable options.
End User:
Supply concentration within bio polyamide end-user segments often reflects the established value chains and specific material requirements of each industry.
- Automotive Sector:This industry utilizes bio polyamides for vehicle lightweighting, fuel efficiency improvements, and sustainable material integration in interior and exterior parts. Demand is particularly strong in Germany and Japan, driven by advanced engineering requirements and a focus on circular economy principles.
- Electronics:Bio polyamides are specified for casings, connectors, and internal components in devices like smartphones and laptops, offering durability, aesthetics, and a lower carbon footprint. The Chinese manufacturing base leads demand, influenced by consumer preferences for sustainable products and regulatory incentives.
- Apparel Industry:Bio polyamides are used for performance wear and sustainable fashion, offering strength and comfort with reduced environmental impact.
- Consumer Goods:This segment includes various products from household items to sports equipment, benefiting from the durability and sustainable profile of bio polyamides.
The Automotive Sector's demand is driven by stringent emissions regulations. The Electronics segment's growth is propelled by consumer preference for sustainable and high-performance device materials.
Form:
Application diversity significantly influences the demand for bio polyamides across different forms, catering to specific manufacturing processes and end-use requirements.
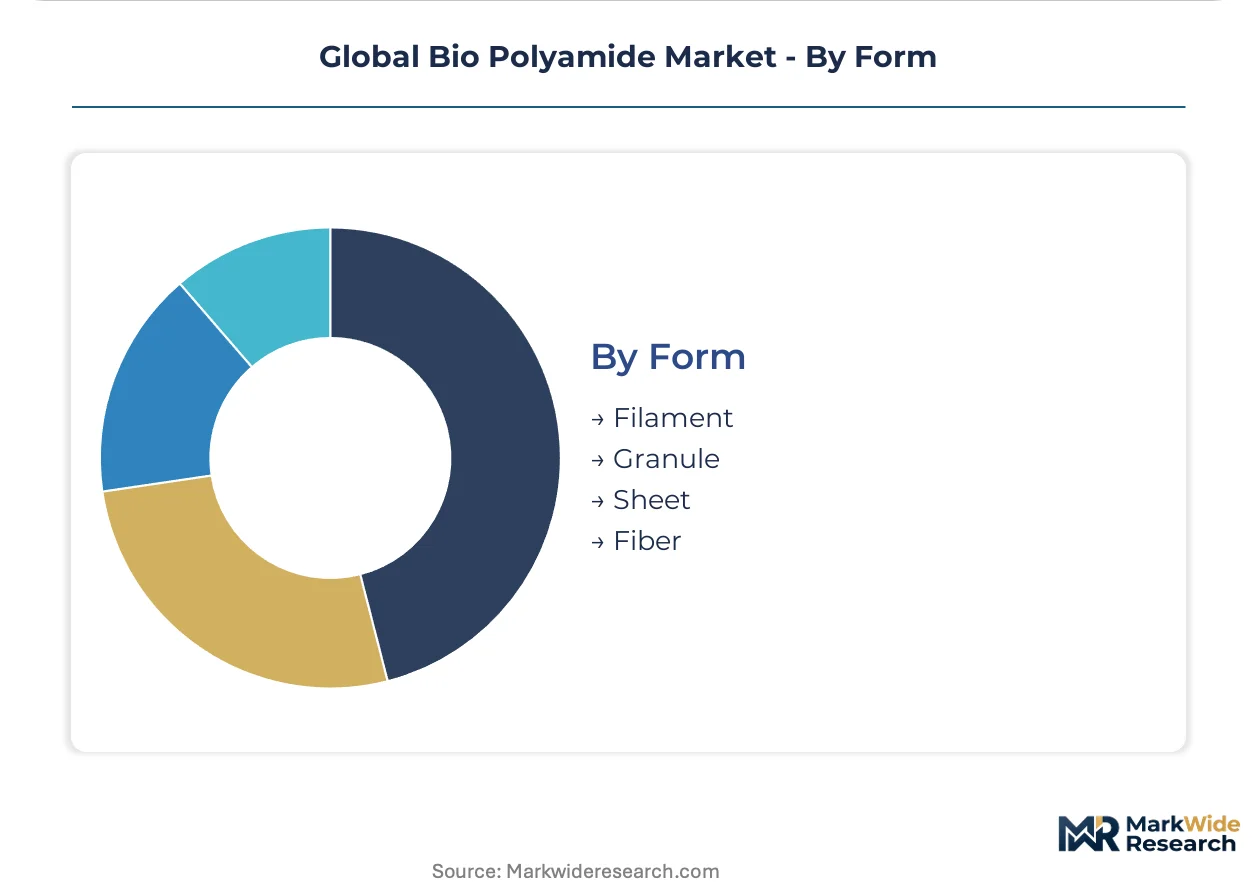
- Granule:This form is the most common for injection molding and extrusion processes, enabling the production of diverse components for automotive and consumer goods. Its versatility makes it a foundational input for various manufacturing operations across China and Europe.
- Fiber:Bio polyamide fibers are extensively used in the textile industry for performance apparel, technical textiles, and non-woven applications due to their strength and sustainability. Demand for these fibers is notably high in European textile hubs, driven by eco-conscious brands.
- Filament:Used in 3D printing and specialized textile applications, bio polyamide filament offers precision and strength for advanced manufacturing.
- Sheet:Bio polyamide sheets are employed in packaging and construction, providing durable and flexible material solutions.
Granule form dominates in manufacturing hubs like China due to widespread processing capabilities. Fiber form sees strong demand in European textile production centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's Green Deal significantly influences material specification across the global bio polyamide market. This regulatory framework, coupled with China's dual carbon goals, drives demand for sustainable bio-based polymers. Consequently, regional market dynamics are shifting, reflecting diverse regulatory and industrial priorities.
China
China's robust manufacturing base and significant electronics sector fuel demand for bio polyamides. The country's dual carbon goals provide strong incentives for bio-based material adoption. Industrial clusters in the Yangtze River Delta integrate these polymers into diverse consumer and automotive applications.
Germany
Germany's advanced automotive sector leads demand for high-performance bio polyamides in lightweighting initiatives. Compliance with the EU Green Deal and CSRD mandates sustainable material choices. Engineering hubs in Bavaria and Baden-Württemberg develop specialized bio-based components for electric vehicles.
United States
The United States market sees growing bio polyamide adoption driven by automotive sustainability targets and consumer goods preferences. The Inflation Reduction Act (IRA) incentivizes domestic production of sustainable materials. Automotive supply chains in the Midwest explore localized sourcing for bio-based components.
Japan
Japan's precision engineering and automotive industries generate consistent demand for specialized bio polyamides. METI supports the development of advanced sustainable materials. Manufacturers in the Kanto region focus on bio-based polymer integration for enhanced product life cycles.
France
France's prominent textile industry drives demand for bio polyamide fibers in performance apparel and technical textiles. National circular economy policies, aligned with the EU Green Deal, encourage sustainable material innovation. Textile innovation centers in the Auvergne-Rhône-Alpes region develop new bio-based fabric applications.
Global Bio Polyamide Market Key Industry Players
Specialty chemical manufacturers and bio-based feedstock producers split the market for bio polyamides. The market structure is evolving from a European-centric model to a more geographically diverse landscape. Integrated players focus on high-performance grades, while upstream specialists control key intermediates. Strategic partnerships for feedstock security and significant capacity expansion in China are dominant competitive moves.
Specialists in high-performance bio-based polymers, such as Arkema, leverage long-standing expertise in castor oil chemistry for premium grades. Cathay Biotech, a China-based company, occupies a pivotal position by specializing in the production of bio-based nylon intermediates, thereby controlling a key part of the upstream value chain. DSM-Firmenich, a global science-based company, exemplifies a player offering engineered materials for specialized electronics and automotive applications, showcasing portfolio diversification within the market.
| Leading Market Players |
|---|
| Arkema |
| Cathay Biotech |
| DSM-Firmenich |
| Solvay |
| LANXESS |
| Evonik Industries |
| Avient Corporation |
| Domo Chemicals |
| Ascend Performance Materials |
Cost & Logistics Intelligence
The China-Europe maritime freight corridor's cost dynamics significantly influence bio polyamide supply concentration and downstream price differentiation. This corridor manages substantial volumes of intermediates and finished polymers, impacting global market pricing.
Pricing Analysis
Geographic price spreads for bio polyamides exist, with premium grades commanding higher prices in Europe due to stringent regulatory demands. The dominant pricing model is contract-based long-term offtake, particularly for high-volume automotive and electronics applications. Price differentiation stems from material quality grade, bio-content certification level, and regional delivery costs. Pricing softness reflects increased competition from new Chinese production capacity. The automotive sector exhibits the least price sensitivity for specialized performance parts, while general consumer goods applications show higher price sensitivity.
Supply Chain Analysis
The EU Green Deal's material specification requirements influence bio polyamide supply chain flows, creating a preference for certified sustainable inputs. Geographic supply concentration centers in China, alongside established European producers in Germany and France. The market relies on key raw materials like castor oil and other bio-based monomers. Feedstock price volatility presents a significant structural risk for producers. Distribution primarily runs through direct sales channels to large industrial end-users and specialized distributors for smaller volume applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio polyamide market is at a platform-economics inflection, driven by the expanding sustainable materials ecosystem and interoperability between bio-based polymer production and end-use manufacturing processes.
For Market Incumbents: Entrench existing market share by backward integration into bio-based feedstock production, securing long-term supply agreements for critical raw materials. Expand the portfolio of high-performance bio polyamide grades, focusing on specialized automotive and electronics applications. Invest in advanced bio-content certification and LCA data to counter the threat from emerging lower-cost producers. Prioritize R&D in novel bio-polymers to address performance parity gaps with petroleum-based alternatives.
For New Entrants and Emerging Players: North American market underpenetration offers a significant white-space opportunity for bio polyamide adoption in automotive and consumer goods. Target the rapidly expanding textile and fiber applications, leveraging sustainability as a key differentiator. The consumer electronics casings segment is particularly penetrable for new players offering durable and aesthetically pleasing bio-based solutions. A go-to-market angle should focus on providing specialized, high-margin solutions with clear environmental benefits.
For Investors and Strategic Acquirers: The European Union's Corporate Sustainability Reporting Directive (CSRD) reshapes the acquisition landscape, favoring companies with robust sustainability credentials. Long-term viability over the next decade hinges on the ability to scale sustainable material production and secure feedstock. Acquisition targets should include upstream bio-fermentation startups with proprietary technology or feedstock processing specialists. A key signal to watch is the increasing rate of bio polyamide adoption in previously petroleum-dominated electronics applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | New production facilities in China challenge established European players. |
| Backward Integration into Feedstock | Secures stable and cost-competitive supply of bio-based monomers for producers. |
| Green Manufacturing Transition | Achieves compliance with global regulatory mandates like the EU Green Deal. |
| Long-term Supply Agreements | Mitigates feedstock price volatility for bio polyamide manufacturers. |
| Joint Venture for R&D | Accelerates the development of novel bio polyamide structures and applications. |
Research Approach
The analysis maps bio polyamide product types, applications, and end-user segments, each validated through extensive interviews with R&D directors, procurement leads, material engineers, and sustainability officers. Secondary data sources include customs and trade data, corporate sustainability reports, technical specification sheets, and regulatory filings like REACH. This approach integrates both bottom-up market sizing and top-down validation for comprehensive insights.
The forecast framework holds macroeconomic stability and current regulatory trajectories fixed while varying adoption rates across the analysis window. Segmentation dimensions modeled include product type, application, end-user, form, and regional regulatory frameworks. Compound annual growth rates are derived from historical market size, observed trends, and expert consensus. Key industry-specific forecast inputs include feedstock availability and planned new production capacity additions.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or energy prices would shift the trajectory. Forecasts reflect assumptions documented through primary and secondary research. Geopolitical tensions affecting trade flows or rapid technological disruption in competing materials would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Bio-Based Polymer Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market