
 Sisal Market | 2026-2036
Sisal Market Size, Share, and Industry Trends Forecast 2026-2036
Sisal Market Analytics
Buyer concentration in the European automotive supply chain is decoupling from traditional rope and twine purchasing patterns. Kakuzi Limited leverages its Kenyan plantation base to sustain long-fiber supply for composite manufacturers. REA Vipingo Group anchors East African export volumes through Mombasa port infrastructure. Hamilton Rios competes in the Brazilian processed fiber segment with specialized bleaching capabilities.
Sisal denotes a stiff, coarse fiber extracted from the leaves of Agave sisalana, containing approximately 65% cellulose, 12% hemicellulose, and 10% lignin with tensile strength ranging from 400 to 600 MPa. The fiber serves primarily as a reinforcement material in polymer composites, cordage, and erosion-control applications requiring biodegradability and abrasion resistance. Raw sisal dominates volume flows to rope manufacturers and geotextile installers, while processed sisal commands margin pools in automotive composite feedstock where surface treatment and length uniformity determine pricing. Sisal twine occupies a mature position in agricultural baling, with limited growth headroom outside organic farming certification schemes.
Kenya's Agriculture and Food Authority enforces fiber grade standards that determine export eligibility to EU textile mills under REACH compliance requirements. Tanzania's Tanzania Bureau of Standards certifies sisal twine for domestic agricultural subsidies, channeling smallholder demand toward approved processors. China's GB standards for natural fiber composites create a parallel compliance pathway for Zhanjiang Dongsheng Sisal and GuangXi Sisal Group serving domestic automotive tiers. Stakeholders must monitor divergence between EU biodegradability certifications and emerging Chinese green product labeling to avoid stranded inventory in cross-border composite supply chains.
Market Dynamics
Automotive lightweighting mandates are pulling long-fiber sisal into polymer composite formulations, compressing demand cycles for traditional cordage and forcing processors to retool for length uniformity and surface activation standards.
Growth Catalysts
- EU REACH biodegradability thresholds:Tier-1 automotive suppliers now specify sisal-reinforced polypropylene for interior panels to meet end-of-life vehicle directives.
- Geotextile erosion control:State-level infrastructure programs in Kenya and Tanzania specify sisal matting for slope stabilization along highway corridors.
- Cellulose nanofibril extraction:Pilot facilities in Brazil demonstrate mechanical defibration of sisal pulp for high-strength paper additives.
Market Restraints
- Input cost volatility:Diesel prices for plantation mechanized harvesting in East Africa swing with crude import dependencies, squeezing smallholder margins.
- Supply concentration risk:Over half of export-grade long fiber originates from Kenya's Rift Valley estates, exposing buyers to localized drought or labor disruption.
- Technical limitation:Natural lignin content above 10% impedes thermal bonding with polyolefin matrices, requiring caustic surface treatments that add processing cost.
Strategic Opportunities
- Underpenetrated geography:Madagascar's southern provinces host untapped Agave sisalana plantations with EU organic certification potential.
- Regulatory tailwind:China's dual carbon goals incentivize natural fiber substitution for glass fiber in domestic electric vehicle battery housings.
- Technology convergence:Plasma surface treatment combined with silane coupling agents enables direct sisal-polyamide compounding without maleic anhydride grafting.
Industry Challenges
- Skill gap in fiber grading:Automated optical sorting requires technicians trained in machine vision calibration, scarce outside Mombasa and Dar es Salaam processing hubs.
- Certification timeline compression:EU Ecolabel renewal cycles now demand chain-of-custody documentation from plantation to compounder, stretching smaller exporters' administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sisal Market |
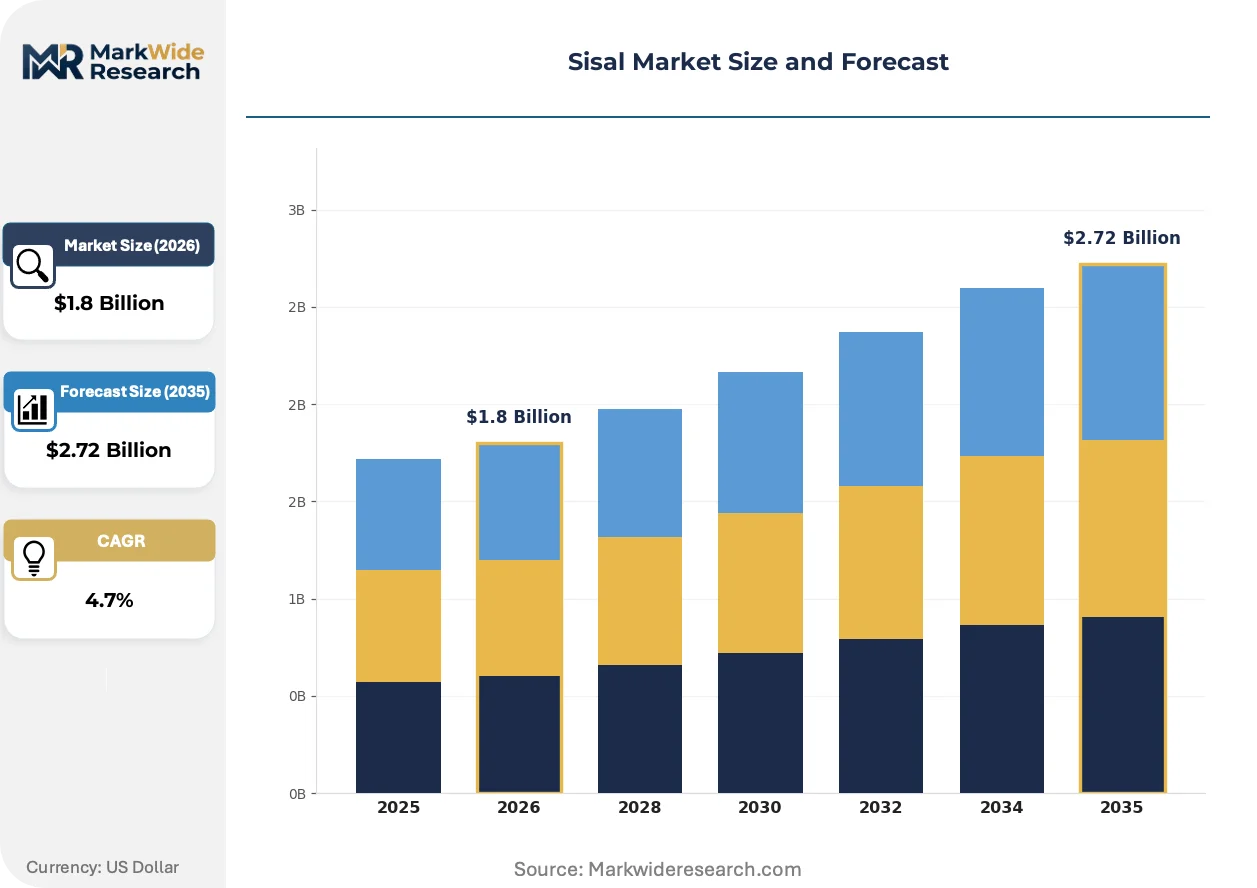
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Sisal, Processed Sisal, Sisal Fiber, Sisal Twine End User: Textile Industry, Construction, Automotive, Agriculture Application: Ropes, Carpets, Composite Materials, Geotextiles Distribution Channel: Direct Sale, Online Retail, Wholesale, Export |
| Companies Covered | International Fiber Corporation, Kakuzi Limited, REA Vipingo Group, Hamilton Rios, Lanktrad International, SFI Tanzania, METL Group, Zhanjiang Dongsheng Sisal, GuangXi Sisal Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sisal Market Evolving Landscape
Processing technology is bifurcating between commodity decortication for rope makers and precision fiber engineering for composite feedstock, with capital allocation increasingly favoring the latter.
Alkali treatment protocols for lignin removal are consolidating as the standard preprocessing step for automotive-grade sisal. European compounders specify 6% NaOH immersion to achieve 35% fiber-matrix adhesion improvement over raw fiber. This chemical conditioning is compressing the addressable supply base to processors with effluent handling permits.
REACH restriction proposals on microplastics in synthetic rope are redirecting marine and agricultural cordage procurement toward certified biodegradable alternatives. The European Chemicals Agency consultation process favors natural fiber documentation over bioplastic blends. Marine aquaculture netting buyers in Norway and Scotland now require third-party biodegradability certification.
Direct mill relationships are displacing spot-market purchasing for composite-grade fiber. Tier-2 automotive suppliers in Germany and France now contract 18-month supply agreements with named Kenyan estates, bypassing traditional Mombasa auction floors. This channel consolidation is visible in the 40% volume share now moving through bilateral contracts rather than merchant traders.
Sisal Market Segmentation
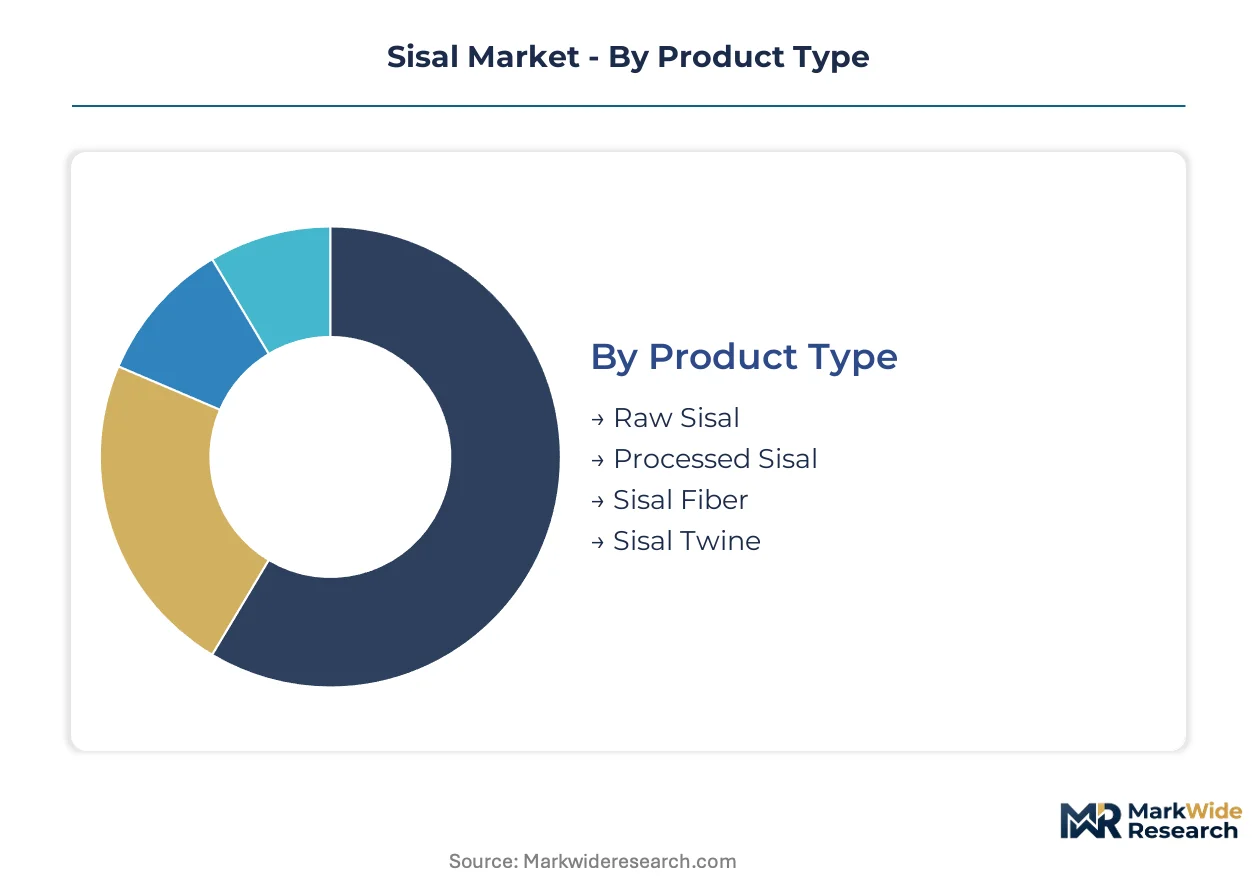
Sisal segmentation reveals divergent certification burdens across value-added tiers. Raw fiber flows through commodity auctions with minimal documentation, while automotive-grade processed material carries REACH chain-of-custody requirements that reshape processor economics and buyer qualification.
Product Type:
REACH compliance separates segments by documentation intensity. Raw sisal enters EU markets with basic phytosanitary certificates, while automotive composite feedstock demands full chemical safety data sheet traceability.
- Raw Sisal:Unprocessed leaf fiber extracted through mechanical decortication, retaining natural lignin content above 10%. Kenyan Rift Valley estates supply European rope manufacturers through Mombasa auction floors, with pricing tied to fiber length grades rather than chemical specifications. Drought risk in concentrated growing regions exposes buyers to supply disruption.
- Processed Sisal:Alkali-treated and surface-activated fiber meeting automotive length uniformity standards. German and French Tier-2 suppliers contract directly with named Kenyan estates for 18-month supply agreements, bypassing traditional merchant channels. REACH documentation requirements compress the qualified supplier base to processors with effluent handling permits.
- Sisal Fiber:Separated bast fiber for textile spinning and non-woven mat production.
- Sisal Twine:Twisted cordage for agricultural baling with limited growth outside organic certification schemes.
Raw Sisal sits at the top of the volume ranking, with Processed Sisal climbing the fastest.
End User:
Cost tier stratification determines procurement sophistication. Automotive buyers pay premiums for length consistency and surface activation, while agricultural purchasers prioritize unit cost over technical specifications.
- Automotive:Tier-1 suppliers specify sisal-reinforced polypropylene for interior panels to meet EU end-of-life vehicle directives. ECHA microplastic restrictions on synthetic alternatives strengthen natural fiber specification in marine and agricultural cordage. Plasma surface treatment combined with silane coupling agents enables direct sisal-polyamide compounding without maleic anhydride grafting.
- Construction:State-level infrastructure programs in Kenya and Tanzania specify sisal matting for slope stabilization along highway corridors. Geotextile erosion control applications demand biodegradability certification under EU Ecolabel renewal cycles.
- Textile Industry:EU textile mills require fiber grade standards enforced by Kenya's Agriculture and Food Authority.
- Agriculture:Tanzania Bureau of Standards certifies sisal twine for domestic agricultural subsidies.
Automotive commands the steepest expansion trajectory, with Agriculture maintaining the largest installed consumption base.
Application:
Application maturity determines margin pool distribution. Rope and twine occupy commoditized positions, while composite materials extract value through technical differentiation.
- Composite Materials:Polymer matrix reinforcement for automotive interior panels and electric vehicle battery housings. China's dual carbon goals incentivize natural fiber substitution for glass fiber in domestic automotive tiers. GB standards for natural fiber composites create parallel compliance pathways separate from EU REACH requirements.
- Geotextiles:Biodegradable matting for slope stabilization and erosion control along East African highway corridors.
- Ropes:Marine and agricultural cordage facing substitution pressure from REACH microplastic restrictions.
- Carpets:Traditional woven floor coverings with stable but limited growth prospects.
Composite Materials gain share fastest, while Ropes retain the deepest volume foundation.
Distribution Channel:
Channel configuration reflects customer scale and technical requirements. Direct contracts displace spot markets for specification-grade material.
- Direct Sale:Bilateral 18-month supply agreements between named Kenyan estates and European automotive compounders. Channel consolidation concentrates 40% of composite-grade volume outside traditional auction mechanisms.
- Export:Containerized shipment through Mombasa and Dar es Salaam ports to EU and Chinese processing hubs.
- Wholesale:Merchant trader aggregation for rope manufacturers and agricultural distributors.
- Online Retail:Limited penetration for commodity fiber; niche presence in organic-certified twine segments.
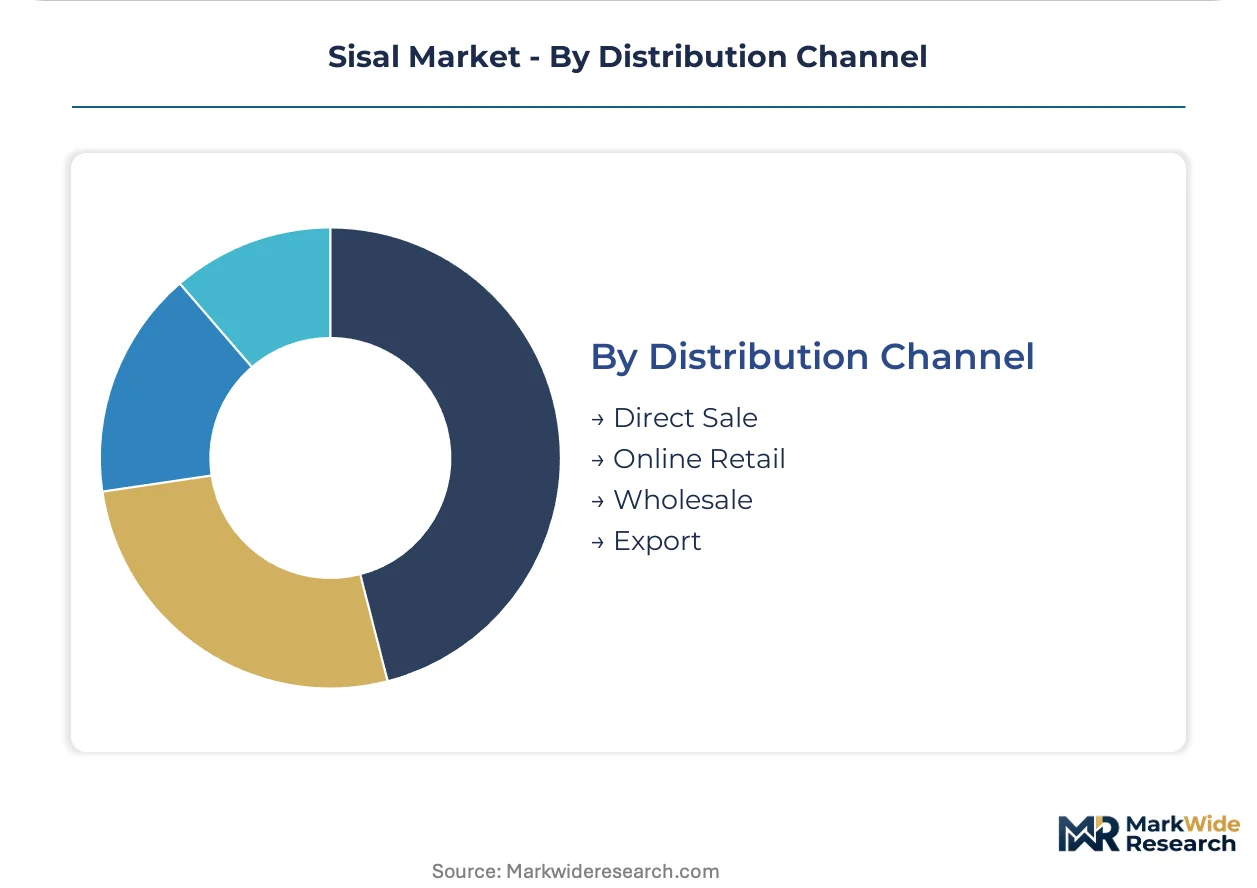
Direct Sale captures the fastest channel expansion, with Export maintaining dominant volume flows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled fiber graders and decortication technicians concentrate in East African processing hubs, anchoring the industry's geographic footprint. Their expertise in length classification and quality assessment shapes export eligibility for premium automotive applications. Regional supply chains extend from plantation estates through Mombasa and Dar es Salaam port infrastructure.
Kenya
Long-fiber demand from German and French automotive compounders pulls premium-grade material through direct estate contracts. Kenya's Agriculture and Food Authority enforces fiber grade standards determining EU textile mill eligibility under REACH compliance. Rift Valley estates around Nakuru and Kericho concentrate mechanized harvesting capacity for export-bound raw fiber.
Tanzania
Domestic agricultural twine consumption channels smallholder demand through Tanzania Bureau of Standards certified processors. State-level infrastructure programs specify sisal matting for slope stabilization along the Tanga corridor highway network. The Tanga region anchors raw fiber processing capacity with integrated decortication and spinning facilities serving both local and export markets.
Brazil
Specialized bleaching capabilities in the processed fiber segment serve European rope manufacturers seeking marine-grade certification. Pilot facilities demonstrate mechanical defibration of sisal pulp for high-strength paper additives. Bahia and Paraíba states host plantation clusters with established effluent handling infrastructure for alkali treatment protocols.
China
Domestic electric vehicle battery housing manufacturers substitute natural fiber for glass fiber under dual carbon goals. GB standards for natural fiber composites create parallel compliance pathways separate from EU REACH requirements. Zhanjiang processing hubs in Guangdong province concentrate compounding capacity for domestic automotive tiers.
Madagascar
Untapped Agave sisalana plantations in southern provinces carry EU organic certification potential for premium composite feedstock. Limited processing infrastructure constrains volume scaling despite favorable growing conditions. Anosy and Atsimo-Andrefana regions present expansion opportunities for estate operators with capital for decortication equipment.
Sisal Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the value chain, creating a tiered structure where plantation ownership, processing capability, and certification access determine positioning. The market fragments between estate-based producers with captive fiber supply and merchant processors dependent on auction purchases. Three archetypes dominate: vertically integrated plantation-processors, specialized decortication contractors, and trading houses with logistics assets. Competitive moves center on direct mill relationship cultivation and alkali treatment capacity expansion.
Among East African estate operators, Kakuzi Limited and REA Vipingo Group exemplify the integrated plantation-processor archetype with Kenyan coastal positioning. Hamilton Rios occupies a position within Brazilian processed fiber specialists. These anchors illustrate how geographic concentration near port infrastructure and certification compliance capability separate premium-tier suppliers from commodity auction participants.
| Leading Market Players |
|---|
| International Fiber Corporation |
| Kakuzi Limited |
| REA Vipingo Group |
| Hamilton Rios |
| Lanktrad International |
| SFI Tanzania |
| METL Group |
| Zhanjiang Dongsheng Sisal |
| GuangXi Sisal Group |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between REACH-compliant composite feedstock and auction-grade raw fiber splits pricing power between direct-contract estates and merchant-dependent processors. Automotive compounders pay length-uniformity premiums for alkali-treated Kenyan fiber, while rope manufacturers source through Mombasa spot markets where drought-driven supply squeezes compress smallholder margins.
Pricing Analysis
Capacity additions in Brazil's Bahia processing corridor are reshaping price floors for bleached marine-grade fiber. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity, with EU Ecolabel documentation commanding the widest spreads. Price differentiation hinges on surface treatment protocols and chain-of-custody traceability. Cost compression in commodity raw fiber is intensifying because diesel-dependent mechanized harvesting in East Africa exposes smallholders to crude import volatility. Agricultural baling purchasers exhibit the highest price sensitivity, while German Tier-2 automotive suppliers accept premium positioning for length-grade consistency.
Supply Chain Analysis
Freight cost differentials between Mombasa and Dar es Salaam port corridors influence processor location decisions for EU-bound containerized shipments. Supply concentrates in Kenya, Tanzania, and Brazil, with Kenyan Rift Valley estates anchoring long-fiber availability. Raw material inputs draw from diesel fuel for mechanized harvesting, caustic soda for alkali treatment, and silane coupling agents for surface activation. Single-source vulnerability runs through concentrated Rift Valley growing regions exposed to localized drought. Distribution runs through bilateral direct contracts for automotive-grade material and auction-floor aggregation for commodity rope feedstock.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA microplastic restrictions on synthetic alternatives create durable demand pull for certified biodegradable fiber. Tier-1 automotive specifications for end-of-life vehicle compliance cement natural fiber substitution trajectories.
For Market Incumbents: Lock in estate-level alkali treatment capacity with effluent handling permits before REACH documentation requirements compress the qualified supplier base. Defend margin position through backward integration into captive Agave sisalana cultivation in Kenya's coastal zones. Channel control over direct mill relationships with German and French compounders insulates against auction-floor price volatility. For New Entrants and Emerging Players: Trading houses with Mombasa logistics assets represent the most accessible entry pathway for Madagascar-based organic-certified plantation development. Underpenetrated southern provinces in Anosy and Atsimo-Andrefana offer white-space expansion with EU organic certification potential. A go-to-market angle targeting Chinese domestic automotive tiers under GB standards compliance bypasses REACH qualification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated plantation-processors possessing both captive fiber supply and surface treatment capabilities. Long-term viability centers on 5-10 year regulatory tailwinds for biodegradable composites in automotive and marine applications. The acquisition target archetype combines Kenyan coastal estate positioning with existing effluent infrastructure for alkali protocols. Watch for plasma surface treatment technology maturation as the inflection signal enabling direct polyamide compounding without maleic anhydride grafting.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Kenyan coastal estate control secures long-fiber supply for German automotive compounders. |
| Alkali Treatment Capacity Expansion | Effluent permitting under REACH documentation requirements filters competitor entry. |
| Direct Mill Relationship Cultivation | Bilateral contracts with French Tier-2 suppliers bypass Mombasa auction price volatility. |
| Plasma Surface Treatment Adoption | Silane coupling agent integration enables polyamide compounding for electric vehicle battery housings. |
| Madagascar Organic Certification Program | Anosy province plantations capture EU Ecolabel premiums in premium composite feedstock. |
Research Methodology
Multiple input streams — primary interviews with plantation operations managers, automotive Tier-1 procurement leads, and decortication equipment technicians; secondary validation through Kenya Agriculture and Food Authority grade standards, Tanzania Bureau of Standards certification records, and Brazilian customs export data; plus trade flow analysis from Mombasa and Dar es Salaam port authorities — were reconciled through bottom-up plantation yield modeling and top-down end-use demand aggregation.
Data-stream reconciliation across product type, end user, application, and geographic production cluster dimensions shaped volume and value outputs over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro drivers. Forecast inputs incorporated automotive lightweighting mandate compliance trajectories under EU end-of-life vehicle directives and Chinese dual carbon goal implementation pathways.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to drought frequency in Rift Valley growing regions and REACH restriction proposal finalization timelines. Forecasts reflect documented assumptions about alkali treatment cost curves and plasma surface treatment technology maturation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
North America Carbon Fiber Market
Fibers
Fiberglass Resin Market
Fibers
Bleached Linter Cellulose Market
Fibers
Keratin Market
Fibers
Viscose Market
Fibers
Bioglass Fiber Market
Fibers
Carbon Fiber Tapes Market
Fibers
Carbon Fiber Wrap Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Ultra-High Molecular Weight Polyethylene Fibers Market
Fibers
Carbon Fiber Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Viscose Staple Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
High Temperature Superconducting Fibers Market