

Thermoformed Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Fiber Market Insights
European molded fiber converter capacity is decoupling from legacy paperboard supply chains as dedicated thermoforming lines come online. Huhtamaki leverages its integrated pulp-to-package operations across Finland and Poland to secure fiber sourcing advantages. Brødrene Hartmann sustains leadership in egg and fruit packaging through proprietary vacuum-forming tooling optimized for recycled cellulose. Sonoco Products Company anchors North American supply with multi-plant compression molding networks serving food service accounts.
Thermoformed fiber denotes cellulose pulp or agricultural residue substrates that are slurry-formed, vacuum-deposited onto molds, pressed, and dried into dimensionally stable rigid containers with wall thickness typically ranging from 0.8 to 3.0 millimeters; the process yields compostable packaging and industrial dunnage that replaces expanded polystyrene and petroleum-based plastics. Natural fiber formulations dominate current tonnage owing to cost parity with recycled paperboard and established collection infrastructure, while carbon fiber-reinforced variants command premium positioning in aerospace components and sporting goods where strength-to-weight ratios justify material outlays. Vacuum forming technology leads packaging applications for its energy efficiency and tooling flexibility, though thermoforming press systems are gaining share in automotive interiors requiring deeper draws and tighter dimensional tolerances.
The EU Green Deal and F-Gas Regulation indirectly bolster thermoformed fiber by raising compliance costs for synthetic polymer competitors, while FDA food contact substance notifications govern cellulose tray acceptance in United States retail channels. China's GB standards for biodegradable materials and India's BIS certification requirements for food-grade molded products are creating divergent compliance pathways that favor regional specialists over standardized global platforms. Stakeholders must monitor regulatory acceleration in extended producer responsibility schemes and decide between regional formulation adaptation versus unified platform investments.
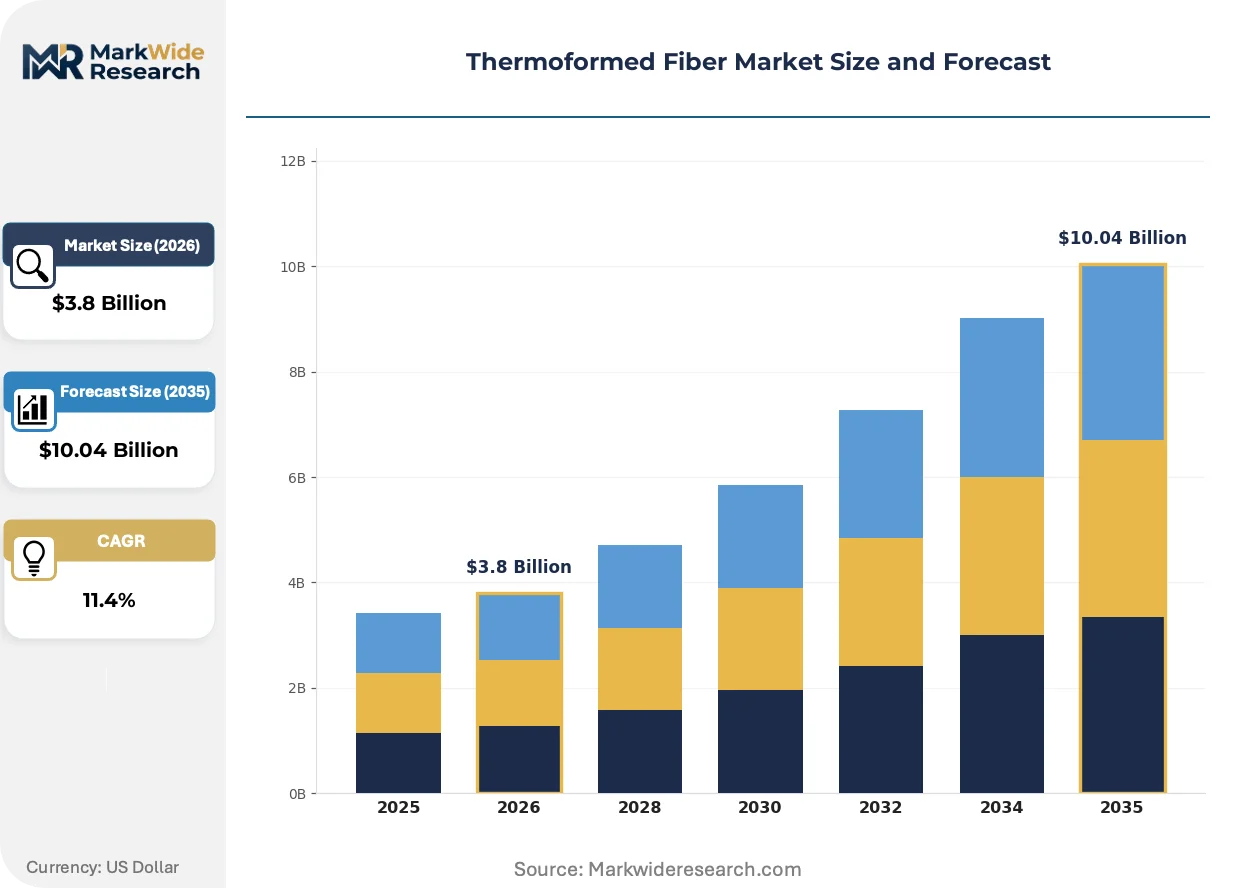
Market Dynamics
Single-use plastic bans across Germany, France, and California are forcing food service operators to reconfigure packaging procurement around cellulose-based alternatives, compressing supplier qualification timelines and reshaping converter capacity investments.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates recycled content minimums that thermoformed fiber satisfies through established pulp recovery streams, redirecting retail and food service procurement.
- Compression molding tooling advances:Enable deeper draws and tighter tolerances for automotive interior applications, opening industrial demand beyond traditional packaging.
- China:GB standards for biodegradable materials create compliance pathways that favor domestic molded fiber producers over imported synthetic alternatives.
Market Restraints
- Recycled OCC price volatility:Old corrugated container feedstock costs swing with Chinese import policy shifts, compressing converter margins unpredictably.
- Drying energy intensity:Thermoforming lines require sustained thermal input that exposes producers to natural gas and electricity price spikes.
- Barrier coating limitations:Current water-based and PLA coatings fail to match polyethylene performance for high-moisture foods, restricting addressable categories.
Strategic Opportunities
- India:BIS certification requirements for food-grade molded products favor early movers who establish local testing partnerships and formulation adaptation.
- Aerospace dunnage:Carbon fiber-reinforced variants command premium positioning where strength-to-weight ratios justify material outlays over expanded polystyrene.
- Extended producer responsibility schemes:France and Italy's advancing EPR frameworks create compliance service revenue streams for integrated fiber-to-package operators.
Industry Challenges
- Tooling engineer scarcity:Vacuum-forming mold design expertise concentrates in legacy paperboard regions, constraining capacity expansion in emerging production clusters.
- FDA food contact notification timelines:Cellulose tray approvals for novel barrier coatings extend 12-18 months, delaying product launches in United States retail channels.
- Legacy ERP integration:Converter scheduling systems built for paperboard runs require reconfiguration to handle thermoforming's shorter batch cycles and mold changeovers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Fiber Market Trends and Innovations
Equipment automation and material science advances are compressing cycle times while expanding thermoformed fiber into precision applications previously reserved for petroleum-based plastics.
Continuous thermoforming lines with inline drying and robotic transfer systems are overtaking batch vacuum-forming setups in high-volume food tray production. European dairy and produce packers are adopting these systems to meet retailer sustainability scorecard requirements. The technology is overtaking conventional molded pulp by cutting unit costs and enabling real-time thickness control.
The EU F-Gas Regulation raises compliance costs for synthetic polymer competitors using fluorinated greenhouse gases in foaming processes. Thermoformed fiber avoids these levies entirely while satisfying CSRD disclosure requirements for Scope 3 emissions. Food service operators in Germany and the Netherlands are accelerating cellulose tray specifications to preempt regulatory disadvantage.
Direct procurement relationships between quick-service restaurant chains and dedicated fiber converters are displacing traditional distribution through packaging wholesalers. Chains in California and New York negotiate multi-year supply agreements with guaranteed recycled content percentages. This pattern concentrates most visibly in burger and coffee segments where standardized tray formats enable scale commitments.
Thermoformed Fiber Market Segmentation
Thermoformed fiber applications span radically different performance requirements, from commodity food trays to aerospace-grade structural components. Segmentation reveals where pulp-based formulations compete on cost versus where engineered fiber composites command technical premiums.
Product Type:
Natural fiber formulations integrate directly into existing paperboard collection streams, while carbon and aramid variants demand specialized supply chains and processing equipment.
- Natural Fiber:Cellulose pulp derived from wood or agricultural residues dominates tonnage through cost parity with recycled paperboard. Food service operators in Germany and California specify these grades to meet single-use plastic bans while leveraging established municipal composting infrastructure.
- Carbon Fiber:Reinforced thermoformed sheets deliver strength-to-weight ratios critical for aerospace dunnage and high-performance sporting goods. Aircraft assemblers specify these variants where load-bearing capacity must replace expanded polystyrene without mass penalties.
- Glass Fiber:Intermediate mechanical properties suit automotive interior panels requiring dimensional stability under thermal cycling.
- Aramid Fiber:Impact resistance and thermal tolerance position these formulations in protective equipment and specialized industrial dunnage.
- Synthetic Fiber:PET and polypropylene blends offer moisture resistance where pure cellulose barriers fail, though compostability claims weaken.
Volume placements concentrate in Natural Fiber; the faster expansion belongs to Carbon Fiber.
Technology:
Equipment selection hinges on draw depth requirements and production scale, with vacuum forming serving shallow-draw packaging and press systems handling complex automotive geometries.
- Vacuum Forming:Slurry deposition onto porous molds followed by suction drying yields thin-wall trays and clamshells with sub-millimeter tolerances. European dairy packers favor this method for its energy efficiency and rapid tooling changeovers between SKUs.
- Compression Molding:Matched-die pressing of pre-formed blanks enables deeper draws and tighter dimensional control for automotive interior components. Vehicle fabricators in Germany specify compression-molded door panels and headliners to replace petroleum-based substrates.
- Injection Molding:Pelletized fiber compounds feed standard plastics equipment, bridging pulp processing and polymer manufacturing infrastructure.
- Thermoforming Press:Heated platen systems with robotic transfer accommodate multi-stage forming for complex geometries in sporting goods and electronics enclosures.
Equipment deployments favor Vacuum Forming for packaging scale; Compression Molding is climbing the fastest as automotive qualification cycles complete.
Application:
Application segmentation tracks where fiber-based solutions displace incumbent materials through regulatory pressure versus technical superiority.
- Packaging Solutions:Food trays, produce containers, and protective shipping formats absorb the majority of pulp tonnage. Quick-service restaurant chains negotiate direct supply agreements specifying minimum recycled content percentages to preempt CSRD disclosure requirements.
- Automotive Interiors:Door panels, trunk liners, and headliners exploit thermoformed fiber's acoustic dampening and lightweighting potential. OEMs in Germany and the United States qualify these components to meet fleet emissions targets through mass reduction.
- Consumer Electronics:Molded pulp inserts and device enclosures serve premium unboxing experiences and protective shipping.
- Aerospace Components:Cargo dunnage and non-structural interior panels specify carbon fiber-reinforced grades where F-Gas Regulation penalties disadvantage synthetic foam competitors.
- Sporting Goods:Protective gear and equipment housings leverage aramid and carbon fiber variants for impact management.
Shipment volumes cluster in Packaging Solutions; Automotive Interiors are gaining share fastest as Tier 1 supplier capacity comes online.
End User Industry:
Procurement patterns diverge between industries with mandated sustainability disclosures and those driven purely by total cost of ownership.
- Packaging Companies:Integrated converters and independent molders serve retail and food service accounts with standardized tray formats. These firms anchor demand through multi-year supply agreements with quick-service chains in California and New York.
- Vehicle Fabricators:OEM engineering teams qualify thermoformed fiber components against stringent flammability and emissions standards, creating lengthy approval cycles but durable supplier relationships.
- Electronics Manufacturers:Premium device brands specify molded fiber for unboxing experiences and protective shipping, though cost sensitivity limits penetration in mid-market segments.
- Aircraft Assemblers:Airframers specify thermoformed fiber dunnage for weight reduction and F-Gas compliance, with qualification requirements favoring established aerospace material suppliers.
- Sports Equipment Producers:Niche manufacturers source carbon and aramid fiber composites for protective gear and high-performance equipment housings.
Contract volumes concentrate with Packaging Companies; Vehicle Fabricators show the steepest expansion trajectory as platform qualification cycles mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pulp supply from Nordic forests and recycled corrugated networks anchors converter capacity across Germany, the United States, and China. Regulatory pressure from single-use plastic bans is redirecting procurement toward cellulose-based alternatives in food service and consumer goods channels.
United States
Quick-service restaurant chains in California and New York negotiate multi-year supply agreements specifying minimum recycled content percentages. FDA food contact substance notifications govern cellulose tray acceptance in retail channels, extending approval timelines for novel barrier coatings. The Pacific Northwest and Southeast manufacturing clusters host compression molding networks serving food service accounts with standardized tray formats.
Germany
Food service operators accelerate cellulose tray specifications to preempt regulatory disadvantage under the EU F-Gas Regulation. The EU Packaging and Packaging Waste Regulation mandates recycled content minimums that thermoformed fiber satisfies through established pulp recovery streams. Bavaria and North Rhine-Westphalia concentrate converter capacity where integrated pulp-to-package operations secure fiber sourcing advantages.
China
Domestic molded fiber producers benefit from GB standards for biodegradable materials that create compliance pathways favoring local supply over imported synthetic alternatives. Yangtze River Delta manufacturing bases scale thermoforming lines to serve electronics and food export packaging demand. Shanghai and Jiangsu province clusters lead equipment automation investments that compress cycle times for high-volume production.
India
BIS certification requirements for food-grade molded products favor early movers who establish local testing partnerships and formulation adaptation. Maharashtra and Gujarat industrial corridors attract converter investments targeting quick-service restaurant supply chains. Mumbai-Pune and Ahmedabad-Vadodara clusters develop dedicated thermoforming capacity as municipal composting infrastructure expands.
Poland
Integrated pulp-to-package operations leverage proximity to Nordic fiber supply and EU market access for food tray exports. The EU Green Deal raises compliance costs for synthetic polymer competitors, redirecting procurement from German retail accounts toward Polish converter capacity. Silesia and Greater Poland voivodeships host expanding thermoforming lines serving dairy and produce packers.
Thermoformed Fiber Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty barrier coatings and carbon fiber-reinforced variants for aerospace applications. The market structures around three maturity tiers: integrated multinational converters with captive pulp supply, regional specialists serving single geography accounts, and technology-focused entrants targeting automotive and industrial dunnage segments. Capacity expansion and strategic partnerships dominate competitive moves as players secure recycled fiber feedstock agreements and qualify for extended producer responsibility scheme participation.
Among Nordic-integrated operators, Huhtamaki and Brødrene Hartmann exemplify the pulp-to-package archetype through fiber sourcing control and proprietary tooling development. Sonoco Products Company anchors North American supply scale through multi-plant compression molding networks. These three represent distinct competitive positions: Nordic integration, European vacuum-forming specialization, and North American geographic coverage density.
| Leading Market Players |
|---|
| Huhtamaki |
| Brødrene Hartmann |
| Sonoco Products Company |
| UFP Technologies |
| Pactiv Evergreen |
| Pro-Pac Packaging |
| Henry Molded Products |
| EnviroPAK |
| Sabert Corporation |
| Others |
Pricing and Supply Chain Analysis
Quick-service restaurant chains mandating minimum recycled content percentages in California and New York procurement contracts are forcing converters to secure long-term fiber supply agreements, compressing margins on spot-market purchases while rewarding backward-integrated operators with captive pulp supply.
Pricing Analysis
Service bundling separates tooling ownership from per-unit tray pricing, with multi-year agreements covering mold maintenance and barrier coating qualification support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—FDA food contact notification status commands measurable premiums over BIS-equivalent grades. Cost compression in natural fiber formulations is intensifying because Chinese OCC import policy swings expose converters to feedstock volatility. Food service operators show highest price sensitivity, while aerospace dunnage buyers prioritize strength-to-weight performance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale quick-service restaurant demand through dedicated thermoforming lines, while packaging wholesalers serve fragmented produce packer accounts. Raw material supply concentrates in Finland, Poland, and the United States where integrated pulp-to-package operations secure Nordic fiber and domestic OCC streams. Converter operations draw from slurry chemicals, vacuum-forming molds, and barrier coating formulations as critical inputs. Single-source vulnerability runs through specialized vacuum-forming tooling engineers concentrated in legacy paperboard regions. Distribution runs through converter-direct relationships displacing traditional wholesale channels in high-volume food service segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive fiber supply and proprietary mold design capabilities determine margin capture, with players pursuing upstream pulp sourcing control as the decisive lever.
For Market Incumbents: Acquire vacuum-forming tooling engineering capabilities to defend against emerging Asian equipment suppliers offering automated thermoforming lines at compressed price points. Secure long-term OCC supply agreements with municipal recovery facilities to insulate margins from Chinese import policy volatility. Expand compression molding capacity in Germany and the United States to capture accelerating automotive interior qualification cycles before Tier 1 suppliers consolidate preferred supplier lists. For New Entrants and Emerging Players: Regional quick-service restaurant chains outside California and New York represent underserved buyer archetypes seeking cellulose tray supply without minimum volume commitments that exclude mid-market operators. India's BIS certification pathway offers the most penetrable regulatory entry point for converters establishing local testing partnerships. Pursue direct procurement relationships with municipal composting operators to secure end-of-life infrastructure guarantees that differentiate offerings against imported synthetic alternatives. For Investors and Strategic Acquirers: The window for entry favors integrated pulp-to-package operators with demonstrated FDA notification success and captive fiber supply in Nordic or North American basins. Long-term viability hinges on exposure to extended producer responsibility scheme participation revenue streams in France and Italy. Watch carbon fiber-reinforced variant qualification cycles at major airframers as the inflection signal for aerospace dunnage segment maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive OCC and agricultural residue sourcing insulates converters from Chinese import policy volatility. |
| Barrier Coating R&D Partnership | Collaboration with PLA and water-based coating specialists addresses high-moisture food performance gaps. |
| Automotive Interior Qualification | Tier 1 supplier approval for compression-molded door panels opens OEM platform standardization opportunities. |
| Extended Producer Responsibility Enrollment | France and Italy EPR framework participation creates compliance service revenue for integrated operators. |
| Continuous Thermoforming Line Deployment | Inline drying and robotic transfer systems compress cycle times for European dairy and produce packer accounts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with thermoforming line operators, pulp procurement managers, quick-service restaurant sustainability directors, and automotive Tier 1 supplier engineers. FDA food contact substance notifications, EU ECHA substance registrations, Chinese GB standard compliance databases, and Indian BIS certification records provided regulatory validation. Bottom-up capacity assessments at converter facilities across Germany, the United States, and China reconciled against top-down pulp consumption estimates from Nordic forestry and OCC recovery trade associations.
Data-stream reconciliation merged equipment installation records from European dairy packers with automotive interior component qualification timelines at German OEMs. Segmentation modeling spanned fiber type, forming technology, application category, and end-user industry across the projection horizon. CAGRs derived from weighted average of historical capacity expansion rates and forward-looking procurement commitment disclosures. Forecast inputs incorporated EU Packaging and Packaging Waste Regulation implementation schedules and California single-use plastic ban enforcement phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to barrier coating breakthrough timelines and Chinese OCC import policy trajectories. Base assumptions reflect sustained regulatory pressure on synthetic polymer competitors and stable natural gas pricing for drying energy inputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.