
 Fiberglass Mat Market | 2026-2036
Fiberglass Mat Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Mat Market Analytics
Market Context
The EU Green Deal is repositioning specification priorities across European construction and wind energy supply chains, favoring lightweight reinforcement materials with lower embodied carbon. Owens Corning leverages its integrated glass-melting and mat-forming operations to secure cost advantages in North American wind blade supply. China Jushi Co. Ltd. anchors global supply through massive furnace capacity at its Jingjiang and Jiujiang complexes. Johns Manville sustains technical leadership in specialty surface mats for corrosion-resistant applications.
Technical Definition and Segments
Fiberglass mat consists of randomly oriented glass fibers bonded with powder or emulsion binders into nonwoven sheets, typically weighing 150–900 g/m², serving as reinforcement in polymer matrix composites. Chopped strand mat dominates volume due to its compatibility with hand lay-up and spray-up processes in boat hulls and building panels, though continuous filament mat commands premium positioning in automated wind blade manufacturing where fiber alignment controls mechanical performance. Surface mat generates concentrated margins from chemical storage tank and pipe applications requiring corrosion barriers, while woven roving competes in structural laminates demanding higher strength-to-weight ratios.
Regulatory Frame and Outlook
REACH regulates binder chemistry and styrene emissions in European composite manufacturing, while the EPA enforces National Emission Standards for Hazardous Air Pollutants at US fiberglass production facilities. China's GB standards and MEE enforcement on industrial emissions shape local plant upgrades and product certification requirements. Stakeholders must monitor evolving carbon border adjustments and renewable content mandates that will redefine competitive access across major demand centers.
Market Dynamics
The EU Green Deal's embodied carbon disclosure requirements are redirecting specification decisions across construction and wind energy supply chains, compressing demand toward lower-carbon reinforcement materials and rewarding producers with integrated furnace-to-mat operations.
Growth Catalysts
- China's state infrastructure programs:Massive wind farm buildouts and state-backed construction initiatives consume substantial chopped strand mat volumes, anchoring regional demand expansion.
- REACH binder chemistry standards:European regulatory pressure on styrene emissions and binder formulations is accelerating plant upgrades that favor modern emulsion-based mat production.
- Lightweight substitution in marine:Boat builders are replacing heavier woven roving with continuous filament mat to reduce hull weight and improve fuel efficiency.
Market Restraints
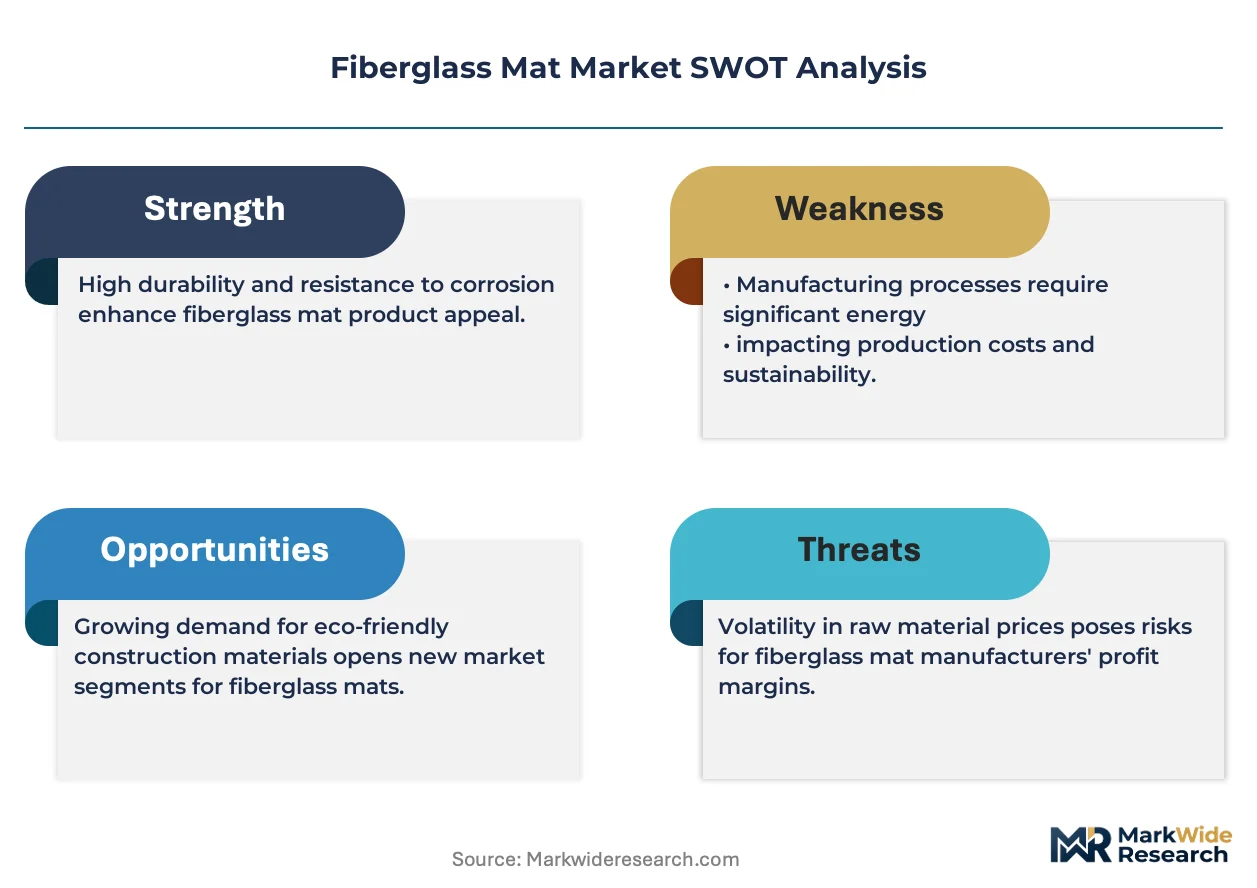
- Borosilicate glass cost volatility:Energy-intensive melting operations face input cost pressure from natural gas and electricity price swings, compressing margin stability for non-integrated producers.
- Furnace concentration in eastern China:Jingjiang and Jiujiang industrial clusters control disproportionate global melting capacity, creating geographic supply risk during regional power rationing or environmental enforcement waves.
- Carbon fiber substitution threat:Wind blade manufacturers above 80-meter lengths are evaluating carbon fiber spar caps for stiffness-critical sections, displacing fiberglass mat in high-performance blade architectures.
Strategic Opportunities
- India's PLI scheme for composites:Production-linked incentives for advanced materials manufacturing are attracting furnace investments to serve domestic wind and construction demand.
- Recycled content mandates:The EU's evolving circular economy requirements for construction products create first-mover advantage for mat producers developing post-consumer glass fiber recovery processes.
- Digital distribution platforms:Specialized B2B marketplaces for industrial textiles are disintermediating traditional distributor networks in European specialty mat procurement.
Industry Challenges
- Skilled furnace operator scarcity:Glass melting requires specialized temperature control expertise that aging workforces in North America and Europe cannot readily replace.
- GB standard certification timelines:China's product conformity assessment procedures for construction-grade mats extend market entry cycles for new foreign suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Mat Market |
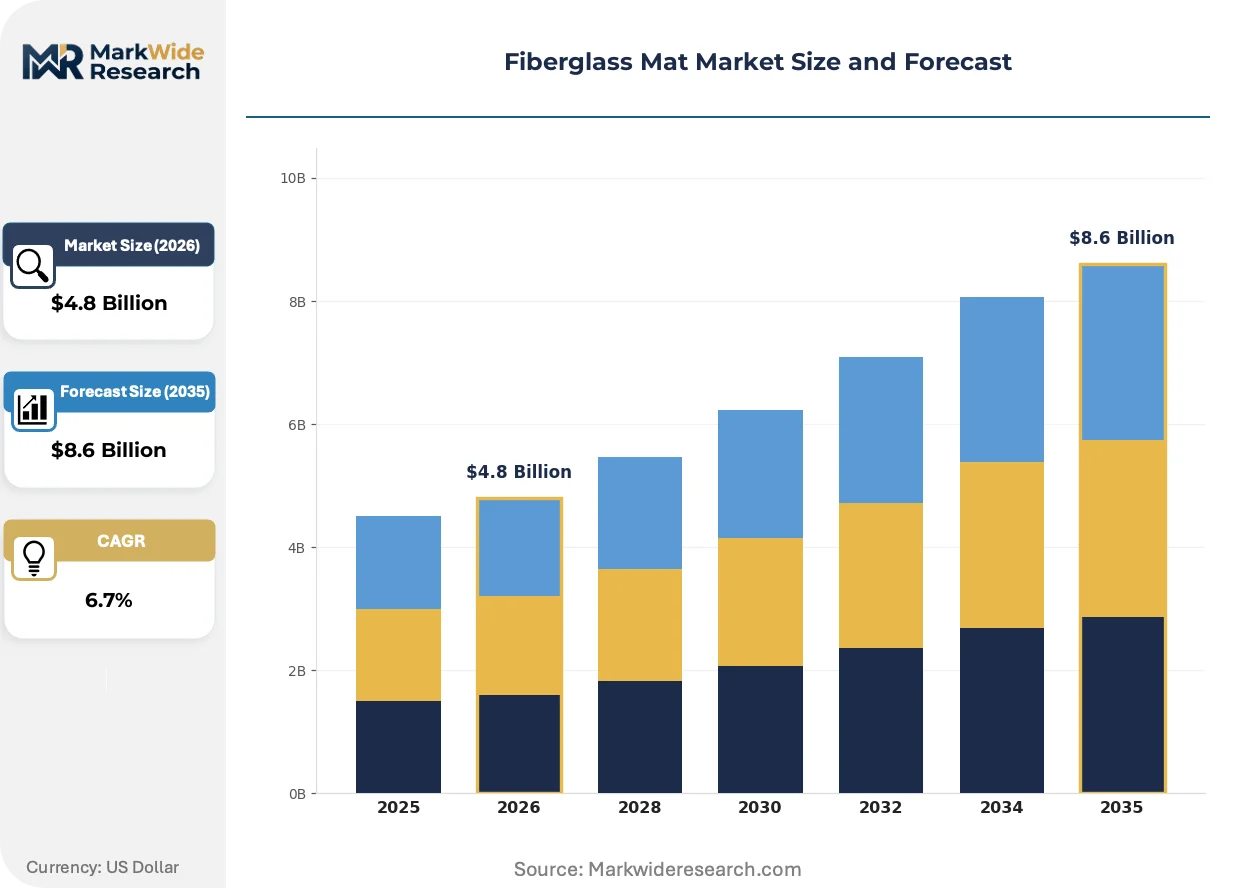
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chopped Strand Mat, Woven Roving, Continuous Filament Mat, Surface Mat Application: Automotive Components, Marine Applications, Construction, Electrical Insulation End User: Aerospace, Consumer Goods, Building & Construction, Wind Energy Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Johns Manville, 3M Co., Owens Corning, Nitto Boseki Co. Ltd., Nippon Electric Glass Co. Ltd., China Jushi Co. Ltd., Taishan Fiberglass Inc., BASF SE, Compagnie de Saint Gobain SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Mat Market Evolving Landscape
Digital process control and sustainable binder chemistry are converging to reduce energy intensity and emissions profiles across mat production, while procurement patterns favor suppliers with verified lifecycle carbon data.
Continuous filament mat technology is consolidating position in automated wind blade manufacturing. Vestas and Siemens Gamesa specification engineers specify this format for spar cap and shear web laminates where fiber alignment controls mechanical performance. The technology is consolidating supply relationships around producers with in-house direct-melt capabilities.
REACH Annex XVII restrictions on formaldehyde-releasing binders are forcing European mat producers to reformulate emulsion chemistries. Industrial laminate manufacturers in Germany and the Netherlands face compliance deadlines that favor suppliers with certified low-emission product lines. Surface mat segments for chemical storage applications are absorbing the highest compliance costs.
Specification decisions now hinge on Environmental Product Declarations with third-party verified embodied carbon figures. Wind farm developers in Denmark and the Netherlands are unbundling material procurement from blade fabrication contracts to direct-source lower-carbon reinforcement. This pattern is compressing traditional integrated blade maker margins while rewarding standalone mat producers with transparent supply chains.
Fiberglass Mat Market Segmentation
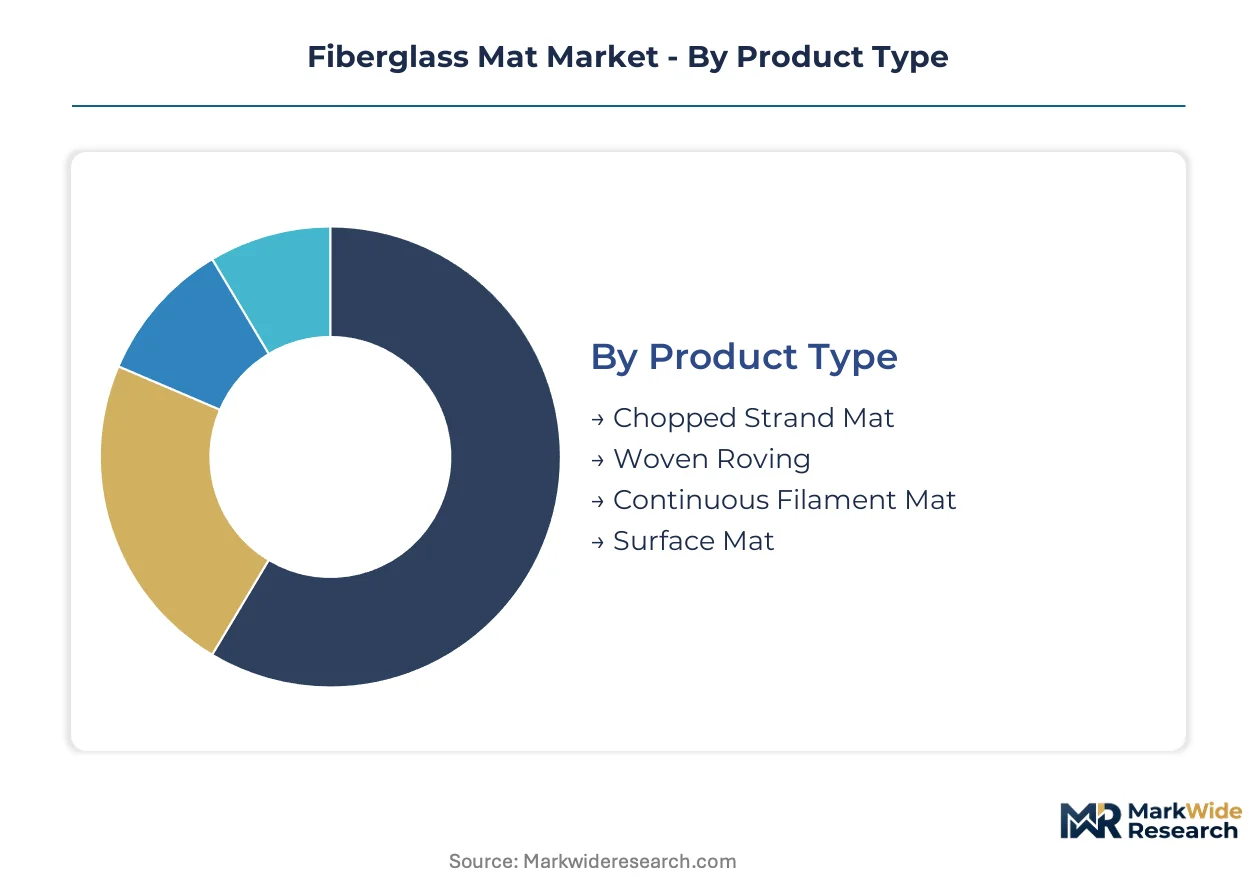
Segmentation in fiberglass mat markets determines specification pathways, as chopped strand mat serves hand-layup boat builders while continuous filament mat feeds automated wind blade lines. Certification requirements and end-use performance standards fragment procurement across construction, marine, and renewable energy supply chains.
Product Type:
REACH compliance on binder chemistry and GB standard certification for construction-grade reinforcement create divergent approval burdens across mat formats, with surface mat facing the strictest chemical resistance testing regimes.
- Chopped Strand Mat:Randomly oriented glass fiber strands held by powder or emulsion binders, compatible with manual lay-up and spray-up processes. Demand concentrates in China's state-backed construction programs and marine hull fabrication, driven by cost efficiency in labor-intensive manufacturing environments.
- Continuous Filament Mat:Unidirectional or multidirectional continuous fibers produced via direct-melt processes, engineered for automated tape laying and resin infusion. Vestas and Siemens Gamesa specify this format for wind blade spar caps and shear webs where fiber alignment governs mechanical performance.
- Woven Roving:Bidirectional fabric woven from continuous roving strands, delivering higher strength-to-weight ratios in structural laminates. Boat builders in the Netherlands and Germany specify woven roving for hull reinforcements requiring directional load bearing.
- Surface Mat:Fine-diameter fibers forming thin surfacing veils, functioning as corrosion barriers and cosmetic finish layers. Chemical storage tank manufacturers absorb premium pricing for certified surface mat meeting ECHA corrosion resistance standards.
Chopped strand mat sits at the top of the volume ranking, with continuous filament mat climbing the fastest.
Application:
Cost tiers separate specification decisions, as automotive component procurement prioritizes lightweight substitution economics while electrical insulation demands dielectric certification premiums.
- Construction:Reinforcement for building panels, roofing membranes, and infrastructure composites requiring fire resistance ratings. The EU Green Deal's embodied carbon disclosure rules redirect European specification toward lower-carbon mat options with verified Environmental Product Declarations.
- Marine Applications:Boat hulls, decks, and superstructures utilizing mat for osmotic blister prevention and impact resistance. Fuel efficiency regulations from the IMO drive substitution of woven roving with lighter continuous filament mat in yacht and commercial vessel production.
- Automotive Components:Underbody shields, battery enclosures, and structural reinforcements in electric vehicle platforms. OEMs in Germany and South Korea specify thermoplastic-compatible mat formats for compression molding cycle time reduction.
- Electrical Insulation:Transformer boards, motor slot liners, and printed circuit substrate cores demanding dielectric strength certification. BIS and IEC standards govern insulation-grade mat procurement in India's power infrastructure expansion.
Construction commands the largest application share, with marine applications gaining share fastest on lightweight substitution momentum.
End User:
Customer type determines volume contracting structures, with wind energy developers unbundling material procurement from blade fabrication while building contractors rely on distributor intermediation.
- Wind Energy:Blade manufacturers and wind farm developers sourcing mat for spar caps, root reinforcements, and nacelle components. Danish and Dutch developers now direct-source lower-carbon reinforcement, compressing traditional integrated blade maker margins.
- Building & Construction:General contractors, panel fabricators, and infrastructure specialists procuring mat for roofing, cladding, and structural composites. China's state infrastructure programs anchor regional demand through centralized procurement of construction-grade chopped strand mat.
- Aerospace:Secondary structure manufacturers and interior component suppliers utilizing specialty mat for flame-retardant applications. FAA and EASA certification requirements limit supplier qualification to producers with aerospace-grade quality systems.
- Consumer Goods:Sporting equipment, furniture, and appliance manufacturers incorporating mat for aesthetic surfacing and structural ribs. Premium pricing applies to low-emission mat formats meeting formaldehyde-restricted furniture standards in California and the EU.
Building and construction dominates end-user procurement volumes, with wind energy expanding most quickly on turbine capacity additions.
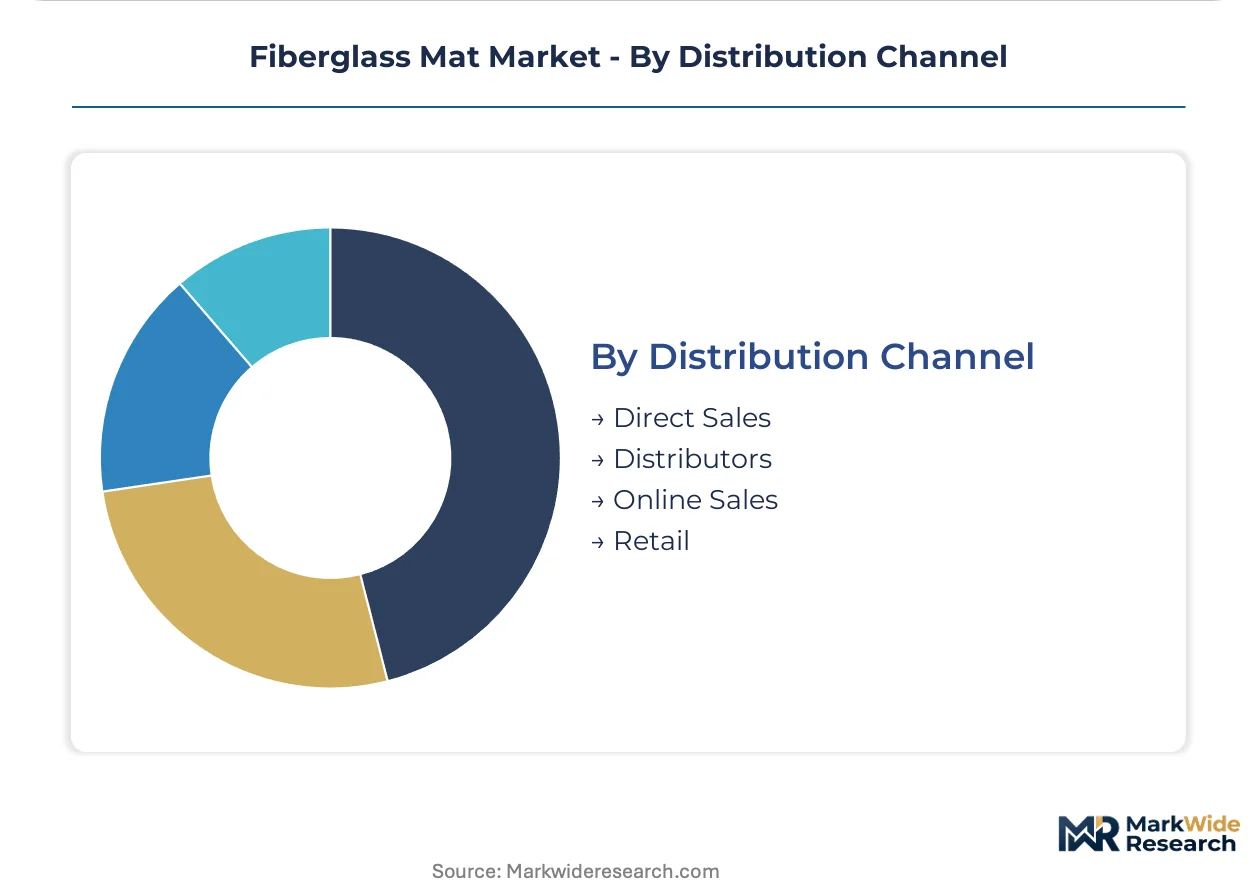
Distribution Channel:
Supply concentration shapes channel selection, as furnace-integrated producers leverage direct sales for wind energy accounts while specialty mat flows through technical distributors.
- Direct Sales:Volume contracts between mat producers and wind blade manufacturers, automotive Tier 1s, and construction panel fabricators. Owens Corning and China Jushi anchor direct relationships through captive glass-melting and mat-forming integration.
- Distributors:Technical wholesalers stocking chopped strand mat and woven roving for marine repair shops, small fabricators, and regional construction suppliers. European specialty mat procurement is disintermediating through digital B2B platforms.
- Online Sales:E-commerce portals serving prototype builders, research institutions, and small-batch composite shops. Limited to standard formats with published technical data sheets and rapid fulfillment requirements.
- Retail:Hardware and marine supply stores carrying small-quantity mat for DIY boat repair and hobbyist applications. Margins compress on retail-format packaging and inventory carrying costs.
Direct sales captures the highest volume flows, with distributor channels steepest expansion trajectory on digital platform penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass fiber mat production traces its industrial lineage to 1930s Ohio, where Owens Corning pioneered continuous filament drawing for insulation and reinforcement applications. That technical foundation seeded furnace-to-mat integration models now replicated across three continents. Contemporary demand patterns reflect this geographic diffusion of melting and forming expertise.
United States
Wind blade fabrication in Iowa and Colorado consumes substantial continuous filament mat volumes for spar cap laminates. EPA National Emission Standards for Hazardous Air Pollutants govern binder chemistry and furnace emissions at Texas and South Carolina production facilities. Toledo, Ohio retains technical leadership in specialty surface mat development for corrosion-resistant chemical storage applications.
Germany
Automotive OEMs in Bavaria specify thermoplastic-compatible mat formats for electric vehicle battery enclosure compression molding. REACH Annex XVII restrictions on formaldehyde-releasing binders force emulsion reformulation across Baden-Württemberg mat forming operations. The Ruhr industrial cluster concentrates glass melting capacity serving construction panel and wind energy supply chains.
China
State-backed infrastructure programs and offshore wind farm buildouts in Jiangsu and Guangdong absorb massive chopped strand mat volumes. GB standards and MEE enforcement on industrial emissions shape furnace upgrades at Jingjiang and Jiujiang complexes. The Yangtze River Delta anchors global melting capacity, though regional power rationing periodically disrupts supply continuity.
India
Wind energy developers in Gujarat and Tamil Nadu source mat for domestic blade fabrication under PLI scheme incentives for advanced materials manufacturing. BIS certification requirements for construction-grade reinforcement extend market entry timelines for foreign suppliers. The Maharashtra industrial corridor attracts furnace investments targeting regional construction and renewable energy demand.
Netherlands
Wind farm developers in Rotterdam and Eemshaven direct-source lower-carbon reinforcement with verified Environmental Product Declarations, bypassing traditional blade maker intermediation. EU Green Deal embodied carbon disclosure rules redirect specification toward furnace-integrated mat producers. The Randstad logistics hub enables just-in-time distribution to North Sea offshore wind construction ports.
Fiberglass Mat Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology pathways. Integrated glass-melting and mat-forming operations command cost advantages in volume wind energy contracts, while specialized surface mat fabricators sustain margin premiums in corrosion-resistant chemical applications. Three archetypes dominate: furnace-integrated multinationals with captive raw material supply, regional specialists concentrating on certified construction grades, and diversified chemical conglomerates leveraging binder chemistry expertise. Competitive dynamics center on backward integration into borosilicate glass production and geographic expansion to serve localized wind energy supply chains.
Within the furnace-integrated tier, Owens Corning and China Jushi Co. Ltd. exemplify scale-driven positioning through captive melting capacity. Johns Manville occupies a specialist position in surface mat segments requiring ECHA corrosion resistance certification. Among diversified materials conglomerates, Compagnie de Saint Gobain SA represents the chemical and construction cross-sector archetype with integrated glass operations spanning multiple reinforcement formats.
| Leading Market Players |
|---|
| Johns Manville |
| 3M Co. |
| Owens Corning |
| Nitto Boseki Co. Ltd. |
| Nippon Electric Glass Co. Ltd. |
| China Jushi Co. Ltd. |
| Taishan Fiberglass Inc. |
| BASF SE |
| Compagnie de Saint Gobain SA |
| Others |
Value Network & Pricing Analysis
Wind blade manufacturers in Denmark and the Netherlands concentrate procurement authority through direct-sourcing contracts, compressing margins for non-integrated mat producers while rewarding furnace-integrated suppliers with transparent carbon accounting. This buyer consolidation anchors a contract-based long-term offtake model where volume commitments lock in pricing stability against raw material volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified low-emission surface mat for chemical storage from commodity chopped strand mat and generic woven roving. Price differentiation hinges on GB standard certification grade and volume scale, with construction-grade mat facing the steepest cost compression from China's state-procurement price ceilings. Price erosion runs through the economy tier as eastern Chinese furnace overcapacity floods regional spot markets. Wind energy developers exhibit the lowest price sensitivity, prioritizing fiber alignment consistency and embodied carbon verification over per-kilogram economics.
Supply Chain Analysis
Single-source vulnerability sits with China's Yangtze River Delta industrial clusters, where Jingjiang and Jiujiang furnace complexes control disproportionate global borosilicate glass melting capacity. Raw material dependencies draw from soda ash, boron compounds, and natural gas feedstocks sourced through concentrated petrochemical corridors. Tariff exposure on US-bound mat shipments compounds geographic concentration risk as carbon border adjustments reshape European import economics. Distribution runs through direct sales channels for wind energy accounts, while technical distributors intermediate specialty surface mat flows to chemical tank fabricators and marine repair shops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between China's furnace-dominant cost base and Europe's regulatory-premium pricing environment, where EU Green Deal carbon disclosure requirements widen margin spreads for low-emission producers.
For Market Incumbents: Cement backward integration into borosilicate glass production to defend margin position against carbon fiber substitution threats in wind blade spar caps. Expand furnace capacity in India under PLI scheme incentives to serve localized renewable energy demand without China's power-rationing exposure. Prioritize REACH-compliant emulsion binder certification to capture European chemical storage tank specification shifts.
For New Entrants and Emerging Players: Sustainable binder chemistry platforms offer a technology-first wedge into European surface mat segments facing formaldehyde-restriction compliance deadlines. Target India's Maharashtra industrial corridor for greenfield furnace investments serving domestic wind energy buildouts. Pursue digital B2B marketplace partnerships to disintermediate traditional distributor networks in specialty mat procurement.
For Investors and Strategic Acquirers: Diversified chemical conglomerates with binder chemistry expertise are the most active acquirer in this space, consolidating fragmented regional specialists. Five-to-ten-year viability hinges on furnace-to-mat integration depth and geographic diversification beyond eastern China. Watch for carbon border adjustment implementation timing as the inflection signal separating premium-tier from commodity-grade producer valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Melting | Captive borosilicate supply insulates Owens Corning and China Jushi from natural gas price volatility. |
| REACH-Compliant Binder Reformulation | Low-emission emulsion chemistry secures German chemical tank manufacturer specification lock-in. |
| India PLI Scheme Capacity Expansion | Maharashtra furnace investments serve Gujarat wind developers under domestic content incentives. |
| Environmental Product Declaration Certification | Third-party verified carbon data unlocks direct procurement from Dutch offshore wind farm developers. |
| Digital B2B Platform Partnership | Specialized marketplaces disintermediate European technical distributor networks in surface mat procurement. |
Research Methodology
Multiple input streams — primary interviews with furnace operations managers, wind blade procurement leads, and chemical tank fabricator technical directors; secondary validation through customs trade data, GB standard certification records, and SEC filings from listed glass fiber producers; plus patent filing analysis — were reconciled through bottom-up and top-down triangulation. Plant managers at Jingjiang and Jiujiang complexes provided capacity utilization perspectives, while downstream OEM procurement teams disclosed specification shift timelines. Trade databases tracked mat format-specific import flows, and ECHA regulatory filings documented binder chemistry compliance trajectories.
Historical volume trajectories were cross-referenced against expert panel assessments of wind energy capacity additions and construction sector substitution rates across the analysis window. Segmentation modeling incorporated product type, application end-use, and geographic production hub dimensions. CAGRs were derived from slope analysis of reconciled demand curves, with sensitivity testing around China's infrastructure program funding cycles and EU carbon border adjustment implementation pace. Borosilicate glass input cost indices and REACH compliance cost estimates fed industry-specific forecast adjustments.
The model holds under stable Chinese state infrastructure spending and gradual EU regulatory phase-in; deviation in abrupt power-rationing waves or accelerated carbon border enforcement would shift volume and value trajectories. Forecasts reflect documented assumptions about furnace technology migration timelines and binder chemistry reformulation costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Carbon Fiber Filament Market
Fibers
Aramid Fiber Reinforcement Materials Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Fiber Intermediates Market
Fibers
Fiberglass Resin Market
Fibers
Metal Fiber Felt Market
Fibers
Bioglass Fiber Market
Fibers
E-Glass Fiber Market
Fibers
Renewable Carbon Fibers Market
Fibers
Global Concrete Fiber Market
Fibers
High Performance Fibers for Defense Market
Fibers
Global Nylon Monofilament Market
Fibers
Global Basalt Fiber Market
Fibers
Citrus Pulp Fiber Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Asia-Pacific Carbon Fiber Market