
 North America Glass Fiber Reinforced Gypsum Market | 2026-2036
North America Glass Fiber Reinforced Gypsum Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glass Fiber Reinforced Gypsum Market Intelligence
The availability of specialized architectural artisans for custom molding installation is bifurcating the market from installers of standardized panel systems. Stromberg Architectural specializes in complex, custom decorative moldings for high-end commercial projects across the United States. In contrast, USG Corporation leverages its extensive distribution network to supply standard ceiling tiles and wall panels for volume applications. Formglas Products Ltd. also competes in the high-specification segment, focusing on intricate architectural forms for institutional and hospitality clients.
Glass Fiber Reinforced Gypsum is a composite material made from high-density alpha gypsum reinforced with continuous filament glass fibers. Its non-combustible nature, low weight, and ability to be molded into complex shapes make it ideal for creating non-load-bearing interior architectural elements. While the commercial end-user segment represents the largest share due to large-scale projects, the residential sector shows strong growth in high-end renovation projects. In terms of product type, decorative moldings offer higher margins for custom work, whereas ceiling tiles and wall panels drive consistent volume.
ASTM International standards, specifically ASTM C1355/C1355M, govern the specification, manufacture, and testing of GFRG composites in North America. Adherence to these standards, alongside local building codes enforced by municipal authorities in cities like Toronto and Houston, is mandatory for fire resistance and structural integrity in public and commercial buildings. Manufacturers must now navigate the growing pressure from architects and developers for greater material circularity and lower embodied carbon in all building materials.
Market Dynamics
The North American GFRG market is defined by a central tension between the demand for standardized, volume-driven panel systems and the high-margin, craft-intensive segment of custom architectural moldings. This bifurcation influences supply chain structures, skill requirements, and competitive positioning for all participants.
Growth Catalysts
- Fire Safety Regulations:Stricter building codes, including those from the National Fire Protection Association (NFPA) in the US, mandate the use of non-combustible materials in commercial and public assembly buildings, directly benefiting GFRG.
- Aesthetic Architectural Demand:The hospitality and institutional sectors are specifying GFRG for complex, custom interior elements to create unique brand aesthetics and improve acoustic performance in large spaces.
- Regional Construction Activity:Concentrated commercial and public infrastructure project pipelines in high-growth corridors, such as the Southern United States and Ontario, Canada, provide a steady stream of large-scale opportunities.
Market Restraints
- Material Cost:The price of high-density alpha gypsum, a primary raw material, is higher than that of standard gypsum, impacting the overall cost-competitiveness of GFRG against more conventional interior finishing materials.
- Substitution from Alternatives:GFRG faces competition from materials like Glass Fiber Reinforced Concrete (GFRC) for certain applications, as well as traditional plaster and modern polymer composites that can achieve similar decorative effects.
- Technical Application Limits:The material's non-load-bearing characteristic restricts its use to decorative and non-structural applications, precluding its use in elements that require structural support and limiting its market scope.
Strategic Opportunities
- Retrofit and Renovation Projects:A significant opportunity exists in retrofitting existing commercial buildings to meet updated fire codes and acoustic standards, particularly in aging urban cores across North America.
- Expansion into Mexico:Mexico's expanding commercial and high-end hospitality construction sectors represent a largely underpenetrated market for specialized GFRG products beyond basic panels.
- Digital Fabrication Integration:Pairing GFRG manufacturing with digital design tools and 3D printing for mold creation can drastically reduce lead times and costs for complex, custom geometries, opening new design possibilities.
Industry Challenges
- Artisan Skill Scarcity:A shortage of skilled artisans trained in the specific techniques for installing complex, custom-molded GFRG shapes creates installation bottlenecks and drives up labor costs for high-end projects.
- Logistical Complexity:The transportation and handling of large, often fragile, and uniquely shaped GFRG components require specialized logistics, adding cost and risk of damage compared to standardized building materials.
- Code Compliance Variation:Manufacturers and installers must navigate a complex web of differing municipal building codes in cities like Toronto and Houston on top of baseline ASTM standards, complicating projects that span multiple jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glass Fiber Reinforced Gypsum Market |
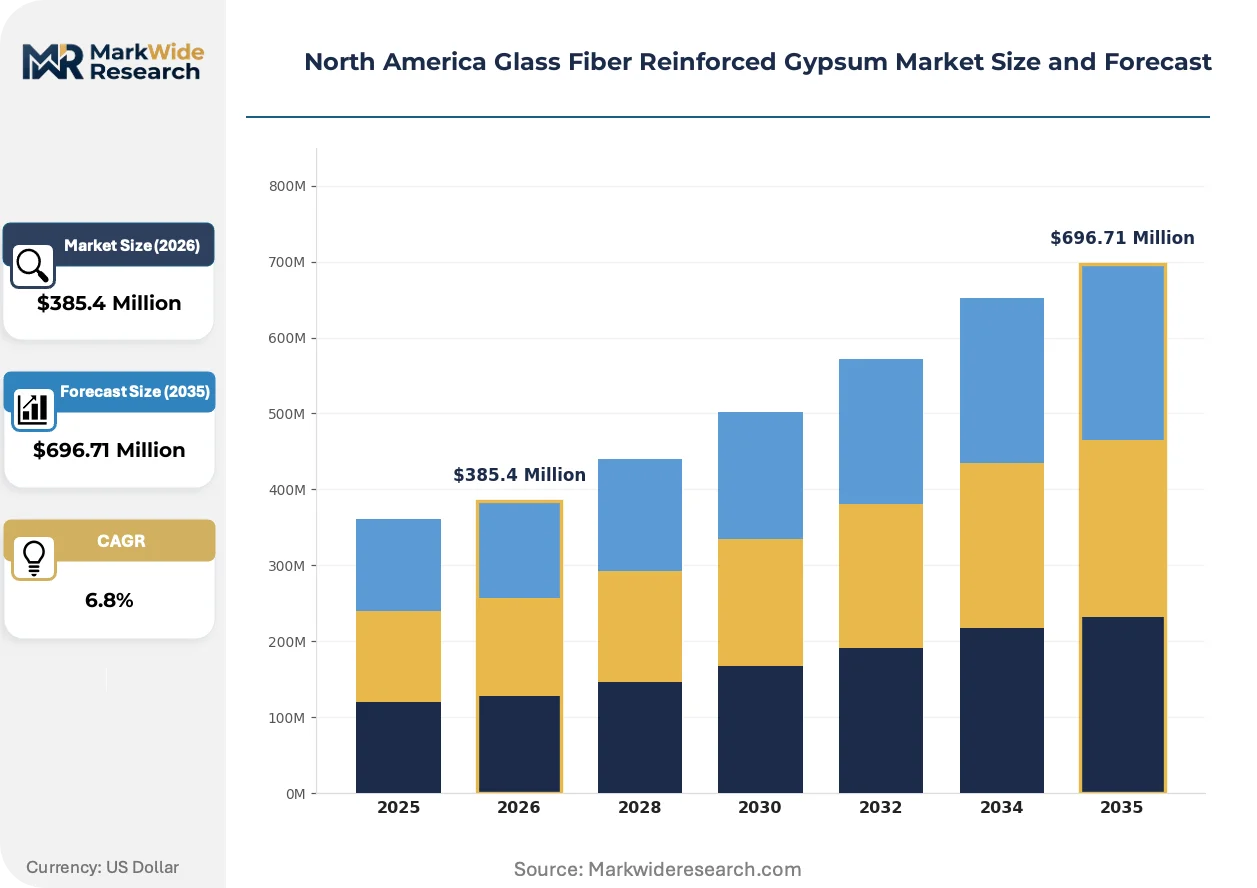
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceiling Tiles, Wall Panels, Decorative Moldings, Partition Systems End User: Residential, Commercial, Industrial, Educational Institutions Application: Interior Design, Acoustic Treatment, Fire Resistance, Aesthetic Finishing Installation Type: Drywall System, Direct Installation, Suspended Installation, Renovation Projects |
| Companies Covered | Owens Corning, Stromberg Architectural, USG Corporation, National Gypsum, American Gypsum, Georgia-Pacific, Formglas Products Ltd, Saint-Gobain, CertainTeed, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glass Fiber Reinforced Gypsum Market Strategic Shifts & Innovations
Digital fabrication methods and a growing emphasis on material sustainability are reshaping how Glass Fiber Reinforced Gypsum components are designed, specified, and manufactured. These forces are pushing the industry beyond traditional craft-based processes toward more integrated, data-driven production workflows.
Digital Fabrication for Custom Molds
Advanced digital fabrication is now used to create the complex molds for custom GFRG pieces. Architects and specialized fabricators are adopting CNC milling and large-format 3D printing to produce molds directly from design files with high precision. This technology is fragmenting the market for mold-making, as it lowers the barrier to entry for producing intricate designs that were once the exclusive domain of master craftsmen.
Sustainability and Embodied Carbon
Heightened focus on sustainable building practices, driven by standards like LEED certification in the United States and Canada, is increasing scrutiny on the embodied carbon of all materials. This development pressures GFRG manufacturers to improve transparency in their supply chains and document the lifecycle impacts of their products. Panel and tile producers are particularly affected, leading them to explore greater use of recycled gypsum and alternative, lower-impact binders.
Shift Toward Programmatic Procurement
A clear behavioral shift is occurring as large-scale developers move away from single-project bidding toward establishing programmatic, long-term supply agreements for GFRG products. This change disrupts the traditional, transactional sales model and favors larger manufacturers who can guarantee supply and consistent quality across multiple projects. This pattern is most visible in the context of phased, multi-year commercial and institutional campus developments in major North American metropolitan areas.
North America Glass Fiber Reinforced Gypsum Market Segmentation
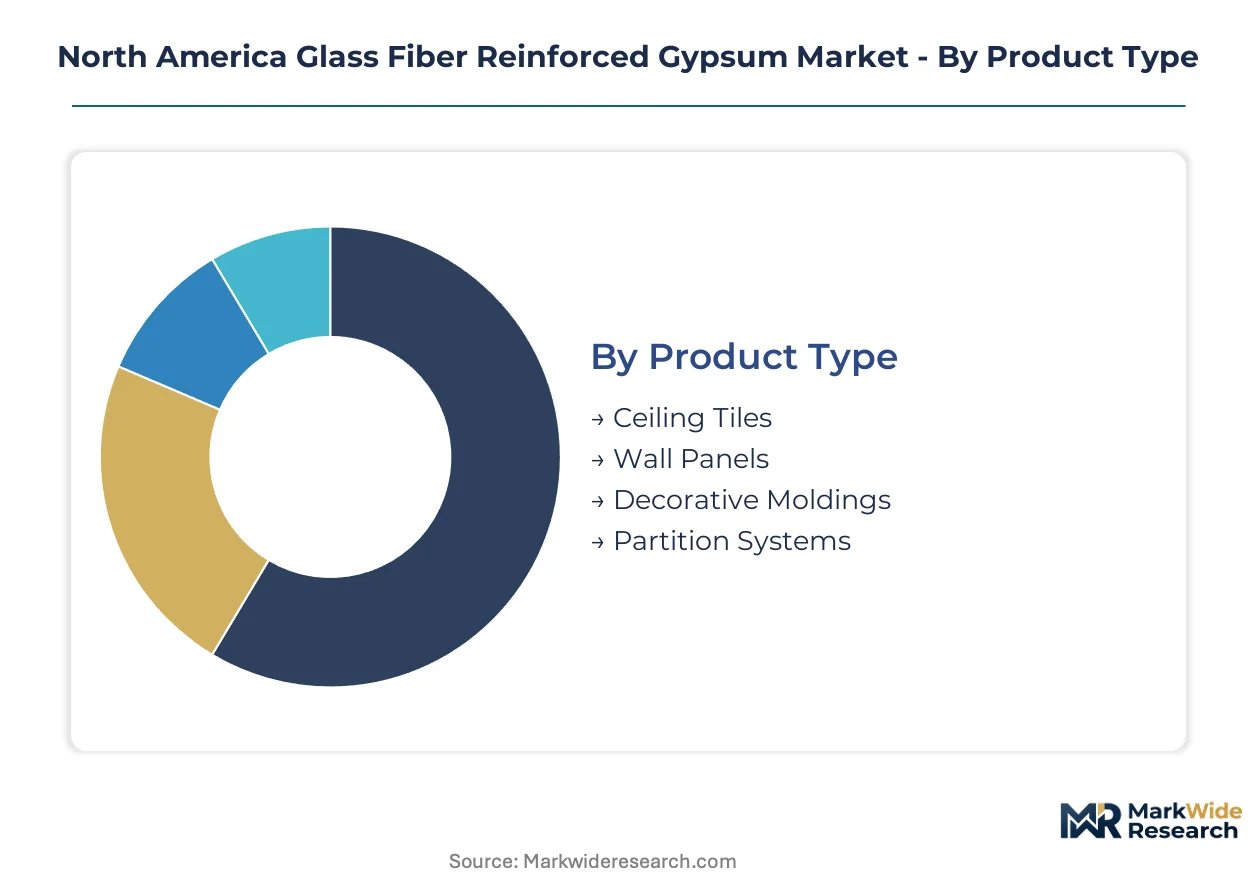
The segmentation of the North America Glass Fiber Reinforced Gypsum (GFRG) market provides a granular view of demand drivers, material specifications, and competitive dynamics. Understanding these distinct segments is crucial for manufacturers to tailor product offerings and for stakeholders to identify specific growth opportunities within the region.
Product Type:
North American building codes and safety standards significantly influence the product types specified for GFRG applications.
- Ceiling Tiles:Ceiling tiles are standardized GFRG panels, typically square or rectangular, designed for suspended ceiling grid systems. These panels see consistent volume demand in commercial construction due to their ease of installation and inherent fire resistance properties.
- Wall Panels:Wall panels are large, flat GFRG sheets used for interior wall surfacing and cladding in various commercial settings.
- Decorative Moldings:Decorative moldings are custom-fabricated GFRG elements, often featuring intricate patterns, cornices, and column covers. Demand concentrates in high-end commercial projects, particularly where unique brand aesthetics are required in the United States.
- Partition Systems:Partition systems involve non-load-bearing GFRG components used to create interior room dividers and acoustic barriers.
Established volume favors Ceiling Tiles; emerging adoption favors Decorative Moldings.
End User:
The diverse requirements of various end-user segments shape demand patterns for GFRG products across North America.
- Residential:The residential sector encompasses single-family homes and multi-unit dwellings, primarily for high-end interior renovations. This segment shows strong growth, particularly in custom architectural elements for luxury properties across North America.
- Commercial:The commercial sector includes offices, retail spaces, and large public venues utilizing GFRG for interior finishes. This segment represents the largest share of GFRG consumption, driven by extensive project pipelines in the Southern United States and Ontario, Canada.
- Industrial:Industrial end-users deploy GFRG for specific applications requiring fire resistance and durability in non-production areas.
- Educational Institutions:Educational institutions utilize GFRG for aesthetic and acoustic improvements in auditoriums, libraries, and common areas.
The commercial sector drives the largest volume, while high-end residential renovation projects represent the fastest-growing trajectory.
Application:
The specific functional and decorative applications of GFRG drive varying margin profiles and material specifications.
- Interior Design:Interior design applications focus on GFRG's aesthetic versatility, allowing architects to create bespoke architectural features.
- Acoustic Treatment:Acoustic treatment utilizes GFRG's ability to absorb or diffuse sound, improving sound quality in interior spaces. Hospitality and institutional sectors specify GFRG for enhancing acoustic performance in large lobbies and conference halls.
- Fire Resistance:Fire resistance applications leverage GFRG's non-combustible properties to meet stringent building codes. Stricter regulations from the NFPA in the US and provincial codes in Canada compel GFRG use in public assembly buildings.
- Aesthetic Finishing:Aesthetic finishing involves using GFRG for decorative surfaces, cornices, and other visual enhancements in commercial projects.
Fire resistance remains a primary driver for GFRG adoption, while acoustic performance gains importance in public spaces.
Installation Type:
Installation methods for GFRG are dictated by project scale, structural conditions, and client-specific aesthetic requirements.
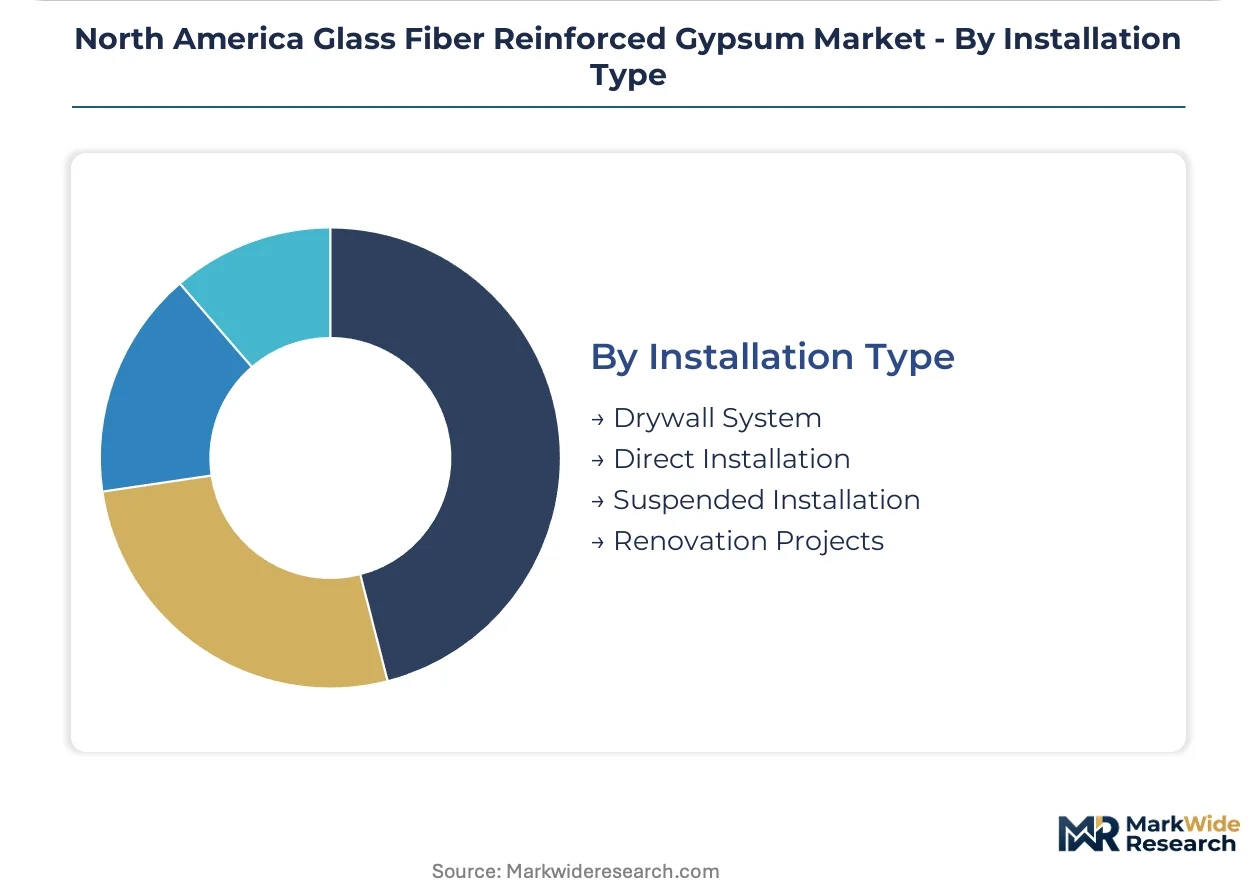
- Drywall System:Drywall systems incorporate GFRG panels directly into conventional gypsum board constructions for seamless integration.
- Direct Installation:Direct installation involves affixing GFRG components directly to structural surfaces using adhesives or mechanical fasteners.
- Suspended Installation:Suspended installation refers to GFRG components, primarily ceiling tiles, hung from a structural ceiling grid. This method is prevalent in commercial construction due to its efficiency for large areas and accessibility for building services.
- Renovation Projects:Renovation projects involve integrating GFRG into existing structures, often to meet updated codes or enhance aesthetics. A significant opportunity exists in retrofitting commercial buildings in aging urban cores across North America to improve fire safety and acoustics.
Suspended installation optimizes for large-scale applications, whereas renovation projects offer tailored integration opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North America Glass Fiber Reinforced Gypsum market responds directly to regulatory mandates and regional construction trends. NFPA regulations in the United States drive the use of non-combustible materials in commercial buildings. This significantly influences material specifications across the region.
United States
Commercial construction projects and high-end aesthetic finishing applications consistently drive GFRG demand. Stricter fire safety codes from the NFPA mandate GFRG use in public assembly buildings. Project pipelines in the Southern United States, particularly in cities like Houston, concentrate significant regional demand for these materials.
Canada
Canadian provincial regulations, especially concerning fire safety, bolster demand for GFRG in commercial and institutional sectors. These provincial codes compel the use of non-combustible interior materials. Ontario, Canada, exhibits substantial project pipelines, reflecting concentrated GFRG adoption in major metropolitan areas.
Mexico
Mexico's expanding commercial and high-end hospitality construction sectors present an underpenetrated market for specialized GFRG products. Local building codes increasingly emphasize fire resistance and aesthetic quality in new developments. Major urban centers like Mexico City are seeing increased specification for advanced interior finishing materials.
Southern United States
Large-scale commercial developments and high-end residential renovation projects drive GFRG consumption in the Southern United States. Municipal authorities enforce local building codes for fire resistance and structural integrity. High-growth corridors across states like Texas and Florida demonstrate consistent demand for GFRG solutions.
Ontario, Canada
Significant commercial and institutional project pipelines in Ontario fuel GFRG market expansion. Provincial fire safety regulations directly influence material selection for public and private buildings. Toronto's vibrant construction sector, including new high-rise and hospitality projects, represents a key concentration of GFRG use.
North America Glass Fiber Reinforced Gypsum Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the GFRG market. The market exhibits a tiered structure, with specialists in custom solutions at one end and volume producers at the other. Strategic archetypes include high-end custom fabricators, standardized panel manufacturers, and diversified building material suppliers. Capacity expansion and strategic partnerships represent dominant competitive moves among market participants.
Specialists in complex, custom decorative moldings like Stromberg Architectural serve high-end commercial projects across the United States. USG Corporation leverages its extensive distribution network to supply standard ceiling tiles and wall panels for volume applications. Formglas Products Ltd. also competes in the high-specification segment, focusing on intricate architectural forms for institutional and hospitality clients.
| Leading Market Players |
|---|
| Owens Corning |
| Stromberg Architectural |
| USG Corporation |
| National Gypsum |
| American Gypsum |
| Georgia-Pacific |
| Formglas Products Ltd |
| Saint-Gobain |
| CertainTeed |
| Others |
Cost & Logistics Intelligence
Large-scale manufacturing of GFRG panels drives significant scale economies, establishing price floors for standardized products. This concentration of production capacity influences supply chain structures and competitive dynamics across North America.
Pricing Analysis
Geographic price variations exist for GFRG products, influenced by regional construction activity and local labor costs. The dominant pricing model is project-based, with custom decorative moldings commanding higher value through bespoke design and intricate fabrication. Price differentiation stems from customization level and specialized installation requirements. Pricing softness affects standardized ceiling tiles due to volume competition, while high-end commercial projects exhibit lower price sensitivity for unique architectural elements.
Supply Chain Analysis
The United States and Canada anchor GFRG manufacturing, producing both high-volume standard panels and intricate custom components. Raw material dependencies include high-density alpha gypsum and continuous filament glass fibers, primarily sourced from regional suppliers. A structural risk involves the logistical complexity of transporting large, fragile GFRG components. Distribution runs through a bifurcated model, with specialized fabricators for custom work and extensive networks for standard products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GFRG market presents a compelling service-attach opportunity, particularly in specialized installation and maintenance. Custom mold fabrication, a recurring service, is expanding faster than the initial product sale for intricate architectural forms.
For Market Incumbents:Shield market share by investing in digital fabrication technologies to reduce lead times for custom projects. Consolidate distribution channels for standardized panels to counter emerging competition from alternative materials like polymer composites. Focus R&D on developing lower embodied carbon GFRG formulations to meet evolving sustainability mandates. This will protect against margin pressure from rising raw material costs.
For New Entrants and Emerging Players:ASTM C1355/C1355M certification fast-tracking offers a direct entry point for specialized GFRG fabricators. Target the high-end residential renovation segment in major urban centers, which shows strong growth for custom architectural elements. A go-to-market angle involves partnering with boutique architectural firms to offer bespoke design-and-build GFRG solutions. Focus on intricate decorative moldings, a less commoditized product type.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized GFRG installers and custom mold fabricators. The market demonstrates long-term viability, driven by stringent fire safety codes and aesthetic demand in commercial construction. Acquisition targets include regional custom fabricators with strong architectural relationships and digital fabrication capabilities. The signal to watch is the increasing specification of GFRG in public infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Fabrication Investment | Accelerates custom mold production, reducing lead times for architectural firms. |
| Sustainable Material Development | Addresses embodied carbon concerns, appealing to LEED-certified commercial projects. |
| Artisan Training Programs | Mitigates scarcity of skilled installers for complex GFRG decorative moldings. |
| Regional Capacity Expansion | Supports demand in high-growth corridors like the Southern United States. |
| Long-term Supply Agreements | Secures consistent material flow for programmatic commercial campus developments. |
Research Approach
A standing panel of GFRG manufacturers, architectural specifiers, general contractors, and building code officials provided ongoing calibration for market insights. This involved combining primary interviews with industry stakeholders and secondary validation from ASTM standards and municipal building codes. Bottom-up and top-down triangulation ensured data accuracy across all segments.
Forecast outputs were validated against external benchmarks, including regional construction spending and material specification trends. The analytical framework modeled segmentation dimensions by product type, end-user, application, and installation type across the analysis window. Compound annual growth rates were derived from historical performance and projected construction pipelines. Project density in major metropolitan areas served as a key forecast input.
Underlying assumptions cover stable raw material availability and consistent regulatory enforcement, with deviation risk concentrated in unforeseen economic downturns or rapid material substitution. Forecasts reflect these assumptions, acknowledging potential shifts in construction activity. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
North America Nanofiber Market
Fibers
Precision Fiber Molding Market
Fibers
Dry-Molded Fibre Market
Fibers
Basalt Continuous Fiber (BCF) Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
High Performance Fibers for Defense Market
Fibers
Global Fiberglass Mold Market
Fibers
Carbon Fiber Wrap Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Carbon Fiber Filament Market
Fibers
Metal Fiber Felt Market
Fibers
Global Bicomponent Fiber Market
Fibers
Global Electronic Grade Glass Fibers Market
Fibers
Citrus Pulp Fiber Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Global Concrete Fiber Market