
 Malaysia Construction Chemicals Market | 2026-2036
Malaysia Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Construction Chemicals Market Insights
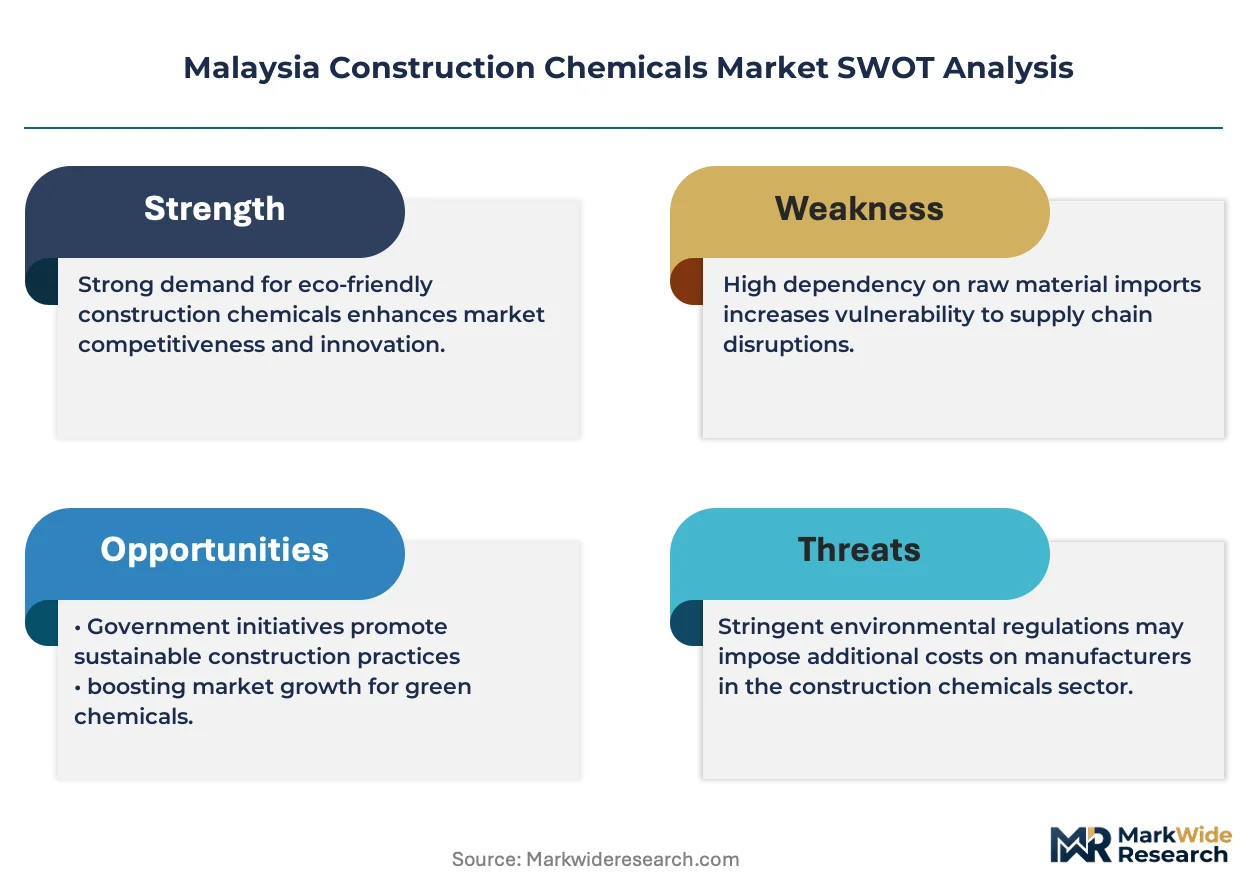
A widening capability gap in polymer synthesis and on-site technical service is rotating competitive dynamics among Malaysian suppliers. Sika leverages its integrated admixture and waterproofing portfolio to dominate complex infrastructure bids. MBCC Group sustains R&D intensity in cementitious systems for high-performance concrete applications. Fosroc anchors its position through channel control in East Malaysia, where logistics complexity limits rival penetration.
Construction chemicals encompass formulated admixtures, sealants, protective coatings, and repair mortars engineered to enhance concrete durability, structural bonding, and environmental resistance through controlled chemical reactions with cementitious substrates. These formulations typically incorporate acrylic polymers, epoxies, or silanes to achieve specified compressive strength gains, permeability reduction, or chloride ion resistance thresholds. Admixtures command the deepest margin pools due to volume scale in ready-mix concrete supply chains. Waterproofing technology is displacing conventional membrane systems in basement and tunnel specifications across Peninsular Malaysia. Sealants occupy a mature growth trajectory tied to glazing and facade replacement cycles in Kuala Lumpur's commercial stock.
CIDB Malaysia enforces product certification and contractor grading requirements that filter substandard admixture imports from regional traders. The Department of Standards Malaysia (DSM) aligns construction chemical testing protocols with MS EN benchmarks, while the Green Building Index accreditation framework elevates low-VOC and recycled-content formulations in public tender evaluations. Stakeholders must monitor how Putrajaya integrates carbon-intensity thresholds into infrastructure procurement rules without diluting performance specifications for tropical exposure conditions.
Market Dynamics
CIDB Malaysia's enforcement of BIS-equivalent product certification is filtering substandard admixture imports and consolidating procurement around technically qualified suppliers. This regulatory tightening intersects with the Twelfth Malaysia Plan's infrastructure megaprojects to reshape competitive access.
Growth Catalysts
- The Twelfth Malaysia Plan:Infrastructure megaprojects spanning mass rapid transit extensions and flood mitigation schemes are mandating high-performance concrete specifications that require certified admixture and waterproofing systems.
- Green Building Index accreditation:Public tender evaluations now weight low-VOC and recycled-content formulations, redirecting specification authority toward environmentally credentialed suppliers in Selangor and Kuala Lumpur.
- Klang Valley concentration:Urban densification in the Kuala Lumpur-Selangor corridor is compressing basement and tunnel construction timelines, accelerating specification of rapid-setting repair mortars and crystalline waterproofing systems.
Market Restraints
- Petrochemical feedstock volatility:Acrylic polymer and epoxy resin costs fluctuate with regional naphtha pricing, compressing margin visibility for formulators serving price-sensitive government contractors.
- East Malaysia logistics fragmentation:Sabah and Sarawak's archipelagic geography limits bulk liquid admixture distribution, constraining ready-mix concrete supply chain integration outside Peninsular Malaysia.
- Cementitious system performance ceilings:Tropical humidity and chloride-laden coastal exposure challenge conventional repair mortar durability, forcing premature reapplication cycles on marine infrastructure.
Strategic Opportunities
- Johor Bahru-Singapore corridor:Iskandar Malaysia's special economic zone status and cross-border logistics integration offer untapped specification channels for high-performance concrete projects serving Singaporean contractors.
- Silane-based hydrophobic treatments:Nanoscale penetrating sealers are penetrating heritage conservation and monument protection applications previously served by surface coatings, opening premium pricing tiers.
- CIDB contractor grading alignment:Suppliers bundling technical training with product certification can capture specification authority from upgrading G-grade contractors seeking eligibility for federal infrastructure tenders.
Industry Challenges
- Polymer synthesis technical capacity:Malaysian formulators lack captive production of performance-grade acrylic emulsions, creating dependency on Thai and Singaporean specialty chemical imports for high-specification waterproofing systems.
- MS EN testing protocol compliance timelines:DSM-aligned certification cycles for novel admixture chemistries extend 12-18 months, delaying commercialization of modified formulations against faster-moving regional competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Construction Chemicals Market |
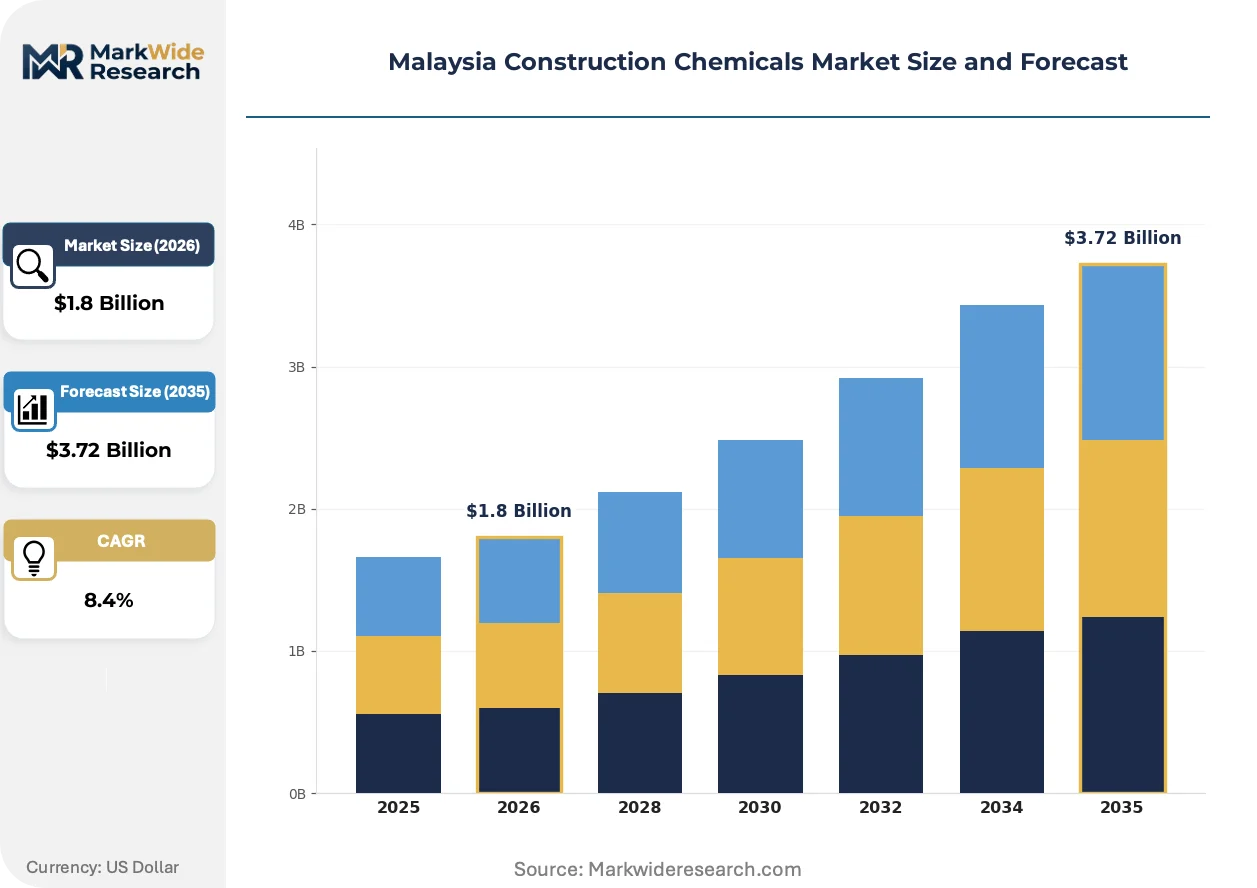
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Coatings, Mortars Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Developers, Architects, Engineers Technology: Waterproofing, Self-Leveling, Lightweight, Polymer-Based |
| Companies Covered | Sika, MBCC Group, Fosroc, Mapie, Pentens, Bostik, Ardex Group, Cementaid International, MC-Bauchemie, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Construction Chemicals Market Trends and Innovations
Crystalline waterproofing technology is displacing conventional membrane systems across Malaysian basement and tunnel specifications. Regulatory pressure from green building frameworks is compressing VOC thresholds. Procurement concentration among tier-one contractors is reshaping channel economics.
Crystalline waterproofing admixtures penetrate concrete capillaries to form insoluble crystalline structures that block water migration. Mass rapid transit contractors in Kuala Lumpur are specifying these systems for station box structures and tunnel linings. The technology is displacing sheet membrane applications that require labor-intensive surface preparation and joint detailing in confined underground conditions.
Malaysia's Department of Standards Malaysia alignment with MS EN testing protocols is elevating documentation requirements for chloride ion permeability and sulfate resistance. Formulators must now submit extended durability data to CIDB for product listing. High-performance concrete applications in marine environments and coastal highway projects face the most stringent verification timelines.
Consolidation among G7-grade contractors under CIDB's registration system is concentrating specification authority with fewer procurement decision-makers. These contractors are unbundling technical service from material supply, engaging independent testing laboratories for mix design validation. The Klang Valley's ready-mix concrete supply chains exhibit the most pronounced shift toward performance-guaranteed supply contracts.
Malaysia Construction Chemicals Market Segmentation
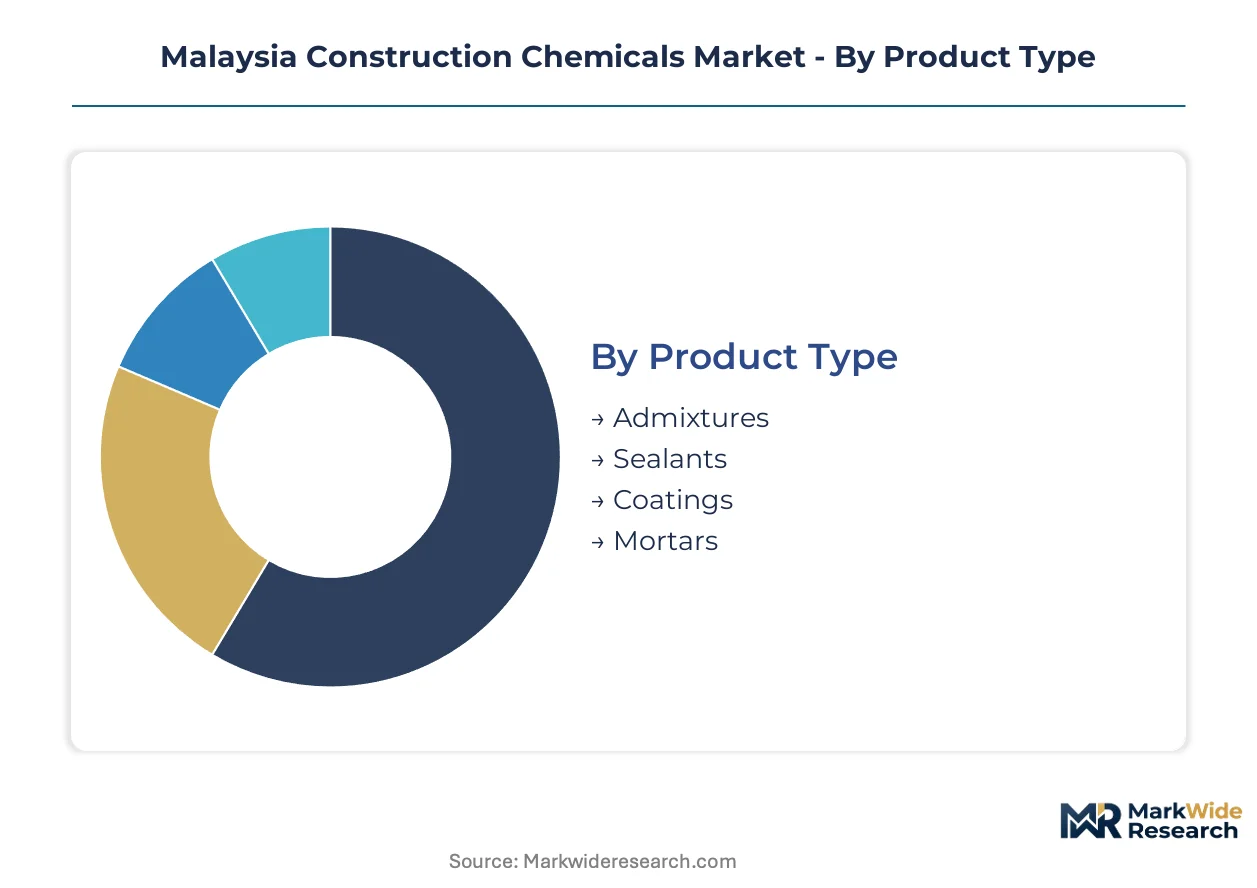
Segmentation in Malaysia's construction chemicals market reveals how regulatory pressure, project scale, and technical service requirements reshape procurement patterns across distinct customer clusters and application environments.
Product Type:
Domestic manufacturing concentrates in Peninsular Malaysia's Klang Valley industrial corridor, while specialty polymer imports from Thailand and Singapore serve high-specification waterproofing and repair applications.
- Admixtures:These cement-compatible formulations incorporate water reducers, accelerators, and retarders to modify concrete workability and curing profiles. Mass rapid transit contractors in Kuala Lumpur specify certified admixtures for high-performance concrete in station box structures and tunnel linings, with CIDB certification filtering substandard imports from regional traders.
- Sealants:Polyurethane and silicone compounds engineered for movement joint accommodation and weatherproofing in facade assemblies. Demand concentrates in commercial glazing replacement cycles across Kuala Lumpur's aging office stock, where Green Building Index accreditation elevates low-VOC specifications in public tender evaluations.
- Coatings:Epoxy and acrylic protective layers for steel reinforcement and concrete surface defense.
- Mortars:Cementitious repair compounds for structural rehabilitation and surface restoration.
Admixtures command the established base. The steepest expansion runs through waterproofing technology displacing conventional membrane systems.
Application:
Cost tier stratification separates premium performance-guaranteed contracts for infrastructure megaprojects from price-sensitive residential procurement.
- Residential:Standard-grade waterproofing and tile adhesive applications in high-rise condominium construction across Selangor. Volume scale in ready-mix concrete supply chains compresses margins, with developers prioritizing cost efficiency over extended durability warranties in speculative housing projects.
- Commercial:Integrated facade systems combining sealants, coatings, and crystalline waterproofing for office and retail developments. Green Building Index requirements redirect specification authority toward suppliers with documented recycled-content formulations and technical service capabilities for mix design validation.
- Industrial:Chemical-resistant flooring and protective coatings for manufacturing facilities.
- Infrastructure:High-performance concrete specifications for bridges, highways, and marine structures under Twelfth Malaysia Plan funding.
Infrastructure absorbs the premium tier. Commercial applications are climbing the fastest as green certification tightens.
End User:
Customer type determines technical service intensity, with contractor grading systems concentrating specification authority among fewer procurement decision-makers.
- Contractors:CIDB-registered G7-grade contractors dominate federal infrastructure tenders, unbundling technical service from material supply and engaging independent testing laboratories for mix design validation. These firms specify performance-guaranteed supply contracts that shift liability to admixture suppliers for concrete achievement targets.
- Developers:Speculative residential and commercial project sponsors prioritizing cost control and construction timeline compression. Procurement concentrates in the Klang Valley corridor, where urban densification accelerates basement and tunnel construction specifications for rapid-setting repair systems.
- Architects:Design-phase specification authority for aesthetic and durability performance in landmark commercial projects.
- Engineers:Structural verification and chloride ion permeability compliance for marine and coastal highway applications.
Contractors control volume flows. Engineers are gaining specification influence fastest through compliance verification demands.
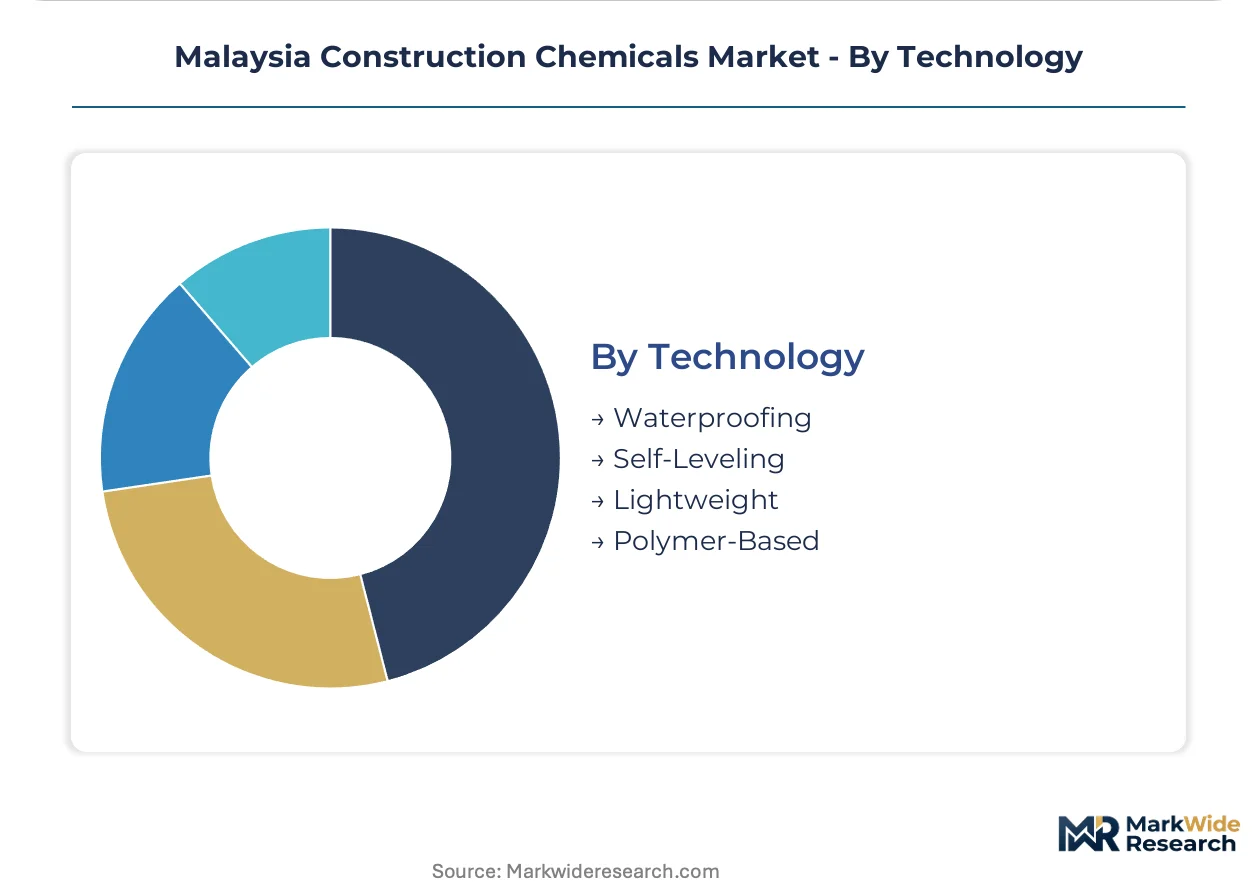
Technology:
Supply concentration in polymer synthesis capability separates domestic formulators from import-dependent competitors in advanced waterproofing systems.
- Waterproofing:Crystalline admixtures and silane-based hydrophobic treatments penetrating concrete capillaries to block water migration. Mass rapid transit extensions in Kuala Lumpur specify these systems for confined underground conditions where sheet membrane application faces labor and joint detailing constraints.
- Self-Leveling:Polymer-modified cementitious underlayments for flooring preparation in commercial fit-outs. Demand tracks refurbishment cycles in Kuala Lumpur's aging commercial stock, with rapid-setting formulations compressing construction timelines in occupied buildings.
- Lightweight:Density-reduced concrete additives for structural weight optimization in high-rise construction.
- Polymer-Based:Acrylic and epoxy formulations for bonding, repair, and protective applications.
Waterproofing holds the technology lead. Self-leveling systems are expanding most quickly through commercial refurbishment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's construction chemicals sector maintains a net import position for specialty polymer intermediates while exporting formulated admixtures to neighboring Southeast Asian markets. Trade flows concentrate through Port Klang's chemical handling facilities and Singapore's transshipment hub.
Klang Valley
Mass rapid transit extensions and flood mitigation infrastructure under the Twelfth Malaysia Plan are consuming crystalline waterproofing and high-performance concrete admixtures. CIDB Malaysia enforces BIS-equivalent certification for all federally funded projects, filtering substandard imports. Kuala Lumpur and Selangor host the densest concentration of ready-mix concrete batching plants and technical service laboratories.
Johor
Iskandar Malaysia's special economic zone status attracts Singaporean contractors specifying performance-guaranteed concrete supply contracts. Cross-border logistics integration enables just-in-time admixture delivery for high-rise residential towers serving the Singapore commuter market. Johor Bahru's industrial parks house regional distribution centers for waterproofing system imports.
Penang
Electronics manufacturing facility construction drives demand for chemical-resistant flooring and cleanroom-grade sealants. The state's northern location creates supply chain dependencies on Thai specialty chemical imports for advanced polymer formulations. Bayan Lepas and Batu Kawan industrial zones concentrate specification authority with multinational EPC contractors.
Sabah
Archipelagic geography fragments ready-mix concrete supply chains, limiting bulk liquid admixture distribution to major coastal population centers. Marine infrastructure projects face premature repair cycles due to chloride-laden exposure conditions challenging conventional cementitious systems. Kota Kinabalu anchors procurement for federal infrastructure spending in East Malaysia.
Sarawak
Hydropower and coastal highway projects under state development plans specify extended durability warranties for tropical exposure conditions. Logistics complexity favors suppliers with established channel control and localized technical service presence. Kuching and Miri serve as procurement hubs for hinterland construction activity.
Malaysia Construction Chemicals Market Competitive Landscape
Concentration sits with integrated multinational suppliers possessing captive polymer synthesis capabilities and CIDB-certified product portfolios. The vendor base stratifies across three tiers: global formulators with full-service technical capabilities, regional specialists in waterproofing or repair niches, and local distributors serving price-sensitive residential segments. Competitive dynamics rotate around certification maintenance, on-site technical service deployment, and contractor grading alignment. M&A activity targets regional waterproofing specialists, while capacity expansion concentrates in Peninsular Malaysia's Klang Valley corridor.
Within the integrated multinational tier, Sika and MBCC Group exemplify suppliers combining admixture manufacturing with waterproofing system integration. Fosroc occupies a position emphasizing channel depth in East Malaysia, where logistics barriers protect established relationships. These three anchors represent distinct strategic postures: Sika through portfolio breadth, MBCC Group through cementitious system specialization, and Fosroc through geographic coverage in fragmented peripheral markets.
| Leading Market Players |
|---|
| Sika |
| MBCC Group |
| Fosroc |
| Mapie |
| Pentens |
| Bostik |
| Ardex Group |
| Cementaid International |
| MC-Bauchemie |
| Others |
Pricing and Supply Chain Analysis
Forty-five-day inventory cycles for acrylic polymer emulsions concentrate pricing power with Thai and Singaporean specialty chemical suppliers serving Malaysian formulators. This lead-time exposure amplifies margin compression when naphtha feedstock volatility intersects with CIDB certification delays.
Pricing Analysis
The customization-premium spread separates performance-guaranteed supply contracts for G7-grade contractors from standard-grade admixtures in speculative residential projects. Pricing stratifies across premium, standard, and economy tiers based on CIDB certification tier and volume scale, with government contractors least price-sensitive due to Twelfth Malaysia Plan specification mandates. Cost compression in the residential tier intensifies because developers prioritize timeline efficiency over extended durability warranties.
Supply Chain Analysis
Singapore's Jurong Island petrochemical complex anchors regional acrylic emulsion supply for Malaysian waterproofing formulators lacking captive polymer synthesis. Domestic manufacturing draws from Thai specialty chemical imports for high-performance cementitious systems, while bulk liquid admixture distribution hinges on Port Klang's chemical handling infrastructure. Single-source vulnerability concentrates in Singapore-originated epoxy resin feedstocks, with distribution running through ready-mix concrete batching plants concentrated in the Klang Valley corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against crystalline waterproofing technology displacing conventional membrane systems across basement and tunnel specifications. The threat intensifies as mass rapid transit contractors mandate performance-guaranteed supply contracts that shift liability to suppliers.
For Market Incumbents: Compound technical service capabilities through CIDB contractor grading alignment, bundling mix design validation with product certification to capture specification authority from upgrading G-grade contractors. Backward integration into acrylic emulsion production reduces Thai and Singaporean import dependency for high-specification waterproofing systems. Channel control investments in Sabah and Sarawak exploit logistics fragmentation that limits rival penetration.
For New Entrants and Emerging Players: Lead with silane-based hydrophobic treatments penetrating heritage conservation and monument protection applications previously served by surface coatings, commanding premium pricing tiers unavailable to commodity admixture competitors. Target Johor Bahru-Singapore corridor projects through cross-border logistics integration serving Iskandar Malaysia's special economic zone. Engage Singaporean contractors specifying performance-guaranteed concrete supply contracts as the primary go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a certification-anchored consolidation play because CIDB enforcement of BIS-equivalent standards filters substandard imports and consolidates procurement around technically qualified suppliers. Acquisition candidates include regional waterproofing specialists with established MS EN testing protocol documentation and on-site technical service deployment capabilities. Monitor Putrajaya's integration of carbon-intensity thresholds into infrastructure procurement rules as the signal for specification authority rotation toward low-VOC and recycled-content formulators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylic emulsion production reduces Thai and Singaporean import dependency for waterproofing systems. |
| CIDB Certification Investment | Accelerates product listing timelines against 12-18 month MS EN testing protocol compliance cycles. |
| Technical Service Expansion | On-site mix design validation captures specification authority from G7-grade contractors unbundling supply from service. |
| East Malaysia Channel Buildout | Localized presence in Sabah and Sarawak exploits archipelagic logistics barriers limiting rival penetration. |
| Green Formulation Development | Low-VOC and recycled-content credentials align with Green Building Index accreditation in public tender evaluations. |
Research Methodology
The analysis maps admixtures, waterproofing systems, sealants, and repair mortars, each validated through technical directors at ready-mix concrete suppliers, procurement leads at CIDB-registered contractors, distribution channel partners in Peninsular and East Malaysia, and regulatory affairs specialists at Department of Standards Malaysia. Primary interview insights triangulate against customs and trade data, CIDB product certification registers, Green Building Index accreditation records, and SEC filings of listed multinational suppliers. Bottom-up volume estimates from application-level consumption patterns reconcile with top-down market sizing derived from Twelfth Malaysia Plan infrastructure expenditure allocations.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework models segmentation dimensions including product type, application sector, end-user category, and technology tier, with regional production hub differentiation across Klang Valley, Johor, and East Malaysia clusters. CAGRs derive from trend extrapolation of specification shifts, regulatory enforcement intensity, and contractor grading consolidation patterns, incorporating petrochemical feedstock cost trajectories and infrastructure project pipeline visibility as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Twelfth Malaysia Plan funding execution, stable CIDB certification enforcement, and continued Green Building Index accreditation adoption would require recalibration. Forecasts reflect documented assumptions about polymer synthesis capability gaps, MS EN testing protocol timelines, and logistics fragmentation in East Malaysia. Practitioners should keep alternative scenarios live as Putrajaya's carbon-intensity procurement integration and regional petrochemical supply disruptions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
2-(4-(Bromomethyl)phenyl)propionic Acid (BMPPA) Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
South America Isoamyl Acetate Market
Chemicals
3-Fluoro-5-Nitrotoluene Market
Chemicals
Phosgene Market
Chemicals
US Methanol Market
Chemicals
Calcium Hydroxide Market
Chemicals
Middle East and Africa Construction Chemicals Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
CHPTAC Market
Chemicals
Immunochemicals Market
Chemicals
Perchloric Acid Market
Chemicals
Brazil Methanol Market
Chemicals
Welding Chemicals Market
Chemicals
Malic Acid Market