
 Global Metal Fiber Market | 2026-2036
Global Metal Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Fiber Market Foresight
Aerospace industry demand is restructuring the Global Metal Fiber Market as defense and commercial aviation programs scale heat-resistant material orders. N.V. Bekaert S.A. leverages its spun metal fiber capacity to anchor European supply chains for filtration and shielding applications. Nippon Seisen Co., Ltd. dominates precision stainless steel fiber output for Asian electronics manufacturers. IntraMicron, Inc. specializes in micro-diameter fibers that sustain premium positioning across battery separator and chemical processing segments.
Metal fiber consists of filaments drawn or spun from metals and alloys, typically ranging from one to one hundred micrometers in diameter, engineered for conductivity, thermal resistance, or filtration efficiency across industrial processes. Stainless steel fiber leads product type shipments due to established corrosion resistance and weldability in harsh chemical environments. Melt blown metal fiber technology captures expanding margin pools as battery separator applications require finer, more uniform filament structures. Powder metallurgy remains mature but occupies critical niches in aerospace-grade titanium fiber production where porosity control determines performance.
FDA, EPA, and REACH frameworks shape metal fiber demand by mandating filtration efficiency thresholds in pharmaceutical and chemical processing equipment. The EU Green Deal and China's dual carbon goals are forcing producers to document lifecycle emissions in metal fiber supply chains. Stakeholders must monitor how evolving battery safety standards in multiple jurisdictions redefine acceptable conductivity and thermal runaway specifications for separator materials.
Market Dynamics
Aerospace thermal protection requirements and battery separator specifications are compressing fiber diameter tolerances while expanding addressable applications across defense and energy storage verticals.
Growth Catalysts
- Battery separator demand:Solid-state and lithium-ion manufacturers require sub-ten-micrometer stainless steel fibers to prevent thermal runaway, pulling capacity expansion from melt-blown producers in Germany and China.
- REACH compliance deadlines:European chemical processors must retrofit filtration systems by 2027, mandating corrosion-resistant metal fiber media in pharmaceutical and specialty chemical plants.
- Titanium fiber composites:NASA and ESA re-entry vehicle programs are qualifying 3D-woven titanium fiber matrices for ablative heat shields, creating dedicated supply streams distinct from commodity stainless grades.
Market Restraints
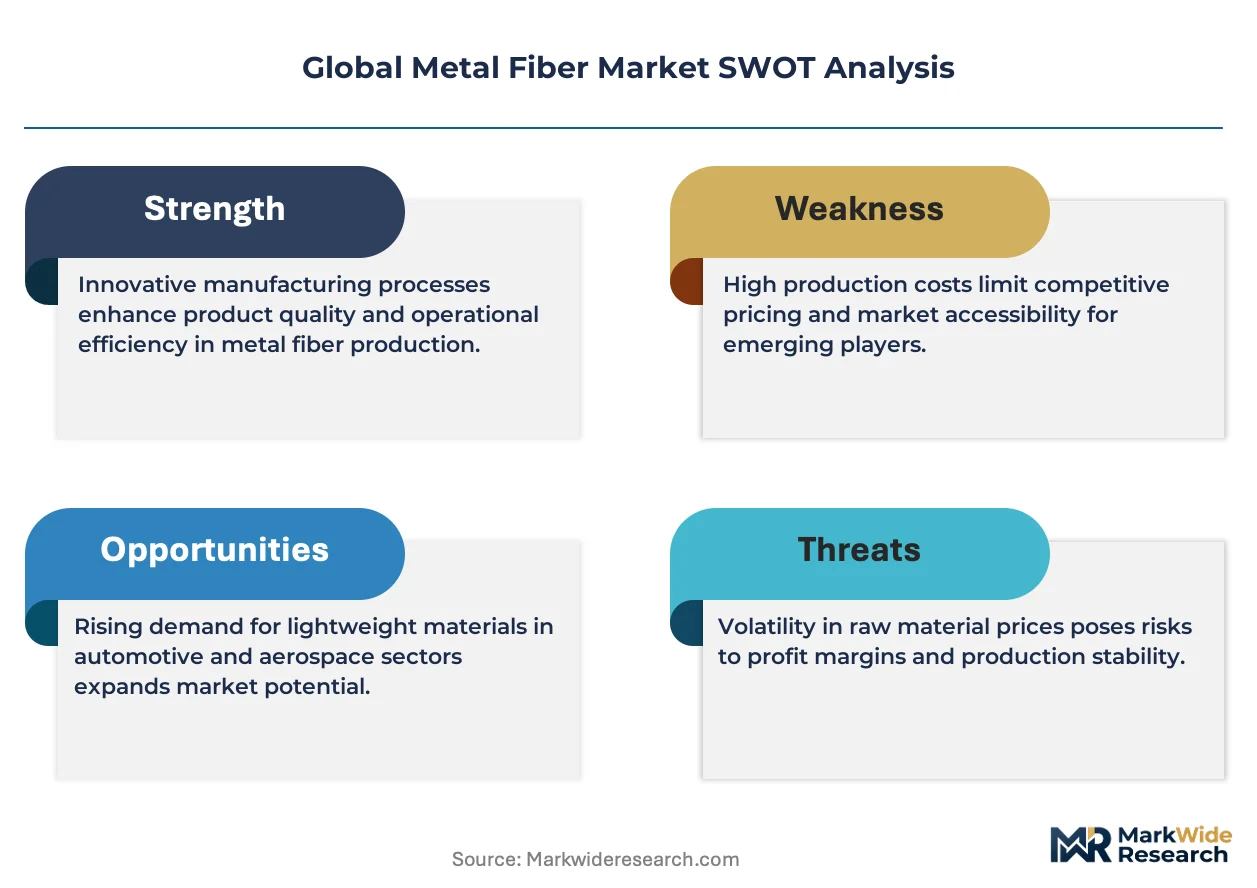
- Raw material volatility:Nickel and titanium sponge prices swing with Indonesian ore export restrictions and Russian supply disruptions, compressing margins for non-integrated fiber spinners.
- Spun capacity concentration:Precision metal fiber drawing equipment is manufactured by fewer than six specialized machinery builders globally, creating eighteen-month lead times for capacity expansion.
- Polymer fiber substitution:High-performance polyimide and aramid fibers from Teijin and DuPont capture cost-sensitive filtration applications below 200°C operating thresholds.
Strategic Opportunities
- India manufacturing localization:PLI scheme incentives for advanced battery cell production are attracting metal fiber separator suppliers to Gujarat and Tamil Nadu industrial corridors.
- Hydrogen infrastructure filtration:Proton exchange membrane electrolyzers require palladium-coated metal fiber diffusers, an application with near-zero current supplier penetration outside Japan.
- CSRD disclosure requirements:European industrial buyers must document Scope 3 emissions, favoring metal fiber producers with verified low-carbon melt-blown processes over conventional drawn fiber imports.
Industry Challenges
- Micro-diameter drawing expertise:Operators capable of maintaining 2-5 micrometer consistency across kilometer-length spools number fewer than 400 globally, constraining output scaling for battery-grade specifications.
- Multi-jurisdiction certification overlap:Aerospace fiber lots require concurrent FAA, EASA, and CAAC qualification, extending commercialization timelines by 18-24 months for new alloy formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Fiber Market |
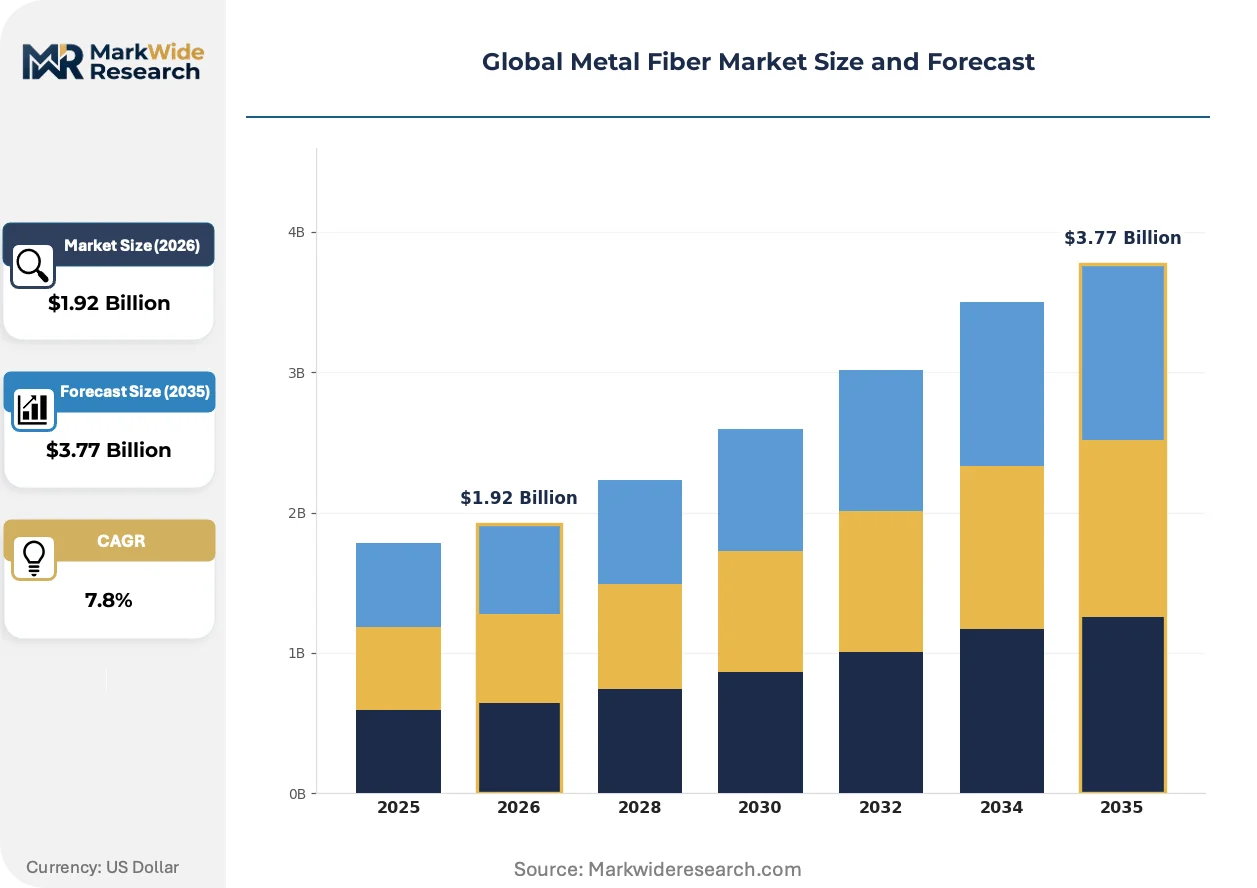
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.77 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
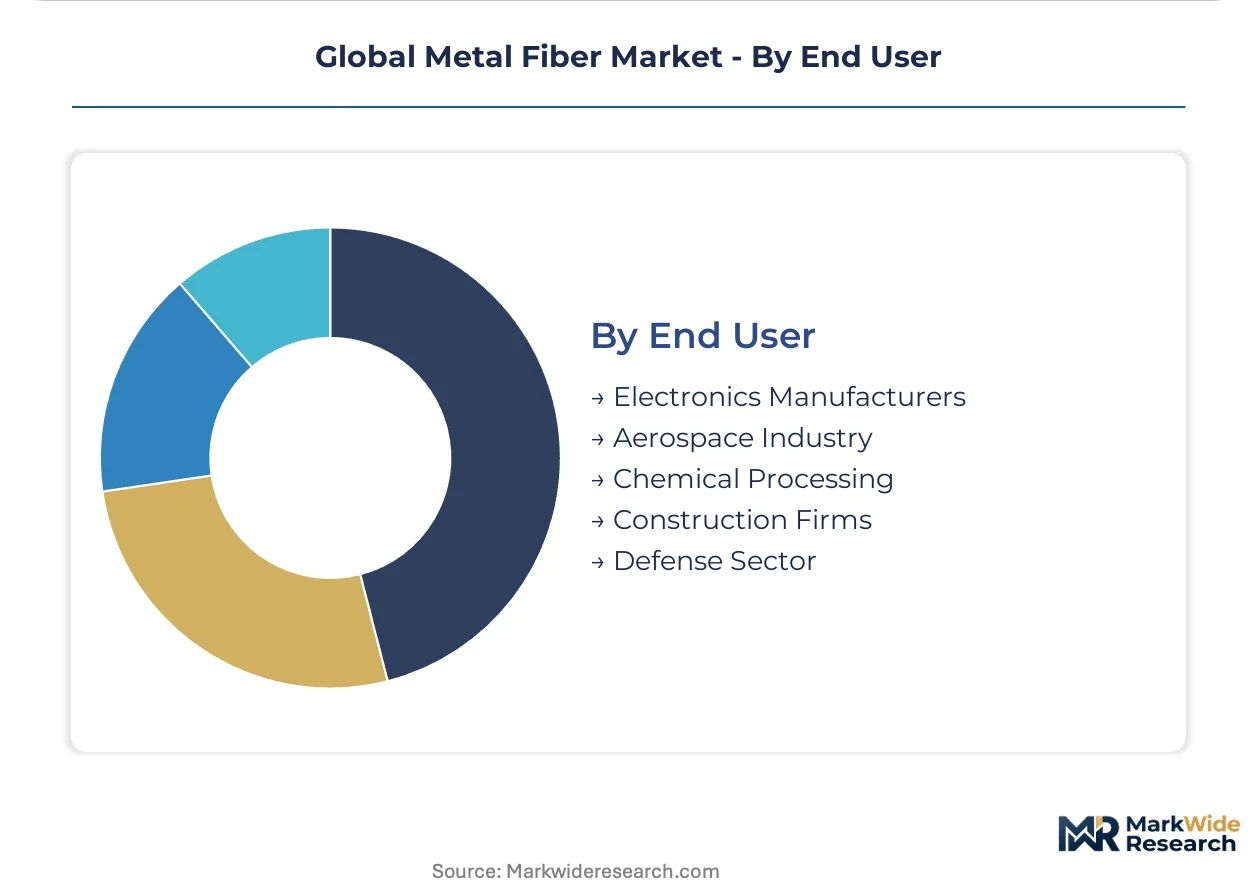
| Segmentation | Product Type: Stainless Steel Fiber, Aluminum Fiber, Copper Fiber, Nickel Fiber, Titanium Fiber Technology: Spun Metal Fiber, Melt Blown Metal Fiber, Powder Metallurgy, Electrospinning, Expanded Metal Fiber Application: Filtration, Electromagnetic Shielding, Battery Separator, Sound Absorption, Heating Elements End User: Electronics Manufacturers, Aerospace Industry, Chemical Processing, Construction Firms, Defense Sector |
| Companies Covered | N.V. Bekaert S.A, Fibrometals SRL, Nippon Seisen Co., Ltd, Addas Group, Green Steel Group, IntraMicron, Inc., Guven Metal, BinNova Metal Fiber Technology GmbH, MBC Metal Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Fiber Market Shifts & Advancements
Melt-blown metal fiber production is displacing conventional drawing for applications demanding sub-ten-micrometer uniformity, while regulatory frameworks harden material traceability requirements across battery and aerospace supply chains.
Electrospinning-derived metal fiber mats are consolidating as the dominant architecture for next-generation battery separators. Korean and Chinese cell manufacturers specify these non-woven structures for their tortuosity control and electrolyte wicking performance. The technology is consolidating supplier margins toward equipment-integrated producers capable of in-house polymer-to-metal conversion.
EU Green Deal carbon border adjustment mechanisms are forcing non-European metal fiber exporters to document embodied emissions. German filtration OEMs now require supplier-specific Environmental Product Declarations certified under EN 15804, shifting procurement preference toward European melt-blown capacity with grid-decarbonized electricity inputs. Italian and Polish chemical processors are accelerating stainless fiber inventory builds ahead of 2026 compliance deadlines.
Long-term offtake contracting is displacing spot purchasing across aerospace and battery verticals. Tier-1 filtration system builders in the United States are locking three-to-five-year titanium and nickel fiber supply agreements directly with spun metal producers, bypassing traditional distributor intermediaries. This pattern concentrates most visibly in California and Texas, where defense contractors and solid-state battery startups compete for identical high-purity fiber specifications.
Global Metal Fiber Market Segmentation
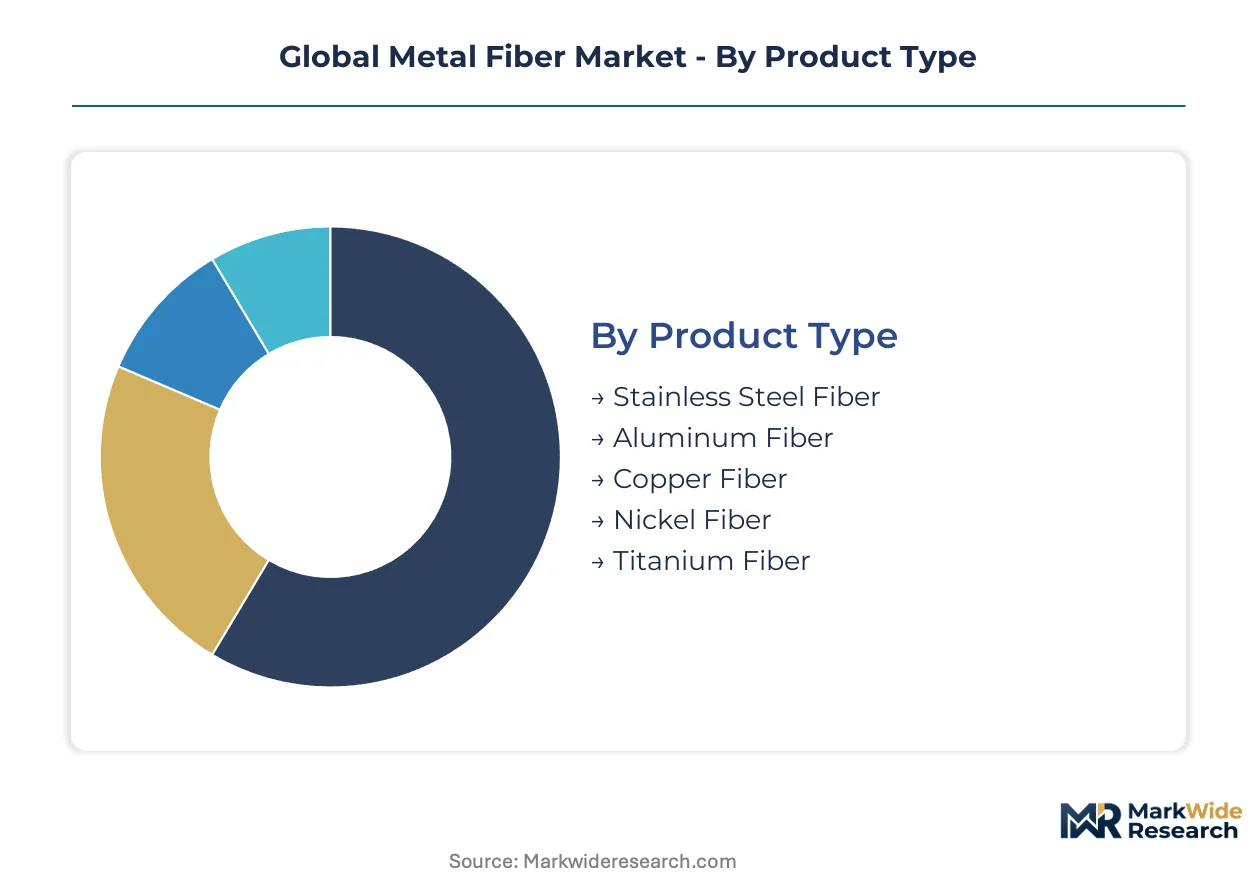
Metal fiber specifications diverge sharply across end-use requirements, with aerospace thermal protection systems demanding titanium grades that filtration OEMs would reject as economically unviable. Technology selection locks producers into distinct capital intensity tiers, while application-driven purity standards fragment procurement patterns across regional supply chains.
Product Type:
Replacement cycles for corrosion-resistant filtration media and battery separator substrates are compressing as REACH compliance deadlines and thermal runaway safety standards force premature equipment upgrades across European and Asian processing facilities.
- Stainless Steel Fiber:Austenitic and ferritic grades dominate chemical processing filtration where sulfuric acid exposure demands chromium-nickel matrices above 18% Cr content. German pharmaceutical OEMs in Ludwigshafen and Chinese battery separator producers in Ningbo account for the bulk of melt-blown capacity absorption, driven by FDA filtration efficiency mandates and domestic dual carbon documentation requirements.
- Titanium Fiber:CP-Ti and Ti-6Al-4V alloys woven into 3D matrices serve ablative heat shields for NASA and ESA re-entry vehicles, with porosity control below 40% determining qualification. Dedicated supply streams exclude commodity stainless spinners due to vacuum arc remelt feedstock requirements and kilometer-length spool consistency below 5 micrometers.
- Aluminum Fiber:Lightweight conductivity drives electromagnetic shielding applications in Korean consumer electronics, though oxidation sensitivity limits harsh environment deployment.
- Copper Fiber:Superior electrical conductivity positions this grade for heating element architectures in industrial process equipment, particularly where rapid thermal response outweighs corrosion concerns.
- Nickel Fiber:High-temperature oxidation resistance serves aerospace combustion liner applications, with Inconel-derived variants capturing specialty chemical processing niches above 800°C operating thresholds.
Volume placements concentrate in stainless steel fiber; the faster expansion belongs to titanium fiber.
Technology:
Cost tier stratification separates equipment-integrated producers capable of in-house polymer-to-metal conversion from commodity spinners dependent on external machinery builders.
- Melt Blown Metal Fiber:Sub-ten-micrometer uniformity for battery separator applications requires controlled gas attenuation of molten metal streams, capturing premium margin pools as Korean and Chinese cell manufacturers specify tortuosity-controlled non-woven architectures. Grid-decarbonized electricity inputs in German production facilities now command procurement preference under EU Green Deal carbon border adjustment mechanisms.
- Spun Metal Fiber:Bundle drawing of stainless and nickel alloys maintains established filtration market share through corrosion resistance in pharmaceutical and specialty chemical plants, though diameter consistency above 20 micrometers excludes next-generation separator specifications.
- Electrospinning:Polymer-to-metal conversion via calcination of precursor mats consolidates supplier margins toward integrated producers with captive polymer synthesis, particularly in Japanese and Korean electronics supply chains.
- Powder Metallurgy:Mature titanium fiber production for aerospace grades where porosity control determines performance, occupying critical niches despite slower throughput versus melt-blown alternatives.
- Expanded Metal Fiber:Slit-and-stretch processing of foil stock serves cost-sensitive heating element and sound absorption applications where fiber diameter uniformity is secondary to conductive surface area.
Capital intensity climbs from expanded metal toward electrospinning; the steepest expansion trajectory sits with melt-blown capacity.
Application:
Customer type fragmentation separates specification-driven aerospace procurement from price-sensitive construction sector purchasing, with intermediate tiers showing mixed margin profiles.
- Filtration:Corrosion-resistant stainless steel media in pharmaceutical and specialty chemical processing faces mandatory retrofit deadlines under REACH compliance, with Italian and Polish processors accelerating inventory builds ahead of regulatory enforcement. Efficiency thresholds for sub-micron particle capture favor finer diameter melt-blown structures over conventional spun alternatives.
- Battery Separator:Solid-state and lithium-ion manufacturers require sub-ten-micrometer stainless steel fibers to prevent thermal runaway, with thermal conductivity and electrolyte wicking performance specifications consolidating procurement toward electrospun non-woven architectures from integrated Korean and Chinese suppliers.
- Electromagnetic Shielding:Copper and aluminum fibers serve consumer electronics and defense applications where weight reduction competes with attenuation performance across GHz frequency ranges.
- Heating Elements:Resistive heating applications in industrial process equipment favor nickel-chromium and iron-chromium-aluminum fiber mats for rapid thermal cycling durability.
- Sound Absorption:Porous metal fiber structures in automotive and industrial noise control leverage tortuous path acoustic impedance matching, typically employing expanded metal or coarse spun grades where cost minimization dominates specification.
Filtration retains the largest installed base; battery separator applications are climbing the fastest.
End User:
Supply concentration among machinery builders creates eighteen-month lead times that favor long-term offtake contracting over spot purchasing across defense and energy storage verticals.
- Aerospace Industry:NASA and ESA re-entry vehicle programs qualify 3D-woven titanium fiber matrices for ablative heat shields, with concurrent FAA, EASA, and CAAC certification requirements extending commercialization timelines by 18-24 months for new alloy formulations. California and Texas defense contractors compete directly with solid-state battery startups for identical high-purity fiber specifications.
- Electronics Manufacturers:Korean and Chinese cell producers specify electrospun separator architectures, while Japanese electronics OEMs maintain precision stainless fiber demand for electromagnetic shielding in consumer devices.
- Chemical Processing:European pharmaceutical and specialty chemical plants face mandatory filtration system retrofit deadlines, mandating corrosion-resistant metal fiber media with documented lifecycle emissions under CSRD disclosure requirements.
- Defense Sector:Thermal protection and electromagnetic shielding applications drive titanium and nickel fiber procurement through long-term supply agreements bypassing traditional distributor intermediaries.
- Construction Firms:Sound absorption and heating element applications in commercial building systems represent the most price-sensitive demand tier, with expanded metal and coarse spun grades capturing share through distributor channels.
Procurement concentration sits with aerospace and electronics manufacturers; construction firms represent the most fragmented demand tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for advanced battery cell production is concentrating metal fiber separator investment in Gujarat and Tamil Nadu industrial corridors. Special economic zones in these states offer capital subsidies that offset eighteen-month machinery lead times.
United States
Defense contractors in California and Texas compete with solid-state battery startups for identical high-purity titanium and nickel fiber specifications. The FAA maintains concurrent certification requirements with EASA and CAAC that extend commercialization timelines. Long-term offtake contracting now bypasses traditional distributor intermediaries in these states.
Germany
REACH compliance deadlines mandate corrosion-resistant metal fiber media retrofit in Ludwigshafen pharmaceutical and specialty chemical plants. The EU Green Deal carbon border adjustment mechanism favors domestic melt-blown capacity with grid-decarbonized electricity. ECHA enforcement timelines are accelerating stainless fiber inventory builds ahead of 2026.
China
Ningbo battery separator producers absorb expanding melt-blown capacity for sub-ten-micrometer specifications. Dual carbon goals under MEE oversight force producers to document lifecycle emissions in supply chains. Domestic cell manufacturers specify electrospun non-woven architectures from integrated Korean and Chinese suppliers.
Japan
Palladium-coated metal fiber diffusers for proton exchange membrane electrolyzers show near-zero supplier penetration outside domestic producers. METI industrial policy supports hydrogen infrastructure filtration development. Precision stainless fiber output serves consumer electronics electromagnetic shielding for regional OEMs.
South Korea
Cell manufacturers specify electrospun separator architectures with tortuosity control and electrolyte wicking performance. MFDS battery safety standards redefine acceptable conductivity specifications for separator materials. Seoul-based electronics OEMs maintain demand for precision fiber in electromagnetic shielding applications.
Global Metal Fiber Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with equipment-integrated producers capturing premium margin pools while commodity spinners face margin compression. The vendor base concentrates among fewer than six specialized machinery builders globally, creating capacity bottlenecks that favor long-term contracting. Two archetypes dominate: integrated producers with captive polymer-to-metal conversion, and regional specialists leveraging localized regulatory compliance. Competitive moves center on backward integration into feedstock supply and geographic expansion through joint ventures in battery manufacturing clusters.
Among European-based fabricators, N.V. Bekaert S.A. and BinNova Metal Fiber Technology GmbH occupy positions anchored to filtration and shielding applications. Nippon Seisen Co., Ltd. represents the Asian precision specialist archetype. IntraMicron, Inc. exemplifies the micro-diameter capability tier that sustains premium positioning across battery separator segments.
| Leading Market Players |
|---|
| N.V. Bekaert S.A |
| Fibrometals SRL |
| Nippon Seisen Co., Ltd |
| Addas Group |
| Green Steel Group |
| IntraMicron, Inc. |
| Guven Metal |
| BinNova Metal Fiber Technology GmbH |
| MBC Metal Limited |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon border adjustment mechanisms gate qualified supply access and premium-tier pricing power for metal fiber producers serving European filtration OEMs. German pharmaceutical and specialty chemical processors now require supplier-specific Environmental Product Declarations certified under EN 15804, shifting procurement preference toward domestic melt-blown capacity with documented grid-decarbonized electricity inputs and compressing margins for conventional drawn fiber imports lacking verified low-carbon process documentation.
Pricing Analysis
Eighteen-month lead times for precision metal fiber drawing equipment create acute premium pricing for short-lead-time delivery contracts, while spot inventory of standard-grade stainless fiber trades at discount to long-term offtake agreements. Three-tier pricing structure across aerospace-qualified, battery-grade, and industrial filtration tiers reflects certification burden and diameter consistency requirements. Cost compression in commodity stainless spun fiber intensifies because Indonesian nickel ore export restrictions feed raw material volatility. Construction sector buyers show highest price sensitivity, while NASA and ESA thermal protection programs accept premium positioning for titanium fiber matrices with sub-five-micrometer consistency.
Supply Chain Analysis
Titanium sponge feedstock rests on Russian and Ukrainian vacuum arc remelt capacity plus Japanese and Chinese sponge producers, creating concentrated upstream dependency for aerospace-grade fiber specifications. Nickel cathode draws from Indonesian laterite processing and Canadian sulfide mining, while precision drawing machinery hinges on German and Japanese specialized equipment builders. Single-source vulnerability runs through the machinery layer where fewer than six global builders control precision attenuation technology. Distribution runs through direct long-term supply agreements in defense and battery verticals, bypassing traditional distributor intermediaries in California, Texas, and Ningbo manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metal fiber production is becoming a vertical-integration race where captive polymer-to-metal conversion capability separates premium margin capture from commodity margin compression. Control over melt-blown equipment design and grid-decarbonized electricity sourcing represents the decisive upstream lever incumbents and challengers alike are pursuing.
For Market Incumbents: Deploy captive machinery engineering teams to reduce eighteen-month equipment lead times and lock in capacity expansion ahead of competitor ordering cycles. Deepen backward integration into vacuum arc remelt titanium sponge supply through offtake agreements with Ukrainian and Japanese feedstock producers, insulating against Russian supply disruption. Polyimide and aramid fiber substitution from Teijin and DuPont threatens cost-sensitive filtration applications below 200°C thresholds.
For New Entrants and Emerging Players: Electrospun non-woven architectures for solid-state battery separators offer the most penetrable white-space target, as Korean and Chinese cell manufacturers specify tortuosity-controlled structures with limited qualified supplier penetration outside integrated incumbents. Hydrogen infrastructure filtration for proton exchange membrane electrolyzers presents near-zero current competition in palladium-coated metal fiber diffusers outside Japanese domestic supply. Pursue joint venture structures with Gujarat and Tamil Nadu PLI scheme beneficiaries to localize separator production for Indian battery cell manufacturing.
For Investors and Strategic Acquirers: Long-term offtake contracting volume from California defense contractors and Texas solid-state battery startups is the leading indicator that titanium and nickel fiber supply streams are consolidating toward direct manufacturer relationships. Five-to-ten-year viability favors equipment-integrated producers with in-house polymer-to-metal conversion and verified low-carbon process documentation. Watch for FAA-EASA-CAAC concurrent qualification completion as the signal that new alloy formulations have cleared commercialization barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Sponge Supply | Secures vacuum arc remelt feedstock against Russian disruption for aerospace thermal protection programs. |
| Melt-Blown Capacity Expansion in Grid-Decarbonized Zones | Captures EU Green Deal procurement preference under carbon border adjustment mechanisms for German filtration OEMs. |
| Joint Venture Localization in Indian PLI Corridors | Positions separator supply within Gujarat and Tamil Nadu battery cell manufacturing clusters. |
| Multi-Jurisdiction Certification Investment | Accelerates FAA-EASA-CAAC concurrent qualification to reduce eighteen-to-twenty-four month commercialization timelines. |
| Electrospinning Technology Acquisition | Consolidates polymer-to-metal conversion capability for Korean and Chinese cell manufacturer specifications. |
Research Methodology
SEC 10-K filings, ECHA REACH registration databases, and customs trade records formed the secondary backbone for capacity and trade flow analysis. Primary interviews with melt-blown production engineers, aerospace procurement managers at California defense contractors, filtration system builders in Ludwigshafen, and battery separator technical directors in Ningbo validated process economics and specification evolution. Bottom-up capacity modeling triangulated against top-down end-use demand aggregation across aerospace thermal protection, battery separator, and pharmaceutical filtration applications.
Historical trendline analysis of titanium sponge and nickel cathode pricing fed raw material cost projections across the modeling period. Segmentation dimensions included product type, production technology, application, and end-user vertical with regional production hub differentiation. CAGRs derived from slope analysis of fitted trendlines adjusted for regulatory inflection points including REACH compliance deadlines and EU Green Deal implementation phases. Forecast inputs incorporated machinery lead time constraints and concurrent certification timeline assumptions.
Several conditions sit outside the modeled scope, including unannounced Indonesian ore export policy shifts, sudden Russian titanium sponge supply suspension, and breakthrough polymer fiber temperature performance advances. Forecasts reflect documented assumptions about regulatory enforcement timelines and machinery delivery schedules. Supply disruption in precision drawing equipment, feedstock price spikes, and faster-than-expected solid-state battery commercialization warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
North America Nanofiber Market
Fibers
Micro-Fibrillated Cellulose Market
Fibers
Renewable Carbon Fibers Market
Fibers
North America Optical Fiber Raw Material Market
Fibers
Polycrystalline Alumina Fiber Market
Fibers
Global R-Glass Fiber Market
Fibers
Fiber Intermediates Market
Fibers
Polytetrahydrofuran Market
Fibers
Global Concrete Fiber Market
Fibers
Global Nylon Monofilament Market
Fibers
High Performance Fibers for Defense Market
Fibers
Europe Carbon Fiber Market
Fibers
Pitch-Based Carbon Fiber Market
Fibers
Global Electronic Fiberglass Market
Fibers
Citrus Pulp Fiber Market