
 Asia-Pacific Insoluble Dietary Fibers Market | 2026-2036
Asia-Pacific Insoluble Dietary Fibers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Insoluble Dietary Fibers Market Outlook
Subscription-based technical support for fiber fortification formulations is realigning how ingredient suppliers engage food manufacturers in the Asia-Pacific region. Cargill Incorporated leverages its regional grain procurement networks to secure consistent wheat fiber supply chains across multiple countries. J Rettenmaier & Sohne GmbH & Co KG anchors its position through specialized cellulose grades tailored to Asian bakery processing conditions. Ingredion Incorporated competes by extending modified corn fiber solutions that address texture challenges in reduced-calorie applications.
Insoluble dietary fibers are non-digestible carbohydrate polymers that resist hydrolysis by human digestive enzymes, typically retaining structural integrity through the gastrointestinal tract and adding bulk to food matrices. Cellulose derived from plant cell walls functions as a zero-calorie bulking agent with water-binding capacity exceeding five times its dry weight in many commercial grades. Wheat fiber dominates volume flows in the Asia-Pacific bakery segment due to cost positioning and clean-label compatibility with traditional Asian flatbreads. Psyllium husk commands premium positioning within dietary supplements as consumers in Japan and South Korea associate it with clinically validated cholesterol management protocols.
FSSAI in India mandates quantitative fiber disclosure on packaged foods, creating compliance-driven demand for standardized analytical certification from ingredient suppliers. Japan's Ministry of Health, Labour and Welfare maintains strict FOSHU approval pathways that filter which insoluble fiber claims achieve permitted health statements on finished products. China's National Health Commission periodically updates permitted food additive categories, affecting which fiber sources gain formulation access in domestic manufacturing. Stakeholders must monitor regulatory divergence across these three frameworks when designing pan-Asian product portfolios and certification strategies.
Market Dynamics
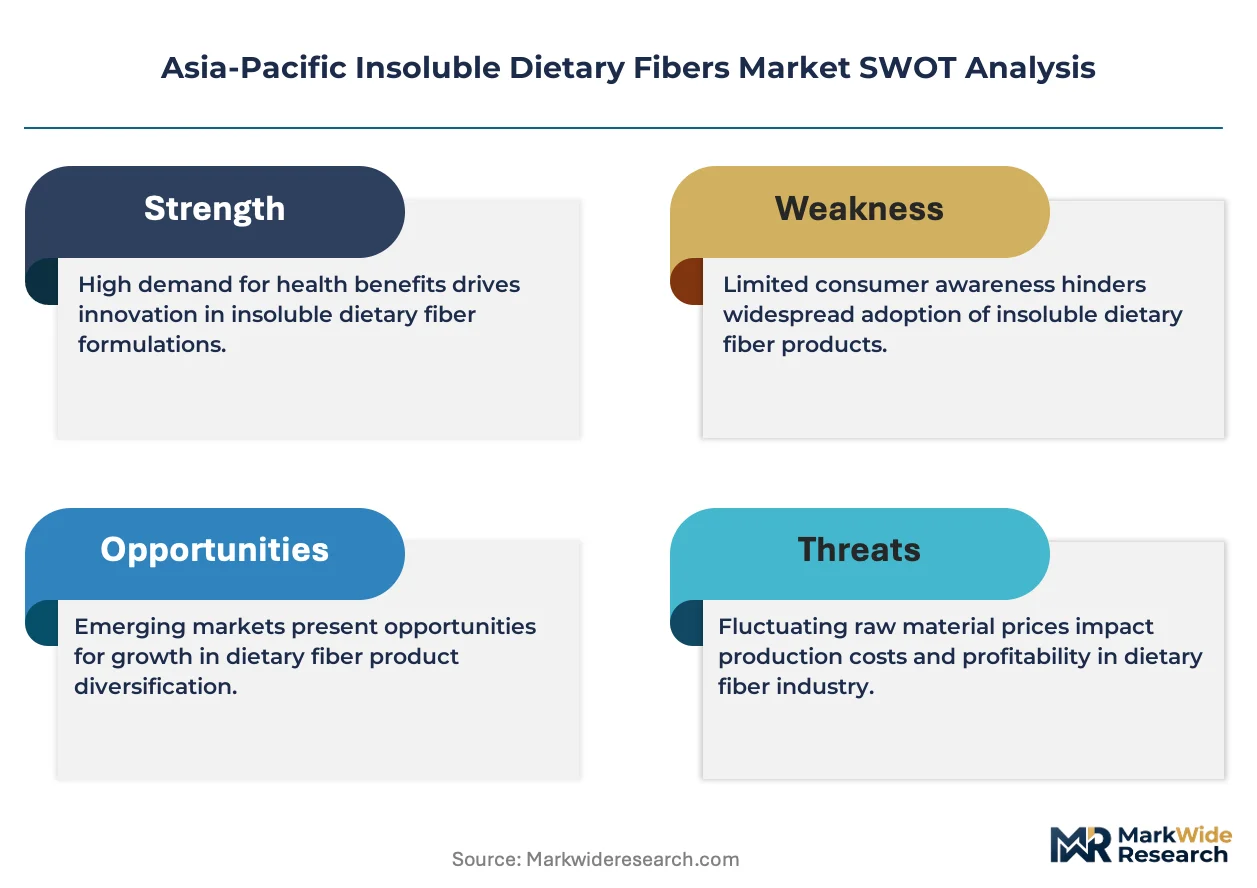
Clean-label reformulation pressure from Southeast Asian food manufacturers is restructuring procurement relationships, as buyers prioritize verified fiber sources with analytical certification over commodity-grade cellulose to meet tightening disclosure mandates from regulators in India, Japan, and China.
Growth Catalysts
- FSSAI quantitative fiber mandates:India's packaged food disclosure rules compel manufacturers to source standardized insoluble fibers with certified analytical backing, creating compliance-driven procurement volumes.
- Functional food positioning in China:Domestic brands leverage cellulose and wheat fiber for digestive health claims, expanding formulation demand beyond traditional bakery applications into beverages and snacks.
- Japanese FOSHU approval pathways:Permitted health statements on finished products filter which insoluble fiber sources achieve premium positioning in supplements and fortified foods.
Market Restraints
- Raw material cost volatility:Wheat fiber pricing fluctuates with regional grain harvests across Australia and Black Sea suppliers, compressing margins for cost-positioned bakery applications.
- Supply concentration in cellulose grades:Specialized cellulose production clusters in Germany and North America create import dependency for Asian manufacturers seeking tailored particle sizes.
- Regulatory divergence friction:Separate approval frameworks across FSSAI, Japan's Ministry of Health, Labour and Welfare, and China's National Health Commission force redundant certification spending for pan-Asian portfolios.
Strategic Opportunities
- Vietnam and Indonesia food manufacturing expansion:Emerging clean-label production hubs seek localized fiber supply partnerships to reduce import lead times and currency exposure.
- Dual carbon policy alignment in China:Agricultural residue fiber streams from wheat and rice processing gain preferential regulatory treatment as low-carbon input materials.
- Direct technical service subscriptions:Ingredient suppliers embed formulation scientists within customer R&D teams, capturing multi-year procurement commitments through joint development agreements.
Industry Challenges
- Analytical certification backlog:FSSAI-mandated fiber quantification methods create testing queue delays, extending new product launch timelines for reformulated packaged goods.
- Legacy equipment incompatibility:High-water-binding cellulose grades require extruder and mixer modifications that many mid-scale Asian bakeries have deferred.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Insoluble Dietary Fibers Market |
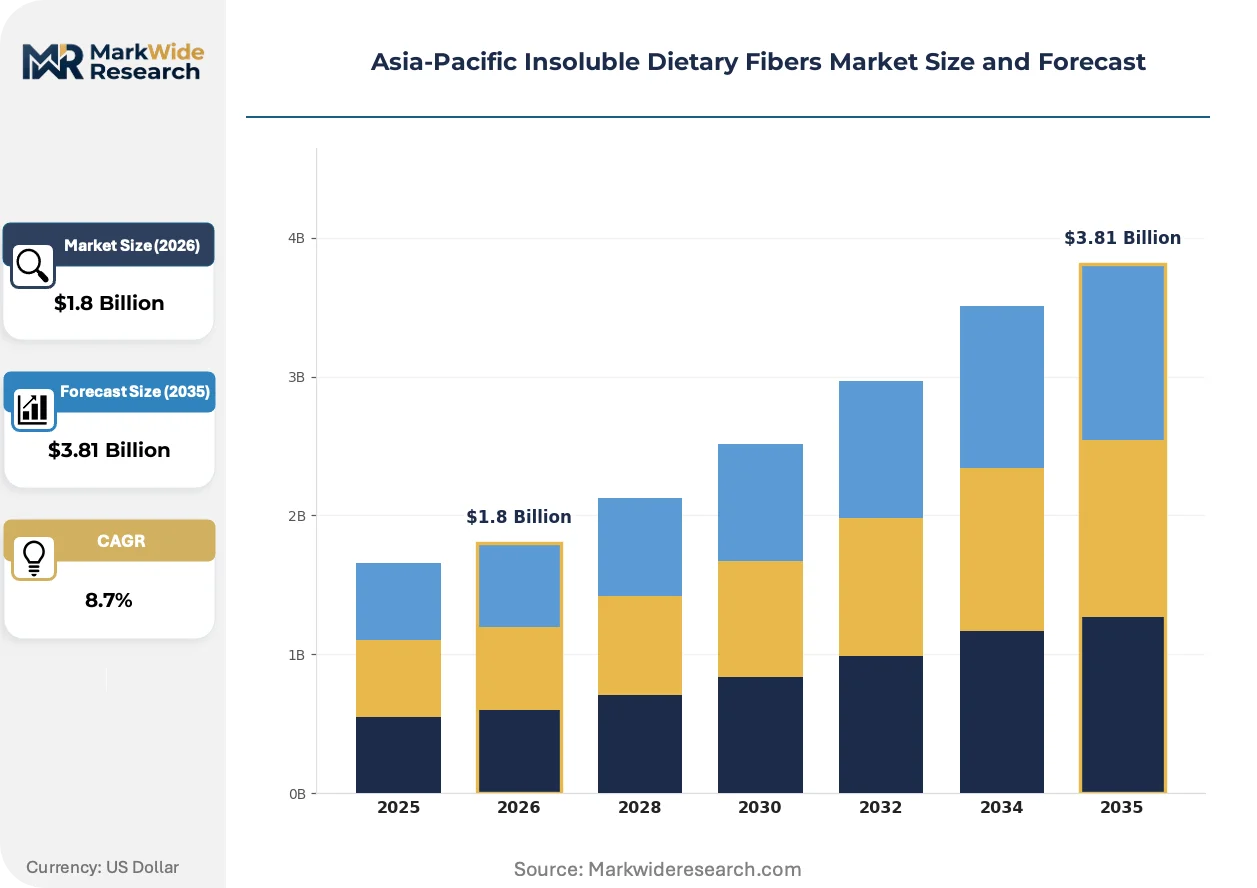
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat Fiber, Cellulose, Corn Fiber, Psyllium Husk Application: Baked Goods, Beverages, Dairy Products, Dietary Supplements End User: Food Industry, Pharmaceuticals, Nutraceuticals, Animal Feed Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Sunopta Inc, J Rettenmaier & Sohne GmbH & Co KG, Cargill Incorporated, CFF GmbH & Co KG, Grain Processing Corporation, DuPont de Nemours and Company, Ingredion Incorporated, Tate & Lyle PLC, Archer Daniels Midland Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Insoluble Dietary Fibers Market Strategic Shifts
Processing technology adaptation and regulatory certification automation are compressing product development cycles while expanding the addressable application set for insoluble fibers beyond traditional bakery matrices into beverages, meat alternatives, and nutraceutical delivery systems.
Cellulose microcrystalline grades with sub-50-micron particle distribution are converging with high-shear beverage processing lines, enabling suspension stability in functional drinks that previously excluded insoluble fibers. Japanese and South Korean beverage manufacturers pilot these grades in cholesterol-management positioned SKUs. The technology is converging with clean-label formulation requirements, collapsing the traditional trade-off between fiber fortification and visual clarity in transparent beverages.
China's National Health Commission updates to permitted food additive categories are redrawing which fiber sources gain formulation access in domestic manufacturing. Domestic brands accelerate wheat fiber and cellulose registrations ahead of anticipated category expansions. Supplement and functional food segments face the steepest compliance recalibration as historical approvals require renewal under tightened safety documentation standards.
Subscription-based technical support models are displacing transactional ingredient sales across Southeast Asian food manufacturers. Procurement teams lock multi-year fiber supply agreements that bundle formulation troubleshooting, analytical certification management, and regulatory filing assistance. Thailand and Vietnam-based clean-label startups represent the fastest adopters, trading volume discounts for embedded supplier expertise.
Asia-Pacific Insoluble Dietary Fibers Market Segmentation
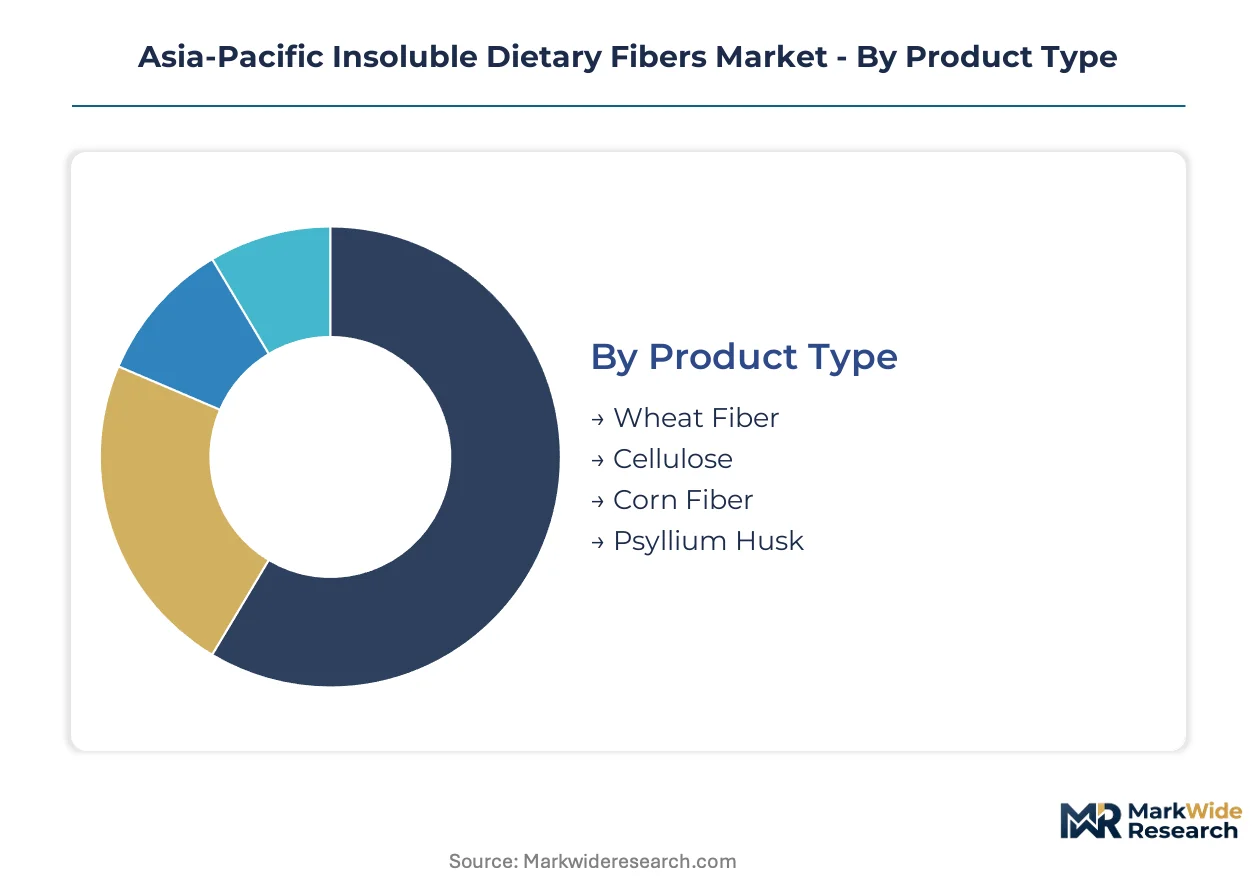
Insoluble dietary fiber suppliers structure portfolios around four intersecting dimensions that determine formulation compatibility, regulatory pathway complexity, and margin capture. Product type and application segmentation reveal where technical service investments yield sticky procurement relationships versus transactional commodity sales.
Product Type:
Cellulose grades function as embedded systems requiring processing equipment alignment, while wheat fiber operates in standalone fortification with minimal line modification.
- Cellulose:Microcrystalline cellulose derived from plant cell walls delivers zero-calorie bulking with water-binding capacity exceeding five times dry weight. Chinese functional food manufacturers source sub-50-micron grades for beverage suspension stability, though high-shear processing requirements limit adoption among mid-scale bakeries.
- Wheat Fiber:Milled from wheat bran with cost positioning 40-60% below specialty cellulose grades, this source dominates Asia-Pacific bakery volumes through clean-label compatibility with traditional flatbreads. India's FSSAI quantitative disclosure mandates have intensified procurement focus on standardized analytical certification for this commodity-adjacent segment.
- Corn Fiber:Modified corn fiber addresses texture challenges in reduced-calorie applications through Ingredion's regional formulation partnerships.
- Psyllium Husk:Commands premium positioning in Japanese and South Korean supplements with clinically validated cholesterol management associations.
Wheat fiber leads volumes today; cellulose is gaining share fastest through beverage processing convergence.
Application:
Segmentation by end-use separates high-volume bakery fortification from emerging beverage and nutraceutical formats demanding technical co-development.
- Baked Goods:Wheat fiber incorporation into Asian flatbreads, steamed buns, and crackers represents the largest addressable volume pool. FSSAI-mandated fiber disclosure has shifted procurement toward verified suppliers with ISO-standardized analytical protocols.
- Beverages:Cellulose microcrystalline grades with sub-50-micron particle distribution enable fiber fortification in transparent functional drinks without visual haze. Japanese and South Korean manufacturers pilot cholesterol-positioned SKUs where suspension stability previously excluded insoluble sources.
- Dairy Products:Texture modification requirements in yogurt and fermented milk applications favor cellulose grades with controlled water-binding profiles.
- Dietary Supplements:Psyllium husk dominates capsule and powder formats in Japan's FOSHU-approved health claims segment.
Baked goods anchor current procurement volumes; beverages show the steepest expansion trajectory as processing technology barriers fall.
End User:
Customer type segmentation distinguishes between formulation-naive commodity buyers and R&D-integrated partners seeking embedded technical support.
- Food Industry:Southeast Asian clean-label manufacturers represent the fastest-growing customer cohort, trading volume commitments for supplier-embedded formulation scientists.
- Pharmaceuticals:Excipient-grade cellulose demands meet pharmacopeial standards with batch-to-batch consistency requirements that filter supplier eligibility.
- Nutraceuticals:Japanese FOSHU pathway navigation creates premium positioning for fiber sources with permitted health claim status.
- Animal Feed:Agricultural residue fiber streams from wheat and rice processing gain traction under China's dual carbon policy alignment for low-carbon input materials.
Food industry procurement dominates transaction volumes; nutraceuticals capture the highest per-kilogram margins.
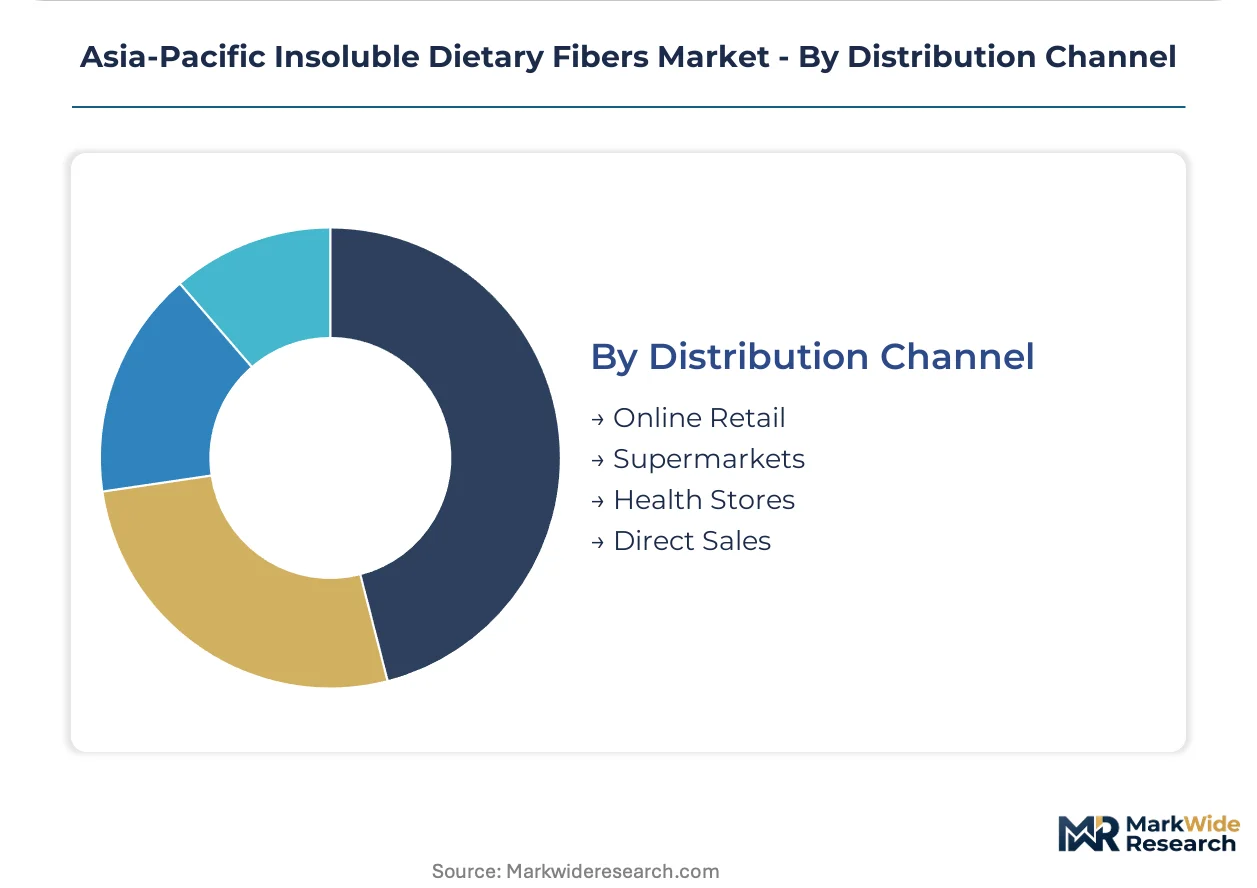
Distribution Channel:
Channel structure reflects customer scale and technical service intensity requirements across the region.
- Direct Sales:Multi-year supply agreements with bundled formulation support, analytical certification management, and regulatory filing assistance lock in Thailand and Vietnam clean-label startups.
- Online Retail:Small-batch nutraceutical and supplement manufacturers source certified fiber grades through B2B platforms with documented chain-of-custody.
- Supermarkets:Indirect procurement for mid-scale food manufacturers with established supplier relationships and lower technical service requirements.
- Health Stores:Niche channel serving specialty supplement brands with premium positioning and low volume thresholds.
Direct sales channels capture the largest contract values; online retail is expanding most quickly among emerging manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's functional food sector sources cellulose and wheat fiber at scale, while India's FSSAI disclosure mandates force procurement toward analytically certified grades. This regulatory divergence shapes distinct national demand profiles across the region.
China
Domestic brands accelerate wheat fiber and cellulose registrations ahead of National Health Commission category expansions. Dual carbon policy alignment grants preferential treatment to agricultural residue fiber streams from wheat and rice processing. Yangtze River Delta manufacturers pilot sub-50-micron cellulose grades in cholesterol-positioned functional beverages.
India
FSSAI quantitative fiber disclosure rules compel packaged food manufacturers to source standardized insoluble fibers with ISO-certified analytical backing. Wheat fiber dominates bakery fortification volumes through cost positioning compatible with traditional flatbreads. Maharashtra-based clean-label startups lock multi-year supply agreements bundling formulation support and certification management.
Japan
Ministry of Health, Labour and Welfare FOSHU approval pathways filter which insoluble fiber claims achieve permitted health statements on finished supplements. Psyllium husk commands premium positioning with clinically validated cholesterol management associations. Kanto region beverage manufacturers pilot microcrystalline cellulose grades in transparent functional drinks.
South Korea
MFDS regulatory frameworks shape fiber fortification protocols in dietary supplements and functional foods. Psyllium husk dominates capsule and powder formats with consumer associations to cardiovascular health positioning. Seoul Capital Area nutraceutical brands source certified grades through B2B platforms with documented chain-of-custody.
Vietnam
Emerging clean-label food manufacturing hubs seek localized fiber supply partnerships to reduce import lead times and currency exposure. Direct technical service subscriptions displace transactional ingredient sales among procurement teams. Ho Chi Minh City-based startups trade volume discounts for embedded supplier expertise and regulatory filing assistance.
Asia-Pacific Insoluble Dietary Fibers Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with ingredient suppliers embedding formulation scientists to capture sticky procurement relationships. The market structures around three tiers: multinational grain processors with captive fiber streams, specialized cellulose refiners with tailored particle grades, and regional distributors serving commodity bakery fortification. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players seek to secure agricultural residue supply chains and localize technical service delivery.
Within the multinational processor tier, Cargill Incorporated leverages regional grain procurement networks to anchor wheat fiber supply chains across multiple countries. J Rettenmaier & Sohne GmbH & Co KG exemplifies the specialized cellulose refiner archetype, occupying a position tied to tailored grades for Asian bakery processing conditions. Ingredion Incorporated represents the modified fiber solutions segment, sitting within the competitive set addressing texture challenges in reduced-calorie applications.
| Leading Market Players |
|---|
| Sunopta Inc |
| J Rettenmaier & Sohne GmbH & Co KG |
| Cargill Incorporated |
| CFF GmbH & Co KG |
| Grain Processing Corporation |
| DuPont de Nemours and Company |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Wheat fiber raw material costs cascade through three pricing tiers as Australian and Black Sea grain harvest volatility compresses margins for cost-positioned bakery applications while premium cellulose grades retain pricing power through specialized particle engineering.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for microcrystalline cellulose grades as domestic manufacturers achieve sub-50-micron particle distributions previously import-dependent. Three-tier pricing structure across premium, standard, and economy levels separates FOSHU-certified Japanese grades from FSSAI-compliant Indian standards and commodity wheat fiber. Cost compression in standard-tier bakery fortification intensifies because Black Sea supply disruptions feed raw material volatility. Mid-scale Southeast Asian manufacturers exhibit highest price sensitivity, while Japanese nutraceutical brands absorb premium positioning for clinically validated psyllium husk.
Supply Chain Analysis
ISO-certified analytical protocols gate supplier eligibility as FSSAI-mandated fiber quantification methods create testing queue delays extending procurement cycles. Specialized cellulose production clusters in Germany and North America supply sub-50-micron grades to Asian beverage manufacturers. Raw material streams draw from Australian wheat bran, Chinese rice processing residues, and Indian corn fiber processing. Single-source vulnerability concentrates in German cellulose refiners for tailored Asian bakery grades. Distribution runs through direct technical service subscriptions bundling formulation support and regulatory filing assistance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory compliance costs into procurement premiums as India's FSSAI quantitative disclosure mandates force reformulation toward verified fiber sources with ISO-certified analytical backing.
For Market Incumbents: Anticipate margin compression in commodity wheat fiber segments as Vietnamese and Indonesian clean-label startups negotiate volume discounts against embedded technical service subscriptions. Defend positioning through captive agricultural residue supply chains under China's dual carbon policy alignment. Prioritize certification investment in FOSHU pathway navigation for Japanese nutraceutical premium retention. For New Entrants and Emerging Players: Capture white-space in Vietnam and Indonesia localized supply partnerships where import lead times and currency exposure disadvantage distant suppliers. Ho Chi Minh City clean-label food manufacturing represents the most penetrable geography. Lead with direct technical service subscriptions displacing transactional ingredient sales among procurement teams trading volume commitments for embedded formulation scientists. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical certification backlogs extend new product launch timelines and filter supplier eligibility. Five-to-ten-year viability favors specialized cellulose refiners with tailored particle grades over commodity wheat fiber distributors. Target acquisition archetype: regional distributors with FSSAI-compliant certification infrastructure and existing Southeast Asian customer relationships. Signal to monitor: National Health Commission category expansions accelerating domestic Chinese registrations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Residue Supply | Cargill leverages regional grain procurement networks to anchor wheat fiber cost positioning across multiple countries. |
| Specialized Particle Grade Development | J Rettenmaier & Sohne occupies tailored cellulose positions for Asian bakery processing conditions requiring equipment alignment. |
| Direct Technical Service Subscription Model | Thailand and Vietnam clean-label startups lock multi-year procurement commitments through embedded formulation scientists. |
| FOSHU Approval Pathway Navigation | Premium positioning in Japanese supplements requires clinically validated fiber sources with permitted health claim status. |
| Dual Carbon Policy Alignment Certification | Chinese agricultural residue fiber streams from wheat and rice processing gain preferential regulatory treatment as low-carbon inputs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ingredient supplier technical directors, FSSAI regulatory consultants, Southeast Asian food manufacturer procurement leads, and Japanese nutraceutical formulation scientists against secondary validation from customs trade databases, National Health Commission additive category filings, FOSHU approval registries, and grain harvest reports from Australian Bureau of Agricultural and Resource Economics. Bottom-up fiber volume estimates by application and country triangulated against top-down market sizing from regional production capacity assessments.
Historical reference periods anchored the forecast window through verified shipment volumes and procurement contract values across the projection horizon. Segmentation dimensions modeled include product type, application format, end-user industry, and regulatory compliance tier. CAGRs derived from slope analysis of normalized growth trajectories against baseline penetration rates. Industry-specific forecast inputs incorporated FSSAI disclosure mandate implementation timelines and Chinese National Health Commission category expansion schedules.
Regulatory enforcement variance, raw material harvest disruption, and processing technology adoption gaps are the dominant revision risks to modeled fiber demand trajectories. Forecasts reflect documented assumptions on certification standardization and equipment upgrade cycles. A model refresh is warranted upon material change in FSSAI quantitative method adoption rates or National Health Commission permitted additive category updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Micro-Fibrillated Cellulose Market
Fibers
North America Carbon Fiber Market
Fibers
Global Metal Fiber Market
Fibers
Glass Fiber Reinforced Polymer Market
Fibers
4-Strand Fan-Shaped Strand Wire Rope Market
Fibers
Natural Fiber Reinforcement Materials Market
Fibers
Global Bicomponent Fiber Market
Fibers
Fiberglass Cloth Market
Fibers
Citrus Pulp Fiber Market
Fibers
Global Glass Fiber Reinforced Gypsum (GFRG) Market
Fibers
Sisal Market
Fibers
Continuous Fiber Thermoplastic (CFT) Market
Fibers
Europe Carbon Fiber Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Fiberglass Sunscreen Market
Fibers
Viscose Filament Yarn Market