
 Carbon Fiber in Light Weight Pressure Vessels Market | 2026-2036
Carbon Fiber in Light Weight Pressure Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber in Light Weight Pressure Vessels Market Insights
The EU Green Deal is expanding the addressable market for carbon fiber pressure vessels by tightening emissions thresholds across transport and energy storage applications. Toray Industries leverages its precursor-to-composite vertical chain to secure aerospace-grade supply contracts. Hexcel Corporation anchors North American filament winding capacity for hydrogen containment systems. SGL Carbon specializes in automotive-qualified tow products that meet NPROXX's Type 4 vessel specifications.
Carbon fiber in lightweight pressure vessels denotes filament-wound or resin-infused composite structures, typically with tensile strengths exceeding 3,500 MPa and fiber volume fractions of 60-70%, engineered to store pressurized gases at 350-700 bar in transport and stationary applications. Type 4 vessels, with all-composite construction excluding polymer liners, command the fastest growth trajectory as hydrogen fuel cell vehicle adoption accelerates. Filament winding dominates manufacturing throughput due to its proven automation and repeatability for cylindrical geometries. Aerospace end users sustain premium pricing for qualification-intensive spherical and custom shape configurations.
FDA standards govern medical oxygen containment vessels in the United States, while EPA tailpipe regulations indirectly stimulate automotive hydrogen storage demand. ECHA's REACH framework governs resin chemistry disclosure across European supply chains, affecting market access for Asian manufacturers. Japan's METI hydrogen roadmap codifies pressure vessel performance benchmarks that shape procurement criteria for export markets. Stakeholders must monitor evolving certification reciprocity between national regulators to anticipate qualification cost shifts and supply chain reconfiguration.
Market Dynamics
The EU Green Deal's F-Gas Regulation is forcing refrigerant containment system redesigns across European automotive supply chains, compressing vessel weight thresholds and accelerating carbon fiber substitution for aluminum.
Growth Catalysts
- Hydrogen mobility fleets:South Korea's metropolitan bus operators are mandating Type 4 composite vessels for 700 bar storage, creating sustained filament winding demand.
- EU F-Gas Regulation:The framework's phasedown of high-GWP refrigerants requires lighter mobile air conditioning systems, pushing automakers toward carbon fiber accumulator vessels.
- Automotive corridor concentration:Germany's Stuttgart-Munich manufacturing belt hosts integrated hydrogen fuel cell prototyping, concentrating vessel qualification programs.
Market Restraints
- Precursor supply concentration:Polyacrylonitrile fiber production clusters in Japan and China, exposing converters to freight cost volatility and currency fluctuation.
- Filament winding equipment scarcity:Automated tow placement systems for 700 bar hydrogen vessels require 18-24 month lead times from specialized machinery builders.
- Aluminum-liner hybrid competition:Type 3 vessels with metal liners retain cost advantages in stationary storage applications below 350 bar.
Strategic Opportunities
- Japan METI hydrogen roadmap:Export-oriented performance benchmarks create qualification templates for Southeast Asian vessel manufacturers seeking European market entry.
- Aerospace spherical configurations:Satellite propulsion systems require custom-wound pressure vessels with qualification premiums unattainable in cylindrical commodity production.
- Medical oxygen containment:FDA standards for portable therapeutic gas storage are tightening aluminum thickness requirements, widening carbon fiber's weight advantage.
Industry Challenges
- Filament winding technician scarcity:Automated programming for complex vessel geometries requires specialized CAD-CAM skills concentrated in aerospace supply chains.
- Multi-jurisdictional certification timelines:Reciprocity gaps between Japan's METI benchmarks and EU pressure equipment directives extend qualification cycles by 8-14 months.
- Resin chemistry disclosure:ECHA REACH compliance for epoxy and thermoplastic matrices demands supply chain documentation unfamiliar to Asian precursor suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber in Light Weight Pressure Vessels Market |
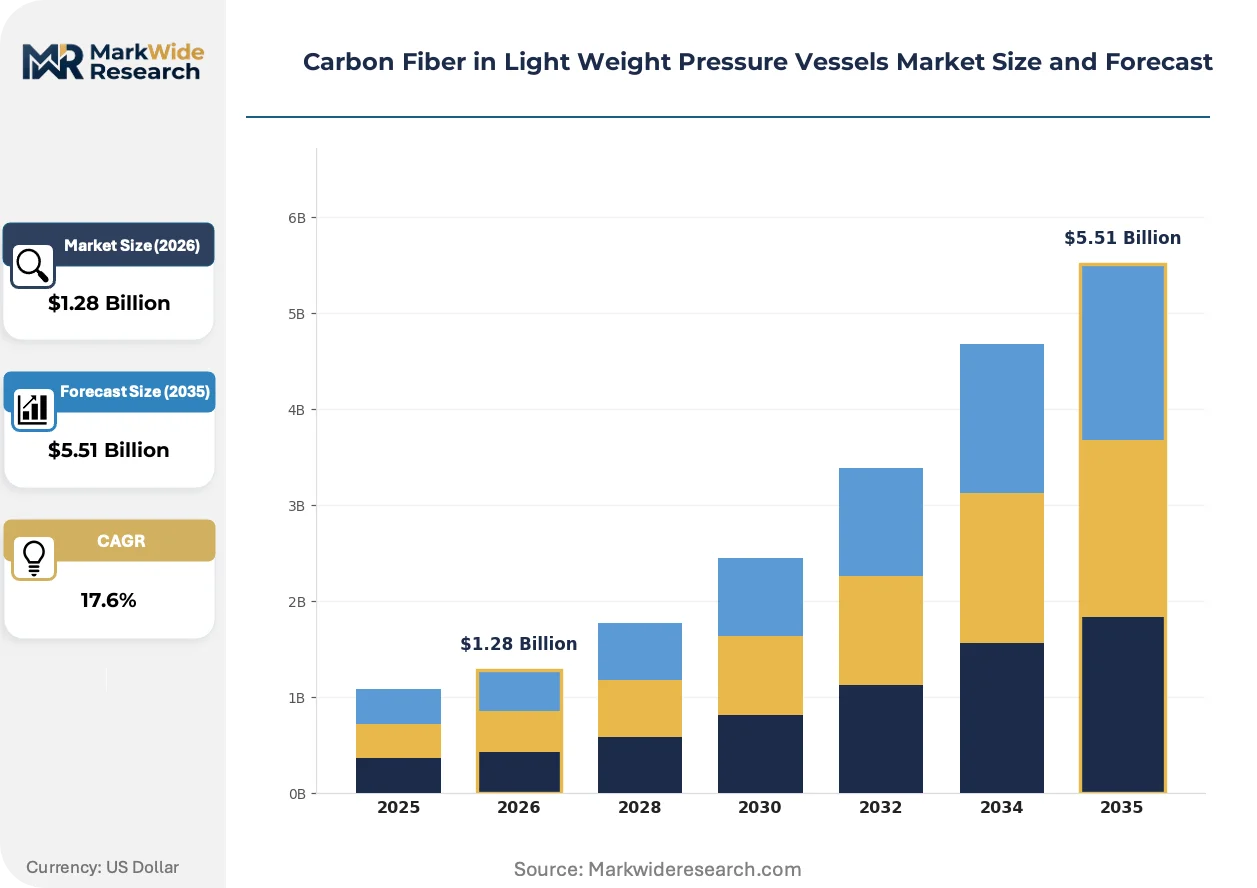
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $5.51 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Type 1 Vessels, Type 2 Vessels, Type 3 Vessels, Type 4 Vessels End User: Aerospace, Automotive, Marine, Industrial Applications Form: Cylindrical, Spherical, Conical, Custom Shapes Manufacturing Process: Filament Winding, Pultrusion, Resin Transfer Molding, Compression Molding |
| Companies Covered | Toray Industries, Inc, Teijin Limited, Hexcel Corporation, SGL Carbon, Solvay, Mitsubishi Chemical Corporation, Luxfer Group, Iljin Composites Corp, NPROXX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber in Light Weight Pressure Vessels Market Trends and Innovations
Thermoplastic resin matrices are displacing epoxies in high-cycle hydrogen applications, while automated fiber placement is compressing vessel-to-vessel variability. Digital twin verification is shortening prototype validation timelines.
Filament winding automation is decentralizing production location decisions for Type 4 hydrogen vessels. Tier-1 suppliers in Germany and South Korea are deploying robotic tow placement cells that reduce labor content per vessel by half. This technology is decentralizing manufacturing from precursor-producing regions to end-use assembly corridors, compressing logistics costs and customs exposure.
The EU F-Gas Regulation's 2024 service ban on high-GWP refrigerants is accelerating mobile air conditioning system redesigns. Automotive thermal management suppliers must demonstrate 40% weight reduction in accumulator vessels to maintain fleet CO2 compliance. German OEMs are responding with integrated carbon fiber vessel procurement specifications that bundle refrigerant containment with hydrogen storage contracts.
Buyers are consolidating vessel procurement around dual-certified suppliers capable of serving both hydrogen mobility and industrial gas containment. Korean hydrogen fleet operators now require ISO 19881 certification alongside KGS approval, compressing the qualified vendor base. This consolidation is most visible in Seoul's metropolitan bus tendering, where three-vessel package awards have replaced single-vessel spot purchasing.
Carbon Fiber in Light Weight Pressure Vessels Market Segmentation
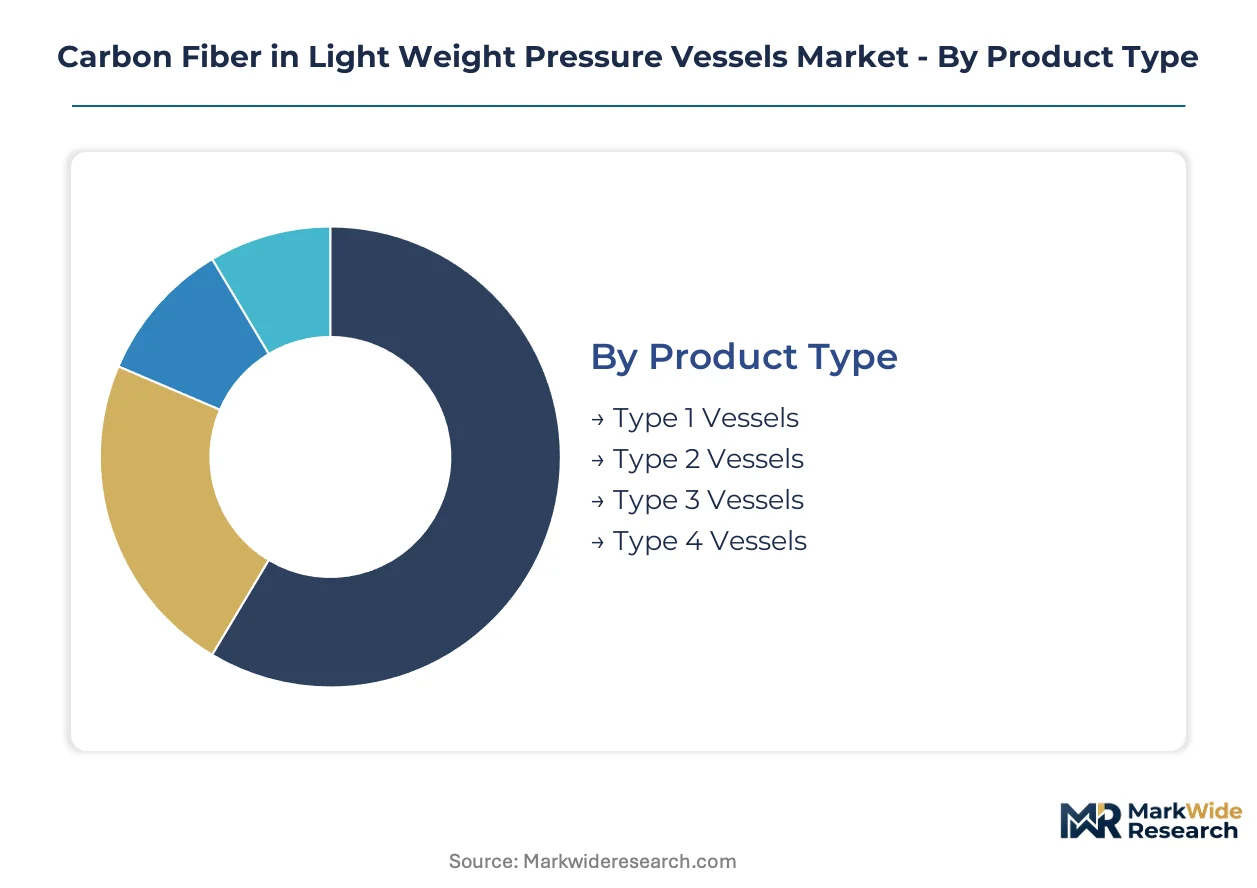
Vessel classification, end-use requirements, and manufacturing economics create distinct commercial battlegrounds across this market. Each segment carries unique certification burdens and margin profiles that reshape supplier positioning.
Product Type:
Volume applications favor metal-composite hybrids while premium hydrogen storage demands all-composite construction.
- Type 4 Vessels:All-composite construction with polymer liners eliminates metallic corrosion risk in 700 bar hydrogen service. South Korea's metropolitan bus fleets are mandating Type 4 specifications, compressing qualification timelines for domestic vessel manufacturers.
- Type 3 Vessels:Aluminum-lined hybrid designs retain cost advantages in stationary storage below 350 bar. German automotive suppliers specify Type 3 for prototype fuel cell testing where cycle frequency remains moderate.
- Type 1 Vessels:All-metal construction serves legacy industrial gas containment with minimal carbon fiber penetration.
- Type 2 Vessels:Glass fiber hoop-wrapped metal cylinders occupy mid-pressure medical and beverage applications.
Today's leader: Type 3 Vessels. Tomorrow's challenger: Type 4 Vessels.
End User:
Application-specific certification regimes fragment procurement patterns across mobility, industrial, and aerospace verticals.
- Automotive:Hydrogen fuel cell vehicle programs in Germany's Stuttgart-Munich corridor drive filament winding capacity expansion. EU F-Gas Regulation compliance now bundles refrigerant containment with hydrogen storage procurement.
- Aerospace:Satellite propulsion and crewed spacecraft demand spherical configurations with qualification premiums unattainable in cylindrical commodity production. NASA and ESA material specifications govern fiber selection and tow placement protocols.
- Industrial Applications:Stationary gas storage and process equipment favor Type 3 vessels for cost-sensitive bulk containment.
- Marine:Submersible and offshore platform applications require corrosion-resistant liners with composite overwrap for deep-pressure service.
Automotive procurement volumes dominate current filament winding throughput. Aerospace qualification premiums define margin ceilings.
Form:
Geometry determines automation feasibility and labor content per vessel.
- Cylindrical:Dominates hydrogen mobility and industrial gas storage with proven filament winding automation. Seoul's bus fleet operators specify 320-400 liter cylindrical vessels for 700 bar service.
- Spherical:Satellite propulsion systems require custom-wound configurations with volume optimization for launch vehicle payload constraints.
- Conical:Aerospace pressure vessels with integrated structural mounting points demand specialized mandrel designs.
- Custom Shapes:Medical oxygen containment and confined-space industrial applications drive non-standard geometry demand.
Cylindrical forms capture production economies. Spherical vessels command qualification premiums.
Manufacturing Process:
Process selection balances automation investment against part complexity and volume requirements.
- Filament Winding:Proven automation and repeatability for cylindrical geometries dominate Type 4 hydrogen vessel production. Korean and German tier-1 suppliers deploy robotic tow placement cells that halve labor content per vessel.
- Resin Transfer Molding:Complex geometries with integrated fittings favor closed-mold infusion for aerospace and medical applications.
- Pultrusion:Continuous profile production serves structural reinforcement rather than pressure containment directly.
- Compression Molding:Thermoplastic matrix processing enables high-cycle hydrogen applications with reduced cure times.
Filament winding anchors hydrogen mobility supply chains. Resin transfer molding serves qualification-intensive aerospace programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Filament winding technicians cluster in Germany's automotive corridor and South Korea's hydrogen valleys, anchoring regional production capacity. Toray Industries draws precursor-to-composite talent from Japan's polymer belt. Hexcel Corporation sources aerospace-qualified engineers from Utah's composites corridor.
Germany
Stuttgart-Munich automotive suppliers specify Type 4 vessels for hydrogen fuel cell prototyping. The EU Green Deal's F-Gas Regulation compresses refrigerant containment weight thresholds. Bavarian OEMs bundle carbon fiber accumulator procurement with hydrogen storage contracts.
South Korea
Seoul metropolitan bus operators mandate Type 4 composite vessels for 700 bar hydrogen service. METI hydrogen roadmap benchmarks shape domestic qualification protocols. Busan-Ulsan manufacturing belt hosts robotic tow placement cells for filament winding automation.
United States
EPA tailpipe regulations stimulate automotive hydrogen storage demand through fuel cell vehicle incentives. FDA standards govern medical oxygen containment vessel specifications. Utah's aerospace corridor sustains premium pricing for qualification-intensive spherical configurations.
Japan
METI hydrogen roadmap codifies pressure vessel performance benchmarks for export market procurement. Precursor production clusters expose converters to freight cost volatility. Nagoya-Chubu region anchors aerospace-grade carbon fiber supply chains for satellite propulsion systems.
China
Dual carbon goals accelerate hydrogen mobility fleet deployment in metropolitan transit authorities. GB standards govern pressure equipment safety requirements for domestic vessel certification. Yangtze River Delta concentration of filament winding machinery builders extends equipment lead times.
Carbon Fiber in Light Weight Pressure Vessels Market Competitive Landscape
The competitive structure tilts toward precursor-to-composite specialists with captive PAN fiber supply. Tier-1 vessel manufacturers consolidate procurement around dual-certified suppliers capable of serving hydrogen mobility and industrial gas containment. Three archetypes dominate: Japanese integrated chemical conglomerates, European automotive-qualified tow specialists, and North American aerospace-grade filament winders. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress vendor bases.
Among Japanese integrated producers, Toray Industries, Inc and Teijin Limited occupy positions defined by backward control over acrylonitrile precursor supply. Hexcel Corporation anchors North American aerospace-grade capacity. SGL Carbon exemplifies the European automotive-qualified specialization tier.
| Leading Market Players |
|---|
| Toray Industries, Inc |
| Teijin Limited |
| Hexcel Corporation |
| SGL Carbon |
| Solvay |
| Mitsubishi Chemical Corporation |
| Luxfer Group |
| Iljin Composites Corp |
| NPROXX |
| Others |
Pricing and Supply Chain Analysis
Polyacrylonitrile precursor costs cascade through three distinct pricing tiers as fiber converters pass freight volatility and currency exposure downstream to vessel manufacturers bundling hydrogen storage with refrigerant containment contracts.
Pricing Analysis
Bundled procurement of hydrogen vessels with mobile air conditioning accumulators commands premium positioning against unbundled spot purchasing for industrial gas containment. Three-tier pricing structure across aerospace-qualified, automotive-certified, and industrial-standard levels reflects certification burden and fiber grade differentiation. Cost compression in the industrial tier intensifies because aluminum-liner Type 3 hybrids retain cost advantages below 350 bar. Fleet operators in Seoul's metropolitan bus systems exhibit lowest price sensitivity due to mandated Type 4 specifications, while stationary storage buyers in China's Yangtze River Delta drive hardest bargain negotiations.
Supply Chain Analysis
Carbon fiber supply rests on Japanese and Chinese PAN precursor producers, with Toray Industries and Mitsubishi Chemical anchoring aerospace-grade output while Chinese state-backed entities feed industrial-grade volumes. Acrylonitrile monomer, specialized oxidation ovens, and automated tow placement systems constitute critical input dependencies. Single-source vulnerability concentrates in filament winding equipment builders clustered in Germany and South Korea, where 18-24 month lead times expose vessel manufacturers to capacity rationing. Distribution runs through tier-1 automotive suppliers in Stuttgart-Munich and Busan-Ulsan corridors who consolidate procurement around dual-certified vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in carbon fiber pressure vessels hinges on thermoplastic resin adoption compressing cure cycles and aerospace qualification premiums widening spreads over commodity cylindrical production.
For Market Incumbents: Acquire automated fiber placement capabilities to defend against Korean and Chinese entrants deploying robotic tow placement cells. Secure captive precursor supply through offtake agreements with Japanese PAN producers, insulating against freight cost volatility that threatens margin stability in automotive-qualified tow segments. For New Entrants and Emerging Players: Launch via qualification partnerships with Southeast Asian vessel manufacturers seeking METI benchmark alignment for European market entry. Target medical oxygen containment where FDA aluminum thickness tightening widens carbon fiber's weight advantage. Pursue spherical satellite propulsion configurations commanding premiums unattainable in cylindrical commodity production. For Investors and Strategic Acquirers: Consolidation pressure builds where filament winding technician scarcity constrains capacity expansion and dual-certification requirements compress qualified vendor bases. Five-to-ten year viability favors precursor-to-composite specialists with backward integration into acrylonitrile supply. Watch METI-EU certification reciprocity negotiations as inflection signal for qualification cost shifts and supply chain reconfiguration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PAN Precursor | Toray Industries' captive acrylonitrile supply secures aerospace-grade fiber allocation amid Japanese production concentration. |
| Filament Winding Automation Deployment | Robotic tow placement cells in Busan-Ulsan halve labor content per Type 4 vessel for Seoul's 700 bar bus fleets. |
| Thermoplastic Matrix Transition | Compression molding adoption enables high-cycle hydrogen applications with reduced cure times versus epoxy systems. |
| Dual Certification Investment | ISO 19881 plus KGS approval requirements consolidate Korean procurement around three-vessel package awards. |
| Aerospace Spherical Qualification | NASA and ESA material specifications govern custom-wound satellite propulsion vessels commanding premium positioning. |
Research Methodology
Direct dialogue with filament winding technicians, tier-1 automotive procurement managers, aerospace composite engineers, and regulatory affairs specialists at vessel certification bodies grounded qualitative assessment. Secondary validation drew from ECHA REACH filings, EPA tailpipe regulation dockets, METI hydrogen roadmap documentation, and SEC disclosures by listed precursor producers. Bottom-up vessel production estimates triangulated against top-down carbon fiber consumption forecasts by end-use application.
Bottom-up modeling aggregated country-level hydrogen fleet deployment schedules, F-Gas Regulation compliance timelines, and medical oxygen containment retrofit cycles across the analysis window. Segmentation dimensions included vessel type classification, end-use vertical, manufacturing process technology, and regional regulatory cluster. CAGRs derived from slope-log analysis of technology adoption curves and substitution elasticity between Type 3 and Type 4 constructions. Forecast inputs incorporated filament winding equipment lead time constraints and precursor capacity expansion announcements.
Several conditions sit outside the modeled scope, including geopolitical trade restrictions on carbon fiber exports, breakthroughs in solid-state hydrogen storage alternatives, and abrupt shifts in refrigerant chemistry obviating accumulator redesign. Forecasts reflect documented assumptions about certification reciprocity progression and thermoplastic resin qualification timelines. A small set of named triggers warrants ongoing watch: METI-EU directive alignment negotiations, Chinese dual carbon goal enforcement intensity, and aerospace prime contractor sourcing consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Carbon Fiber Wrap Market
Fibers
Microfibrillated Cellulose (MFC) Market
Fibers
Viscose Filament Yarn Market
Fibers
Fiberglass Cloth Market
Fibers
Global Basalt Fiber Market
Fibers
Bioglass Fiber Market
Fibers
Global Polyvinyl Alcohol Fiber Market
Fibers
Europe Carbon Fiber Market
Fibers
Asia-Pacific Optical Fiber Raw Material Market
Fibers
High Temperature Superconducting Fibers Market
Fibers
Continuous Fiber Reinforced Thermoplastic (CFR-TP) Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Asia-Pacific Nanofiber Market
Fibers
Viscose Staple Fiber Market
Fibers
Acoustical Fiber Board Market
Fibers
Short Fiber Thermoplastics Market