
 Acoustical Fiber Board Market | 2026-2036
Acoustical Fiber Board Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustical Fiber Board Market Analytics
Commercial building retrofit demand is decoupling from new construction cycles as post-pandemic workspace redesign prioritizes acoustic comfort. ROCKWOOL International leverages its mineral wool specialization to dominate specification-grade ceiling assemblies. Armstrong World Industries sustains channel control through direct contractor relationships and distributor networks across North America. Knauf Insulation anchors European project pipelines with localized manufacturing and CE-marked product portfolios.
Acoustical fiber board comprises engineered fibrous panels manufactured from mineral wool, cellulose, or synthetic polymers, typically densified to densities between 100 and 400 kg/m³ to achieve noise reduction coefficients of 0.70 to 1.05 for broadband sound absorption in built environments. Mineral wool formulations lead specification volumes for commercial suspended ceiling applications where fire resistance ratings and thermal performance compound value. Wall panel installations represent the fastest-growing installation type as open-plan offices and educational institutions deploy vertical acoustic treatments to manage reverberation without sacrificing floor area.
EPA emissions guidelines and OSHA workplace noise exposure limits shape product compliance requirements and installation standards across US commercial and industrial projects. REACH restrictions on formaldehyde-based binders and the EU F-Gas Regulation are redirecting formulation chemistry toward bio-based adhesives and low-global-warming-potential blowing agents. Stakeholders must monitor evolving green building certification thresholds as LEED v5 and BREEAM updates recalibrate material health transparency scoring.
Market Dynamics
Post-pandemic workspace redesign is decoupling acoustical fiber board demand from new construction cycles, as hybrid work models force commercial landlords to retrofit existing stock for acoustic comfort rather than waiting for greenfield projects.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:The updated Energy Performance of Buildings Directive tightens material specifications across member states, mandating lower-carbon interior finishes in commercial retrofits.
- Germany workplace noise ordinances:Federal regulations under the Arbeitsschutzgesetz compel office upgrades, concentrating specification demand in German commercial corridors.
- Mineral wool fire resistance ratings:Enhanced thermal and acoustic performance in a single panel drives substitution of legacy gypsum and synthetic alternatives in suspended ceiling assemblies.
Market Restraints
- Formaldehyde binder cost volatility:REACH restrictions on traditional adhesives force reformulation toward bio-based alternatives, compressing margin structures during transition periods.
- Raw material concentration in Nordic mineral wool supply:Basalt and slag feedstock dependence on Scandinavian smelter output creates geographic chokepoints.
- Cellulose acoustic panels:Lower-density cellulose formulations threaten mineral wool volumes in cost-sensitive educational and residential verticals where fire ratings are less critical.
Strategic Opportunities
- Wall panel vertical treatments:Open-plan offices and university learning commons deploy surface-mounted acoustic cladding to manage reverberation without sacrificing floor area.
- LEED v5 material health transparency:Updated scoring recalibrations reward products with third-party certified ingredient disclosure, favoring early movers in EPD documentation.
- Direct contractor specification channels:Bypassing traditional distributor tiers through embedded design-assist relationships captures margin and locks out competing bids.
Industry Challenges
- Acoustic engineer talent scarcity:Specialized building physics expertise required for complex reverberation modeling outpaces vocational training pipeline output.
- CE marking timeline compression:Harmonized European test protocol updates demand renewed fire reaction and sound absorption certification cycles.
- Legacy suspension system incompatibility:Existing T-bar infrastructure in 1980s-1990s commercial stock requires adapter kits or full tear-out for modern panel integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustical Fiber Board Market |
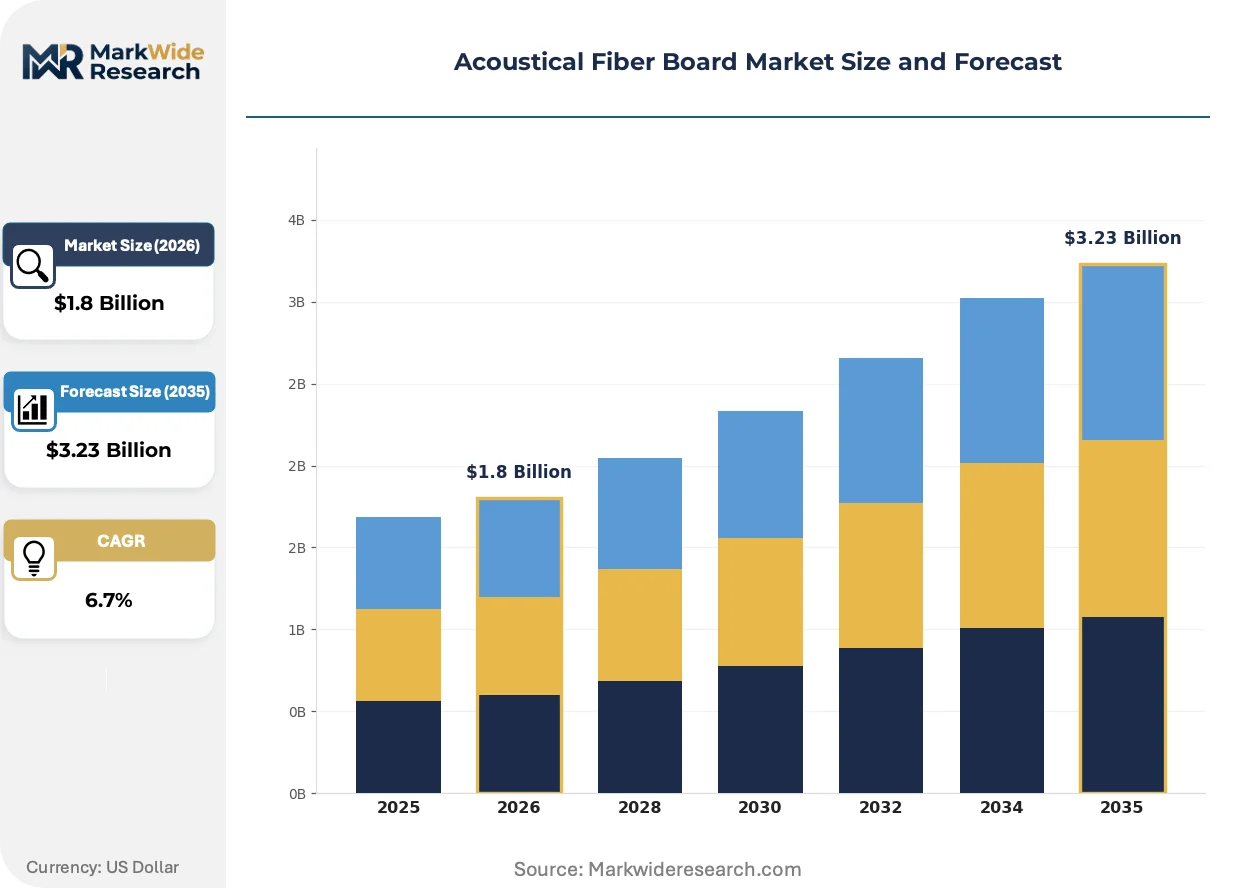
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polystyrene, Polyurethane, Mineral Wool, Cellulose End User: Residential Spaces, Commercial Buildings, Industrial Facilities, Educational Institutions Installation Type: Suspended Ceiling, Wall Panels, Acoustic Tiles, Floor Underlayment Thickness: 1 Inch, 2 Inch, 3 Inch, Others |
| Companies Covered | Armstrong World Industries, ROCKWOOL International, Compagnie de Saint-Gobain, Knauf Insulation, Owens Corning, CertainTeed Corporation, USG Corporation, Rockfon, Kingspan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustical Fiber Board Market Evolving Landscape
Bio-based binder chemistry and digital acoustic modeling are converging to reshape product formulation and specification workflows. These shifts compress development cycles while raising performance transparency expectations.
Plant-derived adhesive systems are electrifying mineral wool panel manufacturing. Commercial developers in Nordic markets specify these formulations for WELL Building Standard compliance. The technology is electrifying competitive positioning by decoupling performance from petrochemical dependence.
REACH F-Gas Regulation restrictions on synthetic blowing agents redirect European production toward water-based expansion. German and French plants retrofit lines to eliminate hydrofluorocarbon inputs. Wall panel segments absorb most compliance cost as they compete directly with imported synthetic alternatives.
Building information modeling integration now mandates acoustic performance simulation before substrate procurement. Large commercial contractors embed NRC and CAC specifications directly into digital twins. North American healthcare and education verticals lead this specification-pattern shift, compressing traditional sample-based selection cycles.
Acoustical Fiber Board Market Segmentation
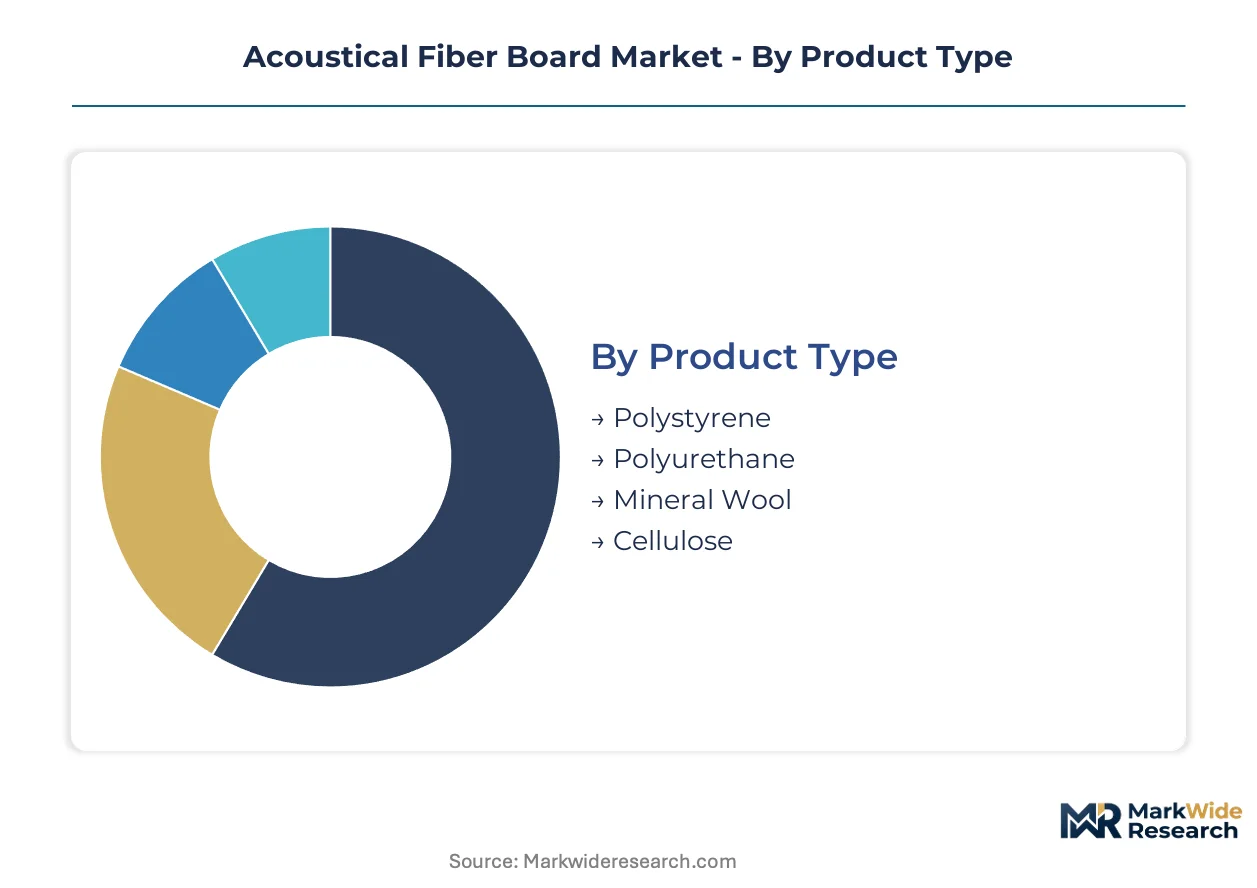
Acoustical fiber board segmentation reveals how formulation chemistry and installation geometry dictate procurement patterns across building typologies. Supply-side specialization in mineral wool and synthetic polymers creates distinct competitive arenas with divergent margin structures and specification barriers.
Product Type:
Raw material sourcing geography and energy intensity of production determine regional manufacturing footprints and cost competitiveness across formulation categories.
- Mineral Wool:Basalt and slag-based panels achieve densities of 100-400 kg/m³ with NRC ratings of 0.70-1.05. German workplace noise ordinances under the Arbeitsschutzgesetz compel specification upgrades in commercial corridors, concentrating demand in DACH region retrofit pipelines.
- Cellulose:Lower-density fibrous panels manufactured from recycled paper pulp and bio-based binders. Educational institutions in cost-sensitive markets deploy these formulations where fire resistance ratings are less critical than acoustic performance per dollar.
- Polystyrene:Expanded synthetic polymer boards with moderate sound absorption coefficients. Lightweight properties suit residential ceiling applications where structural load limits constrain substrate selection.
- Polyurethane:Closed-cell foam formulations combining thermal insulation with acoustic dampening. Industrial cold storage facilities specify these hybrid panels for dual-function envelope assemblies.
Today's leader: Mineral Wool. Tomorrow's challenger: Cellulose.
End User:
Post-pandemic occupancy patterns and regulatory compliance timelines create asynchronous demand cycles across building use categories.
- Commercial Buildings:Hybrid work models force landlords to retrofit existing stock for acoustic comfort rather than awaiting greenfield projects. Open-plan offices deploy vertical treatments to manage reverberation without sacrificing floor area.
- Educational Institutions:University learning commons and K-12 facilities prioritize speech intelligibility in active learning environments. Budget constraints favor cellulose and lower-specification mineral wool alternatives.
- Industrial Facilities:OSHA workplace noise exposure limits mandate hearing conservation programs in manufacturing plants. High-NRC ceiling assemblies reduce ambient sound levels in production areas.
- Residential Spaces:Multi-family construction and home theater installations drive demand for floor underlayment and wall panel solutions. Price sensitivity segments this category across premium and economy tiers.
Commercial Buildings anchor current volume. Educational Institutions climb the fastest as facility modernization programs accelerate.
Installation Type:
Legacy building stock constraints and spatial efficiency requirements reshape specification preferences for mounting geometry.
- Wall Panels:Surface-mounted acoustic cladding manages reverberation in open-plan offices and university commons. These installations gain share fastest as floor-area preservation becomes paramount in dense urban retrofits.
- Suspended Ceiling:T-bar grid systems dominate specification-grade commercial applications where fire resistance and thermal performance compound value. Legacy 1980s-1990s infrastructure requires adapter kits or full tear-out for modern panel integration.
- Acoustic Tiles:Modular lay-in panels for standard 600mm and 1200mm grid configurations. Healthcare and education verticals lead BIM-integrated specification patterns that compress traditional sample-based selection cycles.
- Floor Underlayment:Impact sound insulation for multi-family residential and hospitality construction. Building codes in dense urban markets mandate minimum IIC ratings for vertical noise control.
Suspended Ceiling retains specification dominance. Wall Panels represent the steepest expansion trajectory as vertical surface treatments displace ceiling-only approaches.
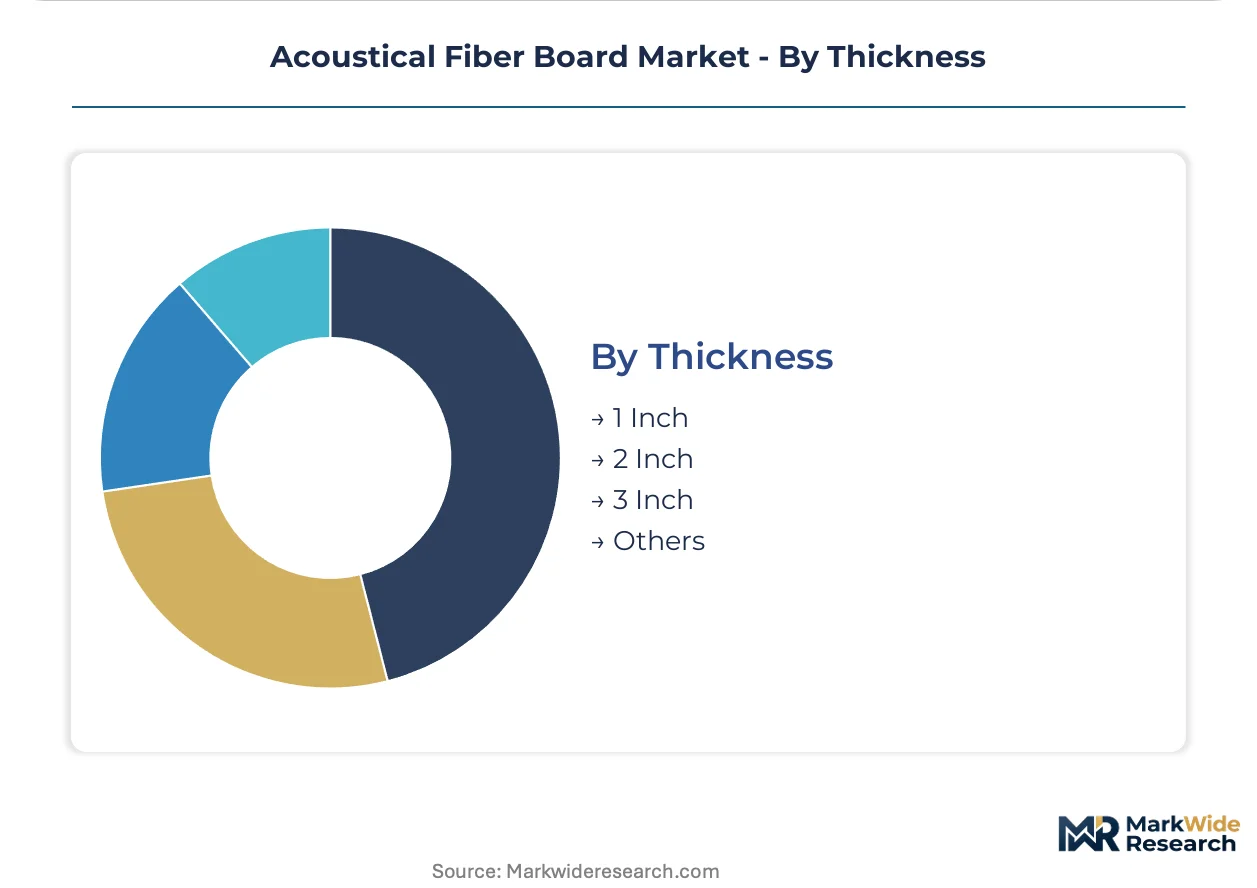
Thickness:
Acoustic performance requirements and spatial constraints create tiered specification bands with distinct manufacturing economies.
- 2 Inch:Standard commercial specification balancing NRC performance with plenum depth limitations. Most suspended ceiling assemblies specify this thickness for broadband absorption in office environments.
- 1 Inch:Space-constrained retrofits and secondary acoustic treatments where ceiling height preservation outweighs maximum absorption. Residential and light commercial applications favor this profile.
- 3 Inch:High-performance assemblies for recording studios, performance venues, and industrial noise control. Premium pricing reflects material volume and specialized edge detailing requirements.
- Others:Custom thicknesses for specialty applications including curved installations and multi-layer composite systems. Architectural acoustic consultants specify these for complex reverberation modeling projects.
2 Inch thickness commands current specification volume. 3 Inch variants gain traction in premium commercial and cultural building segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting acoustical fiber board production toward jurisdictions with lower embodied carbon compliance costs. Manufacturers relocate capacity to exploit gaps between EU Green Deal thresholds and less stringent North American building codes.
Germany
Federal workplace noise ordinances under the Arbeitsschutzgesetz compel commercial landlords to retrofit existing office stock. The updated Energy Performance of Buildings Directive tightens material specifications for interior finishes. The Rhine-Ruhr corridor concentrates specification demand as building owners modernize aging suspended ceiling infrastructure.
United States
OSHA workplace noise exposure limits mandate hearing conservation programs in manufacturing and distribution facilities. EPA emissions guidelines shape product compliance requirements for commercial and industrial projects. The Southeast construction belt from Atlanta to Charlotte drives volume as speculative office and industrial development accelerates.
China
Dual carbon goals and GB standards for green building materials redirect domestic production toward lower-emission formulations. MIIT industrial policy supports mineral wool capacity expansion for domestic infrastructure and export markets. The Yangtze River Delta manufacturing cluster integrates acoustic panel production with regional construction supply chains.
France
RE2020 environmental regulations tighten carbon thresholds for new and renovated commercial buildings. ECHA REACH restrictions on formaldehyde-based binders accelerate reformulation toward bio-based adhesive systems. The Île-de-France region anchors specification volume as Parisian office retrofits prioritize WELL Building Standard compliance.
India
Bureau of Indian Standards certification requirements for fire-resistant building materials create specification barriers for imported products. PLI scheme incentives for construction material manufacturing attract domestic capacity investment. The Delhi-NCR corridor concentrates project demand as commercial real estate development expands in Gurugram and Noida.
Acoustical Fiber Board Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-grade mineral wool panels commanding premium positioning against commodity cellulose alternatives. The vendor base organizes into three tiers: multinational building material conglomerates with integrated distribution, regional specialists with localized manufacturing footprints, and private-label fabricators serving cost-sensitive verticals. Strategic moves center on backward integration into raw mineral wool production and design-assist relationships that bypass traditional distributor channels.
Within the multinational tier, ROCKWOOL International and Armstrong World Industries exemplify divergent approaches to channel control. ROCKWOOL anchors European specification pipelines through CE-marked product portfolios and localized manufacturing in the DACH region. Armstrong sustains North American market access through direct contractor relationships and embedded distributor networks. Knauf Insulation occupies a position bridging both continents with formulation specialization in mineral wool and glass wool alternatives.
| Leading Market Players |
|---|
| Armstrong World Industries |
| ROCKWOOL International |
| Compagnie de Saint-Gobain |
| Knauf Insulation |
| Owens Corning |
| CertainTeed Corporation |
| USG Corporation |
| Rockfon |
| Kingspan Group |
| Others |
Value Network & Pricing Analysis
Acoustic engineer talent scarcity in the DACH region widens labor-cost differentials between premium specification-grade mineral wool panels and economy cellulose alternatives. REACH-driven reformulation toward bio-based binders compresses margins in mid-tier products while CE-marked assemblies command sustained premiums from German commercial landlords facing Arbeitsschutzgesetz compliance deadlines.
Pricing Analysis
Distributor margins on specification-grade mineral wool panels absorb most of the cost compression from formaldehyde binder phase-outs mandated by ECHA restrictions. Three-tier pricing structure across premium, standard, and economy levels stratifies by fire resistance certification and NRC performance rating. Pricing pressure stems from cellulose panel substitution in cost-sensitive educational verticals where fire ratings matter less. Educational institutions exhibit highest price sensitivity; healthcare and commercial office developers prioritize certified performance over unit cost.
Supply Chain Analysis
Direct-to-contractor channels handle specification-grade demand from large commercial retrofit projects in Germany and France. Basalt and slag feedstock draws from Scandinavian smelter output in Sweden, Norway, and Finland. Raw material dependencies center on mineral wool precursor supply, bio-based adhesive chemistry, and water-based blowing agents. Single-source vulnerability in Nordic basalt concentration threatens production continuity. Distribution runs through embedded design-assist relationships that bypass traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acoustical fiber board market functions as a stable compounder anchored by regulatory mandates that refresh commercial building stock on predictable cycles. EU Green Deal embodied carbon thresholds and workplace noise ordinances institutionalize replacement demand regardless of new construction volatility.
For Market Incumbents: Hedge against cellulose substitution by securing backward integration into bio-based binder production before REACH restrictions tighten further. Anchor specification pipelines through CE-marked product portfolios with third-party EPD documentation that satisfies LEED v5 transparency scoring. Mineral wool incumbents face margin erosion from lower-density cellulose competitors in educational and residential verticals where fire ratings are less critical.
For New Entrants and Emerging Players: Capture share in wall panel vertical treatments where open-plan office retrofits drive fastest-growing installation demand. Target cost-sensitive educational institutions in North America and Asia-Pacific with lower-NRC cellulose formulations that undercut mineral wool on price-per-square-meter. Pursue direct contractor specification channels through embedded design-assist relationships that lock out competing bids during early project phases.
For Investors and Strategic Acquirers: Building material conglomerates with integrated distribution networks are the most active acquirer in this space, seeking regional specialists with localized manufacturing footprints. The market offers 5-10 year viability for mineral wool specialists with captive basalt supply and CE marking capabilities. Watch for inflection in German commercial retrofit permit volumes as the dominant demand signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Binders | REACH restrictions on formaldehyde force reformulation chemistry toward plant-derived adhesive systems. |
| CE Marking Investment for EPBD Compliance | Updated Energy Performance of Buildings Directive tightens material specifications across EU member states. |
| Direct Contractor Channel Development | Embedded design-assist relationships capture margin and lock out competing bids in commercial retrofits. |
| Wall Panel Product Line Expansion | Vertical surface treatments gain share fastest as floor-area preservation drives open-plan office specifications. |
| EPD Documentation for LEED v5 | Updated scoring recalibrations reward third-party certified ingredient disclosure in green building certifications. |
Research Methodology
Bottom-up commercial building retrofit modeling reconciled against top-down mineral wool production tracking forms the analytical core of this study. Primary interviews with acoustic specification consultants, commercial contractor procurement leads, and building physics engineers inform demand-side assumptions. Secondary validation draws from ECHA REACH substance restrictions, EU EPBD directive texts, OSHA workplace noise exposure databases, and German federal workplace ordinance filings. Top-down and bottom-up estimates triangulate through cross-referencing distributor shipment data with permit-driven retrofit pipeline analysis.
Input-output matrices map raw mineral wool throughput to finished panel output across density grades and thickness specifications. Segmentation dimensions modeled include formulation chemistry, installation geometry, end-use building typology, and regional regulatory cluster. CAGRs derive from regression analysis of historical specification volumes against retrofit permit trends and embodied carbon compliance timelines. Key forecast inputs include German Arbeitsschutzgesetz enforcement intensity and REACH binder restriction implementation schedules.
Regulatory delay, bio-based adhesive cost volatility, and acoustic engineer training pipeline constraints are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions about compliance timeline adherence and substitution elasticity between mineral wool and cellulose formulations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fibers
Keratin Market
Fibers
Global Perfluorinated Type Plastic Optical Fiber Market
Fibers
Asia Pacific Ceramic Fiber Market
Fibers
Precision Fiber Molding Market
Fibers
North America Carbon Fiber Market
Fibers
Activated Carbon Fiber (ACF) Market
Fibers
Citrus Pulp Fiber Market
Fibers
Asia-Pacific Insoluble Dietary Fibers Market
Fibers
Asia-Pacific Carbon Fiber Market
Fibers
Global Fiberglass Market
Fibers
Ceramic Fiber Market
Fibers
PAN-Based Carbon Fibers Market
Fibers
North America Glass Fiber Reinforced Gypsum Market
Fibers
Triacetate Cellulose Market
Fibers
Fiberglass Cloth Market
Fibers
Fiber Metal Laminate (FML) Market