
 Abdominal Closure Systems Market | 2026-2036
Abdominal Closure Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Abdominal Closure Systems Market Outlook
The EU Medical Device Regulation (MDR) is repositioning procurement criteria across European hospital systems toward traceable, biocompatible closure materials. Johnson & Johnson leverages its broad sutures portfolio to sustain contract relationships with integrated delivery networks. Medtronic anchors its position through robotic-assisted surgical platforms that incorporate proprietary closure protocols. Baxter differentiates via advanced hemostatic adjuncts bundled with closure system workflows.
Abdominal closure systems encompass mechanical and adhesive devices engineered to restore fascial integrity following laparotomy or minimally invasive procedures, typically utilizing polypropylene, polydioxanone, or composite mesh substrates designed to withstand intra-abdominal pressures exceeding 150 mmHg while permitting tissue ingrowth. Sutures retain the largest installed base among product types due to universal compatibility across open procedures, though robotic-assisted technology represents the fastest-expanding segment as surgical suites convert to da Vinci and comparable platforms. Hospitals command the dominant end-user channel given capital requirements and sterilization infrastructure, while ambulatory surgical centers emerge as a high-velocity outlet for bariatric and aesthetic closure applications.
The FDA enforces stringent premarket notification and quality system regulation for Class II surgical mesh and suture devices, while the EU MDR mandates enhanced clinical evidence and post-market surveillance for implantable closure products. Health Canada and Japan's PMDA impose parallel biocompatibility testing protocols that manufacturers must navigate for multi-jurisdictional approval. Stakeholders must monitor evolving reimbursement thresholds for robotic-assisted closure procedures and anticipate MDR-driven consolidation among smaller mesh suppliers unable to absorb elevated clinical trial obligations.
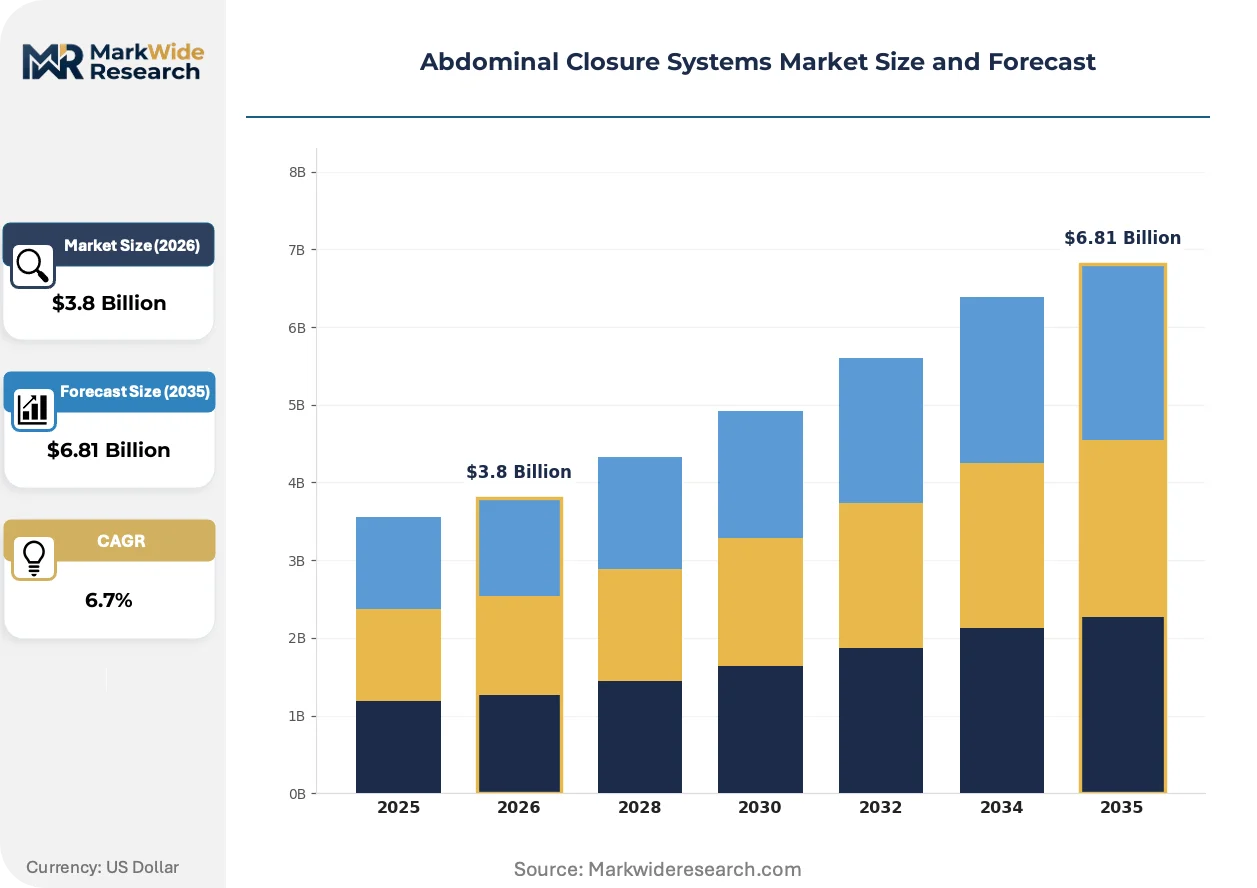
Market Dynamics
The EU MDR's enhanced clinical evidence requirements for implantable closure products are compressing supplier margins and accelerating consolidation among mesh manufacturers unable to absorb elevated post-market surveillance obligations.
Growth Catalysts
- Robotic surgical platform penetration:da Vinci system installations in US trauma centers are standardizing proprietary closure protocols that bundle sutures with robotic workflows.
- Japan PMDA pathway alignment:streamlined biocompatibility testing reciprocity with FDA 510(k) submissions is accelerating multi-jurisdictional approvals for composite mesh substrates.
- Ambulatory surgical center expansion:bariatric procedure volume in Germany and Japan is shifting same-day closure cases to outpatient settings with sterilization infrastructure.
Market Restraints
- Polypropylene raw material concentration:medical-grade polymer supply chains cluster in Texas and Rotterdam, exposing manufacturers to petrochemical price volatility.
- EU MDR clinical trial burden:implantable mesh products now require prospective clinical data that smaller suppliers cannot fund, reducing viable vendor count.
- Biologic sealant substitution:fibrin-based adjuncts from Baxter and J&J are capturing high-risk closure cases previously assigned to mechanical fixation.
Strategic Opportunities
- Underpenetrated India trauma infrastructure:government investment in tier-2 city surgical centers creates first-mover positioning for suture distributors with sterilization logistics.
- Carbon fiber-polymer composite convergence:aerospace material transfer to hernia mesh is enabling 40% tensile strength improvement over standard polypropylene.
- US CMS bundled payment expansion:episode-based reimbursement for robotic-assisted procedures incentivizes hospital IDNs to standardize on single-vendor closure systems.
Industry Challenges
- Robotic surgery technician scarcity:da Vinci console certification programs in Germany and Japan face 18-month backlogs, constraining surgical suite throughput.
- MDR technical documentation backlog:notified body capacity shortages in EU member states are extending CE mark renewal timelines to 24-36 months for legacy mesh products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abdominal Closure Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sutures, Staplers, Adhesives, Clips Application: General Surgery, Trauma Surgery, Bariatric Surgery, Aesthetic Surgery End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Technology: Manual, Automated, Robotic-Assisted, Hybrid |
| Companies Covered | Johnson & Johnson, Smith & Nephew, Medtronic, ACell Inc., Baxter, Teleflex Incorporated, B. Braun Melsungen, neoSurgical, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abdominal Closure Systems Market Strategic Shifts
Closure technology is bifurcating between premium robotic-integrated systems and cost-optimized suture platforms, with regulatory data requirements becoming the primary axis of competitive differentiation.
Absorbable polydioxanone sutures with barbed anti-slip architecture are consolidating market share in open laparotomy procedures. General surgery departments in US academic medical centers are adopting these devices at replacement rates exceeding standard braided polyester. The technology is consolidating procurement decisions around suture-vendor relationships that bundle training and sterilization validation.
EU MDR Article 10 post-market clinical follow-up mandates are reshaping evidence generation obligations for implantable mesh manufacturers. The regulation requires active surveillance registries that capture long-term adhesion and erosion outcomes. Class III mesh suppliers in Germany and France are responding by acquiring independent clinical research organizations to maintain compliance velocity.
Hospital integrated delivery networks are compressing vendor panels to single-source contracts with outcome guarantees. Ambulatory surgical centers in Japan and the United States are displacing traditional distributor relationships with direct manufacturer agreements that include consignment inventory and on-site sterilization technical support. This concentration is most visible in bariatric surgery verticals where closure material standardization reduces operative variability.
Abdominal Closure Systems Market Segmentation
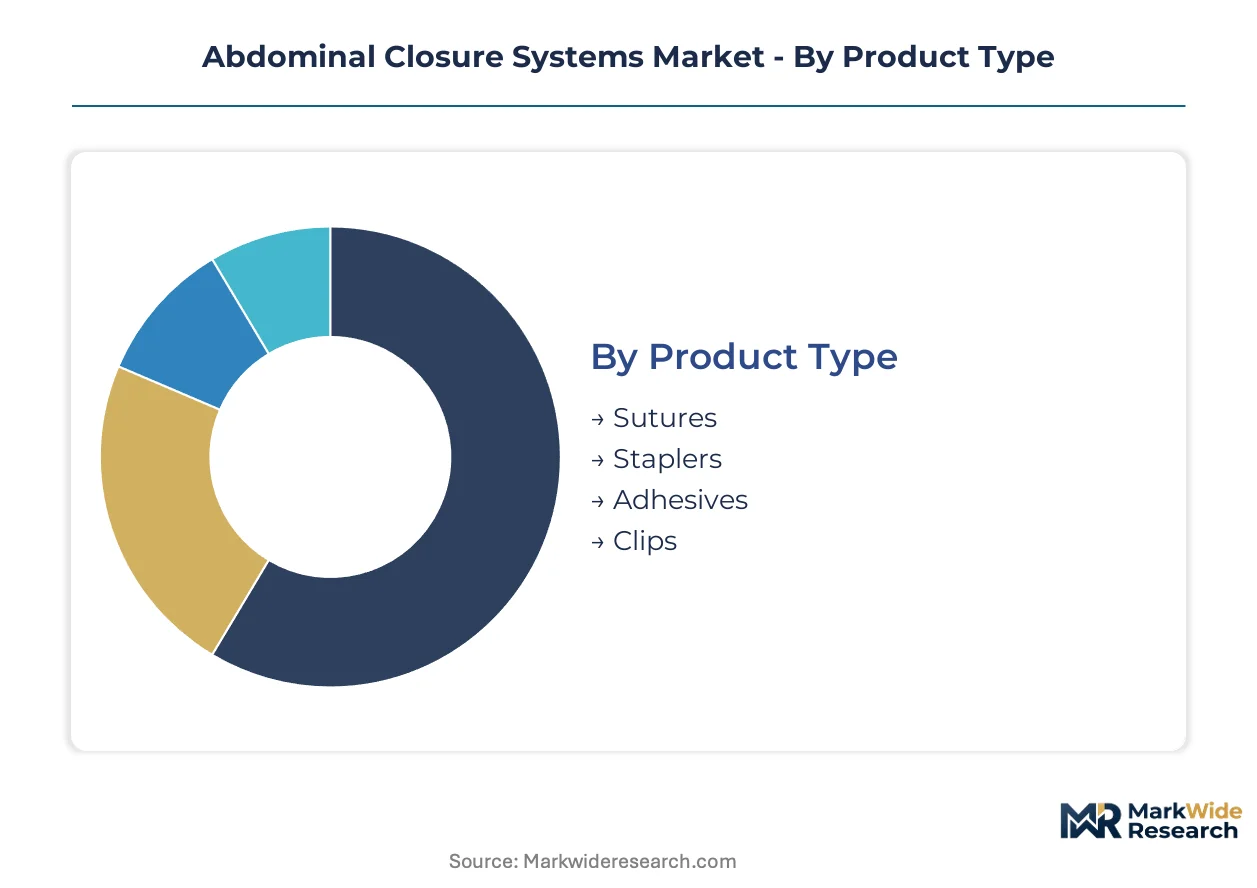
Abdominal closure systems fragment across four intersecting dimensions that determine procurement patterns and margin structures. Product type and technology choices drive capital allocation in surgical suites, while application and end-user channels dictate sterilization logistics and reimbursement pathways.
Product Type:
Supply concentration in medical-grade polymers and precision instrumentation creates divergent margin profiles across closure modalities, with polymer-based products clustering around Texas and Rotterdam feedstock hubs.
- Sutures:Braided polypropylene and polydioxanone monofilaments retain universal compatibility across open laparotomy procedures. Demand concentrates in US academic medical centers replacing standard braided polyester with barbed anti-slip architectures that reduce operative time.
- Staplers:Mechanical fixation devices utilizing titanium or absorbable polymer staples enable rapid fascial approximation in emergency trauma settings. German and Japanese trauma centers are standardizing disposable cartridge systems that integrate with robotic-assisted platforms.
- Adhesives:Cyanoacrylate and fibrin-based sealants provide adjunctive hemostasis in high-risk closure cases.
- Clips:Titanium and absorbable polymer clips offer non-penetrating fascial approximation for select hernia repairs.
Today's leader: Sutures. Tomorrow's challenger: Staplers.
Application:
Procedure volume and reimbursement intensity vary sharply across surgical specialties, with bariatric and trauma applications commanding premium pricing due to complication risk profiles.
- General Surgery:Appendectomy, colectomy, and cholecystectomy procedures generate baseline demand for standard closure protocols. US hospital integrated delivery networks are compressing vendor panels around suture-vendor relationships that bundle training and sterilization validation.
- Bariatric Surgery:Gastric bypass and sleeve gastrectomy closures face elevated fascial dehiscence risk from patient obesity and intra-abdominal pressure. Ambulatory surgical centers in Germany and Japan are displacing traditional distributor relationships with direct manufacturer agreements for same-day discharge protocols.
- Trauma Surgery:Emergency laparotomy closures require rapid, reliable fascial restoration under hemodynamic instability.
- Aesthetic Surgery:Abdominoplasty and body contouring procedures prioritize cosmetic scar outcomes.
Bariatric surgery is climbing the fastest as outpatient conversion accelerates in Germany and Japan.
End User:
Capital requirements and sterilization infrastructure create distinct procurement behaviors across facility types, with hospital systems leveraging scale for outcome-guaranteed contracts.
- Hospitals:General surgery departments in tertiary centers command the dominant channel due to robotic platform capital requirements and 24/7 sterilization infrastructure. US trauma centers with da Vinci installations are standardizing proprietary closure protocols that bundle sutures with robotic workflows.
- Ambulatory Surgical Centers:Bariatric and aesthetic closure cases are shifting to outpatient settings with dedicated sterilization technical support and consignment inventory arrangements.
- Clinics:Minor wound closure and follow-up procedures drive low-volume demand.
- Research Institutions:Preclinical and clinical trial applications support evidence generation for regulatory submissions.
Hospital procurement concentration is accelerating single-source contract consolidation with outcome guarantees.
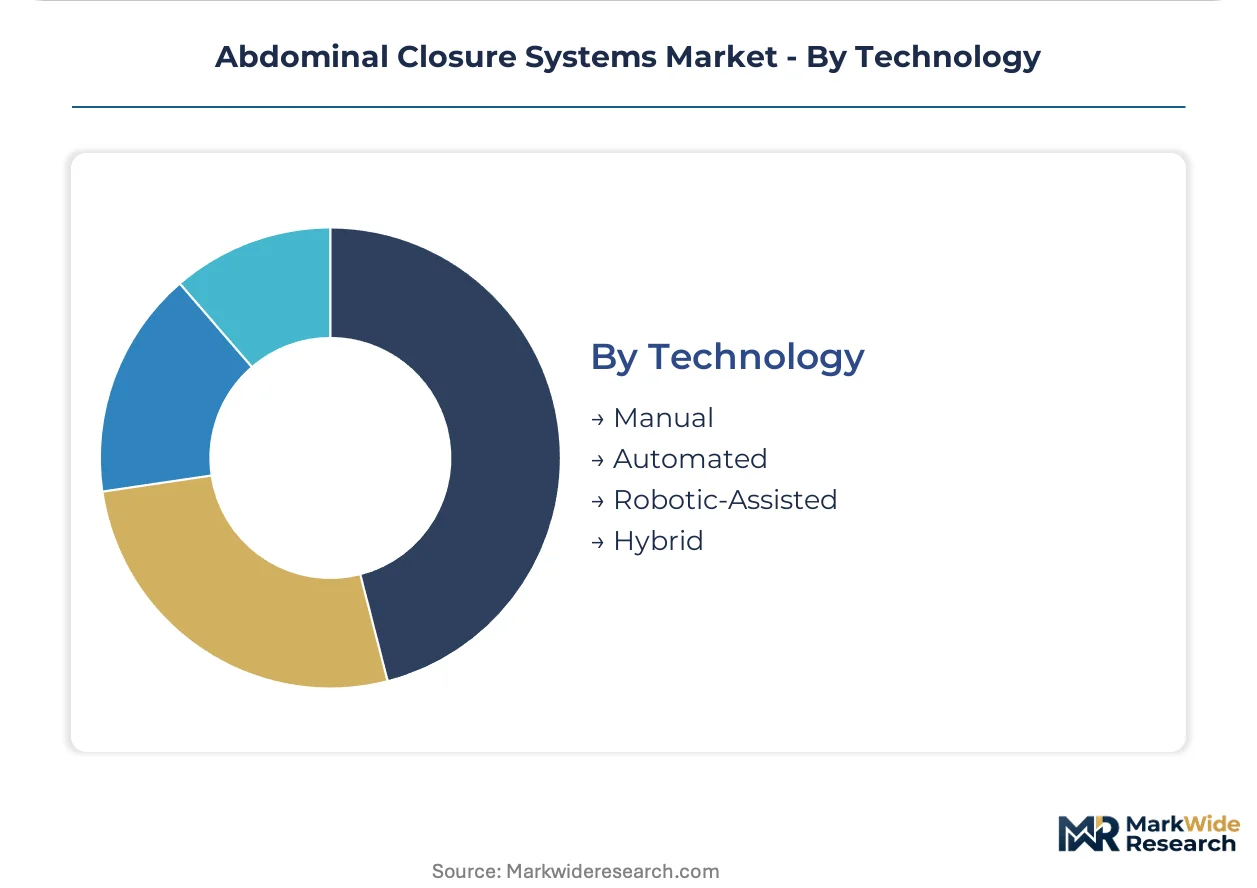
Technology:
Automation intensity determines training requirements, capital depreciation schedules, and FDA 510(k) pathway complexity for manufacturers.
- Manual:Hand-sutured closure remains the fallback protocol across all settings, requiring minimal capital investment but dependent on surgeon technique variability.
- Automated:Powered stapling and suturing devices reduce operative time in high-volume centers.
- Robotic-Assisted:da Vinci and comparable platforms incorporate proprietary closure protocols with instrument articulation and 3D visualization. FDA premarket notification requirements and da Vinci console certification backlogs in Germany and Japan are constraining surgical suite throughput expansion.
- Hybrid:Combined manual-robotic approaches optimize cost and precision in complex reconstructions.
Robotic-assisted platforms are gaining share fastest as surgical suite conversions proceed in US trauma centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Robotic surgical technicians cluster in US trauma centers, German university hospitals, and Japanese metropolitan medical districts, anchoring regional adoption velocity for advanced closure platforms.
United States
Da Vinci system installations in academic medical centers and trauma hubs drive proprietary closure protocol standardization. FDA 510(k) premarket notification requirements enforce biocompatibility validation for polypropylene mesh substrates. The Texas Medical Center in Houston and Mayo Clinic Rochester anchor multi-hospital integrated delivery networks that consolidate vendor contracts around outcome guarantees.
Germany
University hospital general surgery departments convert open laparotomy protocols to robotic-assisted workflows. EU MDR Article 10 post-market clinical follow-up mandates compress supplier margins and accelerate consolidation among mesh manufacturers. The Berlin-Brandenburg and Bavarian medical technology clusters concentrate notified body technical documentation expertise, though 24-36 month CE mark renewal backlogs constrain legacy product continuity.
Japan
PMDA pathway alignment with FDA 510(k) submissions accelerates multi-jurisdictional approvals for composite mesh substrates. Government investment in specialized trauma centers and bariatric surgery infrastructure concentrates demand in Tokyo, Osaka, and Nagoya metropolitan areas. Da Vinci console certification programs face 18-month backlogs, constraining surgical suite throughput expansion in Kanto and Kansai regions.
India
Government investment in tier-2 city surgical centers creates first-mover positioning for suture distributors with sterilization logistics capabilities. CDSCO medical device registration requirements impose parallel biocompatibility testing protocols that domestic and multinational manufacturers must navigate. The Maharashtra and Gujarat hospital networks anchor private-sector bariatric surgery volume growth.
United Kingdom
NHS integrated care systems compress vendor panels toward single-source contracts with training and sterilization validation bundles. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR clinical evidence standards for implantable mesh products. The London and Greater Manchester surgical hub networks concentrate robotic platform capital investment and specialist closure procedure volume.
Abdominal Closure Systems Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the closure systems value chain, with integrated medical device conglomerates controlling robotic platform ecosystems while specialized mesh and suture suppliers occupy component niches. The vendor base concentrates around three strategic archetypes: diversified surgical conglomerates with broad sutures portfolios, robotic platform integrators bundling proprietary closure protocols, and hemostatic adjunct specialists differentiating via workflow bundling. Consolidation accelerates through M&A among mesh manufacturers unable to absorb EU MDR clinical trial burdens, alongside strategic partnerships between suture suppliers and sterilization logistics providers.
Among diversified surgical conglomerates, Johnson & Johnson and Medtronic occupy positions anchoring contract relationships with integrated delivery networks and robotic-assisted surgical platforms respectively. Baxter sits within the hemostatic adjunct tier, exemplifying differentiation through advanced sealant workflows bundled with closure system protocols. These three entities represent the dominant competitive archetypes reshaping procurement concentration in US and European hospital systems.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Smith & Nephew |
| Medtronic |
| ACell Inc. |
| Baxter |
| Teleflex Incorporated |
| B. Braun Melsungen |
| neoSurgical |
| 3M |
| Others |
Value Chain & Pricing Dynamics
Barbed anti-slip suture architectures are compressing cost-per-procedure economics while redistributing procurement power toward vendors with sterilization validation capabilities. This technology transition simultaneously elevates training bundling requirements and concentrates buyer leverage within integrated delivery networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 510(k) clearance tier and robotic platform compatibility. Premium tiers command brand premiums from da Vinci-certified closure protocols, while standard tiers compete on volume scale with academic medical centers. Cost compression in economy sutures is intensifying because Indian and Southeast Asian manufacturers are expanding medical-grade polymer extrusion capacity. Ambulatory surgical centers exhibit highest price sensitivity; trauma centers with robotic installations show lowest sensitivity due to bundled reimbursement protocols.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for medical devices are redirecting suture sourcing toward Maharashtra and Gujarat manufacturing clusters. Medical-grade polypropylene feedstock draws from Texas and Rotterdam petrochemical hubs, with precision extrusion equipment anchored in Germany and Japan. Single-source vulnerability concentrates in medical-grade polymer resin supply, where three global suppliers control specialty-grade specifications. Distribution runs through hospital GPO contracts and direct manufacturer agreements with ambulatory surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The abdominal closure systems market functions as a regulatory compounder where EU MDR Article 10 post-market surveillance mandates are accelerating vendor consolidation and elevating compliance spending as a competitive barrier.
For Market Incumbents: Cement contract durability with integrated delivery networks by acquiring independent clinical research organizations to maintain EU MDR compliance velocity. Deepen backward integration into medical-grade polymer compounding to defend margins against petrochemical price volatility. Biologic sealant substitution from Baxter and J&J represents the primary substitution threat requiring workflow bundling countermeasures. For New Entrants and Emerging Players: Tier-2 city surgical centers in India offer the most penetrable buyer archetype for suture distributors with sterilization logistics capabilities. Carbon fiber-polymer composite mesh substrates enable differentiation through 40% tensile strength improvement claims. Direct manufacturer agreements with Japanese ambulatory surgical centers bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap mesh manufacturers facing EU MDR clinical trial funding gaps. Long-term viability favors suppliers with captive sterilization validation infrastructure and robotic platform certification pipelines. The signal to monitor is CE mark renewal timeline compression as notified body capacity constraints ease.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Article 10 compliance velocity separates viable suppliers from consolidation targets in Germany and France. |
| Hospital System Partnership | Single-source contracts with outcome guarantees lock in volume across US academic medical center networks. |
| Software Companion Development | Robotic platform integration protocols from da Vinci systems standardize closure workflows and instrument compatibility. |
| Reimbursement Strategy | CMS bundled payment alignment for robotic-assisted procedures incentivizes IDN standardization on vendor ecosystems. |
| FDA Submission | 510(k) premarket notification for barbed anti-slip suture architectures secures premium positioning in open laparotomy replacement cycles. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with general surgery department heads, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA CE marking databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis were triangulated to anchor market sizing.
Comparable historical periods anchored the projection horizon across product type, application specialty, end-user facility tier, and technology automation level segmentation dimensions. CAGRs were derived from regression analysis of installed surgical platform base expansion and procedure volume elasticity. Forecast inputs incorporated da Vinci system installation pipelines, EU MDR notified body capacity constraints, and ambulatory surgical center licensing trajectories.
Underlying measurement precision varies by segment; robotic-assisted technology carries tighter precision than manual closure due to platform-specific data availability. Forecasts reflect documented assumptions regarding regulatory timeline stability and reimbursement policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Ultrasonic Dissection Devices Market
Medical Devices
Neuro Navigation System Market
Medical Devices
Lumbar Disc Replacement Device Market
Medical Devices
Otoscope Devices Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Digital BTE Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
LAMEA External Defibrillators Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Urometer Market
Medical Devices
Kirschner Wires Market
Medical Devices
Global Anastomosis Devices Market