
 Disposable Incontinence Products (Dips) Market | 2026-2036
Disposable Incontinence Products (Dips) Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Incontinence Products (Dips) Market Outlook
Home care services are consolidating as the fastest-growing buyer channel for disposable incontinence products, pulling volume away from institutional procurement. Kimberly-Clark Corporation leverages its North American retail footprint to dominate pharmacy and supermarket shelves. Essity AB anchors European supply through specialized manufacturing scale in absorbent hygiene. Paul Hartmann AG differentiates via clinical-grade product lines tailored to nursing home specifications.
Disposable incontinence products encompass single-use absorbent garments and pads engineered with superabsorbent polymer cores, non-woven top sheets, and breathable back sheets to capture and isolate bodily fluids. These products serve medical, geriatric, and post-surgical populations requiring managed continence without laundering infrastructure. Adult diapers command the largest revenue pool due to institutional bulk purchasing, while pants-format designs capture the fastest expansion as ambulatory users prioritize discretion and self-application. Material innovation centers on SAP loading densities, where higher polymer concentrations reduce unit bulk and extend wear time between changes.
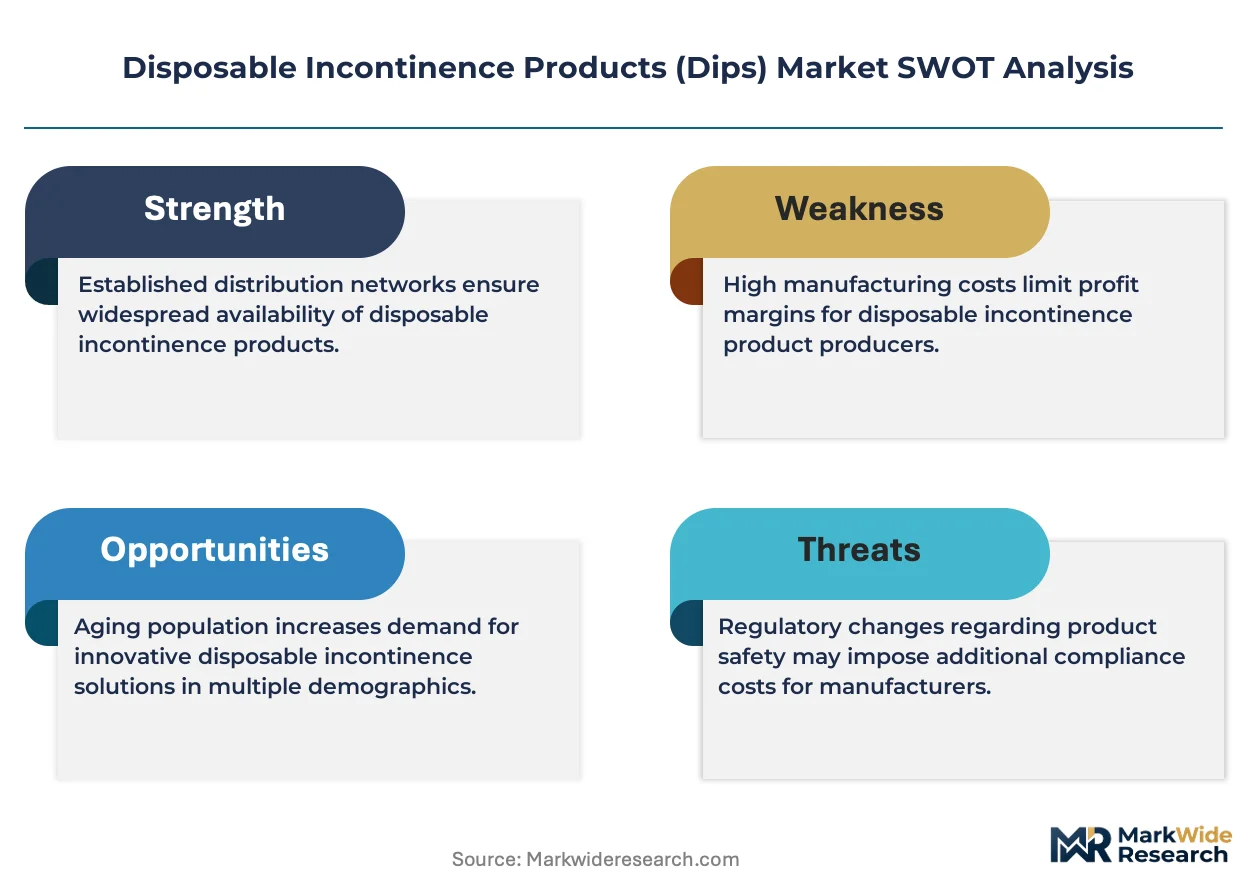
The FDA classifies absorbent incontinence products as Class I medical devices, imposing biocompatibility and labeling standards that shape U.S. market entry requirements. The EU MDR and REACH framework govern chemical safety and clinical performance claims across European markets, raising compliance costs for non-specialized suppliers. Stakeholders must monitor evolving absorbent core standards and reimbursement eligibility shifts in Medicare and national health systems to align R&D portfolios with payer-covered product tiers.
Market Dynamics
The EU Medical Device Regulation (MDR) is compressing supplier margins by mandating clinical-grade absorbency testing and biocompatibility documentation for all absorbent hygiene products entering European markets. Manufacturers lacking specialized polymer chemistry capabilities face forced exit or costly third-party certification.
Growth Catalysts
- Long-term care insurance subsidies:Germany's Pflegeversicherung covers 80-100% of product costs for eligible individuals, removing price barriers for at-home users and expanding addressable demand.
- SAP-enhanced core technology:Superabsorbent polymer loading densities above 400 g/m² now enable 12-hour wear times, reducing caregiver burden and institutional change frequency.
- Aging demographic clusters:Japan's 65+ population exceeds 29% of total residents, creating concentrated demand for discrete pants-format designs among ambulatory elderly.
Market Restraints
- Petrochemical input volatility:Polypropylene and polyethylene prices fluctuate with crude oil indices, compressing gross margins for non-integrated converters.
- REACH compliance costs:The EU's chemical registration framework requires extensive substance dossiers for SAP additives, raising fixed costs for small-batch suppliers.
- Reusable textile substitutes:Washable absorbent underwear with antimicrobial silver-ion treatments captures cost-conscious home care segments in Nordic markets.
Strategic Opportunities
- India's geriatric care gap:Only 12% of India's 100+ million elderly have access to subsidized continence products, presenting whitespace for economy-tier disposable lines.
- E-pharmacy direct channels:Platforms like DocMorris and Zur Rose enable subscription-based replenishment, bypassing pharmacy shelf-space constraints.
- Biodegradable SAP alternatives:Cellulose-based superabsorbents from agricultural waste streams align with EU Green Deal procurement mandates for public healthcare tenders.
Industry Challenges
- MDR technical documentation backlog:Notified body capacity constraints delay product recertification timelines by 14-18 months, freezing portfolio updates.
- Polymer chemistry talent scarcity:Formulation scientists with SAP rheology expertise command premium wages, limiting R&D expansion for mid-tier manufacturers.
- Legacy hospital procurement integration:ERP systems at aging care institutions resist API connectivity with automated inventory platforms, complicating just-in-time supply contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Incontinence Products (Dips) Market |
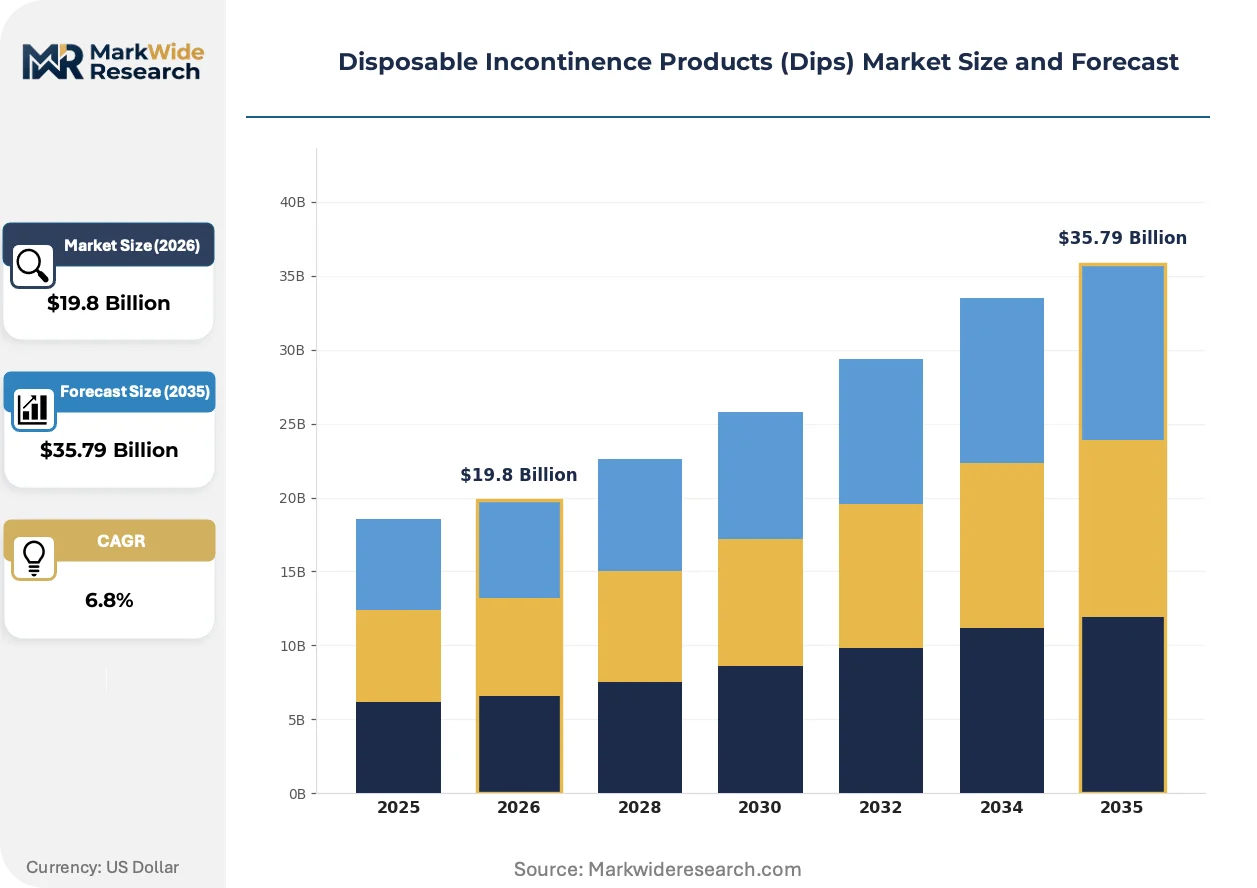
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $35.79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Diapers, Underpads, Guards, Pants End User: Hospitals, Nursing Homes, Home Care, Individual Consumers Material: Polymer, Non-Woven Fabric, Absorbent Core, SAP Distribution Channel: Online Retail, Supermarkets, Pharmacies, Direct Sales |
| Companies Covered | Essity AB, Kimberly-Clark Corporation, Procter & Gamble, Unicharm Corporation, Coloplast A/S, Ontex Group, Cardinal Health, Medline Industries, Paul Hartmann AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Incontinence Products (Dips) Market Strategic Shifts
Wetness indicator integration and skin-sensing materials are transforming product-user interaction from scheduled changes to demand-driven replacement, compressing institutional labor costs while improving dermatological outcomes.
Printed electronics embedded in breathable back sheets is decentralizing continence management by enabling real-time moisture alerts transmitted to caregiver smartphones. Nursing homes in the Netherlands and Belgium are piloting these systems at 15-20% of bed capacity. The technology is decentralizing staff allocation patterns, allowing single caregivers to monitor 30+ residents simultaneously rather than fixed 8-10 patient ratios.
REACH substance restriction proposals targeting residual acrylate monomers in SAP manufacturing are forcing reformulation investments across European supply chains. The industrial consequence is a 12-18 month product development cycle extension as suppliers validate alternative polymerization catalysts. Adult diaper lines with >60% SAP content face the steepest compliance burden, pushing manufacturers toward hybrid cellulose-SAP cores.
Subscription replenishment models are displacing pharmacy counter purchases among home care users in Germany and France. Digital platforms capture 23% of individual buyer volume, diverting traffic from retail shelves. This shift concentrates order data with e-pharmacy operators, who now negotiate directly with manufacturers for private-label supply contracts.
Disposable Incontinence Products (Dips) Market Segmentation
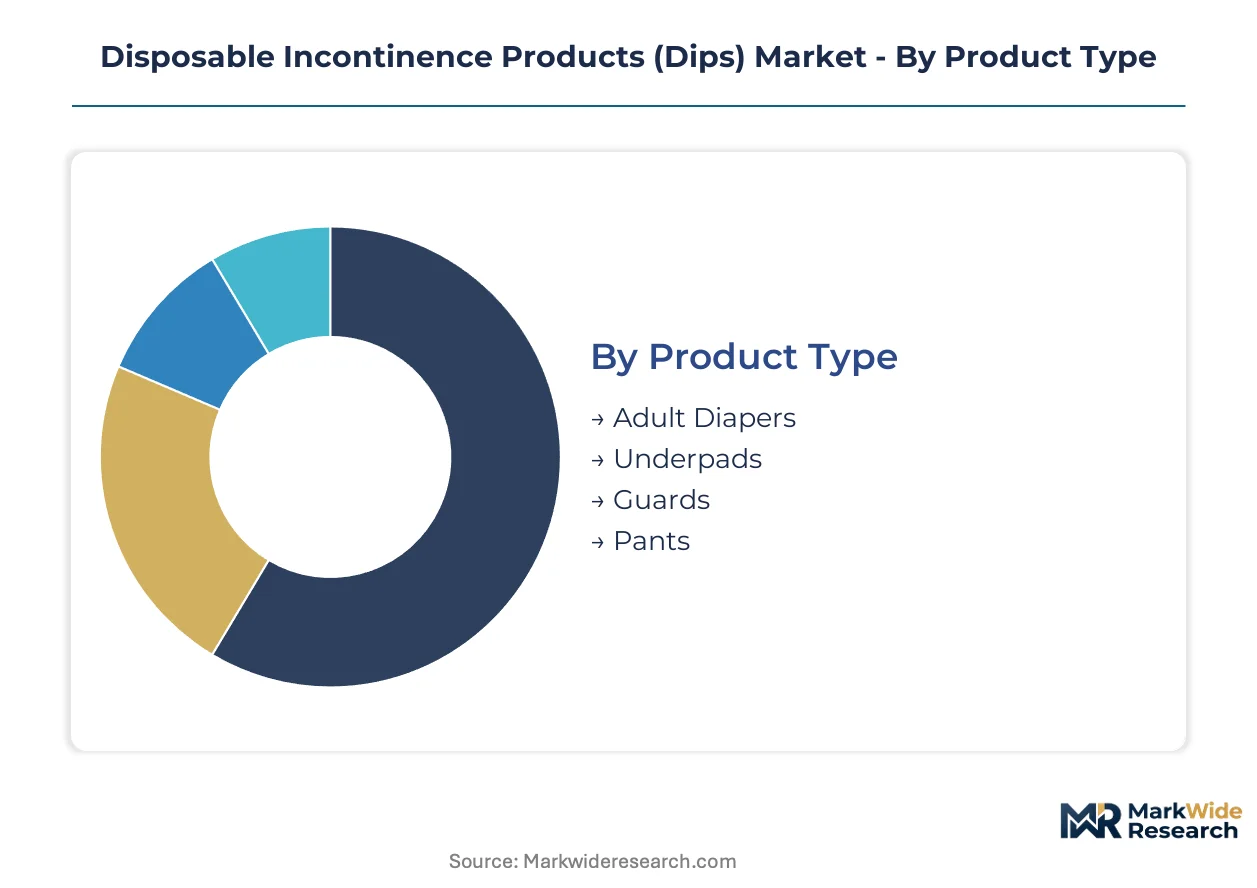
Disposable incontinence products fragment across four critical dimensions that determine formulation chemistry, packaging formats, and channel economics. Product architecture dictates raw material intensity, while end-user concentration shapes reimbursement pathways and bulk procurement terms.
Product Type:
Buyers in this category differentiate by mobility status, caregiver availability, and discretion requirements.
- Adult Diapers:Tape-tab designs with 60-80% SAP cores dominate institutional procurement for bedridden patients. Hospital bulk contracts and nursing home census volumes sustain revenue concentration in North America and Western Europe.
- Pants:Pull-up configurations with elastic waistbands and lower bulk profiles target ambulatory elderly prioritizing self-application and social concealment. Japan's aging demographic and Germany's home care subsidies accelerate demand for discrete daytime wear.
- Underpads:Rectangular absorbent sheets with polyethylene backings protect bedding and furniture surfaces. Post-acute care facilities and hospice providers specify 30x36 inch dimensions for standard mattress coverage.
- Guards:Anatomically contoured pads with adhesive strips attach to standard underwear for light-to-moderate leakage. Prostate surgery recovery populations and active seniors with stress incontinence drive specification.
Adult diapers lead volumes today; pants is gaining share fastest.
End User:
Procurement scale and reimbursement mechanisms separate institutional buyers from individual purchasers.
- Nursing Homes:Census-driven bulk purchasing with 8-12 daily change protocols specifies high-SAP formulations to minimize labor costs. Dutch and Belgian facilities pilot smart moisture monitoring to optimize staffing ratios.
- Home Care:Family-managed replenishment with long-term care insurance coverage removes price sensitivity for subsidized users. Germany's Pflegeversicherung covers 80-100% of product costs for eligible individuals.
- Hospitals:Acute care discharge protocols and surgical recovery units demand clinical-grade absorbency with wetness indicators. FDA Class I device classification governs biocompatibility documentation for U.S. tenders.
- Individual Consumers:Self-funded pharmacy and e-commerce purchases prioritize discretion and trial-sized packaging. Subscription platforms in France and Germany capture 23% of this channel's volume.
Nursing homes anchor institutional procurement today; home care is climbing the fastest.
Material:
Component selection determines absorption capacity, skin health outcomes, and regulatory compliance burden.
- SAP:Superabsorbent polymers at 400-600 g/m² loading densities enable 12-hour wear intervals and reduced caregiver intervention. REACH proposals targeting residual acrylate monomers force reformulation investments across European supply chains.
- Absorbent Core:Multi-layer assemblies combining fluff pulp and polymer granules balance acquisition speed against retention under compression. EU MDR clinical-grade testing mandates documentation of fluid handling under mechanical load.
- Non-Woven Fabric:Polypropylene top sheets deliver rapid fluid wicking and skin dryness. Breathable back sheet variants reduce dermatitis incidence in extended-wear scenarios.
- Polymer:Polyethylene films and elastic components provide moisture barriers and garment integrity. Petrochemical price volatility tied to crude indices compresses margins for non-integrated converters.
SAP commands the highest value per kilogram today; biodegradable cellulose alternatives are advancing most quickly.
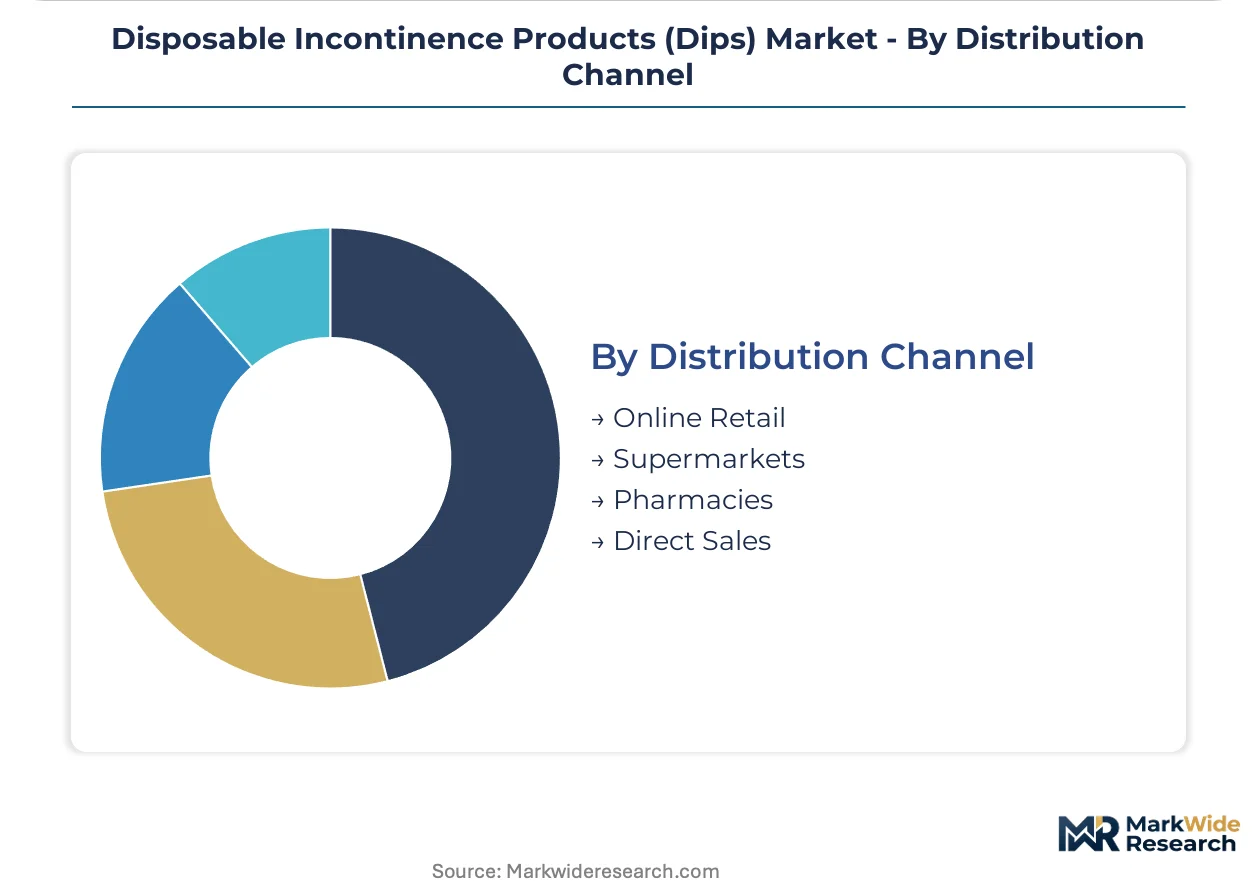
Distribution Channel:
Channel selection reflects buyer urgency, prescription requirements, and subscription preference.
- Pharmacies:Counter consultation and insurance reimbursement processing sustain volume for first-time users and chronic condition management. Germany's Apotheken maintain shelf-space dominance despite e-pharmacy encroachment.
- Online Retail:Direct-to-consumer platforms enable subscription replenishment and private-label penetration. DocMorris and Zur Rose negotiate manufacturer-direct contracts using aggregated demand data.
- Supermarkets:Mass retail placement captures impulse and convenience purchasing for light incontinence products. Kimberly-Clark's North American retail footprint dominates shelf positioning.
- Direct Sales:Institutional contracting with nursing home chains and hospital systems bypasses distributor markups. ERP integration challenges complicate just-in-time delivery at aging care facilities.
Pharmacies retain the largest transaction volume today; online retail is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined medical device pathways, as EU MDR compliance costs compress margins for converters without captive polymer chemistry capabilities. Production migration favors countries with REACH-aligned chemical frameworks but lighter notified body bottlenecks.
Germany
Pflegeversicherung subsidies covering 80-100% of product costs for eligible individuals anchor European demand concentration. The BfArM oversees medical device registration under EU MDR, with notified body backlogs extending recertification timelines. Industrial clustering centers on Heidenheim and Hamburg, where Essity AB and Paul Hartmann AG maintain specialized absorbent hygiene manufacturing scale.
United States
Medicare Advantage expansion into home-based care benefits is accelerating institutional-to-home procurement shifts for adult diaper and pants formats. FDA Class I device classification governs biocompatibility documentation and 510(k) notification pathways. Manufacturing concentrates in Wisconsin and South Carolina, where Kimberly-Clark Corporation operates integrated polymer-to-garment facilities serving North American retail pharmacy networks.
Japan
Ambulatory elderly exceeding 29% of total population generate concentrated demand for discrete pants-format designs with 12-hour wear intervals. PMDA medical device standards align with global ISO 13485 frameworks but impose additional post-market surveillance requirements. Production clusters in Kansai and Chubu regions, where Unicharm Corporation maintains superabsorbent polymer formulation capabilities for Asia-Pacific export.
India
Only 12% of 100+ million elderly citizens access subsidized continence products, creating whitespace for economy-tier disposable lines at sub-$0.50 unit price points. CDSCO medical device rules under Drugs and Cosmetics Act govern absorbency product registration with escalating clinical data requirements. Manufacturing investment concentrates in Gujarat and Maharashtra, where domestic converters assemble fluff pulp-SAP cores for price-sensitive institutional tenders.
Netherlands
Nursing home pilot programs for smart moisture-monitoring garments are compressing caregiver-to-patient ratios from 8-10 to 30+ residents per staff member. The CBG-MEB coordinates EU MDR implementation with accelerated pathways for digital health-integrated devices. Eindhoven and Utrecht host pilot manufacturing for printed electronics-embedded back sheets enabling real-time caregiver alerts.
Disposable Incontinence Products (Dips) Market Competitive Environment
Capacity expansion dominates the current landscape, with integrated converters adding polymer compounding lines to capture margin from SAP price volatility. The supplier base concentrates around three tiers: multinational absorbent hygiene conglomerates with retail pharmacy dominance, European clinical-grade specialists with nursing home contracting expertise, and regional private-label assemblers serving price-sensitive institutional tenders. Strategic archetypes include chemistry-integrated formulators controlling polymer loading densities, channel-anchored brands with pharmacy shelf-space lock-in, and compliance-focused specialists navigating MDR technical documentation. Geographic expansion and portfolio diversification toward smart moisture-sensing formats represent the dominant competitive vectors.
Among chemistry-integrated specialists, Essity AB and Paul Hartmann AG exemplify the European clinical-grade tier with MDR-compliant manufacturing scale, while Kimberly-Clark Corporation anchors the retail-channel archetype through North American pharmacy and supermarket penetration. These three occupy positions spanning institutional contracting, home-care reimbursement capture, and mass-market shelf-space economics, representing the strategic breadth required to absorb regulatory compliance cost escalations across multiple geographies simultaneously.
| Leading Market Players |
|---|
| Essity AB |
| Kimberly-Clark Corporation |
| Procter & Gamble |
| Unicharm Corporation |
| Coloplast A/S |
| Ontex Group |
| Cardinal Health |
| Medline Industries |
| Paul Hartmann AG |
| Others |
Value Chain & Pricing Dynamics
Germany's Pflegeversicherung-subsidized home care segment anchors European demand concentration, binding pricing power to long-term care insurance reimbursement tiers rather than commodity spot dynamics. Manufacturers serving this channel negotiate against fixed reimbursement ceilings while absorbing SAP and petrochemical input volatility.
Pricing Analysis
Pharmacy retail markups compress manufacturer margins by 18-25 points before products reach individual consumers in Germany and France. Pricing stratifies across clinical-grade, standard, and economy tiers, with EU MDR certification and SAP loading density serving as the primary differentiation drivers. Cost compression in economy-tier lines is intensifying because Indian and Southeast Asian converters compete on fluff pulp-SAP assembly costs. Institutional nursing home buyers exhibit lowest price sensitivity due to census-driven bulk contracts, while unsubsidized individual consumers in Southern Europe face highest out-of-pocket burden.
Supply Chain Analysis
EU MDR notified body certification gates concentrate supply among converters with dedicated polymer chemistry laboratories and clinical documentation teams. Manufacturing clusters in Germany, the United States, and Japan feed from Saudi Arabian and South Korean petrochemical feedstocks for polypropylene top sheets and polyethylene backings. Single-source vulnerability runs through superabsorbent polymer supply, where three chemical conglomerates control 70% of global SAP granule production. Distribution runs through institutional contracting desks at nursing home chains and hospital GPOs, with e-pharmacy platforms capturing growing subscription volume in Northern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where EU MDR recertification timelines and REACH substance restrictions accelerate capability consolidation among chemistry-integrated manufacturers. The 2021 MDR enforcement milestone permanently raised fixed cost barriers, entrenching specialists with notified body relationships.
For Market Incumbents: Deepen captive SAP formulation capabilities to offset petrochemical price volatility and deny margin to non-integrated assemblers. Expand Heidenheim and Hamburg manufacturing scale to absorb MDR technical documentation backlogs internally, reducing reliance on constrained notified body capacity. Priority investment targets smart moisture-sensing garment pilots in Dutch and Belgian nursing homes, where staff ratio compression creates subscription lock-in.
For New Entrants and Emerging Players: Enter via India's geriatric care gap, where only 12% of 100+ million elderly access subsidized products and domestic converters lack SAP chemistry depth. Target economy-tier disposable lines at sub-$0.50 unit economics for institutional tenders in Gujarat and Maharashtra. Go-to-market angle: partner with CDSCO-registered local assemblers to bypass capital-intensive polymer compounding while capturing volume in price-sensitive hospital discharge protocols.
For Investors and Strategic Acquirers: Absorbent hygiene conglomerates with retail pharmacy dominance are the most active acquirers in this space, seeking clinical-grade specialists to plug MDR compliance gaps. Long-term viability hinges on chemistry-integrated manufacturing scale rather than brand equity alone. Acquisition target archetype: mid-tier European converters with notified body relationships and nursing home contracting desks. Signal to watch: REACH final guidance on residual acrylate monomer limits, which would force 12-18 month reformulation cycles and strand non-compliant inventory.
| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable SAP Development | Cellulose-based superabsorbents from agricultural waste align with EU Green Deal procurement mandates. |
| Smart Moisture-Sensor Integration | Printed electronics embedded in back sheets enable real-time caregiver alerts and staff ratio optimization. |
| E-Pharmacy Direct Contracting | DocMorris and Zur Rose negotiate manufacturer-direct supply using aggregated subscription demand data. |
| MDR Technical Documentation Investment | In-house regulatory affairs teams compress 14-18 month recertification timelines versus outsourced filing. |
| India Institutional Tender Positioning | CDSCO-registered economy-tier lines capture whitespace in price-sensitive hospital discharge protocols. |
Study Parameters
Bottom-up nursing home census and home care insurance enrollment modeling reconciled against top-down SAP granule and fluff pulp production tracking forms the analytical core of this study. Primary interviews with nursing home procurement directors, GPO contracts managers, biomedical engineers, and absorbent hygiene plant managers were validated against secondary sources including EU MDR notified body filings, REACH substance dossiers, German Pflegeversicherung reimbursement schedules, and CMS Medicare Advantage home care benefit expansions.
Historical trendline analysis of institutional purchasing volumes and individual buyer channel shifts informed projection assumptions across the analysis window. Segmentation dimensions modeled include product architecture, end-user procurement scale, SAP loading density tiers, and distribution channel type. CAGRs were derived from regression-weighted trend extrapolation incorporating demographic aging trajectories, reimbursement policy elasticity, and regulatory compliance cost escalations.
Inputs from notified body capacity registries and polymer chemical trade flows were available through the study window; gaps in real-time nursing home inventory system data introduce uncertainty bands around just-in-time delivery penetration forecasts. Forecasts reflect documented assumptions regarding MDR recertification timeline resolution and REACH substance restriction finalization. A model refresh is warranted upon material change in EU MDR notified body capacity allocation or REACH acrylate monomer limit enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Care Supplies
Global Perineal Care Market
Patient Care Supplies
Hip Shield Market
Patient Care Supplies
Air-Assisted Patient Transfer Systems Market
Patient Care Supplies
Reusable Incontinence Products Market
Patient Care Supplies
Stoma Care Market
Patient Care Supplies
Physical Therapy Supplies Market
Patient Care Supplies
Stretcher Accessories Market
Patient Care Supplies
Self Inflating Bag Market
Patient Care Supplies
US Pressure Ulcer Prevention Market
Patient Care Supplies
Therapy Pillow Market
Patient Care Supplies
GCC Adult Diaper Market
Patient Care Supplies
Reusable Nursing Pads Market
Patient Care Supplies
Global Stoma Care/Ostomy Care and Accessories Market
Patient Care Supplies
Global Patient Lateral Transfer Market
Patient Care Supplies
External Urine Management Products Market
Patient Care Supplies
Asia-Pacific Hospital Supplies Market