
 Asia Pacific Industrial Gloves Market | 2026-2036
Asia Pacific Industrial Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Gloves Market Outlook
REACH compliance migration is expanding the cost-of-entry calculus for glove exporters targeting European-anchored supply chains within Asia Pacific. Ansell Limited leverages its Malaysian manufacturing base to sustain nitrile capacity leadership across ASEAN industrial zones. Hartalega Holdings Berhad anchors high-volume production through automated dipping lines that dominate thin-gauge nitrile output. Top Glove Corporation Bhd competes on polymer sourcing scale, controlling vertical feedstock arrangements across its Thai and Malaysian plants.
Asia Pacific industrial gloves are personal protective equipment engineered from natural rubber latex, synthetic nitrile, vinyl, or polyethylene polymers through coagulant dipping or cast molding processes, designed to shield workers from mechanical abrasion, chemical permeation, and biological contamination. Nitrile formulations lead product type demand due to latex allergy mitigation and superior solvent resistance in chemical processing environments. Food handling applications within the application dimension command premium pricing as HACCP-aligned procurement tightures across ASEAN food export zones. Direct sales channels capture the largest margin pools by bypassing distributor markups for enterprise accounts in manufacturing and healthcare end user segments.
Japan's METI enforces JIS T 8116 cut-resistance gradations that filter import eligibility for high-performance work gloves. China's SAMR and India's BIS operate parallel standardization tracks for chemical permeation breakthrough times, fragmenting certification requirements across the region. Australia's TGA and South Korea's MFDS impose additional medical-grade glove thresholds that overlap with industrial channels. Stakeholders must monitor regulatory divergence between ASEAN harmonization talks and national standards retention to calibrate product development and labeling investments.
Market Dynamics
REACH compliance migration is compressing supplier margins across Asia Pacific industrial glove exports, forcing manufacturers to absorb certification costs or cede European-anchored supply chain access to certified competitors.
Growth Catalysts
- GB Standards Upgrades:China's SAMR mandates stricter chemical permeation breakthrough thresholds, compelling domestic manufacturers to retool dipping lines and creating replacement demand for certified inventory.
- HACCP Procurement Tightening:ASEAN food export zones enforce hazard-critical control point alignment for glove specifications, locking in premium-grade nitrile volumes for seafood and processed food handling.
- Maharashtra-Tamil Nadu Manufacturing Corridors:India's industrial glove demand concentrates in these states as automotive and electronics assembly lines expand protective equipment protocols.
Market Restraints
- Acrylonitrile Feedstock Volatility:Nitrile polymer costs fluctuate with petrochemical pricing, squeezing margin stability for synthetic glove producers dependent on imported monomer supplies.
- Malaysian Production Concentration:Automated dipping capacity clusters in Peninsular Malaysia, creating single-point vulnerability for thin-gauge nitrile output disruption from energy or labor shocks.
- Fragmented BIS-SAMR Parallel Tracks:India's BIS and China's SAMR operate non-harmonized chemical resistance certification timelines, forcing dual testing investments for cross-border suppliers.
Strategic Opportunities
- Vietnam Industrial Zones:Northern provinces around Hai Phong and Bac Ninh show underpenetrated glove procurement as electronics manufacturing shifts from China, creating first-mover channel establishment potential.
- JIS T 8116 Cut-Resistance Premium Tier:Japan's METI gradation system filters import eligibility, rewarding certified high-performance glove suppliers with price premiums in precision metalworking segments.
- Direct Enterprise Sales Channels:Bypassing distributor markups for automotive and healthcare accounts captures margin pools currently captured by industrial supply intermediaries.
Industry Challenges
- Automated Dipping Line Technician Scarcity:Malaysia and Thailand face skilled operator shortages for coagulant bath calibration and thickness control in high-speed nitrile production.
- Dual Certification Timeline Compression:Australia's TGA medical-grade thresholds overlap with industrial channels, extending product validation cycles for suppliers serving both segments.
- Legacy Latex Allergy Liability:Natural rubber formulations retain residual demand in cost-sensitive segments despite protein allergen risks, complicating portfolio transition strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Gloves Market |
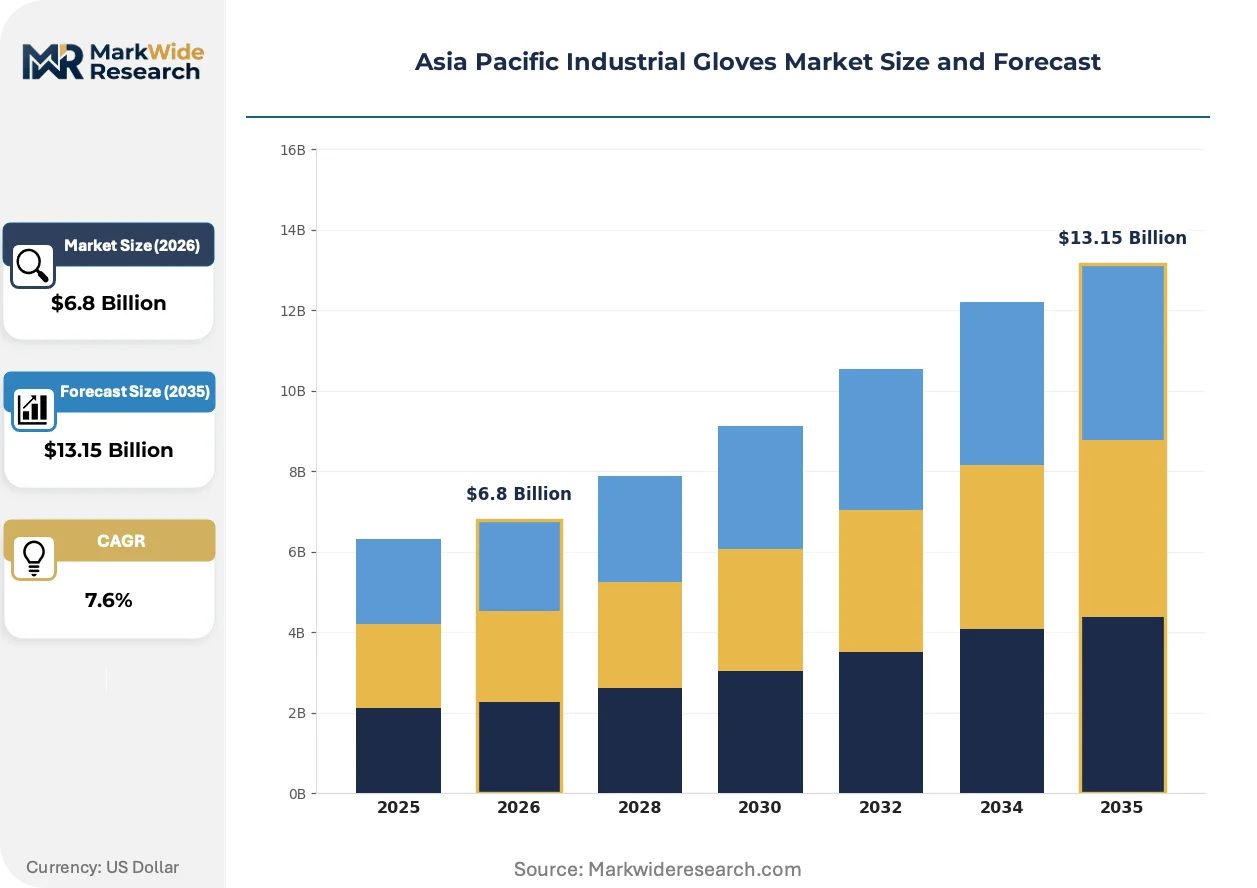
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Latex, Nitrile, Vinyl, Polyethylene End User: Manufacturing, Chemical, Construction, Healthcare Application: Food Handling, Clean Room, Assembly, Chemical Processing Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Ansell Limited, Top Glove Corporation Bhd, Honeywell International Inc., 3M, Kossan Rubber Industries Bhd, Hartalega Holdings Berhad, Showa Glove Co., Supermax Corporation Berhad, Mapa Professional, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Gloves Market Strategic Shifts
Coating chemistry and manufacturing automation are compressing performance-cost tradeoffs, while regulatory fragmentation is forcing modular certification architectures that can pivot across national standards without full product redesign.
Chlorinated surface treatment technology is integrating into nitrile glove finishing lines to reduce surface tack and improve donning performance without powdered lubricants. Electronics assembly plants in South Korea's Gyeonggi Province are adopting these treated specifications for cleanroom compatibility. The technology is integrating downstream quality thresholds into upstream dipping process controls, compressing defect rates and reducing post-production inspection overhead.
China's GB 24541 cut-resistance standards are tightening testing protocols for mechanical protection gloves, forcing domestic manufacturers to upgrade yarn engineering and coating adhesion. The industrial consequence is a supply squeeze in mid-tier performance segments as uncertified inventory exits channels. Metal fabrication and glass handling operations in Shandong and Guangdong provinces are absorbing price premiums for compliant stock while suppliers recertify legacy product lines.
Enterprise buyers in India's automotive hubs are consolidating vendor relationships around integrated safety suppliers offering glove-to-footwear-to-eyewear bundles. Tier-1 component manufacturers in Pune and Chennai are displacing single-category distributors with contracted annual volume agreements that lock in pricing and service levels. This consolidation pattern is most visible where just-in-time assembly lines penalize stockout risk across personal protective equipment categories.
Asia Pacific Industrial Gloves Market Segmentation
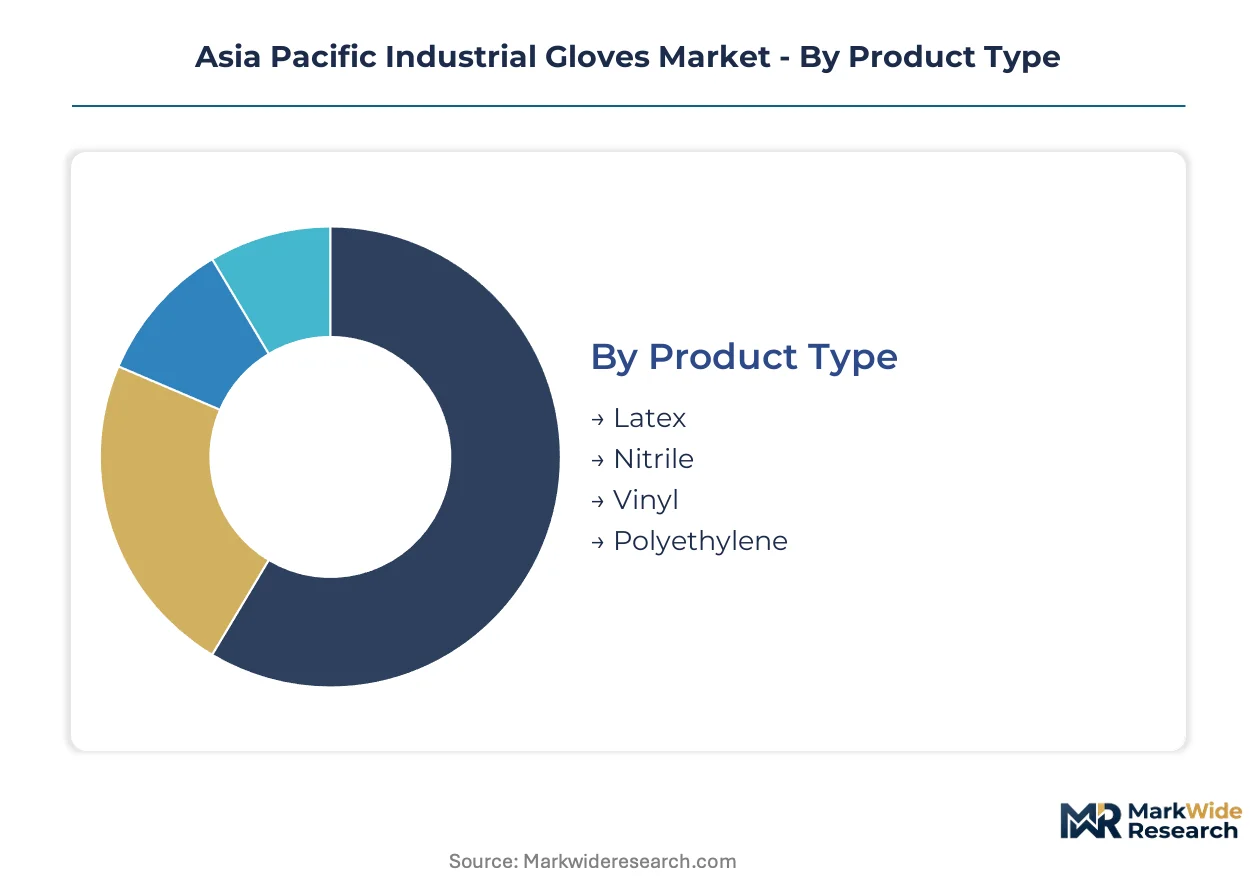
Industrial glove procurement across Asia Pacific segments sharply by chemical resistance requirements and contamination control protocols. Procurement managers in chemical processing and electronics assembly calibrate specifications against divergent national standards, creating tiered demand pools that reward certified suppliers.
Product Type:
Material upgrades dominate replacement cycles as GB standards and BIS timelines force recertification of legacy formulations.
- Nitrile:Synthetic acrylonitrile-butadiene copolymer delivers superior solvent resistance and eliminates latex protein allergens. Demand concentrates in Maharashtra and Tamil Nadu automotive corridors where chemical permeation thresholds are tightening. Malaysian automated dipping lines anchor supply capacity for thin-gauge specifications.
- Latex:Natural rubber formulations retain cost-sensitive volume in general-purpose mechanical protection. Protein allergen liability is compressing share in healthcare and food handling segments across ASEAN export zones.
- Vinyl:Polyvinyl chloride polymer serves low-risk inspection and light assembly tasks where chemical exposure is minimal. Cost positioning sustains demand in India's tier-2 manufacturing clusters.
- Polyethylene:Cast film construction provides single-use barrier protection for food service and sanitation applications. Shorter use cycles drive volume in quick-service restaurant supply chains.
Nitrile sits at the top of the volume ranking, with polyethylene climbing the fastest as food safety protocols expand disposable consumption.
End User:
Customer type determines margin capture, with enterprise accounts consolidating around integrated safety suppliers and spot buyers accepting distributor markups.
- Manufacturing:Automotive and electronics assembly lines in Pune, Chennai, and Bac Ninh drive specification-grade procurement. Just-in-time production penalties for stockouts are locking in annual volume contracts with integrated PPE suppliers.
- Chemical:Petrochemical and specialty chemical plants across Southeast Asia scale glove procurement as SAMR and BIS breakthrough time standards tighten. Chlorinated surface treatments are penetrating this segment for improved donning performance.
- Construction:Mechanical abrasion resistance dominates specification, with cut-resistance gradations filtering import eligibility under Japan's METI frameworks. Project-based demand creates seasonal volume spikes.
- Healthcare:Australia's TGA and South Korea's MFDS medical-grade thresholds overlap with industrial channels, extending validation cycles. Dual-segment suppliers face timeline compression for product launches.
Manufacturing commands the largest revenue pool, with chemical processing gaining share fastest as environmental and safety enforcement intensifies.
Application:
Use-case specificity determines performance tiering, with contamination control applications commanding premium pricing over mechanical protection.
- Food Handling:HACCP-aligned procurement across ASEAN seafood and processed food export zones mandates nitrile specifications with documented allergen control. Premium pricing sustains margin pools for certified suppliers.
- Chemical Processing:Permeation breakthrough testing under parallel BIS-SAMR tracks fragments certification requirements. Suppliers serving both India and China absorb dual testing investments.
- Clean Room:Electronics assembly in South Korea's Gyeonggi Province adopts chlorinated surface treatments for particle control. Downstream quality thresholds are integrating into upstream process controls.
- Assembly:General manufacturing tasks across China's Shandong and Guangdong provinces absorb mid-tier performance segments as GB 24541 cut-resistance standards squeeze uncertified inventory.
Food handling captures the steepest price premiums, with clean room applications expanding most quickly as semiconductor and display manufacturing shifts within the region.
Distribution Channel:
Channel selection directly determines margin retention, with bypass strategies capturing pools currently absorbed by intermediaries.
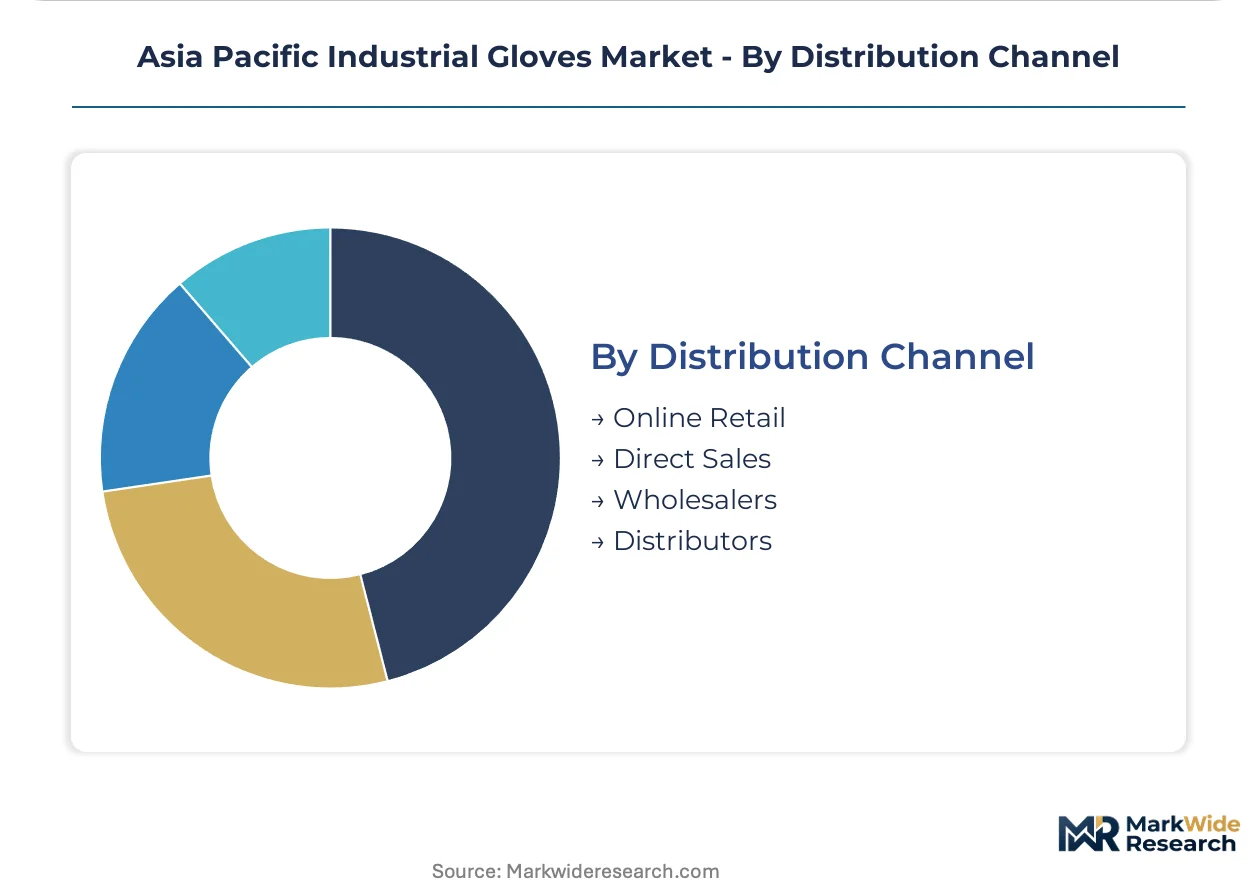
- Direct Sales:Enterprise accounts in automotive and healthcare segments lock in pricing through contracted annual agreements. Tier-1 manufacturers displace single-category distributors for integrated PPE bundles.
- Distributors:Industrial supply intermediaries retain spot-buying volume from small and mid-size manufacturers. Geographic coverage justifies markup acceptance where supplier direct presence is thin.
- Wholesalers:Bulk aggregation serves cost-sensitive construction and general industry segments across India's tier-2 and tier-3 industrial corridors.
- Online Retail:E-commerce penetration remains limited to standard specifications and small-lot procurement. Catalog breadth constraints filter out performance-tier products requiring technical consultation.
Direct sales anchors the margin structure, with distributor relationships contracting fastest as enterprise consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's Peninsular industrial corridor concentrates automated dipping technicians and polymer engineering talent that supply nitrile capacity across ASEAN manufacturing zones. India's Maharashtra and Tamil Nadu states anchor demand concentration from automotive and electronics assembly expansion. Vietnam's northern provinces are emerging as procurement growth vectors as manufacturing relocates from China.
China
Shandong and Guangdong provinces absorb price premiums for GB 24541 cut-resistant gloves as SAMR tightens mechanical protection protocols. The country's dual carbon goals are pressuring petrochemical-dependent nitrile producers to decarbonize acrylonitrile feedstock sourcing. Electronics assembly clusters in the Yangtze River Delta are adopting chlorinated surface treatments for cleanroom compatibility.
India
Automotive tier-1 manufacturers in Pune and Chennai are consolidating vendor relationships around integrated PPE suppliers offering glove-to-footwear bundles. BIS operates parallel chemical permeation certification tracks that force dual testing investments for cross-border suppliers. Tamil Nadu's Sriperumbudur-Oragadam belt is scaling specification-grade procurement as electronics assembly lines expand protective equipment protocols.
Japan
Precision metalworking segments in Aichi Prefecture filter import eligibility through METI's JIS T 8116 cut-resistance gradations. The country's aging workforce is tightening enforcement of hand protection mandates across small and mid-size manufacturing enterprises. Kansai region fabricators are absorbing premium pricing for certified high-performance specifications in automotive component handling.
Vietnam
Electronics manufacturing shifts from China are driving underpenetrated glove procurement in Hai Phong and Bac Ninh industrial zones. The country's national standardization body is developing chemical resistance protocols that reference but do not fully harmonize with Chinese GB standards. Northern province factories are establishing first-mover channel relationships as supply chain relocation accelerates.
Australia
TGA medical-grade thresholds overlap with industrial channels, extending validation cycles for suppliers serving both segments. Mining operations in Western Australia and Queensland drive mechanical abrasion-resistant procurement for extraction and materials handling tasks. The country's resource sector is consolidating annual volume agreements with integrated safety suppliers to penalize stockout risk across remote operations.
Asia Pacific Industrial Gloves Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Malaysian and Thai producers anchor automated dipping capacity for thin-gauge nitrile output, while diversified industrial conglomerates leverage cross-category procurement relationships. Three strategic archetypes dominate: polymer-integrated manufacturers controlling feedstock arrangements, automation-heavy specialists optimizing high-speed production lines, and diversified safety conglomerates bundling glove portfolios with respiratory and eyewear protection. Capacity expansion and backward integration into acrylonitrile sourcing represent the dominant competitive moves as feedstock volatility squeezes margin stability.
Within the pure-play specialist tier, Ansell Limited, Hartalega Holdings Berhad, and Top Glove Corporation Bhd occupy positions that exemplify divergent scale and integration strategies. Ansell leverages its Malaysian manufacturing base to sustain nitrile capacity leadership across ASEAN industrial zones. Hartalega anchors high-volume production through automated dipping lines that dominate thin-gauge output specifications. Top Glove competes on polymer sourcing scale, controlling upstream feedstock arrangements across its Thai and Malaysian plant network. These three specialists collectively represent the automation-capability concentration that defines regional supply structure.
| Leading Market Players |
|---|
| Ansell Limited |
| Top Glove Corporation Bhd |
| Honeywell International Inc. |
| 3M |
| Kossan Rubber Industries Bhd |
| Hartalega Holdings Berhad |
| Showa Glove Co. |
| Supermax Corporation Berhad |
| Mapa Professional |
| Others |
Value Chain & Pricing Dynamics
Captive nitrile polymer sourcing across Thai and Malaysian plant networks anchors both supply security and margin control for synthetic glove producers serving ASEAN industrial zones. This backward integration into acrylonitrile feedstock arrangements insulates certified manufacturers from petrochemical volatility while supporting premium positioning against spot-market dependent competitors.
Pricing Analysis
Bundled annual volume agreements with integrated PPE suppliers capture margin pools that unbundled spot purchasing leaves with industrial supply intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates JIS T 8116 certified high-performance specifications from GB 24541 compliant mid-tier mechanical protection and uncertified general-purpose inventory. Price differentiation rests on dual certification investments under parallel BIS-SAMR tracks and chlorinated surface treatment technology integration. Cost compression in standard-tier nitrile is intensifying as Malaysian automated dipping capacity expands thin-gauge output. Spot buyers in India's tier-2 manufacturing clusters exhibit highest price sensitivity, while Japan's precision metalworking segments absorb premium pricing for certified cut-resistance gradations.
Supply Chain Analysis
Skilled technician scarcity for coagulant bath calibration in Peninsular Malaysia and Thailand constrains automated dipping line expansion despite electronics manufacturing relocation into Vietnam. Raw material sourcing draws from imported acrylonitrile monomer supplies, natural rubber latex from Indonesian and Thai plantations, and chlorination treatment chemicals from South Korean specialty chemical producers. Single-source vulnerability concentrates in Malaysian thin-gauge nitrile capacity, where energy or labor shocks would disrupt regional supply. Distribution runs through direct enterprise sales channels for automotive and healthcare accounts, with industrial supply intermediaries retaining geographic coverage in underpenetrated northern Vietnam provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific industrial gloves function as a stable compounder anchored by tightening workplace safety enforcement across ASEAN manufacturing corridors. Regulatory ratcheting in chemical permeation standards and cut-resistance gradations sustains replacement demand regardless of macroeconomic cyclicality.
For Market Incumbents: Deepen backward integration into acrylonitrile feedstock sourcing to defend margin stability against petrochemical price swings threatening synthetic glove producers. Lock in multi-year enterprise contracts with tier-1 automotive manufacturers in Pune and Chennai before integrated safety conglomerates consolidate vendor relationships. Prioritize JIS T 8116 certification investment to capture premium pricing in Japan's precision metalworking segments before competitors replicate technical capabilities. For New Entrants and Emerging Players: Chlorinated surface treatment technology offers a technology-first wedge into South Korea's Gyeonggi Province electronics assembly cleanroom specifications where incumbent penetration remains limited. Target Vietnam's Hai Phong and Bac Ninh industrial zones through first-mover distributor partnerships before Malaysian and Thai producers establish direct sales presence. Pursue HACCP-aligned food handling certification to access ASEAN seafood export zone premium pricing with lower capital intensity than automated dipping line investment. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap automation-heavy specialists because fragmented BIS-SAMR certification timelines prevent rapid scale replication by capital-rich diversified conglomerates. Platform consolidation of Vietnamese and Indonesian distributors serving tier-2 manufacturing clusters offers 5-10 year viability as supply chain relocation accelerates glove procurement growth. Watch for acrylonitrile price inflection as signal for margin compression timing among non-integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylonitrile Sourcing | Captive polymer supply insulates margins from petrochemical volatility squeezing non-integrated competitors. |
| JIS T 8116 Certification Investment | METI gradation compliance unlocks premium pricing in Japan's precision metalworking import-filtered market. |
| Chlorinated Surface Treatment Scale-Up | Cleanroom-compatible finishing captures South Korean electronics assembly specification-grade demand. |
| Direct Enterprise Sales Channel Buildout | Bypassing distributor markups captures margin pools in India's consolidating automotive PPE procurement. |
| Vietnam Distribution Network Establishment | First-mover positioning in Hai Phong and Bac Ninh industrial zones secures electronics manufacturing relocation volume. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant managers at Malaysian and Thai glove manufacturers, procurement leads at Indian automotive tier-1 suppliers, safety officers at Japanese precision metalworking facilities, and distribution channel partners across Vietnam industrial zones combined with secondary validation. Secondary sources include customs and trade data tracking nitrile and latex import flows, SAMR and BIS certification registry filings, SEC 10-K disclosures from listed glove producers, and ASEAN industrial zone development authority reports.
Input-output matrices map acrylonitrile feedstock availability against automated dipping line capacity across the projection horizon. Segmentation dimensions modeled encompass material formulation, end-use industry, application specificity, and distribution channel structure. CAGRs derive from volume trajectory analysis reconciled against pricing tier evolution. Industry-specific forecast inputs incorporate GB standards upgrade timelines and HACCP procurement tightening enforcement patterns across ASEAN food export zones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to acrylonitrile price volatility, Malaysian energy supply stability, and regulatory harmonization progress between ASEAN and national standardization bodies. Forecasts reflect documented assumptions about certification timeline compression and electronics manufacturing relocation velocity. Material deviation in acrylonitrile feedstock pricing or Malaysian labor availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
North America Healthcare Packaging Market
Medical Supplies
Hydrogel Dressing Market
Medical Supplies
Anesthesia Disposables Market
Medical Supplies
First Aid Kit Market
Medical Supplies
Medical Gauze and Tapes Market
Medical Supplies
Surgical Gloves Market
Medical Supplies
Ostomy Care Market
Medical Supplies
China Hospital Supplies Market
Medical Supplies
Spain Hospital Supplies Market
Medical Supplies
Serum-Free Media Market
Medical Supplies
Filter Needles Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Plasma Collection Containers Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Catgut Sutures Market
Medical Supplies
Nitrile Gloves Market