
 Global Urinary Incontinence Treatment Devices Market | 2026-2036
Global Urinary Incontinence Treatment Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Urinary Incontinence Treatment Devices Market Intelligence
CE marking under the EU Medical Device Regulation is unwinding market access for smaller manufacturers lacking notified body relationships. Coloplast A/S leverages its vertically integrated silicone manufacturing to sustain margin control across catheter and pessary portfolios. Medtronic plc anchors the neuromodulation segment with sacral nerve stimulation systems that dominate urology department procurement in tertiary hospitals. Boston Scientific Corporation competes through differentiated tibial nerve stimulation platforms targeting outpatient clinic workflows.
Urinary incontinence treatment devices encompass mechanical, electrical, and absorbent systems designed to manage involuntary urine leakage through urethral occlusion, neuromuscular stimulation, or fluid capture; sacral nerve stimulators typically deliver 10-14 Hz frequency pulses to modulate detrusor reflex arcs, while modern catheters employ hydrophilic polymer coatings to reduce urethral trauma during intermittent self-catheterization. Catheters occupy the largest product category by procedure volume, though electrical stimulation devices represent the fastest-expanding margin pool as payers expand coverage for non-surgical interventions. Home care settings now outpace hospital channels in growth velocity, reflecting structural shifts toward ambulatory management and remote patient monitoring integration.
The FDA's Center for Devices and Radiological Health classifies implantable continence devices as Class III, mandating premarket approval with long-term safety cohorts, while Japan's PMDA requires local clinical bridging studies for electrical stimulation systems that alters Japan entry timelines for Western manufacturers. The EU MDR's enhanced post-market surveillance obligations are forcing portfolio rationalization among companies with legacy device families lacking sufficient clinical follow-up data. Stakeholders must monitor reimbursement code consolidation across Medicare, Germany's G-BA, and Japan's Chuikyo as these decisions directly determine which device modalities achieve scalable adoption.
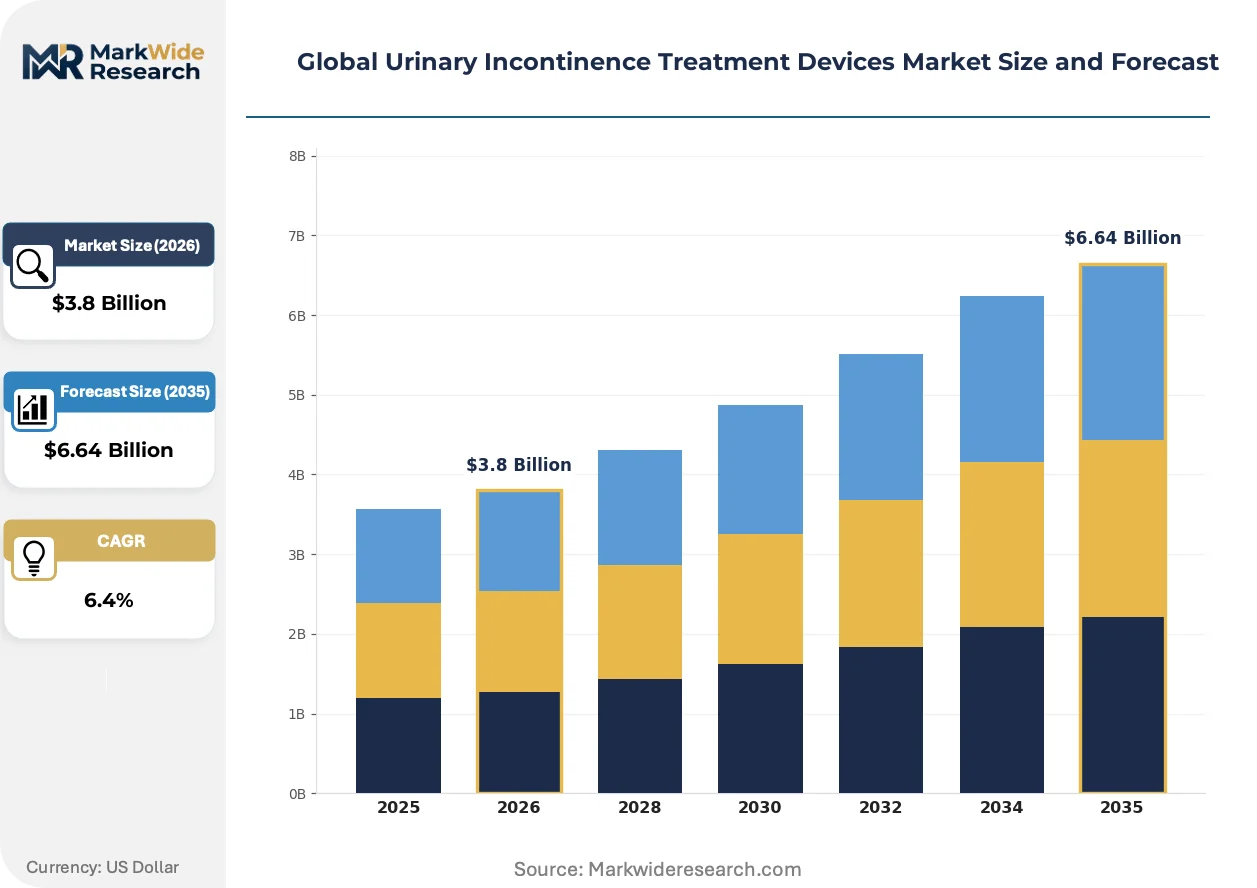
Market Dynamics
The EU Medical Device Regulation's clinical evidence requirements are forcing portfolio consolidation among manufacturers of implantable continence devices, while aging demographics in Japan, Germany, and the United States redirect procurement toward ambulatory-compatible systems.
Growth Catalysts
- Japan's PMDA reimbursement expansion:Electrical stimulation coverage under Chuikyo decisions is accelerating neuromodulation adoption in outpatient urology clinics.
- Home care infrastructure:Remote patient monitoring integration with intermittent catheterization protocols is reducing hospital readmission rates for chronic incontinence patients.
- Silicone polymer advances:Hydrophilic coating chemistry improvements are extending dwell times for indwelling catheters in long-term care settings.
Market Restraints
- Notified body scarcity:EU MDR certification bottlenecks in Germany and the Netherlands are extending time-to-market for novel implantable devices by 18-24 months.
- Platinum-iridium electrode costs:Sacral nerve stimulator manufacturers face raw material price volatility concentrated in South African and Russian supply channels.
- Antimuscarinic pharmacotherapy:Oral medication adherence programs in Medicare Advantage plans retain first-line therapy status, delaying device referral pathways.
Strategic Opportunities
- India's CDSCO fast-track:Class B electrical stimulation devices qualify for abbreviated review under the 2023 Medical Device Rules amendment.
- Tibial nerve-home hybrid systems:Percutaneous lead technology convergence with wearable biofeedback is creating unsupervised treatment protocols.
- Germany's G-BA innovation funding:DiGA (digital health applications) reimbursement for bladder diary apps with connected sensor hardware opens bundled payment models.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity study backlogs at contract research organizations are delaying PMA submissions to FDA.
- Legacy EHR integration:Sacral nerve stimulator programming interfaces require proprietary middleware for Epic and Cerner connectivity in US hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Urinary Incontinence Treatment Devices Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Absorbent Pads, Electrical Stimulation Devices, Urethral Inserts, Pessaries Application: Stress Incontinence, Urge Incontinence, Overflow Incontinence, Functional Incontinence, Mixed Incontinence End User: Hospitals, Long-Term Care Facilities, Rehabilitation Centers, Home Care Settings, Outpatient Clinics Distribution Channel: Pharmacies, Online Retailers, Medical Supply Stores, Direct Sales, Distributors |
| Companies Covered | Coloplast A/S, B. Braun Melsungen AG, Becton, Dickinson and Company, Boston Scientific Corporation, Medtronic plc, ConvaTec Group plc, Teleflex Incorporated, Hollister Incorporated, Essity Aktiebolag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Urinary Incontinence Treatment Devices Market Strategic Shifts & Innovations
Device miniaturization and closed-loop feedback architectures are compressing the boundary between implantable and external neuromodulation systems, with regulatory frameworks scrambling to classify hybrid modalities.
Closed-loop tibial nerve stimulators with real-time detrusor pressure sensing are supplanting open-loop sacral systems in outpatient clinic procurement. Urology departments in German tertiary hospitals are piloting these platforms for urge incontinence dominance. The shift is compressing average selling prices in the neuromodulation segment while expanding addressable patient pools beyond surgical candidates.
EU MDR's Post-Market Clinical Follow-up requirements are mandating 15-year safety registries for implantable continence devices. Manufacturers with legacy sling and artificial urinary sphincter portfolios face retrospective data collection costs exceeding original development budgets. The regulation is driving strategic exits from mechanical implantables among mid-cap European device firms lacking clinical affairs scale.
Patients are self-directing toward direct-to-consumer catheter subscription models, bypassing durable medical equipment distributors. Amazon Business and specialized urology supply platforms are capturing intermittent catheter volume in the United States and United Kingdom. This disintermediation is forcing traditional home health agencies to unbundle product provision from nursing visit billing.
Global Urinary Incontinence Treatment Devices Market Segmentation
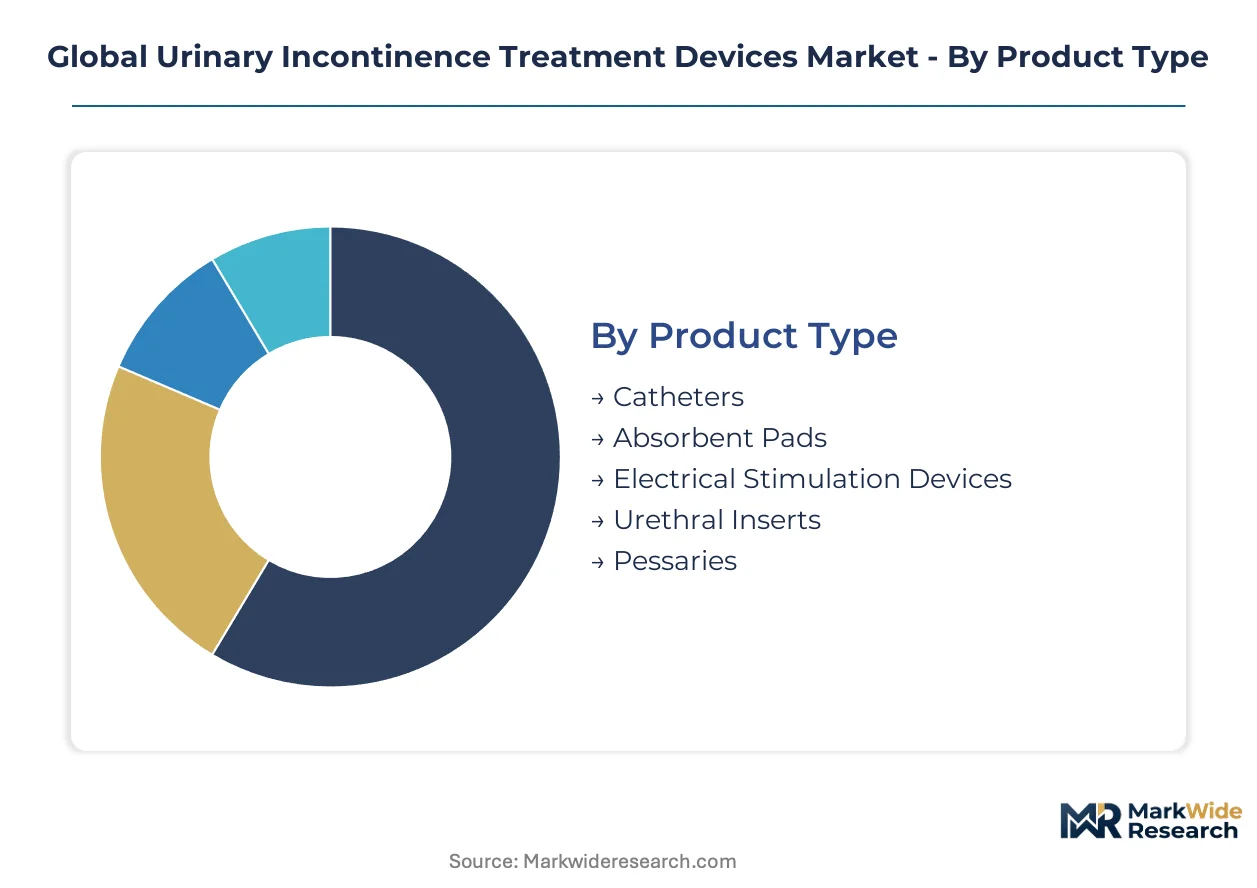
Device segmentation in urinary incontinence treatment reveals divergent margin profiles across mechanical, electrical, and absorbent modalities. Procurement patterns split between institutional tenders and direct-to-consumer channels, with reimbursement codes determining viable commercial pathways for each category.
Product Type:
Catheters and absorbent pads dominate domestic manufacturing footprints in the United States and Germany, while electrical stimulation devices rely heavily on export-led supply chains from South Korea and Switzerland.
- Catheters:Hydrophilic polymer-coated intermittent and indwelling designs reduce urethral trauma during self-catheterization protocols. German long-term care facilities and Japanese home care agencies account for the densest procurement volumes, driven by aging-in-place policies and expanded catheter reimbursement under statutory health insurance.
- Electrical Stimulation Devices:Sacral and tibial nerve stimulators deliver frequency-modulated pulses to modulate detrusor reflex arcs. Outpatient urology clinics in the United States and Japan are the primary demand centers, with PMDA and FDA neuromodulation coverage decisions accelerating clinic-based adoption over surgical alternatives.
- Absorbent Pads:Superabsorbent polymer cores with moisture-wicking top sheets target community-dwelling elderly populations. United Kingdom and Netherlands pharmacy chains move the highest retail volumes through reimbursed continence product schemes.
- Urethral Inserts:Disposable silicone plugs provide temporary occlusion for stress incontinence episodes during physical activity. Direct-to-consumer channels in Australia and Canada capture the majority of commercial flow.
- Pessaries:Silicone ring, cube, and Gellhorn configurations offer mechanical support for pelvic organ prolapse-associated leakage. Gynecology practices in France and Italy maintain the deepest fitting specialist networks.
Catheters command the established base. The steepest expansion runs through electrical stimulation devices.
Application:
Cost tier stratification separates premium neuromodulation therapies from economy absorbent management, with stress and urge incontinence indications capturing the reimbursement depth to support device margins.
- Stress Incontinence:Urethral support devices and pelvic floor stimulators address sphincteric deficiency from childbirth trauma or prostate surgery. Medicare Advantage plans in the United States and Bismarck-model funds in Germany reimburse pessary fitting and electrical biofeedback at tiered rates.
- Urge Incontinence:Overactive detrusor modulation drives sacral nerve stimulator implantation and percutaneous tibial nerve stimulation protocols. Japanese Chuikyo decisions and US CMS national coverage determinations have expanded outpatient clinic access for these interventions.
- Overflow Incontinence:Intermittent catheterization programs manage neurogenic bladder from spinal cord injury or diabetic neuropathy. Veterans Affairs health systems and British NHS spinal injury centers standardize hydrophilic catheter protocols.
- Functional Incontinence:Mobility-limiting arthritis or dementia drives demand for caregiver-assisted absorbent products and bedside commodes. Netherlands Buurtzorg home nursing organizations and US Medicaid waiver programs procure at volume scale.
- Mixed Incontinence:Combined stress and urge symptoms require multimodal device sequencing. French HAS clinical guidelines and NICE technology appraisals in the United Kingdom influence stepped-care algorithm design.
Urge incontinence applications concentrate the highest device margins. Mixed incontinence is gaining share fastest as diagnostic specificity improves.
End User:
Customer type fragmentation splits between acute episode management in hospitals and chronic maintenance in home environments, with remote monitoring integration blurring traditional site-of-care boundaries.
- Hospitals:Tertiary urology departments in Germany, Japan, and the United States implant sacral nerve stimulators and artificial urinary sphincters. FDA premarket approval requirements and PMDA bridging study mandates concentrate implantable device adoption in academic medical centers with clinical trial infrastructure.
- Home Care Settings:Intermittent catheterization and absorbent product subscriptions bypass traditional durable medical equipment distribution. Amazon Business and specialized urology supply platforms in the United States and United Kingdom capture patient-directed procurement volume.
- Long-Term Care Facilities:Indwelling catheter protocols and scheduled pad changes dominate institutional continence management. Japanese kaigo facilities and German Pflegeheime operate under reimbursement caps that favor economy product tiers.
- Rehabilitation Centers:Pelvic floor biofeedback and electrical stimulation protocols follow prostatectomy or obstetric trauma. Australian private rehabilitation networks and Canadian provincial outpatient clinics standardize device-assisted recovery pathways.
- Outpatient Clinics:Tibial nerve stimulation and pessary fitting occur in community urology and gynecology practices. US ambulatory surgery centers and Japanese clinic chains exploit site-of-service payment differentials.
Home care settings anchor volume growth. Outpatient clinics are climbing the fastest as neuromodulation shifts from operating room to office-based procedures.
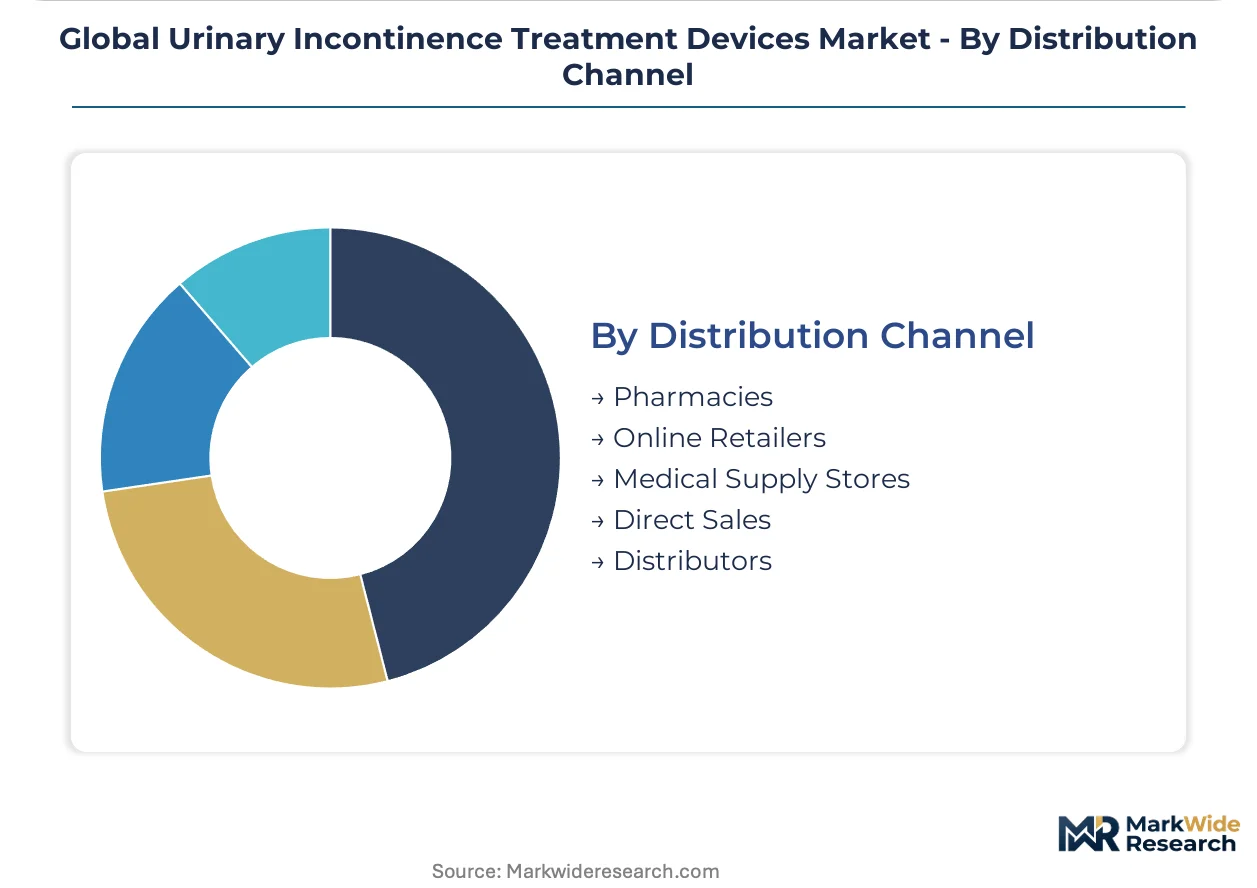
Distribution Channel:
Supply concentration in catheter manufacturing clusters—Coloplast in Denmark, Hollister in the United States, Teleflex in Ireland—determines distributor leverage and direct sales viability across geographic markets.
- Pharmacies:Community and hospital pharmacy networks in France, Spain, and Italy dispense reimbursed absorbent pads and intermittent catheters. ANSM vigilance requirements and national tariff agreements shape product listing decisions.
- Online Retailers:Subscription models for catheter and pad delivery disintermediate traditional home health agencies. Amazon Business, Allegro Medical, and specialized urology platforms in the United States, United Kingdom, and Poland capture recurring revenue streams.
- Medical Supply Stores:Durable medical equipment dealers fit pessaries and dispense advanced wound care adjacent to continence products. Independent dealers in Texas, Florida, and California maintain the densest US storefront networks.
- Direct Sales:Manufacturer field forces target hospital value analysis committees and long-term care group purchasing organizations. Medtronic and Boston Scientific neuromodulation specialists call directly on US urology department chairs.
- Distributors:Cardinal Health, McKesson, and regional players warehouse and deliver high-volume catheter and pad SKUs to institutional customers. German B2B medical distributors and Japanese pharmaceutical wholesalers maintain cold-chain and controlled-substance infrastructure that supports device logistics.
Pharmacies retain the reimbursement-connected base. Online retailers are expanding most quickly as patient self-direction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's Chuikyo reimbursement decisions for electrical stimulation systems have triggered competitive repositioning among device manufacturers seeking outpatient clinic access. Germany's G-BA innovation funding for digital health applications creates bundled payment opportunities for connected continence devices. The United States, Germany, and Japan concentrate procurement volume for neuromodulation systems due to established payer pathways.
United States
Medicare national coverage determinations for sacral nerve stimulation anchor hospital procurement in tertiary urology departments. The FDA's Class III premarket approval requirements concentrate implantable device adoption in academic medical centers with clinical trial infrastructure. Minneapolis-based Medtronic and Marlborough-based Boston Scientific maintain direct sales forces targeting urology department chairs.
Germany
G-BA DiGA reimbursement for bladder diary apps with sensor hardware accelerates connected device adoption in outpatient settings. The EU MDR's enhanced post-market surveillance obligations force portfolio rationalization among manufacturers with legacy sling portfolios. North Rhine-Westphalia's dense network of Pflegeheime drives economy-tier catheter procurement under statutory health insurance caps.
Japan
PMDA bridging study requirements for electrical stimulation systems extend entry timelines for Western manufacturers while accelerating local clinical partnerships. Chuikyo reimbursement expansion for tibial nerve stimulation shifts neuromodulation from operating rooms to clinic chains. Tokyo's kaigo facilities standardize indwelling catheter protocols under long-term care insurance.
United Kingdom
NICE technology appraisals for mixed incontinence influence stepped-care algorithm design across NHS continence services. Pharmacy chains move the highest retail volumes of reimbursed absorbent products through national tariff agreements. London-based home nursing organizations pilot remote monitoring integration with intermittent catheterization protocols.
Switzerland
Swissmedic's streamlined device approval pathways attract neuromodulation specialists seeking European market entry ahead of EU MDR certification bottlenecks. Zurich and Basel host contract research organizations managing ISO 10993 biocompatibility studies for PMA-bound manufacturers. The country's private insurance landscape supports premium-tier electrical stimulation device adoption.
Global Urinary Incontinence Treatment Devices Market Key Industry Players
Listed leaders compete with private specialists across regulatory compliance capabilities, with publicly traded manufacturers absorbing EU MDR retrospective data collection costs that force mid-cap exits. The vendor base stratifies into three tiers: diversified medical technology conglomerates with neuromodulation franchises, vertically integrated silicone specialists controlling catheter and pessary manufacturing, and regional distributors capturing disintermediated home care volume. Dominant competitive moves include strategic partnerships for remote patient monitoring integration and geographic expansion into India's CDSCO fast-track pathway for Class B electrical stimulation devices.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corporation exemplify scale-driven positioning through sacral and tibial nerve stimulation platforms respectively. Coloplast A/S represents the vertically integrated specialist archetype with captive silicone manufacturing sustaining margin control. Among European fabricators, B. Braun Melsungen AG and Becton, Dickinson and Company occupy positions spanning catheter supply chains and institutional procurement channels.
| Leading Market Players |
|---|
| Coloplast A/S |
| B. Braun Melsungen AG |
| Becton, Dickinson and Company |
| Boston Scientific Corporation |
| Medtronic plc |
| ConvaTec Group plc |
| Teleflex Incorporated |
| Hollister Incorporated |
| Essity Aktiebolag |
| Others |
Cost & Logistics Intelligence
Eighteen-month EU MDR recertification queues for implantable continence devices compress inventory turns for notified body-dependent manufacturers while amplifying pricing power for incumbents with pre-certified portfolios. This lead-time asymmetry between regulatory access and commercial demand concentrates margin capture among vertically integrated silicone specialists and diversified neuromodulation conglomerates.
Pricing Analysis
Certification level creates the primary spread across the device landscape, with FDA Class III PMA-grade sacral nerve stimulators commanding premium positioning against CE-marked Class IIa tibial nerve systems and unregulated direct-to-consumer catheters. Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical evidence depth and reimbursement code attachment, with Medicare Advantage and Germany's G-BA tiered reimbursement accelerating price compression in the standard tier. Cost compression in economy catheters intensifies because of Amazon Business disintermediation and patient-directed subscription models. Long-term care facilities and Japanese kaigo institutions exhibit highest price sensitivity, while tertiary hospital urology departments demonstrate lowest sensitivity due to bundled procedural reimbursement.
Supply Chain Analysis
Platinum-iridium electrode sourcing from South African and Russian supply channels constitutes a critical chokepoint for sacral nerve stimulator manufacturers, with alternative supply development lagging 24-36 months behind demand growth. Manufacturing gravity centers on Denmark for hydrophilic catheter coatings, Switzerland for neuromodulation system assembly, and South Korea for electrical stimulation component fabrication. Raw material dependencies span medical-grade silicone from Wacker Chemie and Momentive, platinum-group metals from Anglo American and Norilsk Nickel, and hydrophilic polymers from DSM Biomedical. Single-source vulnerability in notified body relationships for EU MDR certification extends time-to-market for novel implantables. Distribution runs through Cardinal Health and McKesson for institutional catheter volume, with direct-to-consumer platforms capturing accelerating home care share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of clinical affairs infrastructure capable of sustaining 15-year EU MDR post-market surveillance registries is consolidating competitive position among manufacturers with retrospective data archives, while forcing strategic exits from mechanical implantables among mid-cap European firms lacking regulatory scale.
For Market Incumbents: Fortify regulatory compliance capabilities through captive notified body relationships and retrospective clinical data collection infrastructure, while consolidating silicone polymer supply through backward integration into medical-grade elastomer production. The EU MDR's enhanced surveillance obligations threaten mid-cap competitors lacking 15-year safety registries, creating acquisition opportunities for clinical affairs scale. For New Entrants and Emerging Players: Differentiate on closed-loop tibial nerve stimulation architectures with real-time detrusor pressure sensing, targeting outpatient clinic workflows in Germany and Japan where site-of-service payment differentials favor office-based procedures over surgical implantation. India's CDSCO fast-track pathway for Class B electrical stimulation devices offers the most penetrable regulatory entry point, with abbreviated review timelines enabling speed-to-market against entrenched sacral nerve competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with legacy sling and artificial urinary sphincter portfolios facing retrospective data collection costs exceeding original development budgets. Long-term viability across the neuromodulation segment hinges on reimbursement code consolidation decisions by Medicare, Germany's G-BA, and Japan's Chuikyo. Watch CMS national coverage determinations for percutaneous tibial nerve stimulation as the signal indicating inflection toward outpatient clinic dominance over surgical implantation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR recertification timelines determine competitive survival for implantable device portfolios. |
| Hospital System Partnership | Academic medical center alliances secure PMA trial infrastructure and urology department procurement access. |
| Software Companion Development | Bladder diary apps with sensor hardware qualify for Germany's G-BA DiGA reimbursement bundling. |
| Reimbursement Strategy | Chuikyo and CMS coverage decisions directly determine addressable patient pools for neuromodulation systems. |
| FDA Submission | PMA approval with long-term safety cohorts anchors Class III device positioning in tertiary hospital procurement. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across urology department chairs, biomedical engineers, hospital purchasing committees, GPO contracts managers, and home care procurement leads. Primary interview insights combined with secondary validation from FDA 510(k) and PMA filings, EU MDR notified body certification databases, CMS national coverage determinations, and Japan's Chuikyo reimbursement bulletins. Bottom-up procedure volume modeling and top-down manufacturer revenue triangulation anchored market size estimation.
Across the analysis window, analytical frameworks modeled segmentation by product type, application indication, end-user setting, and distribution channel, with neuromodulation system adoption curves derived from payer coverage expansion patterns. CAGRs reflect procedure volume growth adjusted for reimbursement code consolidation and site-of-service payment differentials, with electrical stimulation device penetration calibrated against antimuscarinic pharmacotherapy adherence benchmarks.
The analysis sits within stated boundaries; outcomes outside sustained Medicare Advantage and statutory health insurance reimbursement stability would require recalibration. Forecasts assume continued regulatory enforcement of EU MDR post-market surveillance and PMDA bridging study requirements. Practitioners should keep alternative scenarios live as payer code consolidation decisions and notified body capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Global Ileostomy Market
Medical Devices
Global Digital Dose Inhaler Market
Medical Devices
Global Implantable Drug Delivery Market
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Global Venous Stents Market
Medical Devices
3D Printed Implants Market
Medical Devices
Intracranial Stents Total Addressable Market
Medical Devices
Global Pressure Relief Devices Market
Medical Devices
Global Hysteroscope Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Venous Procedure Devices Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Global Hemostasis Valves Market