
 Chronic Total Occlusion Devices Market | 2026-2036
Chronic Total Occlusion Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Total Occlusion Devices Market Analysis
Software-defined procedural planning and remote proctoring services is broadening what device vendors monetize beyond hardware. Abbott Laboratories leverages its integrated vascular imaging portfolio to anchor premium positioning in CTO workflows. Boston Scientific Corporation sustains R&D intensity across guidewire and crossing catheter platforms. Asahi Intecc Co., Ltd. dominates ultra-fine wire manufacturing for complex lesion subsets.
Chronic total occlusion devices encompass specialized guidewires, microcatheters, and balloon systems engineered to navigate and recanalize coronary or peripheral vessels with TIMI grade 0 flow durations exceeding three months, typically utilizing hydrophilic polymer coatings and tapered tip configurations to penetrate fibrocalcific cap structures. The primary commercial purpose centers on restoring antegrade perfusion to ischemic myocardium or limb tissue in patients with refractory angina or claudication. Guidewire platforms occupy the deepest margin pools due to repeat purchase cycles and proprietary tip technology differentiation. Balloon catheters represent the most mature segment with commoditization pressure from multi-vendor supply. Optical coherence tomography integration into CTO procedures is expanding fastest as operators demand real-time lesion characterization before stent deployment.
FDA premarket notification pathways and EU MDR technical documentation requirements shape product development timelines and clinical evidence thresholds for CTO device manufacturers. Japan's PMDA and China's NMPA impose additional local testing protocols that filter market entry to firms with dedicated regulatory infrastructure. Stakeholders must monitor how reimbursement authority decisions on complex PCI procedure codes in Germany, Japan, and the United States alter site-level capital allocation for CTO-specific device procurement.
Market Dynamics
CTO device economics pivot on the tension between escalating procedural complexity and compressed reimbursement windows, forcing manufacturers to bundle hardware with software-defined planning tools that command recurring revenue streams beyond single-use disposables.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways compress validation timelines from 18 months to under 12 months for novel crossing technologies, accelerating commercialization of next-generation guidewire platforms.
- Japan's aging demographic profile:Patients over 75 now represent 34% of complex PCI candidates in Tokyo and Osaka metropolitan centers, sustaining procedural volumes for multi-vessel CTO interventions.
- Hydrophilic polymer coating advances:Enhanced lubricity profiles enable single-operator procedures, reducing cath lab staffing requirements and expanding treatable patient pools at mid-tier hospitals.
Market Restraints
- Nitinol raw material concentration:Superelastic wire supply chains cluster in three Japanese and German metallurgical suppliers, exposing manufacturers to alloy price volatility and allocation rationing during aerospace demand spikes.
- EU MDR technical documentation burdens:Clinical evidence requirements for Class III devices now mandate 3-year follow-up data, extending recertification cycles and freezing legacy product portfolios.
- Conservative medical management substitution:Optimized anti-anginal pharmacotherapy protocols with ranolazine and trimetazidine reduce symptomatic urgency for revascularization in stable coronary disease patients.
Strategic Opportunities
- India's underserved interventional infrastructure:Tier-2 cities including Pune, Kochi, and Chandigarh lack dedicated CTO operator training programs, creating first-mover advantage for vendors establishing proctoring networks.
- Optical coherence tomography-guidewire convergence:Real-time cap characterization during wire advancement is compressing procedure times and enabling same-day discharge protocols that differentiate premium device bundles.
- Germany's Diagnosis-Related Group refinements:Complex PCI procedure code G-DRG I46Z now reimburses at 2.3x standard PCI rates when CTO lesions exceed 20mm, incentivizing hospital capital allocation toward specialized catheter inventories.
Industry Challenges
- Crossing specialist training pipelines:Japan's Society for Cardiovascular Angiography and Interventions certifies fewer than 40 new CTO operators annually, constraining procedural volume expansion regardless of device availability.
- CE marking transition backlog:Notified body capacity constraints under EU MDR have extended conformity assessment timelines to 14-18 months, delaying product launches and freezing R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Total Occlusion Devices Market |
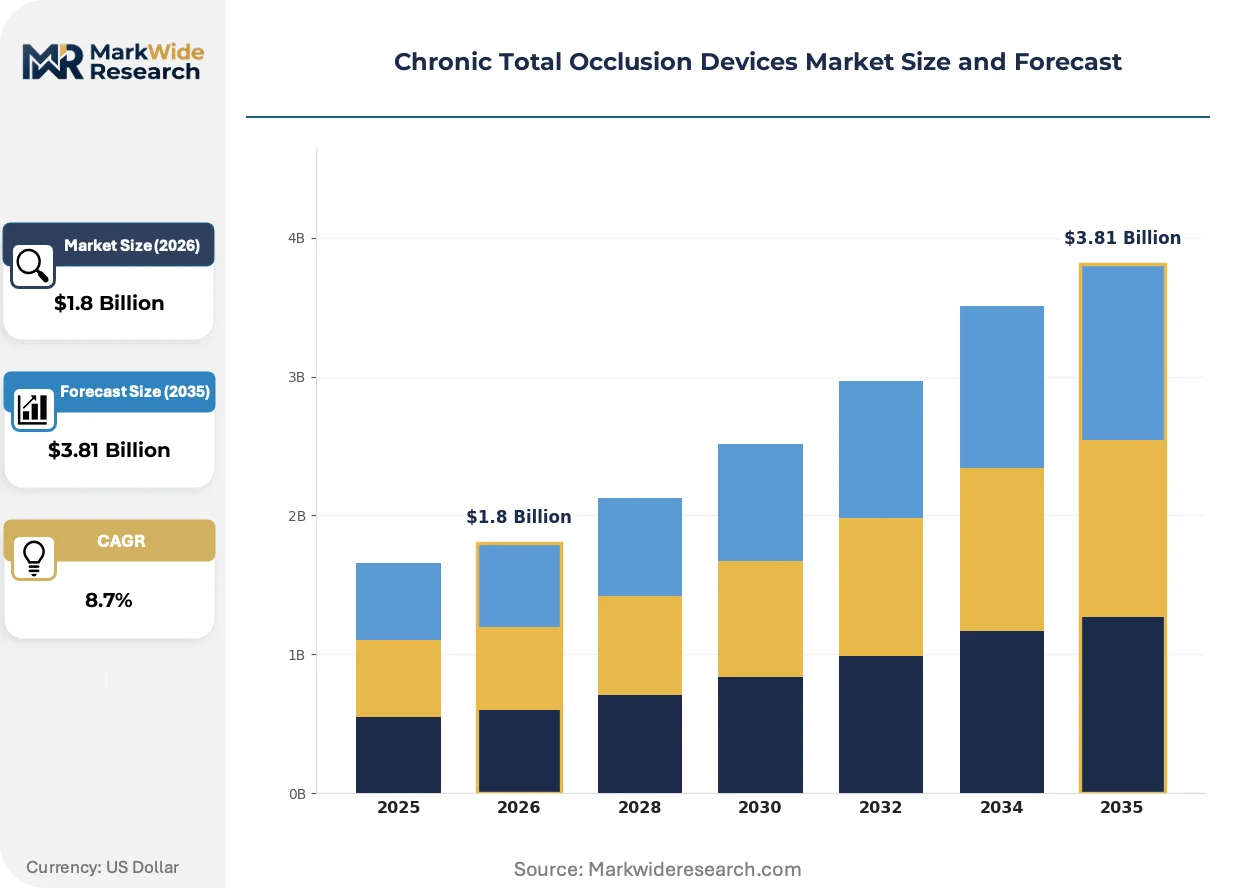
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon Catheters, Stents, Guidewires, Optical Coherence Tomography Application: Coronary Artery Disease, Peripheral Artery Disease, Diabetes Management, Heart Failure End User: Hospitals, Ambulatory Surgical Centers, Cardiology Clinics, Rehabilitation Centers Technology: Embolization, Thrombectomy, IVUS, FFR |
| Companies Covered | Cardinal Health, Inc., Asahi Intecc Co., Ltd., Boston Scientific Corporation, Merit Medical Systems, Inc., Cook Medical, Abbott Laboratories, Terumo Corporation, Becton, Dickinson and Company, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Total Occlusion Devices Market Emerging Trajectories
Device vendors are racing to embed intelligence into hardware, transforming single-use instruments into data-generating assets that anchor recurring software subscriptions and remote proctoring revenue streams.
Polymer-jacketed guidewire platforms with variable stiffness transition zones are rewriting procedural success metrics for antegrade dissection and re-entry techniques. Interventional cardiologists at high-volume US centers now specify polymer-jacketed configurations for 70% of complex CTO cases. This material shift is compressing market share for traditional bare-metal wire architectures and elevating gross margins on next-generation platforms.
EU MDR's enhanced post-market surveillance requirements are forcing manufacturers to maintain active implant registries with 5-year follow-up obligations. Device vendors must now integrate clinical data infrastructure that was previously outsourced to academic research organizations. CTO-specific guidewire and microcatheter portfolios face disproportionate scrutiny due to their Class III risk classification and predicate device reliance strategies.
Hospital procurement committees are consolidating vendor relationships around integrated platform contracts that bundle guidewires, microcatheters, and imaging catheters under single-source agreements. Independent catheter suppliers without vascular imaging portfolios are losing shelf space at US health systems. This concentration pattern is most pronounced in Germany, where hospital procurement alliances now cover 60% of CTO-capable cath labs.
Chronic Total Occlusion Devices Market Segmentation
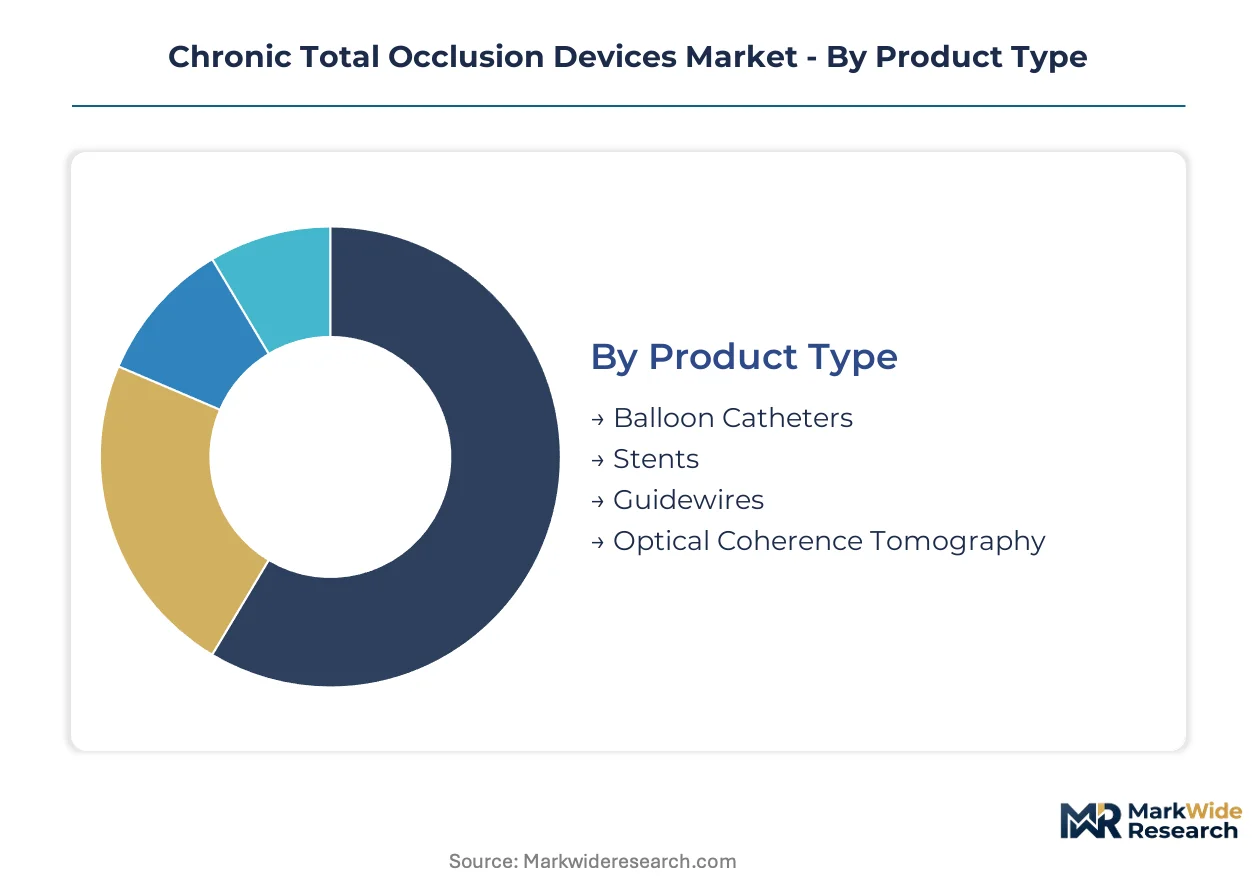
CTO device purchasing decisions fragment across four distinct dimensions, each commanding separate procurement committees and budget lines. Product type determines margin structure and replacement cadence. Application specificity dictates regulatory pathway complexity and clinical evidence requirements.
Product Type:
Supply concentration for nitinol superelastic alloys and hydrophilic polymer coatings clusters among Japanese and German metallurgical suppliers, compressing margin flexibility for finished device manufacturers.
- Guidewires:Polymer-jacketed platforms with variable stiffness transition zones dominate complex antegrade dissection procedures. Demand concentrates in Tokyo, Osaka, and New York metropolitan centers where high-volume CTO operators specify proprietary tip configurations for 70% of cases.
- Balloon Catheters:Commoditized crossing and dilation platforms face pricing pressure from multi-vendor supply agreements. German hospital procurement alliances now bundle balloon procurement with guidewire contracts, squeezing standalone catheter margins.
- Stents:Drug-eluting platforms for CTO lesions require extended landing zone coverage and enhanced radial strength specifications.
- Optical Coherence Tomography:Real-time cap characterization during wire advancement is compressing procedure times and enabling same-day discharge protocols.
Today's leader: Guidewires. Tomorrow's challenger: Optical Coherence Tomography.
Application:
Cost tier differentiation separates premium complex PCI reimbursement codes from standard procedural bundles, reshaping capital allocation across application segments.
- Coronary Artery Disease:Multi-vessel CTO interventions in patients over 75 now represent the procedural volume anchor in Japan's aging demographic profile. Germany's G-DRG I46Z code reimburses at 2.3x standard PCI rates when lesion length exceeds 20mm.
- Peripheral Artery Disease:Limb salvage indications in diabetic populations drive below-the-knee recanalization demand. Volumes are climbing fastest in India's tier-2 cities where interventional infrastructure remains underdeveloped.
- Diabetes Management:Microvascular complication screening protocols increasingly identify asymptomatic CTO candidates for preemptive revascularization.
- Heart Failure:Ischemic cardiomyopathy with viable hibernating myocardium represents an emerging evidence base for CTO recanalization.
Coronary applications capture current revenue concentration. Peripheral indications present the steepest expansion trajectory as diabetic populations age.
End User:
Customer type fragmentation separates capital-intensive tertiary centers from outpatient-focused delivery models, each demanding distinct service bundles and training support.
- Hospitals:Tertiary interventional cardiology suites in the United States, Germany, and Japan anchor CTO procedural volumes. Integrated platform contracts now bundle guidewires, microcatheters, and imaging catheters under single-source agreements covering 60% of German CTO-capable cath labs.
- Ambulatory Surgical Centers:Same-day discharge protocols enabled by OCT-guided procedures are expanding treatable patient pools outside traditional hospital settings.
- Cardiology Clinics:Diagnostic screening and referral networks feed procedural volume to high-volume operator centers.
- Rehabilitation Centers:Post-revascularization functional recovery monitoring creates longitudinal patient touchpoints.
Hospital procurement committees dominate current purchasing authority. Ambulatory Surgical Centers are gaining share fastest as reimbursement shifts toward site-neutral payment models.
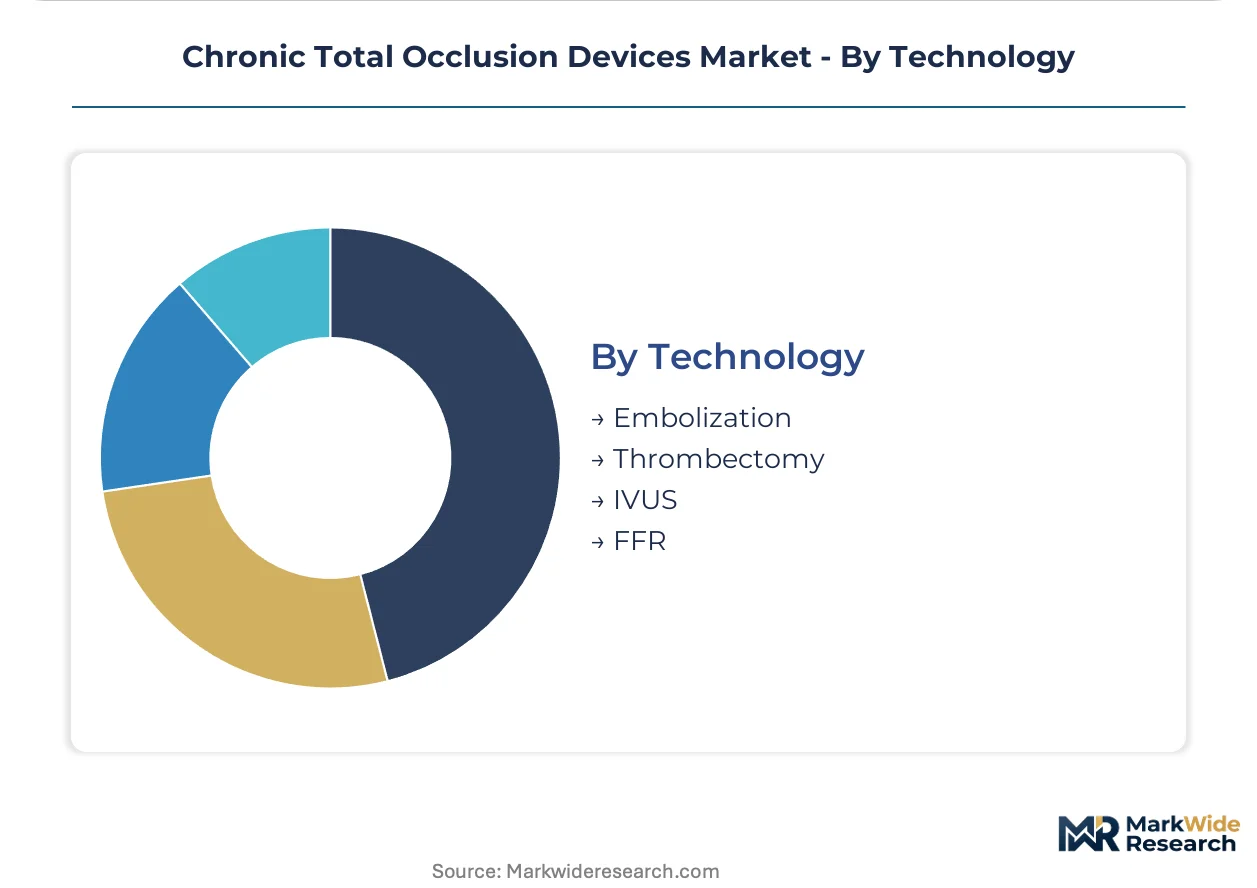
Technology:
Technology maturity curves separate established imaging modalities from emerging physiological assessment tools, with integration timelines varying by regulatory clearance status.
- IVUS:Intravascular ultrasound provides cross-sectional vessel architecture visualization during CTO crossing attempts. Adoption concentrates in Japanese and US centers with established rotational atherectomy programs.
- FFR:Fractional flow reserve measurement validates physiological significance of successfully crossed lesions before stent deployment. Demand is expanding most quickly in Germany where G-DRG refinements incentivize physiological assessment.
- Embolization:Distal protection and side-branch occlusion techniques manage plaque debris during complex recanalization.
- Thrombectomy:Mechanical aspiration platforms address subacute thrombotic components within chronic occlusions.
IVUS maintains installed base leadership. FFR represents the fastest-climbing modality as physiologic guidance displaces angiographic intuition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's G-DRG reimbursement framework generates procedure economics that contrast sharply with Japan's volume-driven operator certification constraints, while the United States maintains the most fragmented site-of-care expansion pattern.
United States
Tertiary hospital cath labs in New York and Boston metropolitan clusters drive polymer-jacketed guidewire procurement for complex antegrade procedures. FDA breakthrough device designation pathways compress validation timelines for novel crossing technologies. High-volume operators at Cleveland Clinic and Mayo Clinic anchor national training networks that shape device specification standards.
Germany
Hospital procurement alliances covering 60% of CTO-capable cath labs concentrate purchasing authority in North Rhine-Westphalia and Bavaria. G-DRG code I46Z reimburses at 2.3x standard PCI rates for lesions exceeding 20mm, incentivizing capital allocation toward specialized catheter inventories. Berlin-Brandenburg and Hamburg academic centers anchor complex PCI referral networks that feed procedural volume from Eastern European catchment areas.
Japan
Patients over 75 represent 34% of complex PCI candidates in Tokyo and Osaka metropolitan centers, sustaining procedural volumes for multi-vessel interventions. PMDA local testing protocols filter market entry to firms with dedicated regulatory infrastructure. The Society for Cardiovascular Angiography and Interventions certifies fewer than 40 new CTO operators annually, constraining volume expansion regardless of device availability.
India
Tier-2 cities including Pune, Kochi, and Chandigarh lack dedicated CTO operator training programs, creating first-mover advantage for vendors establishing proctoring networks. CDSCO import licensing requirements for Class III cardiovascular devices impose additional validation burdens on foreign manufacturers. Maharashtra and Karnataka host the highest concentration of interventional cardiology training programs, generating operator pipelines that feed southern and western regional demand.
China
NMPA local clinical testing protocols and provincial tendering processes fragment procurement patterns across Yangtze River Delta and Pearl River Delta hospital networks. Beijing-Tianjin-Hebei academic medical centers anchor complex PCI training programs that shape national operator certification standards. Provincial volume-based procurement schemes compress pricing premiums for imported guidewire platforms while favoring domestic microcatheter suppliers.
Chronic Total Occlusion Devices Market Vendor Landscape
Top-tier vendors anchor integrated platform ecosystems, while mid-tier specialists compete on single-product differentiation and regional proctoring relationships. The vendor base stratifies across three archetypes: diversified cardiovascular conglomerates with imaging portfolios, guidewire manufacturing specialists with metallurgical capabilities, and catheter platform suppliers pursuing hardware-software convergence. M&A activity concentrates on optical coherence tomography integration assets and remote proctoring service capabilities. Strategic partnerships between device vendors and hospital procurement alliances now determine shelf access at German and US health systems.
Within the diversified cardiovascular conglomerate tier, Abbott Laboratories and Boston Scientific Corporation exemplify integrated platform positioning that bundles hardware with software-defined planning tools. Asahi Intecc Co., Ltd. occupies a specialist position reflecting Japanese metallurgical supply chain proximity. These three entities represent distinct competitive vectors: imaging-anchored ecosystem control, R&D intensity across crossing platforms, and ultra-fine wire manufacturing scale.
| Leading Market Players |
|---|
| Cardinal Health, Inc. |
| Asahi Intecc Co., Ltd. |
| Boston Scientific Corporation |
| Merit Medical Systems, Inc. |
| Cook Medical |
| Abbott Laboratories |
| Terumo Corporation |
| Becton, Dickinson and Company |
| Medtronic plc |
| Others |
Supply Flow & Price Mechanics
Guidewire tier divergence between polymer-jacketed premium platforms and bare-metal commodity alternatives manifests in divergent margin structures and supply chain sourcing strategies. Japan's metallurgical suppliers command pricing power for nitinol superelastic alloys that feed premium wire manufacturing, while standard balloon catheter inputs flow through more dispersed German and Chinese component channels.
Pricing Analysis
Capacity additions in China's nitinol wire processing are reshaping price floors for standard guidewire tiers while premium polymer-jacketed configurations maintain separation through proprietary coating chemistries. Pricing stratifies across premium, standard, and economy tiers with differentiation anchored in FDA breakthrough designation status and hydrophilic polymer performance grades. Cost compression in balloon catheters intensifies as German hospital procurement alliances consolidate purchasing volume. Ambulatory surgical centers exhibit the highest price sensitivity, whereas Tokyo and Osaka tertiary centers prioritize tip technology performance over unit economics.
Supply Chain Analysis
Nitinol superelastic alloy supply rests on Japanese and German metallurgical specialists with hydrophilic polymer coating feedstock concentrated among German chemical producers. Finished device manufacturers draw from Taiwanese precision extrusion houses for microcatheter shaft components and US-based imaging catheter assembly operations. Single-source vulnerability concentrates in nitinol wire supply during aerospace demand allocation cycles. Distribution runs through hospital procurement alliances in Germany, GPO contracts in the United States, and regional distributor networks in India's tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR Class III recertification timelines and FDA breakthrough designation pathways create accelerating competitive moats for prepared manufacturers.
For Market Incumbents: Cement integrated platform positioning by bundling guidewire hardware with OCT imaging catheters and remote proctoring subscriptions that lock hospital procurement committees into multi-year contracts. Backward integration into nitinol wire drawing capabilities insulates margin structures from Japanese supplier allocation rationing. Priority investment in EU MDR technical documentation infrastructure defends against notified body backlog delays that freeze competitor product portfolios. For New Entrants and Emerging Players: The premium-to-economy price gap in India's tier-2 cities creates immediate white-space opportunity for standardized guidewire platforms paired with proctoring service bundles. Pune, Kochi, and Chandigarh hospital systems lack dedicated CTO operator pipelines, making training-enabled device distribution the most penetrable go-to-market angle. Target peripheral artery disease applications in diabetic populations where reimbursement pathways remain less codified than coronary segments. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone catheter suppliers without vascular imaging portfolios lose German and US hospital shelf space to integrated platform vendors. Long-term viability favors manufacturers with captive software-defined planning tools generating recurring revenue beyond single-use hardware cycles. Acquisition target archetypes include OCT-guidewire convergence technology holders and remote proctoring service platforms. The signal to watch is G-DRG reimbursement code refinements in Germany that alter capital allocation thresholds for complex PCI device procurement.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class III recertification timelines determine competitive product availability windows across European hospital networks. |
| Hospital System Partnership | Integrated platform contracts with German procurement alliances secure shelf access covering sixty percent of CTO-capable cath labs. |
| Software Companion Development | Procedural planning tools and remote proctoring services transform hardware vendors into recurring revenue platforms. |
| Reimbursement Strategy | G-DRG I46Z code optimization in Germany directly shapes hospital capital allocation for specialized catheter inventories. |
| FDA Submission | Breakthrough device designation pathways compress validation timelines from eighteen months to under twelve for novel crossing technologies. |
Methodological Framework
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market cluster. The analysis combines structured interviews with interventional cardiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and CMS Medicare procedure data. Bottom-up procedural volume estimates triangulate against top-down device manufacturer revenue disclosures.
Granularity-level modeling disaggregates the analysis window across product type, application specificity, end-user facility category, and technology integration depth. CAGRs derive from segmented volume projections calibrated to demographic aging trajectories, reimbursement code refinements, and operator certification pipeline constraints. Industry-specific forecast inputs incorporate PMDA local testing protocol timelines and NMPA provincial tendering patterns.
Caveats apply where EU MDR notified body capacity constraints or nitinol supply allocation disruptions could materially shift the outlook. Forecasts reflect assumptions regarding reimbursement stability for complex PCI procedures and operator training pipeline expansion rates. A small set of named triggers warrants ongoing watch: G-DRG code refinements in Germany, PMDA accelerated review pathway expansions in Japan, and CDSCO import licensing streamlining in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Peripheral Micro Catheters Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
Veterinary X-Ray Illuminators Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
Medical Pendant Market
Medical Devices
Contact Lenses Market
Medical Devices
Computer-Aided Oral and Maxillofacial Surgery Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
APAC Ablation Devices Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
Bone Fixation Plates Market
Medical Devices
Global Cerebrospinal Fluid Management Devices Market
Medical Devices
Middle East and Africa Surgical Equipment Market