
 Rigid Laparoscope Market | 2026-2036
Rigid Laparoscope Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Laparoscope Market Insights
Modular instrument bundles paired with single-use trocar systems is recalibrating how hospital procurement committees evaluate rigid laparoscope contracts. Olympus Corporation leverages its integrated endoscopy platform to anchor premium service contracts across Japanese and North American hospital networks. KARL STORZ SE & Co. KG sustains dominance in German-speaking European markets through specialized rigid scope manufacturing at its Tuttlingen headquarters. Stryker Corporation competes by extending its surgical visualization portfolio into ambulatory settings with compact tower configurations.
A rigid laparoscope is a straight, non-flexible endoscopic instrument typically constructed from stainless steel or titanium alloy with rod-lens optical systems ranging from 0° to 70° viewing angles, designed to transmit illuminated images from body cavities during minimally invasive diagnostic and surgical procedures. The device serves primarily to enable direct visualization of abdominal and pelvic organs without large incisions, reducing patient recovery time compared to open surgery. Single-port laparoscopes command attention as surgeons push for reduced incision counts in cosmetic-sensitive procedures, while high-definition technology segments attract replacement cycles as hospitals phase out standard-definition towers. Digital imaging technology is displacing fiber optic systems in tertiary hospitals where 4K and 3D visualization improve depth perception during complex dissections.
FDA 510(k) clearance pathways and the EU MDR conformity assessment framework impose clinical evidence requirements that filter out smaller device manufacturers lacking regulatory infrastructure. ISO 13485 quality management standards and IEC 60601 electrical safety specifications further shape product design and market access for rigid laparoscope vendors seeking multi-jurisdiction distribution. Stakeholders must monitor how FDA digital health guidance and EU AI Act risk classifications will apply to emerging computer-assisted visualization features in next-generation surgical scopes.
Market Dynamics
Digital imaging systems are compressing replacement cycles across hospital networks, forcing manufacturers to recalibrate service revenue models around software-enabled scopes rather than hardware durability.
Growth Catalysts
- EU MDR clinical evidence requirements:Stringent post-market surveillance mandates are filtering out marginal competitors, concentrating procurement among vendors with established regulatory infrastructure.
- Ambulatory surgical center expansion:Same-day discharge protocols in United States outpatient facilities are driving demand for compact, portable visualization towers compatible with rigid laparoscope systems.
- 4K resolution adoption:Ultra-high-definition imaging is displacing standard-definition installations in tertiary hospitals, triggering hardware refresh programs.
Market Restraints
- Titanium alloy supply concentration:Japanese and German specialty metal processors control critical raw material inputs for scope construction, exposing manufacturers to input cost volatility.
- FDA 510(k) notification backlog:Extended review timelines for predicate device comparisons delay market entry for novel optical designs.
- Single-port robotic systems:Integrated surgical platforms from Intuitive Surgical and competitors threaten standalone rigid laparoscope utilization in high-volume abdominal procedures.
Strategic Opportunities
- India hospital infrastructure buildout:Government health insurance expansion under Ayushman Bharat is creating installed base opportunities in tier-2 and tier-3 cities.
- AI-assisted visualization convergence:Computer-assisted image enhancement algorithms paired with 4K scopes enable real-time tissue characterization.
- Direct-to-facility distribution:Bypassing traditional medical device distributors reduces channel margin capture and accelerates technical training delivery.
Industry Challenges
- ISO 13485 auditor capacity constraints:Certification body backlogs extend quality management system renewal timelines, freezing product registrations.
- Legacy tower integration complexity:New digital scopes require signal processing upgrades incompatible with analog-era video processors still operational in mid-tier hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Laparoscope Market |
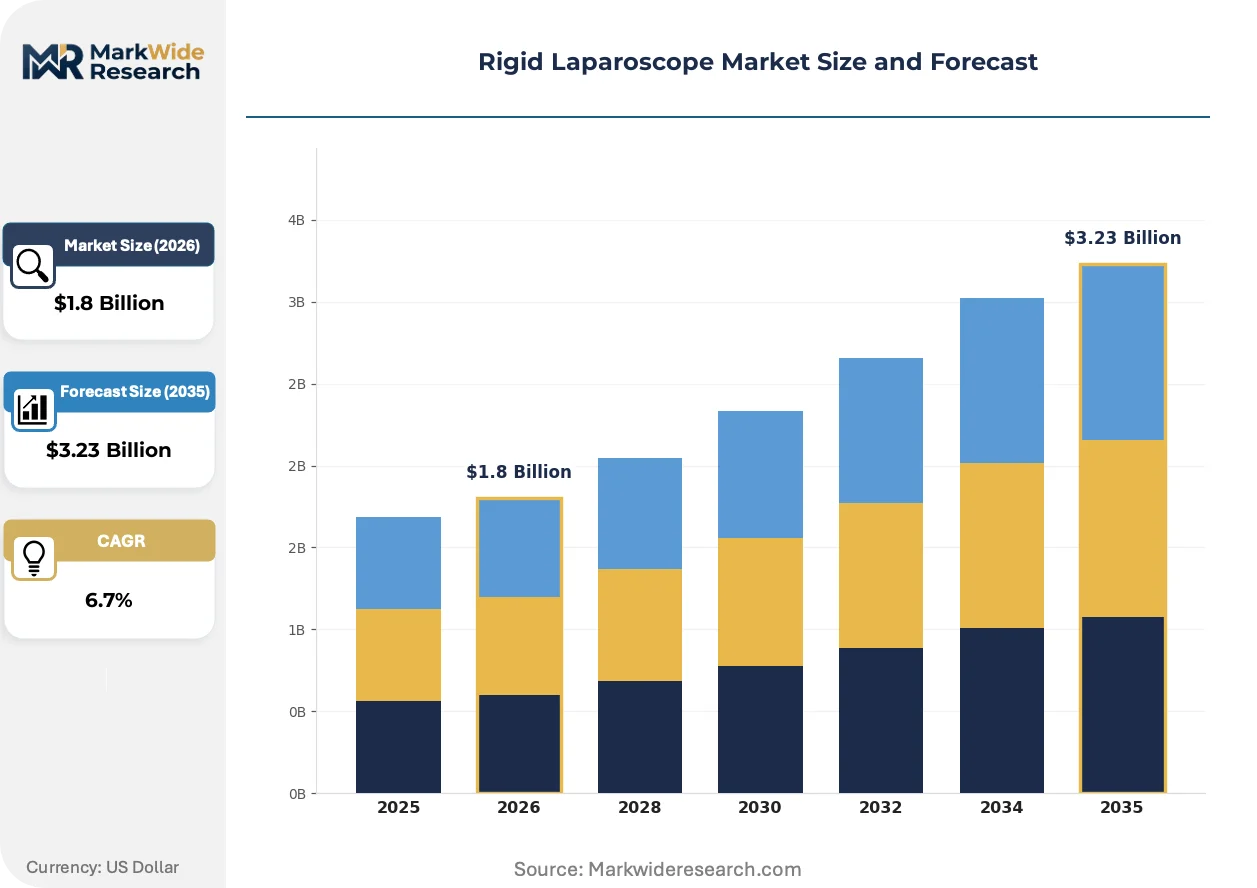
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Port Laparoscopes, Tri-Port Laparoscopes, Variable-Angle Laparoscopes, Custom Laparoscopes End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Laboratories Technology: Optical Technology, Digital Imaging Technology, Fiber Optic Technology, High-Definition Technology Application: Gynecological Surgery, Gastrointestinal Surgery, Urological Surgery, General Surgery |
| Companies Covered | Olympus Corporation, KARL STORZ SE & Co. KG, Stryker Corporation, Medtronic plc, Richard Wolf GmbH, B. Braun Melsungen AG, Smith & Nephew plc, CONMED Corporation, Arthrex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Laparoscope Market Trends and Innovations
Visualization hardware is fragmenting into interoperable components, separating optical capture from image processing and display functions. This decomposition is rewriting vendor-customer relationships and procurement evaluation criteria.
Rod-lens optical assemblies are modularizing into swappable cartridge systems compatible across multiple scope diameters. German university hospitals are piloting these configurations to reduce sterile processing complexity and instrument turnover time. The shift is compressing capital equipment replacement cycles while expanding recurring revenue from disposable optical interfaces.
EU MDR Article 10 post-market clinical follow-up requirements are extending device lifecycle documentation obligations. Manufacturers must now maintain active surveillance registries for each scope model, elevating compliance costs disproportionately for product lines with low shipment volumes. Japanese PMDA is observing these European precedents for potential harmonization in its own device re-registration framework.
Hospital procurement committees are unbundling service contracts from hardware purchases, negotiating separate agreements for preventive maintenance and repair. This behavior is most pronounced in United States integrated delivery networks with centralized supply chain functions. Vendors respond with tiered support offerings calibrated to equipment utilization intensity rather than standard warranty terms.
Rigid Laparoscope Market Segmentation
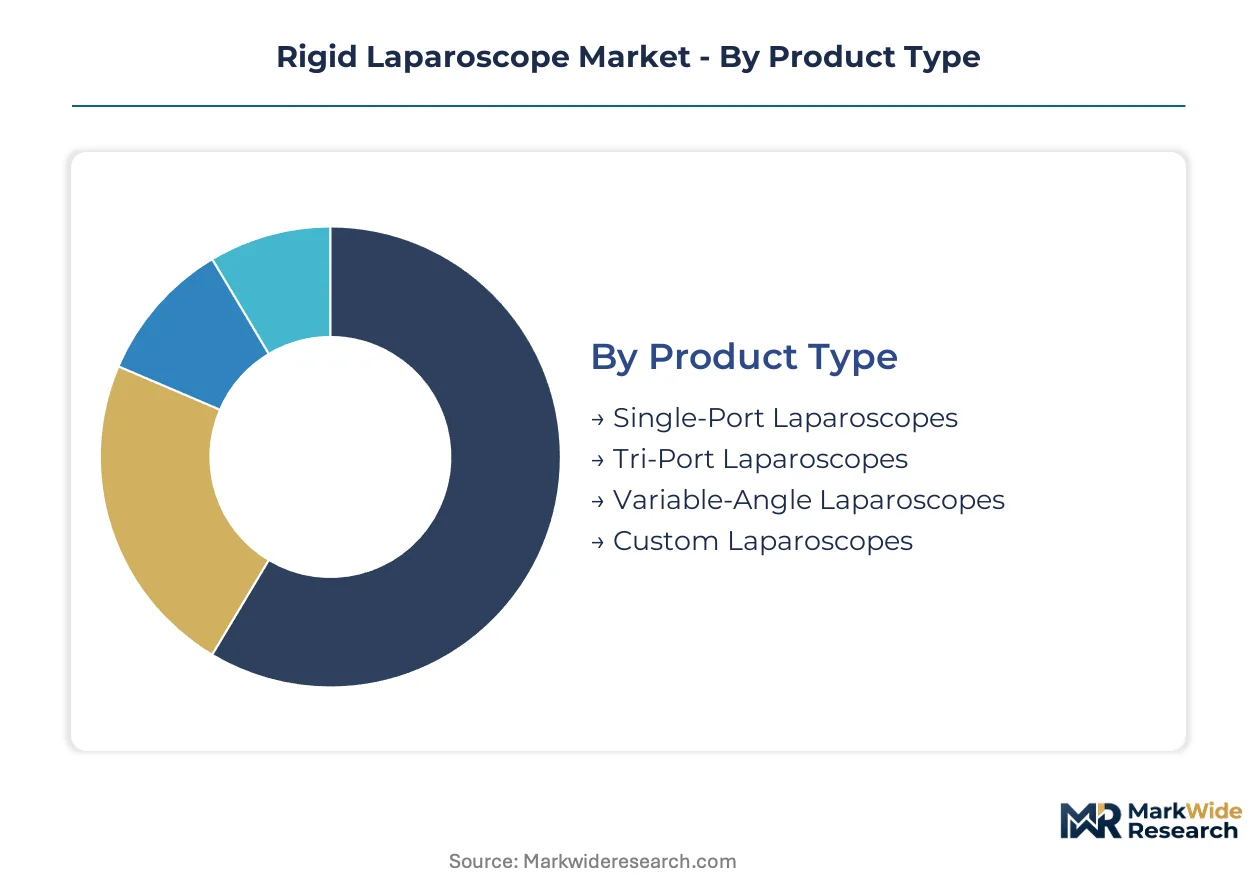
Rigid laparoscope procurement patterns diverge sharply across clinical settings and technical specifications. Hospital capital committees evaluate segments through distinct lenses: upfront equipment cost, sterilization throughput, and compatibility with existing visualization towers. Understanding these segment boundaries clarifies where manufacturers must anchor service contracts versus pursue disposable revenue models.
Product Type:
Capital intensity peaks with variable-angle systems requiring precision-machined articulation mechanisms and specialized optical calibration equipment.
- Single-Port Laparoscopes:These instruments integrate multiple working channels through a single entry point, demanding complex stainless steel or titanium alloy construction with integrated insufflation ports. Demand concentrates in United States cosmetic surgery centers where reduced scar visibility drives patient selection. FDA 510(k) clearance timelines extend for novel port configurations due to predicate device scarcity.
- Variable-Angle Laparoscopes:Rotatable viewing angles from 0° to 70° require rod-lens assemblies with indexed detent mechanisms and sealed bearing systems. German university hospitals lead adoption for complex hepatobiliary procedures where anatomical variation demands optical flexibility. EU MDR technical documentation requirements elevate compliance costs for multi-position locking mechanisms.
- Tri-Port Laparoscopes:Standard three-channel designs dominate general surgery suites with established sterilization protocols.
- Custom Laparoscopes:Bespoke diameter and length specifications serve pediatric and bariatric niche applications.
Most installed capacity flows through Tri-Port Laparoscopes. Expansion is steepest in Single-Port Laparoscopes.
End User:
Procurement authority and utilization intensity separate segments more than technical requirements.
- Hospitals:Tertiary medical centers with dedicated minimally invasive surgery departments drive replacement cycles for 4K-enabled tower systems. United States integrated delivery networks negotiate enterprise-wide service agreements spanning multiple facilities. Capital budgeting cycles typically span five to seven years for visualization infrastructure.
- Ambulatory Surgical Centers:Same-day discharge protocols favor compact, portable tower configurations with rapid sterilization turnaround. Outpatient facilities in United States metropolitan areas are expanding laparoscopic cholecystectomy and hernia repair volumes. Reimbursement pressure from CMS drives demand for lower total cost of ownership equipment.
- Specialty Clinics:Gynecology and urology-focused practices prioritize procedure-specific scope inventories.
- Research Laboratories:Academic medical centers procure experimental configurations for surgical training and device validation studies.
Revenue concentration sits with Hospitals. Volume growth is climbing fastest in Ambulatory Surgical Centers.
Technology:
Digital signal processing requirements create tiered investment thresholds across technology generations.
- Digital Imaging Technology:CMOS and CCD sensor-based systems with integrated image processing enable 4K resolution and 3D depth mapping. Tertiary hospitals in Japan and Germany are phasing out analog-era towers for these configurations. PMDA and EU MDR cybersecurity annexes now apply to network-connected surgical cameras.
- High-Definition Technology:1080p resolution systems represent the replacement sweet spot for mid-tier hospitals balancing visual quality against capital constraints. United States community hospitals with aging standard-definition infrastructure drive upgrade demand. Interoperability with legacy video processors remains a procurement evaluation criterion.
- Optical Technology:Traditional rod-lens systems without electronic capture persist in cost-sensitive markets.
- Fiber Optic Technology:Flexible fiber bundles serve niche applications where scope flexibility outweighs image fidelity requirements.
Shipment volume still routes through High-Definition Technology. Digital Imaging Technology is gaining share fastest as hospitals complete tower modernization programs.
Application:
Procedure reimbursement rates and surgical volume determine equipment utilization intensity across specialties.
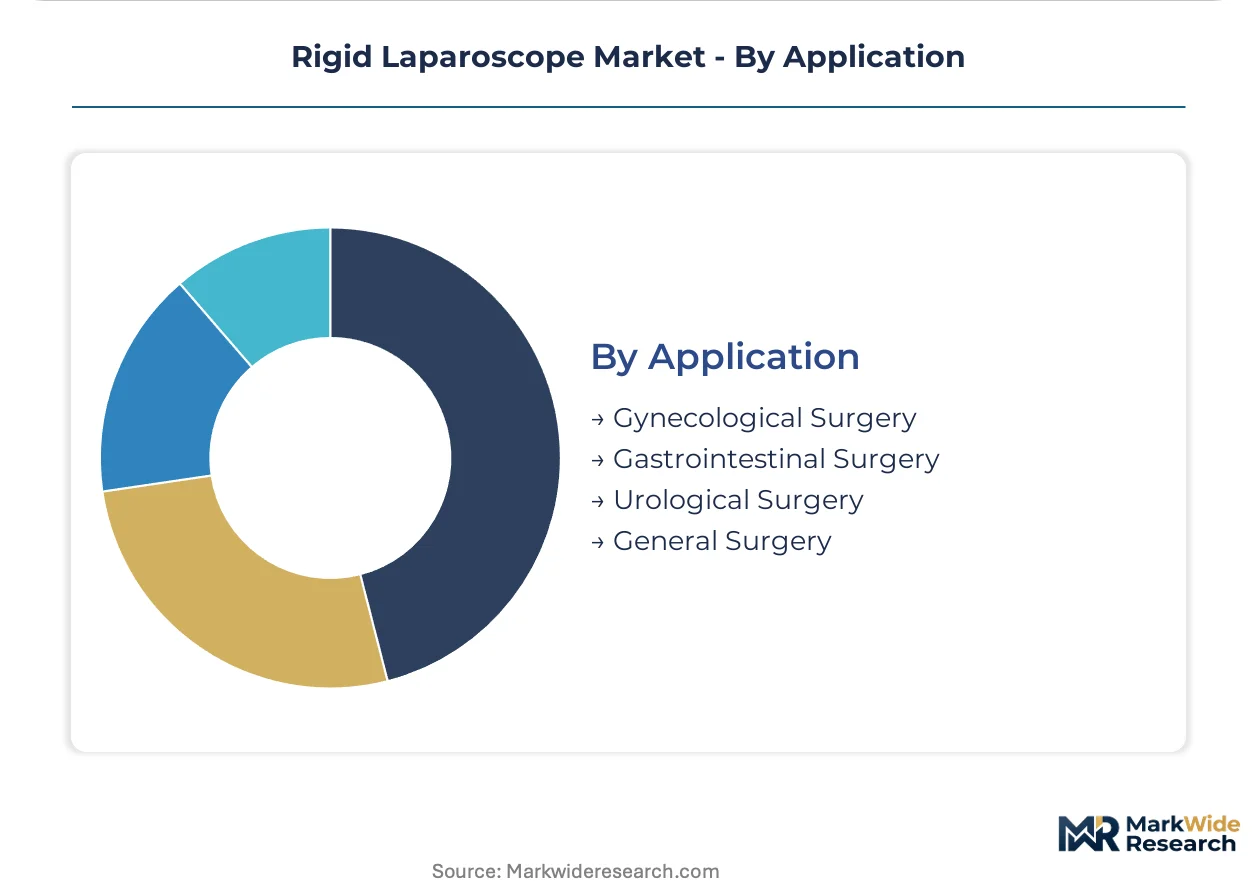
- General Surgery:Cholecystectomy, appendectomy, and hernia repair generate the highest procedure volumes requiring standardized 0° and 30° scope configurations. United States ambulatory surgical centers concentrate demand for rapid-turnover disposable trocar compatibility. Bundled payment models from commercial payers incentivize efficiency-optimized instrument selection.
- Gynecological Surgery:Hysterectomy and ovarian procedures drive demand for 4K visualization to identify ureteral anatomy and minimize thermal injury. Hospital networks in Germany prioritize optical quality for fertility-preserving procedures. Malpractice risk shapes preference for established scope manufacturers with litigation support infrastructure.
- Gastrointestinal Surgery:Colorectal resections and bariatric procedures require extended length scopes and specialized insufflation management.
- Urological Surgery:Prostatectomy and nephrectomy applications favor 0° and 30° angles with integrated irrigation channels.
Procedure volume concentrates in General Surgery. Equipment upgrade urgency is most pronounced in Gynecological Surgery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics manufacturing established the foundational technology for rigid laparoscope systems during the mid-20th century. Rod-lens optical assemblies pioneered in Tuttlingen remain the engineering standard for minimally invasive surgical visualization worldwide.
United States
Ambulatory surgical centers in Texas and Florida are expanding laparoscopic cholecystectomy volumes under CMS same-day discharge protocols. FDA 510(k) notification requirements filter market entry for novel optical designs. The Minneapolis-Saint Paul corridor concentrates service contract negotiations for integrated delivery networks.
Germany
University hospitals in Baden-Württemberg drive adoption of variable-angle systems for complex hepatobiliary procedures. EU MDR conformity assessment frameworks impose clinical evidence requirements that reshape device certification pathways. The Tuttlingen industrial cluster sustains specialized rigid scope manufacturing with vertically integrated optical component supply.
Japan
Metropolitan Tokyo hospitals are phasing out standard-definition towers for 4K-enabled visualization systems. PMDA observes EU MDR post-market surveillance precedents for potential harmonization in device re-registration frameworks. The Nagoya medical device corridor concentrates CMOS sensor integration capabilities for next-generation surgical cameras.
India
Government health insurance expansion under Ayushman Bharat is creating installed base opportunities in Maharashtra and Karnataka tier-2 cities. CDSCO medical device rules classify rigid laparoscopes as Class C devices requiring import license compliance. The Delhi-NCR corridor attracts distribution partnerships for direct-to-facility technical training delivery.
United Kingdom
London integrated care systems negotiate enterprise-wide visualization infrastructure refresh programs spanning multiple hospital sites. MHRA operates under retained EU MDR alignment for post-Brexit device market access. The Cambridge-Oxford arc concentrates research laboratory procurement for experimental surgical training configurations.
Rigid Laparoscope Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory infrastructure depth and service contract anchoring capability. The vendor base stratifies into three tiers: integrated endoscopy platforms, specialized optical manufacturers, and diversified surgical device portfolios. Market structure rewards established regulatory infrastructure over pure product innovation. Dominant competitive moves include unbundling service contracts from hardware purchases and modularizing optical assemblies into swappable cartridge systems.
Within the integrated platform tier, Olympus Corporation and KARL STORZ SE & Co. KG exemplify contrasting geographic anchoring strategies—Olympus occupies a position across Japanese and North American hospital networks while KARL STORZ represents German-speaking European market concentration. Stryker Corporation sits within the diversified surgical portfolio archetype, competing through compact tower configurations calibrated to ambulatory settings. These three entities collectively illustrate how regulatory infrastructure investment and service contract architecture determine sustainable positioning.
| Leading Market Players |
|---|
| Olympus Corporation |
| KARL STORZ SE & Co. KG |
| Stryker Corporation |
| Medtronic plc |
| Richard Wolf GmbH |
| B. Braun Melsungen AG |
| Smith & Nephew plc |
| CONMED Corporation |
| Arthrex, Inc. |
| Others |
Pricing and Supply Chain Analysis
CMS same-day discharge protocols are compressing equipment procurement timelines for United States ambulatory surgical centers, forcing manufacturers to reconfigure production schedules around rapid-turnover tower configurations while absorbing sterilization compatibility testing costs into base pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared 4K-enabled systems from CE-marked high-definition configurations and optical-only instruments for cost-sensitive markets. Price differentiation rests on certification tier and after-sales service bundling. Cost compression in the economy tier is intensifying because Indian and Southeast Asian manufacturers are expanding CMOS sensor integration capabilities. Ambulatory surgical centers exhibit highest price sensitivity; tertiary German university hospitals show lowest.
Supply Chain Analysis
ISO 13485 certification and EU MDR technical documentation requirements gate market access, filtering component suppliers to established German, Japanese, and United States optical manufacturers with quality management infrastructure. Rod-lens optical assemblies draw from titanium alloy processors in Tuttlingen and Nagoya, CMOS sensors from Japanese semiconductor foundries, and sealed bearing systems from German precision engineering specialists. Single-source vulnerability concentrates in specialty metal feedstock for scope construction. Distribution runs through authorized medical device distributors with sterile field training capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage positioning between EU MDR compliance costs in Germany and CDSCO registration pathways in India, where Class C device import licensing creates margin expansion for regulatory infrastructure investments.
For Market Incumbents: Acquire regulatory dossier portfolios from distressed EU MDR transition casualties to consolidate predicate device libraries. Backward integration into titanium alloy processing insulates against Japanese and German specialty metal price volatility. Single-port robotic systems from Intuitive Surgical threaten standalone scope utilization; anchor hospital networks through unbundled service contracts with utilization-based pricing tiers. For New Entrants and Emerging Players: Begin with direct-to-facility distribution in Maharashtra and Karnataka tier-2 cities under Ayushman Bharat infrastructure buildout. India's hospital procurement committees present the most penetrable buyer archetype. Target compact tower configurations for ambulatory surgical centers with rapid sterilization turnaround specifications. Partner with established German or Japanese OEMs for private-label optical cartridge manufacturing. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier manufacturers possessing EU MDR technical documentation but lacking United States FDA 510(k) clearance infrastructure. Long-term viability favors entities with installed base anchoring across multiple hospital networks rather than pure product innovation plays. Watch FDA digital health guidance finalization as inflection indicator for computer-assisted visualization feature monetization.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Establishes predicate device libraries for 4K scope variants across German university hospital networks. |
| Direct-to-Facility Distribution Buildout | Bypasses traditional medical device distributors in Indian tier-2 cities under CDSCO import licensing. |
| Software Companion Development | Positions AI-assisted image enhancement algorithms for PMDA cybersecurity annex compliance in Tokyo metropolitan hospitals. |
| Hospital System Partnership | Secures enterprise-wide service agreements with United States integrated delivery networks in the Minneapolis-Saint Paul corridor. |
| Reimbursement Strategy | Aligns compact tower configurations with CMS same-day discharge protocols for ambulatory surgical centers. |
Research Methodology
Multiple input streams — structured interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; FDA 510(k) filings, EU MDR technical documentation, and CMS Medicare reimbursement data; customs records and hospital procurement databases — were reconciled through bottom-up shipment analysis and top-down market sizing triangulation.
Historical replacement cycle patterns were cross-referenced against panel input from visualization tower manufacturers to anchor growth assumptions across the projection horizon. Segmentation modeling incorporated product type, end user facility tier, technology generation, and application specialty dimensions. CAGRs were derived from installed base expansion rates and hardware refresh program timing. Forecast inputs included PMDA regulatory harmonization signals and Ayushman Bharat infrastructure allocation announcements.
Several conditions sit outside the modeled scope, including unannounced FDA digital health guidance finalization and raw material tariff adjustments. Forecasts reflect documented assumptions about sterilization throughput requirements and ambulatory surgical center expansion trajectories. A model refresh is warranted upon material change in EU MDR post-market clinical follow-up enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Ablation Devices Market
Medical Devices
Snoring Control Devices Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Laser Aesthetic Devices Market
Medical Devices
Asia-Pacific Nerve Repair and Regeneration Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Global Microdermabrasion Devices Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Catheter Systems Market
Medical Devices
Australia Aesthetic Devices Market
Medical Devices
Chest Drainage System Market
Medical Devices
Appendage Management Market