
 Global Wedge Pressure Catheter Market | 2026-2036
Global Wedge Pressure Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wedge Pressure Catheter Market Foresight
The EU Medical Device Regulation is shifting the cost-of-entry calculus for wedge pressure catheter manufacturers seeking CE marking access. Edwards Lifesciences leverages its cardiovascular specialization to sustain premium positioning across European and North American channels. Teleflex Incorporated anchors its competitive stance through integrated vascular access portfolios that span diagnostic and interventional applications. Merit Medical Systems differentiates via manufacturing scale in disposable pressure monitoring kits.
A wedge pressure catheter is a flexible, multi-lumen intravascular device, typically constructed from polyurethane or nylon with embedded pressure transducers or fiber-optic sensors, designed to measure pulmonary capillary wedge pressure during right heart catheterization. The device transmits hemodynamic data through fluid-filled lumens or electronic sensors to external monitoring systems, enabling real-time cardiac function assessment in critical care and catheterization laboratory settings. Balloon-tipped designs dominate procedural volumes due to established clinical familiarity and lower per-procedure cost, while fiber-optic and solid-state segments capture expanding margin pools as hospitals prioritize drift-free accuracy and reduced calibration downtime. Application demand concentrates in cardiac diagnostics and pulmonary pressure monitoring, where reimbursement alignment with heart failure and pulmonary hypertension pathways reinforces utilization.
FDA premarket notification requirements under 21 CFR 870.1200 govern intracardiac pressure transducer safety and electromagnetic compatibility testing, while the EU MDR mandates clinical evidence and post-market surveillance for Class IIa and IIb invasive devices. Japan's PMDA enforces QMS conformity and biocompatibility per ISO 10993 standards for foreign manufacturers seeking market access. Stakeholders must monitor evolving equivalence pathways between FDA breakthrough device designation and EU notified body capacity constraints as these regulatory interfaces reshape commercialization timelines.
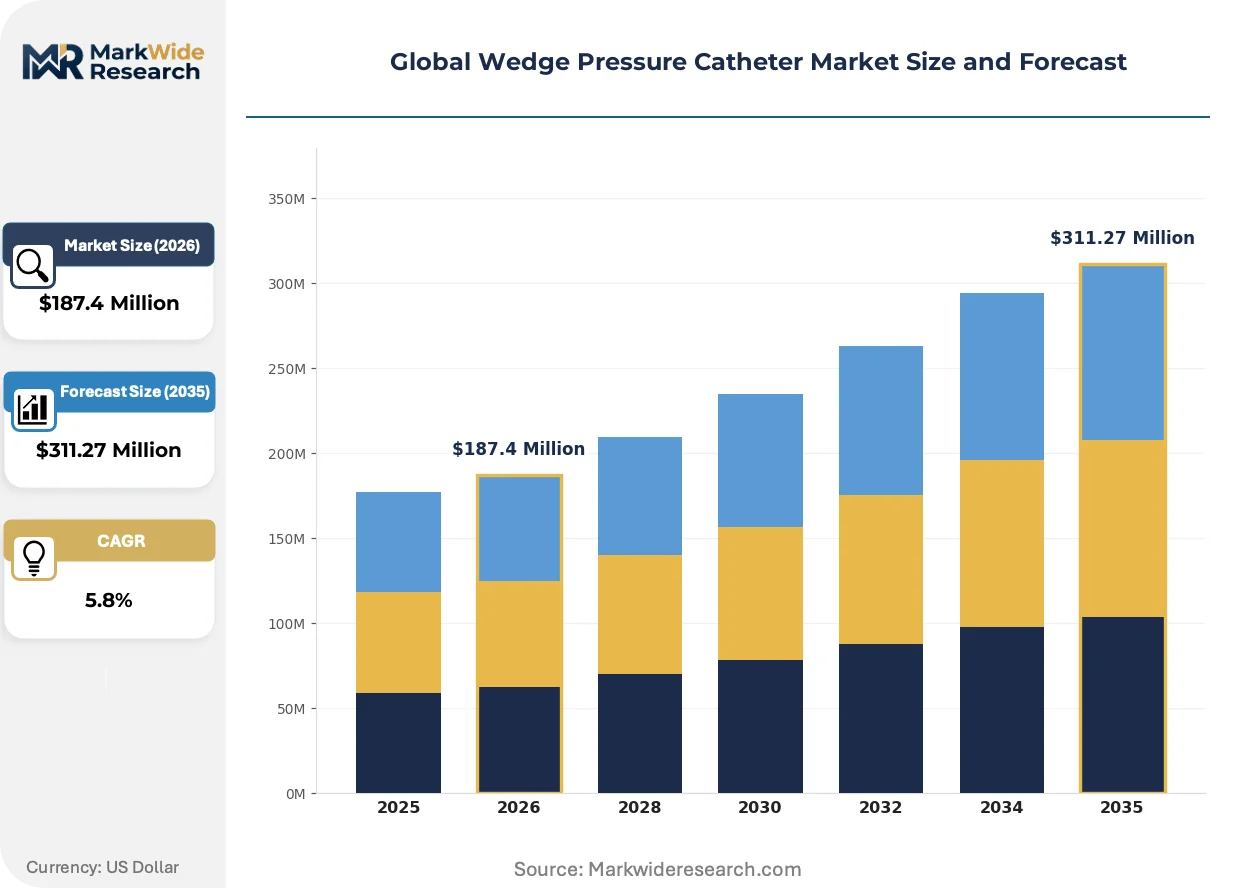
Market Dynamics
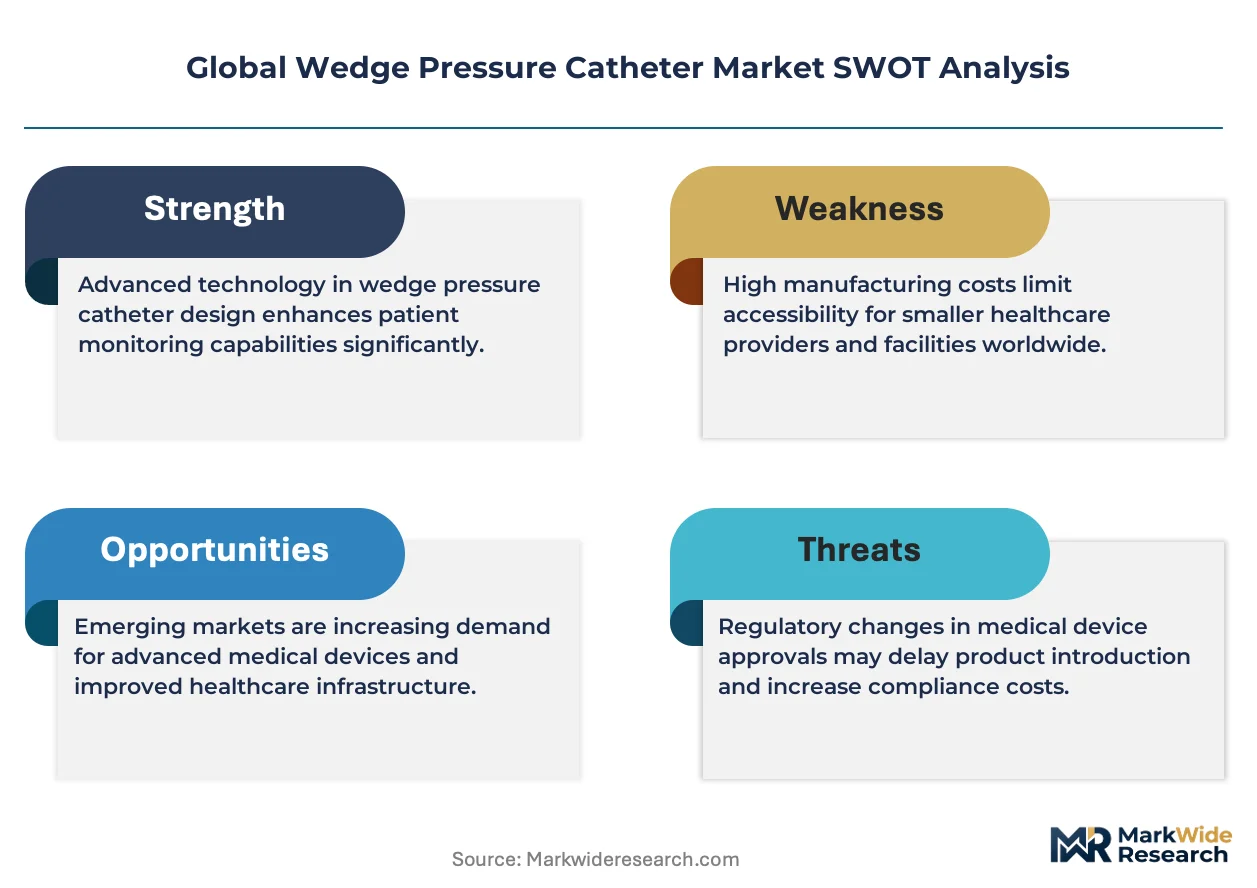
EU MDR biocompatibility mandates are compressing commercialization timelines for wedge pressure catheter manufacturers, forcing dual-track regulatory strategies that prioritize notified body capacity over pure speed-to-market.
Growth Catalysts
- Fiber-optic sensor migration:Tertiary hospitals in Germany and Japan are replacing fluid-filled systems with drift-free solid-state alternatives that eliminate calibration downtime.
- Heart failure reimbursement alignment:US CMS pathway expansions for pulmonary hypertension diagnostics are reinforcing right heart catheterization volumes in cardiac catheterization laboratories.
- ISO 10993-5 cytotoxicity standards:Harmonized biocompatibility testing protocols are reducing redundant validation costs for multi-jurisdiction product launches.
Market Restraints
- Polyurethane resin cost volatility:Medical-grade elastomer feedstock prices fluctuate with petrochemical indices, squeezing margin on balloon-tipped disposable catheters.
- Notified body bottleneck concentration:EU MDR designation capacity clusters among fewer than fifteen accredited organizations, extending CE marking timelines by twelve to eighteen months.
- Non-invasive hemodynamic monitoring:Impedance cardiography and echocardiography advances present substitution pressure for diagnostic wedge pressure indications.
Strategic Opportunities
- India catheterization laboratory buildout:Private hospital chains in Mumbai and Delhi are importing fiber-optic systems ahead of domestic manufacturing scale-up.
- AI-integrated pressure waveform analysis:Machine learning algorithms paired with solid-state transducers enable real-time automated hemodynamic interpretation.
- Japan PMDA QMS ministerial ordinance streamlining:Foreign manufacturer registration pathways are converging with ISO 13485 certification, reducing duplicate audit requirements.
Industry Challenges
- Polymer extrusion technician scarcity:Precision multi-lumen catheter manufacturing requires specialized competencies that outpace vocational training program output.
- FDA 510(k) electromagnetic compatibility testing:IEC 60601-1-2 compliance documentation demands are extending premarket notification preparation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wedge Pressure Catheter Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balloon, Fiber Optic, Microtip, Solid State Application: Cardiac Diagnostics, Pulmonary Pressure Monitoring, Vascular Assessment, Postoperative Care End User: Cardiology Clinics, Diagnostic Labs, Surgical Centers, Research Institutions Technology: Pressure Transducer, Optical Sensor, Microelectromechanical Systems, Piezoelectric Sensor |
| Companies Covered | Alpha Medical Instruments LLC, Advanced Lifesciences Pvt Ltd, Teleflex Incorporated, DeRoyal Industries, ICU Medical Inc, Edwards Lifesciences, B. Braun Melsungen AG, Merit Medical Systems Inc, Nolato AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wedge Pressure Catheter Market Shifts & Advancements
Solid-state pressure sensing architectures are displacing legacy fluid-column transmission in wedge pressure catheters, creating parallel demand strata that reward accuracy premiums over per-procedure cost minimization.
Micro-electromechanical systems (MEMS) pressure transducers embedded in polyurethane catheter shafts deliver drift-free measurements across multi-day intensive care monitoring. Cardiac catheterization laboratories at academic medical centers in the United States and Switzerland are adopting these systems for complex heart failure cases. The technology is expanding into ambulatory surgical centers that previously deferred hemodynamic monitoring due to calibration staffing constraints.
EU MDR Class IIb clinical evidence requirements are mandating post-market surveillance systems that track device-specific adverse events across implantation sites. Manufacturers must maintain electronic data capture infrastructure that interfaces with European competent authority databases. High-risk device categories face expanded notified body audit scopes that delay portfolio refresh cycles.
Hospital procurement committees are consolidating vendor relationships around integrated cardiovascular monitoring portfolios that bundle wedge pressure catheters with arterial lines and central venous access devices. Group purchasing organizations in the United States are negotiating multi-year supply agreements that lock in volume commitments. This concentration is most visible in integrated delivery networks spanning Texas and Florida, where standardization protocols override individual physician preference items.
Global Wedge Pressure Catheter Market Segmentation
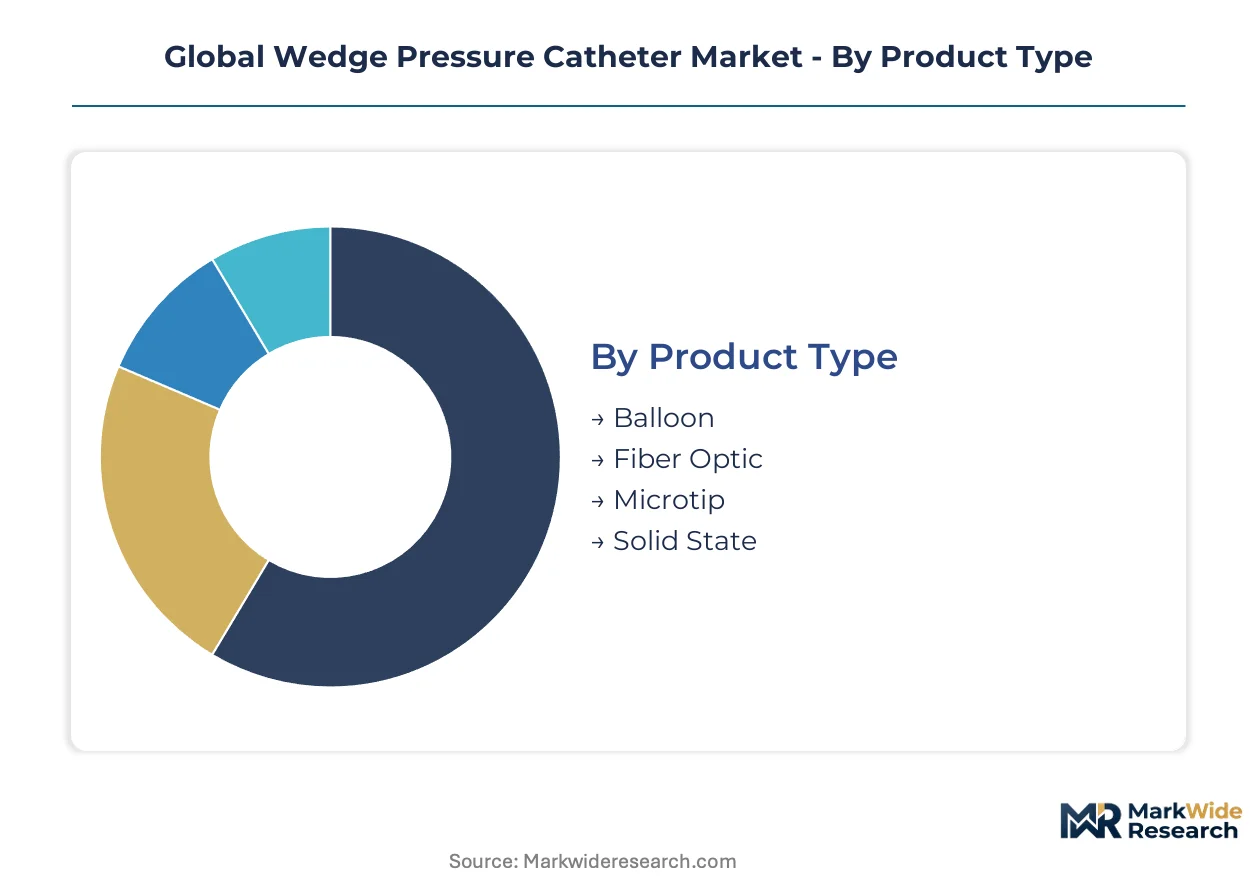
Wedge pressure catheter procurement patterns diverge sharply between high-acuity tertiary settings demanding precision and cost-sensitive environments prioritizing disposability. Understanding these fault lines reveals where margin pools concentrate and which technology transitions will reshape competitive positioning.
Product Type:
Customization intensity spans from commoditized balloon designs to precision-engineered solid-state architectures requiring specialized manufacturing partnerships.
- Balloon:Polyurethane or nylon multi-lumen shafts with inflatable distal tips transmit pressure through fluid-filled columns to external transducers. German and Japanese cardiac catheterization laboratories retain substantial installed bases due to established reimbursement codes and lower per-procedure material costs.
- Fiber Optic:Embedded photonic pressure sensors eliminate hydraulic transmission artifacts and thermal drift across extended monitoring durations. Academic medical centers in Switzerland and the United States are replacing fluid-filled systems in complex heart failure protocols where calibration downtime disrupts critical care workflows.
- Microtip:Miniaturized distal sensing elements enable vascular navigation through tortuous pulmonary anatomy.
- Solid State:MEMS-based transducers integrated into catheter shafts deliver drift-free measurements without external calibration.
Most installed capacity flows through Balloon systems. Expansion is steepest in Fiber Optic.
Application:
Clinical utility concentrates where reimbursement pathways explicitly reward invasive hemodynamic confirmation over non-invasive estimation.
- Cardiac Diagnostics:Right heart catheterization for heart failure phenotyping and valvular disease assessment drives procedural volumes. US CMS pathway expansions for pulmonary hypertension diagnostics reinforce utilization in cardiac catheterization laboratories across Texas and Florida integrated delivery networks.
- Pulmonary Pressure Monitoring:Continuous wedge pressure surveillance during intensive care management of acute decompensated heart failure. Swiss and German tertiary hospitals deploy solid-state catheters for multi-day monitoring where drift-free accuracy guides inotropic and vasodilator titration.
- Vascular Assessment:Hemodynamic profiling during peripheral and coronary interventions.
- Postoperative Care:Surveillance following cardiac surgery or thoracic procedures.
Cardiac Diagnostics commands the dominant revenue share. Pulmonary Pressure Monitoring is climbing the fastest as intensive care units upgrade monitoring infrastructure.
End User:
Capital intensity and regulatory sophistication separate institutional purchasers capable of integrated portfolio negotiations from fragmented standalone operators.
- Cardiology Clinics:Outpatient-focused facilities performing diagnostic right heart catheterizations and hemodynamic assessments. Private clinic chains in Mumbai and Delhi are importing fiber-optic systems ahead of domestic manufacturing scale-up as catheterization laboratory infrastructure expands.
- Diagnostic Labs:Standalone imaging and testing centers without overnight patient capacity. These facilities concentrate on same-day procedures with disposable balloon-tipped catheters due to lower capital requirements and simplified sterilization protocols.
- Surgical Centers:Ambulatory settings performing low-acuity cardiovascular interventions.
- Research Institutions:Academic centers conducting device trials and hemodynamic protocol development.
Cardiology Clinics absorb the majority of procurement volume. Research Institutions are gaining share fastest as clinical trial activity accelerates for next-generation sensor platforms.
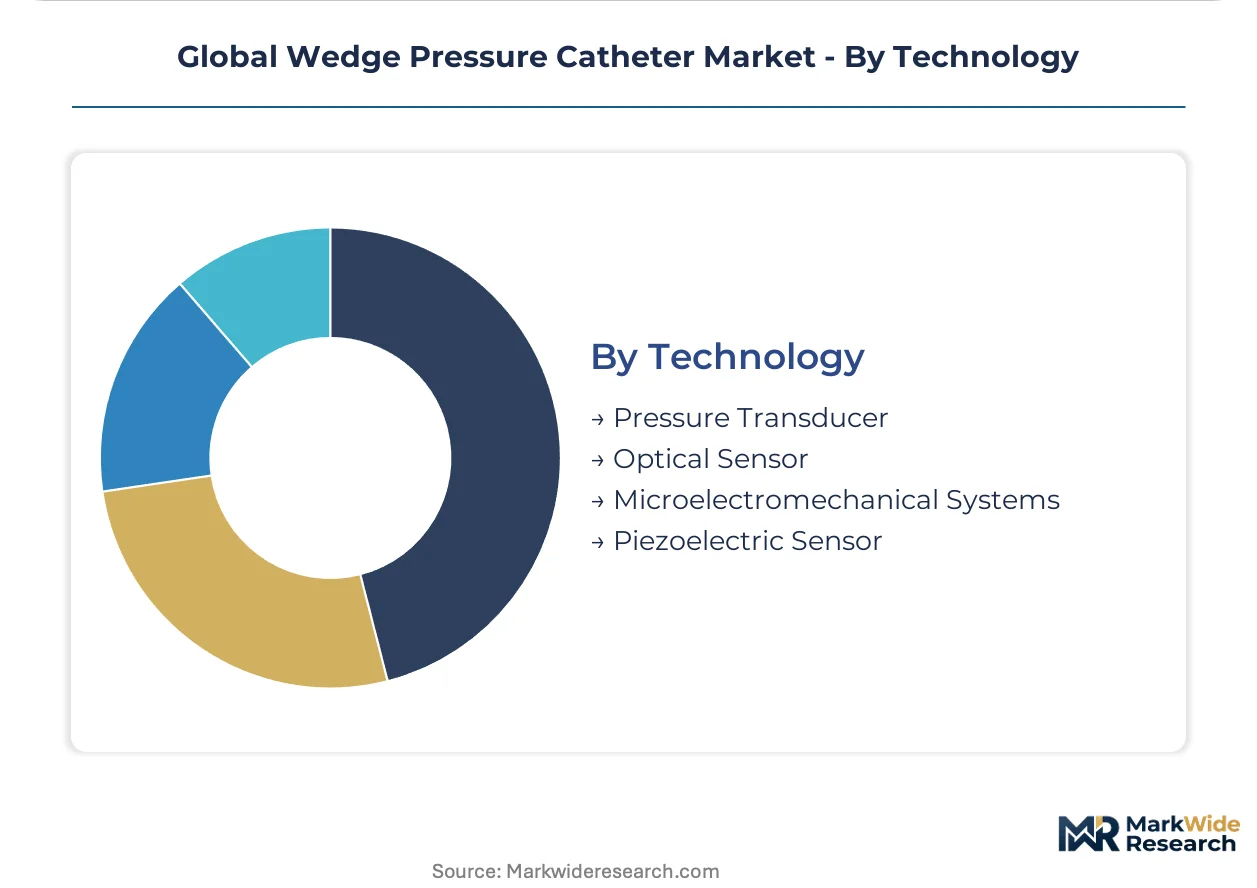
Technology:
Sensor architecture selection determines calibration burden, electromagnetic compatibility requirements, and long-term drift characteristics that shape total cost of ownership.
- Pressure Transducer:External strain-gauge devices coupled to fluid-filled catheter lumens represent the legacy standard. These systems dominate in cost-constrained environments where capital equipment amortization spans decades and technician familiarity reduces training overhead.
- Optical Sensor:Photonic pressure measurement using Fabry-Perot interferometry or similar architectures eliminates electrical interference susceptibility. FDA electromagnetic compatibility testing requirements under IEC 60601-1-2 favor optical approaches in hybrid operating rooms with multiple powered devices.
- Microelectromechanical Systems:Silicon-based MEMS transducers enable miniaturization and batch fabrication economies.
- Piezoelectric Sensor:Ceramic or polymer piezoelectric elements convert mechanical strain to electrical signals.
Pressure Transducer platforms retain the largest installed base. Optical Sensor adoption is expanding most quickly as electromagnetic compatibility compliance costs rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer extrusion technicians and cardiovascular device engineers concentrate in Germany, Switzerland, and the United States, anchoring precision manufacturing clusters that supply tertiary hospitals worldwide.
United States
Texas and Florida integrated delivery networks are consolidating vendor relationships around bundled cardiovascular monitoring portfolios. FDA premarket notification requirements under 21 CFR 870.1200 govern electromagnetic compatibility testing for intracardiac pressure transducers. Academic medical centers in Boston and Houston are deploying solid-state catheter systems for complex heart failure protocols.
Germany
German cardiac catheterization laboratories retain substantial installed bases of balloon-tipped systems due to established reimbursement codes and technician familiarity. EU MDR biocompatibility mandates and notified body capacity constraints are compressing commercialization timelines for new market entrants. Manufacturing clusters in Baden-Württemberg and Bavaria supply fiber-optic catheter components to Swiss and Austrian hospital networks.
Japan
Japanese tertiary hospitals are replacing fluid-filled systems with drift-free solid-state alternatives that eliminate calibration downtime during multi-day intensive care monitoring. PMDA enforces QMS conformity and ISO 10993 biocompatibility standards for foreign manufacturers seeking market access. Tokyo and Osaka academic centers are piloting AI-integrated pressure waveform analysis platforms.
Switzerland
Swiss cardiac catheterization laboratories at university hospitals in Zurich and Geneva are adopting MEMS-based transducer systems for pulmonary hypertension diagnostics. Swissmedic maintains alignment with EU MDR clinical evidence requirements for Class IIb invasive devices. The Basel-Zurich corridor hosts precision sensor component suppliers serving German and French catheter manufacturers.
India
Private hospital chains in Mumbai and Delhi are importing fiber-optic wedge pressure catheter systems ahead of domestic manufacturing scale-up. CDSCO medical device rules are converging with ISO 13485 quality management standards for foreign manufacturer registration. Cardiology clinic procurement is accelerating as catheterization laboratory infrastructure expands in Maharashtra and Karnataka.
Global Wedge Pressure Catheter Market Competitive Landscape
The competitive structure tilts toward diversified cardiovascular device conglomerates with integrated vascular access portfolios. Tier-one positioning requires notified body relationships and multi-jurisdiction regulatory infrastructure that smaller specialists struggle to replicate. Three archetypes dominate: full-line cardiovascular suppliers, precision sensor technology specialists, and disposable kit manufacturers with scale-driven cost positions. M&A activity targets fiber-optic sensor capabilities, while strategic partnerships with academic medical centers secure clinical validation pathways for next-generation platforms.
Among diversified cardiovascular suppliers, Edwards Lifesciences and Teleflex Incorporated exemplify premium-tier positioning through specialized cardiovascular focus and integrated vascular access portfolios respectively. Merit Medical Systems occupies a scale-driven position in disposable pressure monitoring kits. These three companies anchor the competitive landscape by representing distinct strategic vectors: technology specialization, portfolio breadth, and manufacturing scale.
| Leading Market Players |
|---|
| Alpha Medical Instruments LLC |
| Advanced Lifesciences Pvt Ltd |
| Teleflex Incorporated |
| DeRoyal Industries |
| ICU Medical Inc |
| Edwards Lifesciences |
| B. Braun Melsungen AG |
| Merit Medical Systems Inc |
| Nolato AB |
| Others |
Supply & Pricing Matrix
Hospital procurement consolidation into integrated delivery networks across Texas and Florida is forcing catheter manufacturers to restructure pricing around bundled cardiovascular monitoring portfolios rather than standalone device sales, compressing margins on balloon-tipped disposables while creating premium capture opportunities for fiber-optic systems with drift-free accuracy guarantees.
Pricing Analysis
Bundled service contracts versus unbundled per-procedure purchasing splits the market into two pricing strata. Three-tier pricing structure across premium fiber-optic, standard solid-state, and economy balloon-tipped levels reflects FDA breakthrough device designation status and ISO 10993-5 cytotoxicity certification tiers. Price differentiation hinges on calibration-free operation and electromagnetic compatibility compliance costs. Cost compression in the balloon-tipped segment is intensifying because polyurethane resin feedstock prices track volatile petrochemical indices. Diagnostic labs and standalone surgical centers exhibit the highest price sensitivity, while academic medical centers in Boston and Houston prioritize accuracy premiums over per-unit cost.
Supply Chain Analysis
Freight costs for temperature-sensitive polymer resin shipments from Germany and Switzerland to US catheter manufacturing clusters in Massachusetts and Minnesota add measurable landed cost premiums that balloon-tipped disposable producers struggle to pass through. Precision multi-lumen extrusion capacity concentrates in Baden-Württemberg, Bavaria, and the Boston corridor. Raw material dependencies center on medical-grade polyurethane, nylon 12, and MEMS silicon wafers. Single-source vulnerability for fiber-optic sensor components sourced from Swiss precision optics suppliers creates exposure. Distribution runs through group purchasing organization contracts that lock in multi-year volume commitments across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where drift-free accuracy specifications are displacing cost-minimization priorities as intensive care units upgrade monitoring infrastructure for multi-day heart failure surveillance.
For Market Incumbents: Cement notified body relationships ahead of EU MDR Class IIb audit scope expansions that delay portfolio refresh cycles. Deepen backward integration into precision polymer extrusion to offset technician scarcity in multi-lumen catheter manufacturing. Defend against substitution pressure from impedance cardiography by embedding AI-integrated pressure waveform analysis into solid-state platforms.
For New Entrants and Emerging Players: Capture white-space in India's private hospital chains across Mumbai and Delhi where catheterization laboratory buildout is importing fiber-optic systems ahead of domestic manufacturing scale-up. Target CDSCO registration pathways converging with ISO 13485 standards as the most penetrable regulatory entry point. Lead with disposable pressure monitoring kit bundling that mirrors Merit Medical Systems' scale-driven positioning without requiring full cardiovascular portfolio breadth.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision sensor technology specialists holding MEMS fabrication partnerships and FDA electromagnetic compatibility pre-submission histories. Long-term viability hinges on clinical validation pathways secured through academic medical center pilots in Switzerland and Japan. Watch Japan PMDA QMS ministerial ordinance streamlining as the inflection signal for foreign manufacturer registration acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body capacity constraints extend timelines for Class IIb invasive devices by twelve to eighteen months. |
| Hospital System Partnership | Texas and Florida integrated delivery networks consolidate vendor relationships around bundled cardiovascular monitoring portfolios. |
| Software Companion Development | AI-integrated pressure waveform analysis paired with solid-state transducers enables real-time automated hemodynamic interpretation. |
| Reimbursement Strategy | US CMS pathway expansions for pulmonary hypertension diagnostics reinforce right heart catheterization volumes in cardiac catheterization laboratories. |
| FDA Submission | Premarket notification requirements under 21 CFR 870.1200 govern electromagnetic compatibility testing for intracardiac pressure transducers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with catheterization laboratory directors, hospital purchasing committee chairs, biomedical engineers specializing in hemodynamic monitoring, group purchasing organization contracts managers, and regulatory affairs leads at cardiovascular device manufacturers with secondary validation against FDA 510(k) premarket notification databases, EU MDR notified body designation records, CMS Medicare reimbursement pathway documentation, and hospital procurement databases tracking catheter utilization by product type. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from manufacturer revenue disclosures.
Segment-weighting approaches distributed analytical emphasis across product type, application, end user, and technology dimensions, with additional modeling of regional regulatory cluster effects. CAGRs were derived from fitted growth curves across the projection horizon, incorporating catheterization laboratory infrastructure expansion rates, reimbursement pathway alignment indices, and sensor technology substitution elasticities as industry-specific forecast inputs.
Underlying measurement precision varies by segment; fiber-optic and solid-state categories carry tighter precision than commoditized balloon-tipped disposables due to concentrated manufacturer reporting. Forecasts reflect assumptions about EU MDR notified body capacity resolution, polyurethane resin cost stabilization, and non-invasive hemodynamic monitoring substitution rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electrosurgery Devices Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
3D Medical Imaging Devices Market
Medical Devices
Contact Thermometer Market
Medical Devices
Pectus Bar Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
France Minimally Invasive Surgery Devices Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Neuromodulation Market
Medical Devices
Snare Devices Market
Medical Devices
Neurovascular Microcatheter Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
France Anesthesia Devices Market
Medical Devices
Hysterectomy Devices Market