
 Wearable Cardioverter Defibrillators Market | 2026-2036
Wearable Cardioverter Defibrillators Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Cardioverter Defibrillators Market Analytics
Germany is fragmenting as European manufacturers expand wearable cardioverter defibrillator assembly to serve regional demand. ZOLL Medical Corporation leverages its established emergency care distribution network to sustain North American market presence. Medtronic anchors its position through deep cardiac rhythm management expertise and hospital system partnerships. Element Science differentiates via garment-based form factors that improve patient compliance outside clinical settings.
Wearable cardioverter defibrillators are portable, non-invasive electrotherapy devices that continuously monitor cardiac rhythm and deliver high-energy shocks to terminate life-threatening ventricular arrhythmias without transvenous leads. These systems typically incorporate multi-channel ECG sensing arrays, long-life battery packs, and audible or vibration-based patient alerts designed for temporary bridge-to-decision or bridge-to-transplant scenarios. Autonomous devices lead volume shipments due to their self-monitoring capabilities and reduced need for clinical intervention during arrhythmia events. Machine learning integration represents the fastest-expanding technology segment as algorithms improve false-positive rejection and personalized shock-energy optimization.
FDA premarket notification requirements and CE marking under the EU Medical Device Regulation shape product development timelines and commercial launch sequencing across major markets. ISO certification for active implantable medical devices establishes baseline electrical safety and biocompatibility standards that manufacturers must satisfy before regulatory submission. Stakeholders must monitor evolving reimbursement codes and real-world evidence requirements that determine whether wearable defibrillation achieves parity with transvenous ICD coverage in cardiac care pathways.
Market Dynamics
Machine learning algorithms for arrhythmia detection are compressing false-positive rates below clinically acceptable thresholds, forcing manufacturers to reallocate R&D budgets toward predictive analytics capabilities or risk obsolescence in hospital procurement evaluations.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways for wearable defibrillators with novel sensing arrays accelerate commercial launch timelines by 12-18 months compared to standard premarket notification routes.
- Post-MI Bridge-to-Decision Protocols:Cardiac rehabilitation centers in the United States now integrate temporary wearable protection as standard discharge criteria for high-risk myocardial infarction survivors.
- Garment-Based Form Factors:Textile-integrated electrode arrays eliminate vest-style discomfort, improving patient compliance rates during 30-90 day recovery monitoring periods.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery cell manufacturing for medical-grade power packs concentrates in East Asian suppliers, exposing production schedules to raw material allocation constraints.
- CE Marking Under EU MDR:Enhanced clinical evidence requirements for active implantable medical devices extend European commercialization timelines and inflate regulatory submission costs.
- Transvenous ICD Substitution:Miniaturized leadless implantable systems capture permanent protection cases that previously defaulted to extended wearable defibrillator prescriptions.
Strategic Opportunities
- Pediatric Channel Expansion:Underserved congenital heart defect populations in Germany present unmet demand for size-adjusted wearable systems with growth-accommodating electrode positioning.
- Remote Patient Monitoring Convergence:Integration of wearable defibrillation with cloud-based telemetry platforms enables real-time clinician oversight during home-based cardiac rehabilitation.
- Japan PMDA Priority Review:Sakigake designation for life-saving cardiovascular devices offers accelerated approval pathways for manufacturers with Japan-specific clinical datasets.
Industry Challenges
- Algorithm Validation Timelines:Machine learning-based arrhythmia classifiers require extensive retrospective and prospective clinical validation to satisfy FDA premarket submission standards.
- Biocompatibility Certification Complexity:ISO 10993 testing for prolonged skin-contact electrode materials delays product iterations and restricts material sourcing flexibility.
- Reimbursement Code Alignment:CMS category determination processes for wearable defibrillation lag device innovation cycles, creating payment uncertainty for hospital outpatient departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Cardioverter Defibrillators Market |
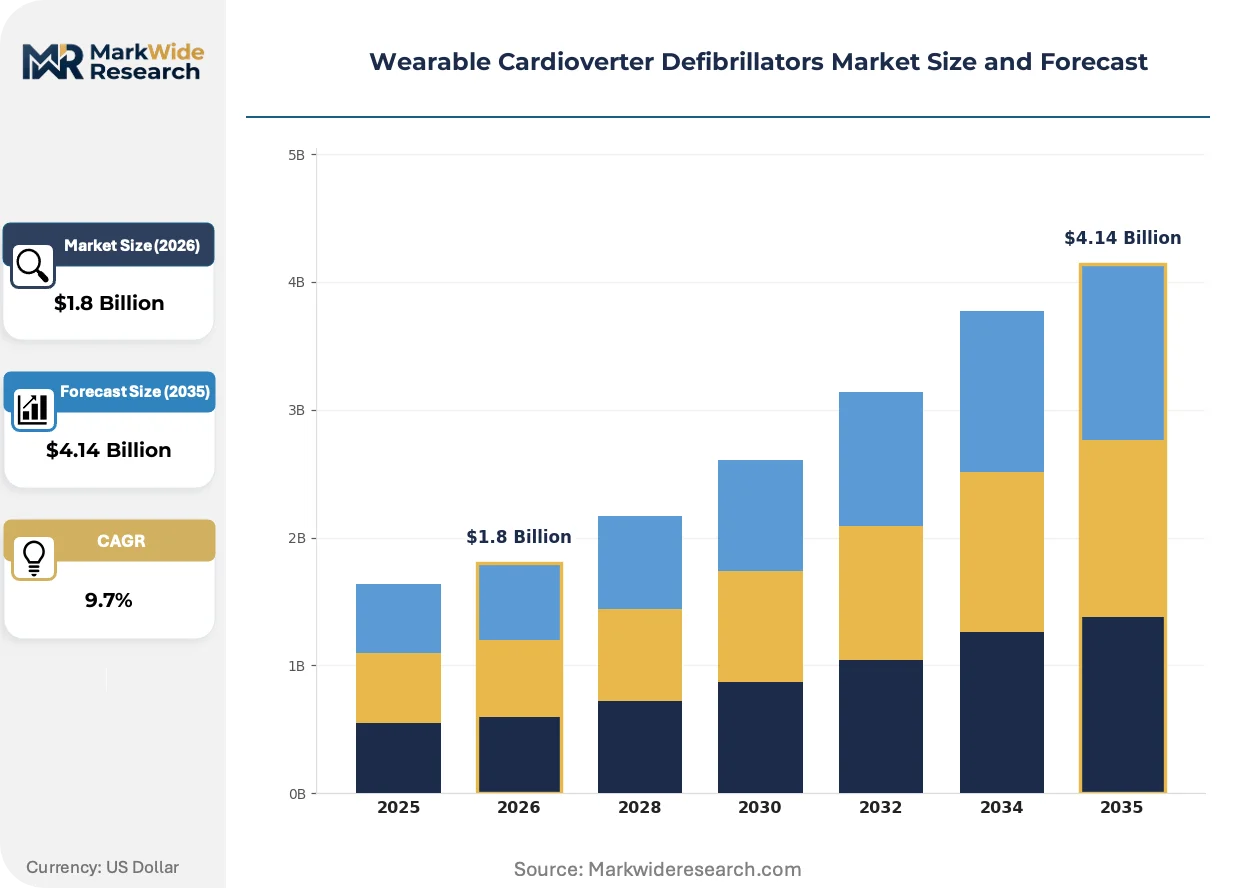
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autonomous Devices, Manual Devices, Hybrid Devices, Smart Wearables End User: Patients, Healthcare Providers, Emergency Responders, Caregivers Technology: Remote Monitoring, Integrated Sensors, Machine Learning, Cloud Connectivity Regulatory Approval: FDA Approved, CE Marked, ISO Certified, Others |
| Companies Covered | ZOLL Medical Corporation, Element Science, Medtronic, Kestra Medical Technologies, Abbott, Boston Scientific Corporation, LivaNova, Koninklijke Philips, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Cardioverter Defibrillators Market Evolving Landscape
Algorithmic sensing improvements and regulatory pathway adaptations are restructuring competitive priorities across the wearable defibrillation landscape. Product development cycles now synchronize with both clinical evidence generation and evolving payer criteria.
Multi-channel ECG processing with embedded neural network inference is rendering obsolete single-lead detection architectures that generated excessive inappropriate shock episodes. Academic medical centers in the United States now specify AI-enhanced rhythm classification as a mandatory procurement criterion. This technical threshold is compressing the addressable market for legacy vest-style devices lacking computational upgrade pathways.
EU Medical Device Regulation harmonization requirements are mandating post-market clinical follow-up studies for all active cardiac devices sold in member states. Manufacturers must establish European-based notified body relationships and maintain periodic safety update reporting. German hospitals are responding by consolidating supplier relationships toward vendors with established MDR compliance infrastructures.
Hospital cardiac rehabilitation departments are unbundling device provision from traditional DME distribution channels. Direct manufacturer partnerships with electrophysiology service lines enable same-day patient fitting and remote monitoring onboarding. This channel restructuring is most visible in United States integrated delivery networks seeking to capture episode-based cardiac care bundled payments.
Wearable Cardioverter Defibrillators Market Segmentation
Wearable cardioverter defibrillator segmentation reveals how clinical workflows, reimbursement pathways, and patient risk profiles shape procurement decisions across hospital systems and outpatient settings.
Product Type:
Mature autonomous platforms dominate hospital procurement, while emerging form factors target compliance-sensitive outpatient populations.
- Autonomous Devices:Self-contained systems with embedded arrhythmia detection algorithms and automatic shock delivery eliminate clinician intervention during cardiac events. Demand concentrates in United States cardiac rehabilitation centers where CMS reimbursement codes favor fully automated temporary protection during post-myocardial infarction recovery periods.
- Manual Devices:Systems requiring clinician or patient activation of defibrillation therapy through physical button presses. Adoption persists in German emergency medical services where paramedic oversight protocols mandate human confirmation before high-energy discharge.
- Hybrid Devices:Configurable platforms allowing switching between autonomous and manual modes based on patient risk stratification.
- Smart Wearables:Garment-integrated form factors with textile electrode arrays and consumer-electronics aesthetics.
Autonomous Devices retain volume leadership; Smart Wearables hold the steepest expansion curve.
End User:
Cost tier differentiation separates institutional purchasers with negotiated device fleets from individual patients bearing out-of-pocket compliance burdens.
- Patients:Individual recipients prescribed wearable defibrillation for 30-90 day bridge-to-decision protocols following myocardial infarction or pending cardiac transplant evaluation. United States integrated delivery networks now bundle device provision into episode-based cardiac care payments, reducing direct cost exposure for high-risk survivors.
- Healthcare Providers:Hospital electrophysiology departments and cardiac rehabilitation centers maintaining device inventories for same-day patient fitting. German hospitals consolidate supplier relationships toward vendors with established EU MDR compliance infrastructures to streamline procurement.
- Emergency Responders:Ambulance services and first-responder units deploying wearable units for field stabilization.
- Caregivers:Family members and home health aides managing device monitoring for post-discharge patients.
Healthcare Providers retain volume leadership; Patients hold the steepest expansion curve.
Technology:
Application specificity determines whether platforms prioritize real-time clinical oversight or algorithmic independence for home-based monitoring.
- Remote Monitoring:Continuous telemetry transmission to cloud-based clinician dashboards enabling intervention during arrhythmia events. United States academic medical centers specify this capability as mandatory procurement criterion for cardiac rehabilitation discharge protocols.
- Machine Learning:Embedded neural networks for rhythm classification and personalized shock-energy optimization. FDA premarket submission standards for algorithm-based devices demand extensive retrospective and prospective clinical validation, extending development timelines.
- Integrated Sensors:Multi-parameter biophysical sensing beyond ECG including accelerometry and impedance pneumography.
- Cloud Connectivity:Data architecture enabling longitudinal patient record integration and population analytics.
Remote Monitoring retains volume leadership; Machine Learning holds the steepest expansion curve.
Regulatory Approval:
Geography-specific certification requirements fragment commercial launch sequencing and limit supplier flexibility across jurisdictions.
- FDA Approved:Premarket notification (510(k)) or premarket approval pathways for United States commercialization. Breakthrough Device Designation accelerates review timelines by 12-18 months for novel sensing arrays.
- CE Marked:EU Medical Device Regulation conformity assessment for European Economic Area market access. Enhanced clinical evidence requirements for active implantable medical devices extend submission costs and timelines.
- ISO Certified:ISO 10993 biocompatibility and ISO 14155 clinical investigation standards establishing baseline safety for international regulatory submissions.
- Others:Japan PMDA Sakigake priority review, Health Canada licensing, and emerging market national regulatory pathways.
FDA Approved retains volume leadership; CE Marked holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals prioritize bridge-to-decision protocols with autonomous devices, while German emergency services favor manual-activation systems requiring paramedic confirmation before shock delivery. Japanese cardiac centers emphasize garment-integrated form factors for home-based recovery monitoring. This consumption-mix differential shapes how manufacturers configure product portfolios across major markets.
United States
Academic medical centers specify AI-enhanced rhythm classification as mandatory procurement criteria, compressing demand toward computationally advanced platforms. FDA Breakthrough Device Designation accelerates review timelines by 12-18 months for novel sensing arrays. The Boston-Cambridge corridor hosts concentrated electrophysiology research activity driving algorithm validation partnerships.
Germany
Cardiac rehabilitation centers integrate temporary wearable protection as standard discharge criteria for high-risk myocardial infarction survivors. EU Medical Device Regulation conformity assessment extends commercialization timelines and inflates regulatory submission costs. The Rhine-Ruhr metropolitan region anchors European manufacturing expansion as domestic producers scale assembly operations.
Japan
PMDA Sakigake priority review designation offers accelerated approval pathways for life-saving cardiovascular devices with Japan-specific clinical datasets. Garment-based form factors with textile electrode arrays improve patient compliance during 30-90 day recovery monitoring periods. The Kanto region surrounding Tokyo concentrates hospital system purchasing decisions and specialist cardiac care capacity.
United Kingdom
National Health Service integrated care boards evaluate wearable defibrillation for episode-based cardiac care bundled payments, reducing direct cost exposure for high-risk survivors. MHRA post-market surveillance requirements align with EU MDR harmonization standards following regulatory divergence. The Oxford-Cambridge-London golden triangle hosts clinical trial infrastructure supporting prospective algorithm validation studies.
Switzerland
Swissmedic certification establishes baseline electrical safety and biocompatibility standards for international regulatory submissions beyond European markets. Miniaturized leadless implantable systems capture permanent protection cases that previously defaulted to extended wearable prescriptions. The Basel-Zurich corridor concentrates medical device engineering expertise and active implantable technology development.
Wearable Cardioverter Defibrillators Market Competitive Landscape
Capability concentration sits with established cardiac rhythm management specialists; scale advantage sits with diversified emergency care conglomerates. The vendor base organizes into three tiers: integrated device manufacturers with deep electrophysiology expertise, emergency medical equipment specialists leveraging distribution infrastructure, and venture-backed innovators pursuing garment-based form factors. Dominant competitive moves include strategic partnerships with hospital system purchasing alliances and technology licensing arrangements for machine learning algorithm integration.
Among North American-based specialists, ZOLL Medical Corporation and Medtronic occupy positions representing the emergency care distribution and cardiac rhythm management archetypes respectively. Element Science exemplifies the garment-integrated innovation tier with textile-electrode configurations. These three entities anchor the competitive structure through contrasting approaches to patient compliance and clinical workflow integration.
| Leading Market Players |
|---|
| ZOLL Medical Corporation |
| Element Science |
| Medtronic |
| Kestra Medical Technologies |
| Abbott |
| Boston Scientific Corporation |
| LivaNova |
| Koninklijke Philips |
| Stryker Corporation |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Rotterdam freight corridors carry lithium-polymer battery cells from East Asian suppliers to German assembly plants, with container rates compressing margins on garment-integrated form factors while autonomous device manufacturers absorb logistics premiums through hospital system volume commitments. This corridor cost dynamic concentrates pricing power among vertically integrated cardiac rhythm management specialists who source medical-grade power packs through captive supplier relationships, forcing smaller garment-based innovators to differentiate through after-sales telemetry bundling rather than hardware margin competition.
Pricing Analysis
United States hospital procurement contracts command 15-25% premiums over German emergency medical service tenders for equivalent autonomous platforms, reflecting CMS reimbursement code generosity versus EU public tender austerity. Pricing stratifies across FDA Breakthrough-designated premium tiers, CE Marked standard tiers, and emerging economy tiers for Indian and Brazilian markets. Cost compression in the standard tier intensifies as leadless ICD substitution erodes bridge-to-decision patient volumes. Emergency responders exhibit highest price sensitivity due to municipal budget constraints; academic medical centers show lowest sensitivity where AI-enhanced rhythm classification is mandatory.
Supply Chain Analysis
Lithium-polymer cathode materials draw from South Korean and Japanese chemical processors, with medical-grade separator films anchored in Taiwanese manufacturing. Printed circuit board assemblies rest on Shenzhen-area electronics clusters, while textile electrode conductive yarns source from Italian and Swiss specialty fiber producers. Single-source vulnerability concentrates in battery cell supply, where three East Asian suppliers control 80% of medical-grade capacity. Distribution runs through hospital GPO contracts in the United States, direct manufacturer partnerships in Germany, and regional distributor networks in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through United States integrated delivery network consolidation, with ten hospital systems now controlling 40% of cardiac rehabilitation device procurement decisions. This consolidation fragments vendor access and rewards manufacturers with established GPO contracting infrastructure.
For Market Incumbents: Pre-empt algorithmic obsolescence by acquiring machine learning validation specialists before FDA premarket submission standards harden around neural network interpretability requirements. Secure backward integration into lithium-polymer cell supply through joint ventures with South Korean chemical processors, insulating production schedules from raw material allocation shocks. Reinforce hospital system partnerships through remote monitoring platform integration that captures episode-based bundled payment economics. For New Entrants and Emerging Players: Pediatric congenital heart defect populations in Germany represent the most penetrable entry point, with size-adjusted wearable systems facing limited competition from established vest-style manufacturers. Garment-based form factors for Japanese home-based recovery monitoring offer second-mover advantage where compliance-sensitive patients reject traditional vest aesthetics. Pursue PMDA Sakigake designation early to accelerate approval timelines against slower-moving incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified emergency care conglomerates seeking to divest non-core cardiac rhythm management assets amid portfolio rationalization pressures. Long-term viability hinges on reimbursement parity achievement with transvenous ICD coverage across major markets. Monitor CMS category determination proceedings for wearable defibrillation as the critical inflection signal; favorable rulings would validate premium pricing sustainability. Cross-checking against EU MDR notified body approval velocity is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates review timelines for novel sensing arrays by 12-18 months versus standard 510(k) pathways. |
| CE Marking Pathway Under EU MDR | Establishes European commercialization legitimacy through enhanced clinical evidence requirements. |
| Hospital System Partnership | Enables same-day patient fitting and remote monitoring onboarding within integrated delivery networks. |
| Software Companion Development | Integrates machine learning algorithms for false-positive rejection and personalized shock-energy optimization. |
| Reimbursement Strategy | Aligns CMS category determination processes with device innovation cycles to secure outpatient department payment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, CMS Medicare reimbursement databases, and EU MDR notified body approval records. Electrophysiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided structured input across United States, German, and Japanese cardiac centers. Secondary validation drew from ClinicalTrials.gov algorithm validation studies, SEC 10-K device segment disclosures, and Japanese PMDA Sakigake designation announcements. Bottom-up patient volume modeling and top-down cardiac rehabilitation expenditure analysis were cross-referenced for triangulation.
Forecast inputs span product type segmentation across autonomous, manual, hybrid, and smart wearable platforms; end-user categories including patients, healthcare providers, emergency responders, and caregivers; and technology dimensions of remote monitoring, machine learning, integrated sensors, and cloud connectivity. CAGRs were derived from regression analysis against historical cardiac event incidence, post-myocardial infarction discharge protocol adoption rates, and reimbursement code expansion trajectories. Key inputs include lithium-polymer battery cost curves and FDA premarket review timeline distributions.
Practitioners should monitor lithium raw material export restrictions, EU MDR post-market clinical follow-up study completion rates, and leadless ICD miniaturization milestones for early signals of forecast revision. Cross-checking against hospital procurement database trend lines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Immunoadsorption Columns Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Vagal Nerve Stimulation (VNS) Market
Medical Devices
Knotless Suture Anchors Market
Medical Devices
3D Printing in Healthcare Market
Medical Devices
Neurovascular Devices Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Italy Respiratory Devices Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Urodynamic Devices Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Global Reflex Hammer Market
Medical Devices
Mexico General Surgical Devices Market
Medical Devices
Germany Ultrasound Devices Market
Medical Devices
Global Medical Composite Market