
 Global Extruded Plastics Market | 2026-2036
Global Extruded Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Extruded Plastics Market Intelligence
The adoption of high-performance polymers for specialized applications is reorganizing the competitive landscape for extruded plastics. SABIC leverages its extensive material science portfolio to supply engineered thermoplastics for demanding end-uses. Dow Inc. specializes in polyethylene and co-extrusion technologies for advanced packaging films. LyondellBasell sustains a strong position through its large-scale production of polypropylene compounds.
Extruded plastics are materials shaped by forcing molten polymer through a die of a specific cross-section. This continuous manufacturing process, often involving single or twin-screw extruders, produces items like pipes, tubing, films, and profiles for industrial and consumer use. Commodity resins like Polyethylene and Polypropylene command the largest volume share due to their widespread use in packaging and consumer goods. The construction application segment, including profiles and insulation, offers higher-margin opportunities for specialized PVC and polystyrene products.
Regulatory frameworks such as the EU's REACH legislation and US EPA rules on volatile organic compounds govern material composition and processing emissions. In China, national GB standards dictate the performance and safety requirements for extruded plastics used in construction and food packaging. Stakeholders must now navigate increasing pressure for material circularity and the development of bio-based or recycled-content feedstocks.
Market Dynamics
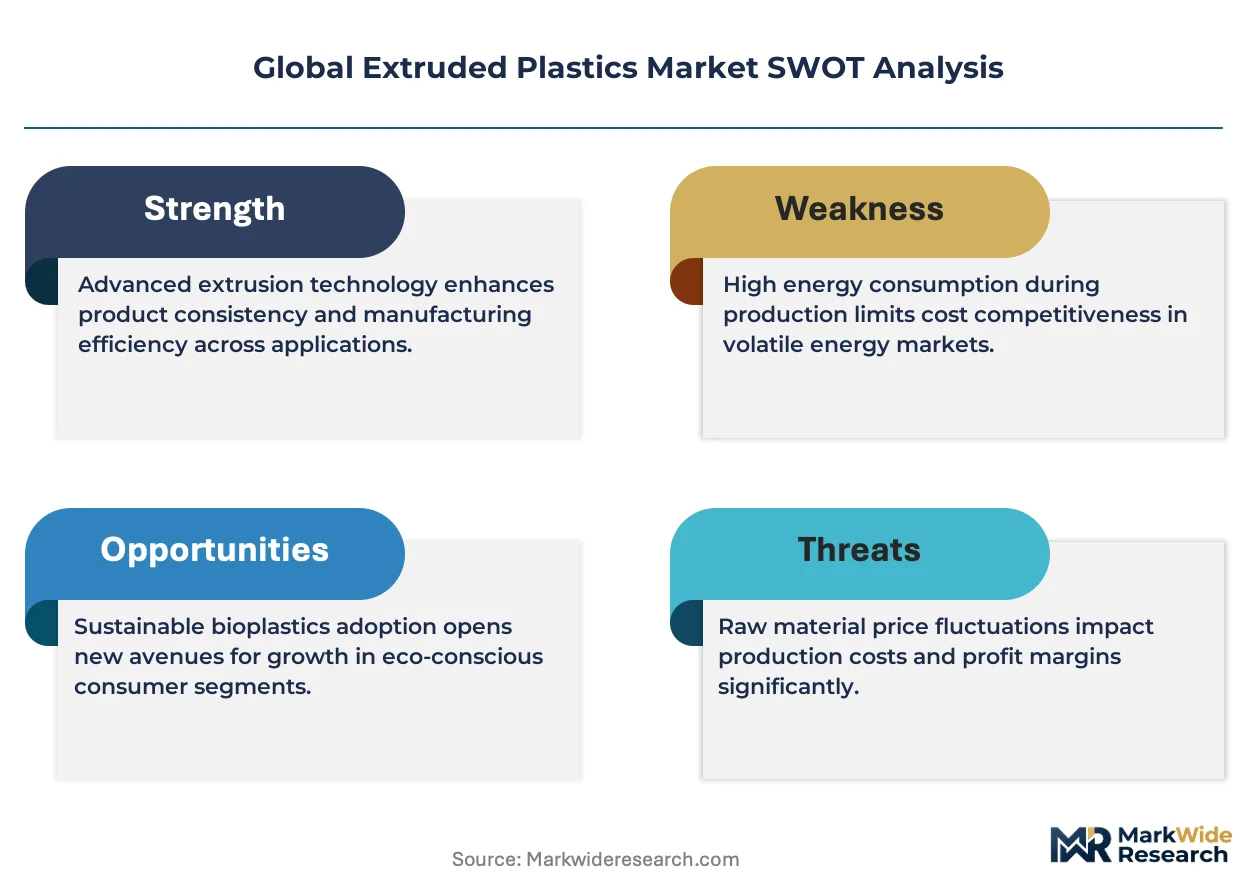
The central structural force shaping the extruded plastics market is the tension between the automotive and construction sectors' demand for lightweight, high-performance materials and a global regulatory push for material circularity, which complicates feedstock sourcing and product end-of-life management.
Growth Catalysts
- Automotive Lightweighting:Vehicle manufacturers are replacing metal with extruded plastic profiles, tubing, and panels to reduce weight and improve fuel efficiency, a trend accelerated by the specific needs of electric vehicle battery systems and thermal management.
- Infrastructure Expansion:Large-scale public works and residential construction projects in countries like India and Brazil create sustained demand for extruded PVC pipes, conduits, siding, and window profiles, supporting high-volume production.
- Advanced Film Technologies:Co-extrusion processes are enabling the creation of multi-layer packaging films with superior barrier properties, extending shelf life for food and medical products and driving adoption over single-layer alternatives.
Market Restraints
- Feedstock Price Volatility:The price of commodity resins like polyethylene and polypropylene is directly tied to volatile crude oil and natural gas markets, creating unpredictable input costs and margin pressure for extrusion companies.
- Substitution by Alternatives:In high-strength applications, extruded plastics face competition from alternative materials such as aluminum composites in construction facades and pultruded fiberglass profiles in industrial settings, limiting market penetration.
- Regulatory Restrictions:The EU's REACH framework and similar regulations in other jurisdictions restrict or ban certain plasticizers, flame retardants, and stabilizers, forcing costly reformulation and re-certification of existing products.
Strategic Opportunities
- Bio-Based and Recycled Feedstocks:Developing capabilities to process bio-polymers like PLA and high-purity post-consumer recycled (PCR) resins opens access to sustainability-focused customers and markets with circular economy mandates.
- Medical and Healthcare Applications:There is an underpenetrated opportunity for precision-extruded, medical-grade tubing, catheters, and fluid bags in the expanding healthcare sectors of Southeast Asia and Latin America.
- High-Performance Polymers:Extrusion of high-temperature and chemically resistant polymers like PEEK and fluoropolymers for demanding aerospace, semiconductor, and chemical processing applications offers significant margin potential.
Industry Challenges
- Recycled Feedstock Quality:A primary operational hurdle is the inconsistent quality and contamination levels in post-consumer recycled plastic streams, which complicates processing and limits use in high-specification applications like food packaging.
- Skilled Labor Scarcity:The industry faces a shortage of technicians with the expertise to operate, maintain, and troubleshoot sophisticated twin-screw extruders, advanced die tooling, and downstream automation equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Extruded Plastics Market |
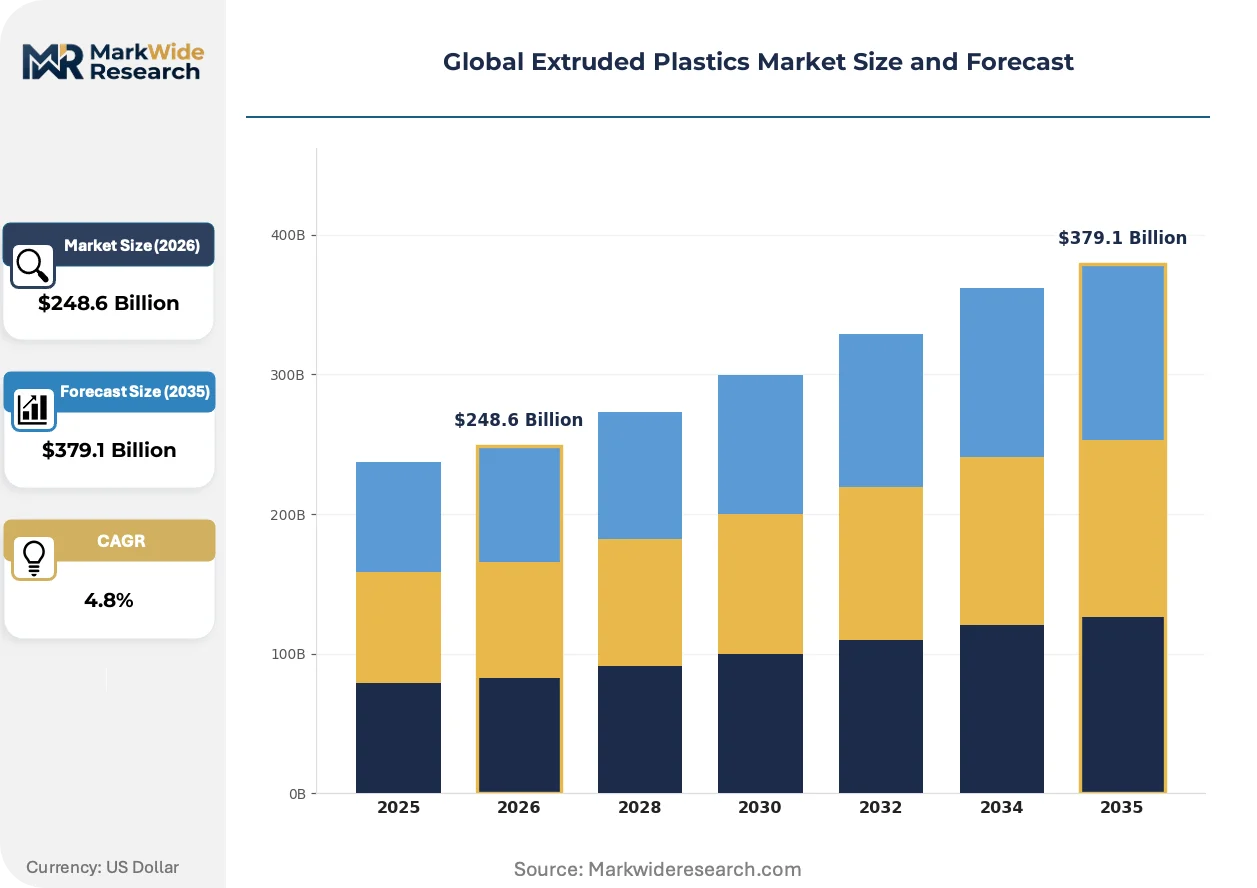
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $379.1 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polyvinyl Chloride, Polypropylene, Polystyrene, Acrylonitrile Butadiene Styrene, Nylon Technology: Single Screw Extrusion, Twin Screw Extrusion, Co-Extrusion, Blown Film Extrusion, Cast Film Extrusion, Sheet Extrusion Application: Packaging, Construction, Electrical Insulation, Agriculture, Consumer Goods, Transportation Components End User Industry: Packaging Manufacturers, Building & Construction Firms, Electronics Producers, Farming Equipment Makers, Household Goods Enterprises, Vehicle Assemblers |
| Companies Covered | LyondellBasell Industries N.V., Berry Global Inc., SABIC, Dow Inc., Formosa Plastics Corporation, BASF SE, ExxonMobil Corporation, Sealed Air Corporation, Sigma Plastics Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Extruded Plastics Market Strategic Shifts & Innovations
Functionality is displacing sheer volume as the primary value driver in extruded plastics. Innovations are concentrated in material science and process control to deliver specific performance characteristics, from enhanced barrier properties in films to precise dimensional tolerances in medical tubing, moving beyond commodity-driven growth.
Advanced Processing and Material Science
Micro-extrusion technology enables the production of components like multi-lumen tubing and fine filaments with micron-level dimensional accuracy. The medical device industry is the primary adopter for manufacturing minimally invasive surgical tools and catheters. This capability is miniaturizing critical components within diagnostic equipment and wearable health sensors, allowing for more compact and sophisticated product designs.
Sustainability and Circular Economy Mandates
Regulatory mandates, including the EU's directives on single-use plastics and packaging waste, are forcing a systemic shift towards circularity. These rules compel manufacturers to incorporate recycled content and design products for recyclability. The polyethylene film and PET sheet segments are most affected, investing heavily in wash lines and sorting technologies to create food-grade recycled feedstocks.
Specification-Driven Procurement
Specification-driven purchasing is becoming standard in the building and construction industry, supplanting traditional relationship-based sales. Architects and engineers now select window profiles, insulation boards, and piping based on certified performance data for thermal resistance, fire retardancy, and acoustic properties. This trend is most advanced in Europe and North America, where stringent building energy codes favor suppliers with documented performance credentials.
Global Extruded Plastics Market Segmentation
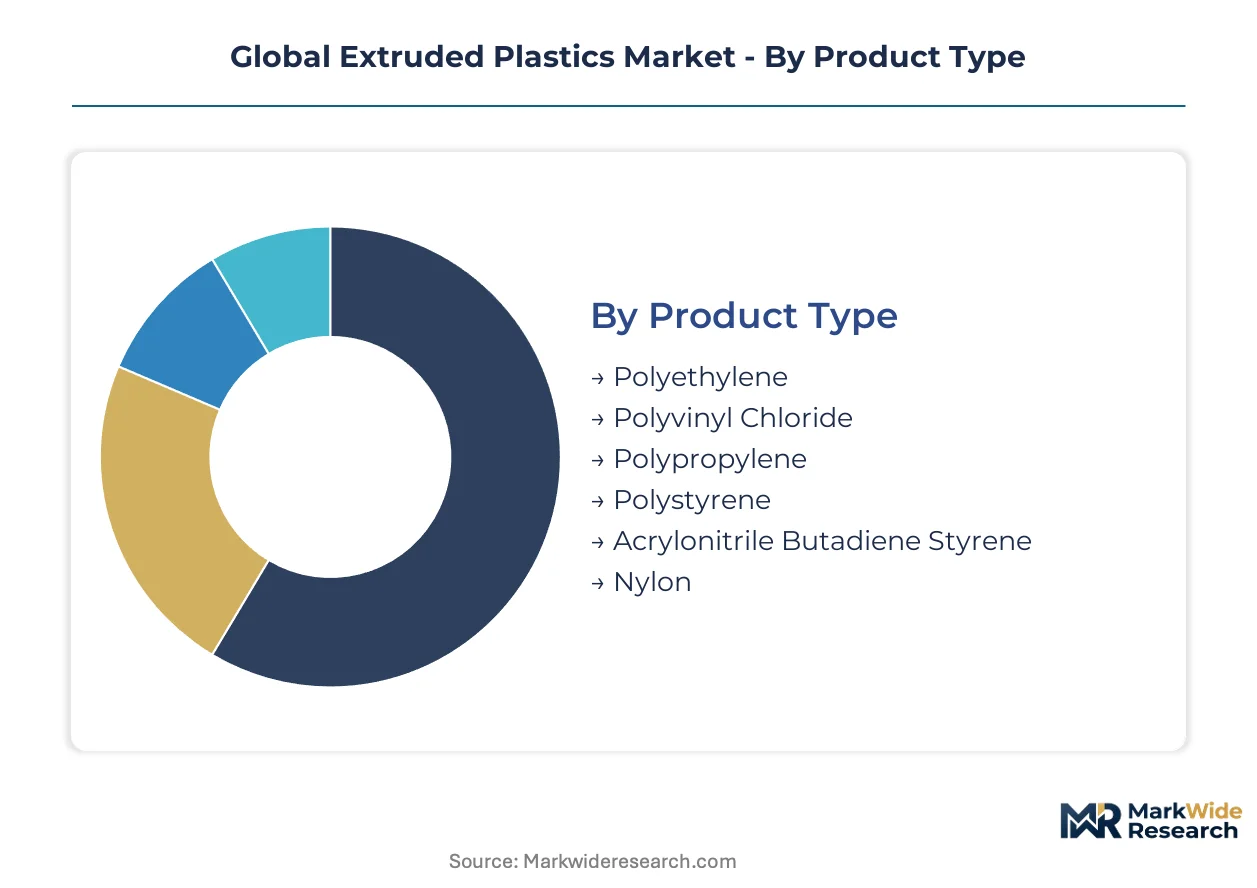
Understanding the segmentation of the global extruded plastics market is crucial for identifying specific growth pockets and competitive battlegrounds. This detailed breakdown highlights the diverse material requirements and processing capabilities that define distinct sub-markets within the broader industry.
Product Type:
The product type segmentation highlights how material substitution pressures influence resin selection for specific performance needs.
- Polyethylene:This thermoplastic polymer offers excellent chemical resistance and flexibility, widely used in films, sheets, and pipes. Demand concentrates in packaging for its barrier properties and in agriculture for irrigation systems.
- Polypropylene:A lightweight thermoplastic known for its high strength-to-weight ratio and fatigue resistance, suitable for structural components. Demand concentrates in automotive for lightweighting and in consumer goods for durable applications.
- Polyvinyl Chloride:A versatile polymer providing rigidity and chemical inertness, extensively used for construction profiles and medical tubing.
- Polystyrene:An amorphous polymer offering clarity and stiffness, primarily for food packaging, disposable items, and insulation boards.
- Acrylonitrile Butadiene Styrene:An impact-resistant engineering thermoplastic favored for consumer electronics housings and automotive interior parts.
- Nylon:A polyamide offering high tensile strength and abrasion resistance, critical for industrial filaments, gears, and automotive components.
Polyethylene anchors the volume base while Acrylonitrile Butadiene Styrene gains share at the steepest rate.
Technology:
The technology segmentation reflects the diverse processing methods required to achieve specific product forms and performance characteristics.
- Twin Screw Extrusion:This process utilizes two intermeshing screws for efficient compounding and devolatilization of complex polymer formulations. Demand concentrates in producing high-performance compounds for engineering applications and recycled plastics processing.
- Co-Extrusion:This technology combines multiple polymer layers into a single structure, enhancing barrier properties, aesthetics, or mechanical strength. Demand concentrates in advanced food packaging films and multi-layer pipe systems for improved functionality.
- Single Screw Extrusion:A foundational process for manufacturing pipes, profiles, and basic sheets, driven by high-volume commodity production.
- Blown Film Extrusion:Produces seamless tubular films for bags, liners, and agricultural covers, emphasizing thinness and strength.
- Cast Film Extrusion:Creates flat, uniform films for packaging, lamination, and medical uses, known for optical clarity and surface finish.
- Sheet Extrusion:Manufactures rigid plastic sheets for thermoforming, signage, and construction panels, requiring precise thickness control.
Co-Extrusion technology enables advanced material layering for superior product performance, influencing innovation across packaging and construction.
Application:
The application segmentation illustrates where the largest volumes of extruded plastics are consumed, driven by essential infrastructure and consumer needs.
- Packaging:This application utilizes extruded films, sheets, and containers to protect and preserve goods, extending shelf life and ensuring safe transport. Demand concentrates in food and beverage sectors for barrier films and rigid containers across global markets.
- Construction:This segment employs extruded pipes, profiles, and insulation boards for building infrastructure, water management, and energy efficiency. Demand concentrates in residential and commercial development projects in emerging economies like India.
- Electrical Insulation:Uses extruded plastics for wire and cable jacketing, protecting electrical systems and ensuring safety in various environments.
- Agriculture:Applies extruded films for greenhouse coverings and irrigation tubing, enhancing crop yield and water management efficiency.
- Consumer Goods:Incorporates extruded profiles and components for household appliances, toys, and recreational equipment.
- Transportation Components:Leverages lightweight extruded plastics for interior trims, fluid lines, and structural elements in vehicles, supporting fuel efficiency.
Packaging applications continue to dominate volume share, while Transportation Components exhibit significant growth due to lightweighting initiatives.
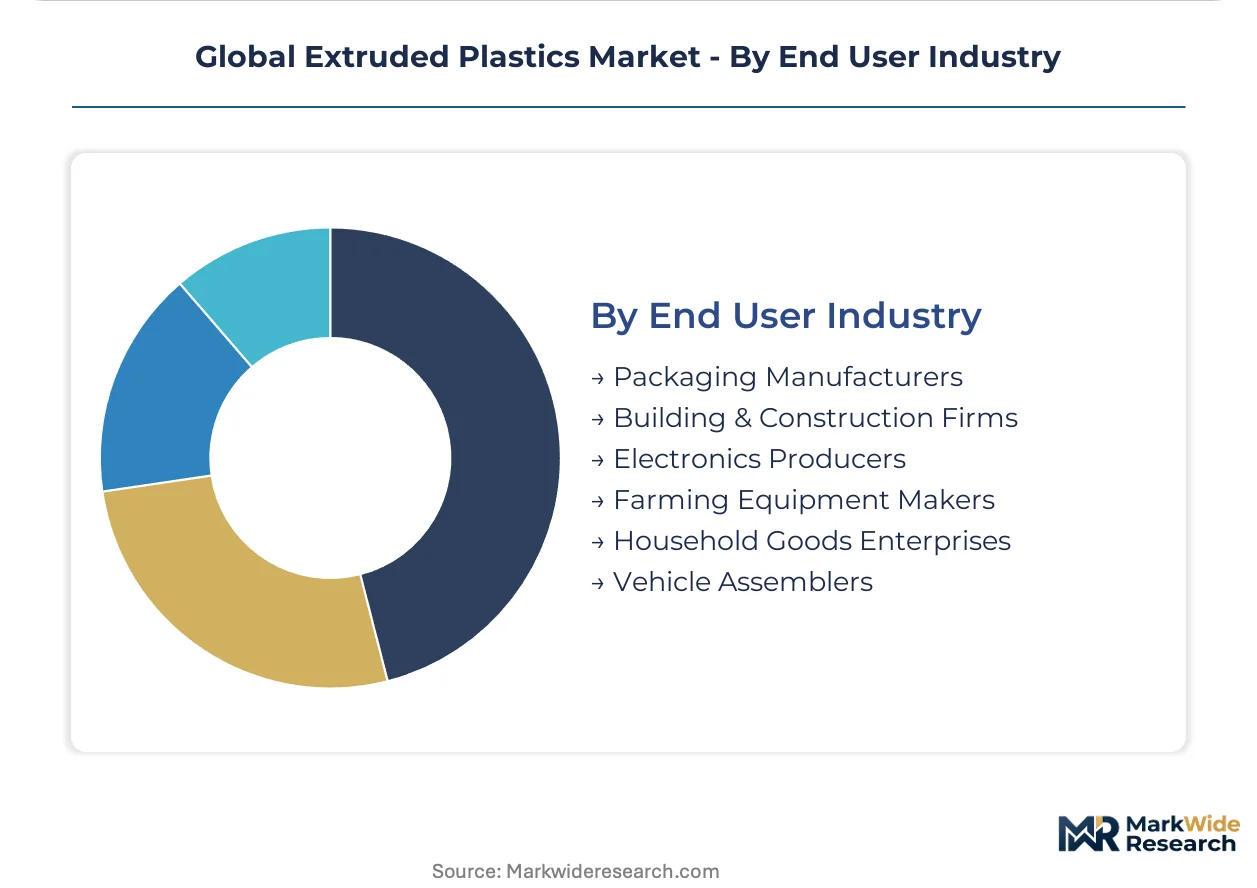
End User Industry:
The end user industry segmentation delineates the primary commercial entities driving procurement decisions and material specifications for extruded plastics.
- Packaging Manufacturers:These firms convert extruded films and sheets into flexible packaging, rigid containers, and protective wraps for diverse products. Their procurement is driven by material cost, barrier properties, and regulatory compliance for food contact.
- Building & Construction Firms:These enterprises specify extruded pipes, window profiles, and insulation materials for new builds and renovation projects. Their procurement is driven by durability, thermal performance, and compliance with local building codes.
- Electronics Producers:Integrate extruded components for cable management, housings, and protective enclosures in electronic devices.
- Farming Equipment Makers:Utilize extruded plastics for irrigation systems, protective covers, and durable components in agricultural machinery.
- Household Goods Enterprises:Source extruded profiles and parts for consumer appliances, furniture, and various home products.
- Vehicle Assemblers:Incorporate extruded plastic tubes, profiles, and interior components to reduce vehicle weight and improve fuel efficiency.
Building & Construction Firms represent a foundational market segment, with Vehicle Assemblers increasingly demanding specialized extruded solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive manufacturing capabilities position it as a significant exporter of extruded plastic components to global markets. This supply chain dynamic influences material availability and pricing across various industries. The country's industrial output drives substantial regional demand.
China
China's rapid infrastructure development and manufacturing activity sustain high demand for extruded plastics. National GB standards dictate the performance and safety requirements for plastics used in construction and food packaging. The Yangtze River Delta region, a major industrial cluster, concentrates significant plastics processing and consumption.
United States
United States demand for extruded plastics stems from its robust automotive sector and extensive construction projects. US EPA rules on volatile organic compounds influence material composition for various applications. The Gulf Coast region, rich in petrochemical production, supports the raw material supply for extrusion companies.
Germany
Germany exhibits strong demand for high-performance extruded plastics in its automotive and specialized industrial sectors. The EU's REACH legislation rigorously governs the chemical composition of polymers and additives. North Rhine-Westphalia, a key industrial hub, hosts numerous advanced materials and plastics processing firms.
India
India's large-scale public works and residential construction projects create sustained demand for extruded PVC pipes and profiles. BIS standards set quality benchmarks for plastic products across various end-uses. Gujarat, a prominent industrial state, serves as a significant center for chemical and plastics manufacturing.
Brazil
Brazil's ongoing infrastructure expansion and growing consumer goods sector drive the consumption of extruded plastics. ANVISA regulations specifically impact the use of plastics in food packaging and medical applications. The industrial heartland around São Paulo concentrates significant plastics conversion and manufacturing activity.
Global Extruded Plastics Market Key Industry Players
Listed leaders compete with private specialists across the extruded plastics value chain, creating a tiered market structure. Large petrochemical conglomerates often operate alongside niche fabricators focusing on specific applications. Strategic archetypes include integrated material suppliers, specialized film producers, and profile manufacturers. Dominant competitive moves involve capacity expansion and targeted mergers and acquisitions.
Within the integrated material supplier archetype, LyondellBasell Industries N.V. exemplifies large-scale polypropylene production, a material critical for automotive and consumer goods. Dow Inc., a US-based corporation, anchors the advanced packaging film segment through its polyethylene and co-extrusion technologies, serving critical food and medical product needs. SABIC, a Saudi Arabian company, represents the high-performance polymer sector with its extensive material science portfolio, catering to demanding end-uses in aerospace, semiconductor, and chemical processing applications.
| Leading Market Players |
|---|
| LyondellBasell Industries N.V. |
| Berry Global Inc. |
| SABIC |
| Dow Inc. |
| Formosa Plastics Corporation |
| BASF SE |
| ExxonMobil Corporation |
| Sealed Air Corporation |
| Sigma Plastics Group |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements for commodity resins like polyethylene and polypropylene lock in supply access and provide price visibility for large-volume buyers. This structure mitigates some volatility for major processors.
Pricing Analysis
Pricing for advanced co-extrusion technologies commands a premium over single-screw extrusion for commodity products. Value-based pricing applies to specialized applications like medical tubing, reflecting stringent certification levels and customization. Commodity resins often trade on contract-based long-term offtake, but feedstock price volatility exerts downward pressure on margins. Packaging manufacturers are highly price-sensitive, while aerospace and medical sectors prioritize performance over cost.
Supply Chain Analysis
China's extensive manufacturing capabilities position it as a significant exporter of extruded plastic components, influencing global material availability. The United States and Germany also contribute substantial volumes of specialized polymers. The industry draws from petrochemical inputs such as polyethylene and polypropylene, whose prices are tied to crude oil markets. Commodity price volatility remains a structural risk, impacting input costs for processors globally. Distribution runs through direct sales channels to large industrial buyers and a network of specialized distributors for smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The extruded plastics market presents a capability-scarcity story, particularly concerning the expertise required to operate and maintain sophisticated twin-screw extruders. This specialized knowledge dictates processing efficiency and product quality.
For Market Incumbents:Fortify core processing capabilities by investing in advanced co-extrusion and micro-extrusion technologies to meet demanding application specifications. Secure long-term feedstock agreements for high-purity recycled and bio-based polymers to mitigate regulatory pressure for material circularity. Pursue certifications for food-grade recycled content to expand market access and sustain margin.
For New Entrants and Emerging Players:Lead with specialized capabilities in precision micro-extrusion for medical-grade tubing and high-temperature polymers like PEEK for aerospace. The underpenetrated healthcare sectors of Southeast Asia offer a viable entry point for these high-margin products. A sustainability-focused go-to-market angle, emphasizing bio-based or high-purity recycled materials, can differentiate offerings.
For Investors and Strategic Acquirers:Recurring-revenue conversion is highest among specialized fabricators providing critical components for long-lifecycle assets like medical devices or infrastructure. Long-term viability over a 5-10 year window favors companies with proven capabilities in high-performance polymers or advanced recycling processes. Acquisition targets should include niche players with strong intellectual property in bio-based materials or precision extrusion. Investment in advanced sorting and washing technologies for recycled plastics signals market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Addresses sustained demand from infrastructure projects in India and residential construction. |
| Green Manufacturing Transition | Aligns with EU's directives on single-use plastics and packaging waste. |
| Long-term Supply Agreement | Secures access to high-purity post-consumer recycled (PCR) resins for critical applications. |
| Product Launch | Introduces precision-extruded medical-grade tubing to expanding healthcare sectors. |
| Acquisition of Specialist Firm | Integrates micro-extrusion technology for miniaturized diagnostic equipment components. |
Research Approach
Operator-level perspectives from plant managers, R&D directors, procurement leads, and automotive engineers anchored the qualitative base for this study. Primary interviews with industry stakeholders were combined with extensive secondary validation from various sources. Secondary data included national GB standards, EU REACH legislation, US EPA rules, and specialized industry association reports. Bottom-up market sizing was triangulated against top-down industry revenue figures.
Sensitivity analysis informed the projection of market trajectories across the analysis window, accounting for various macroeconomic scenarios. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and regional market maturity. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key forecast inputs included crude oil prices and global construction spending.
Forecasts assume regulatory continuity in the EU, US, and China; material policy shifts would require re-modeling. The projections reflect assumptions regarding feedstock price stability, trade policy, and the pace of new environmental regulations. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Augmented Reality in Retail Market
Others
Japan Automotive LED Lighting Market
Others
Hypersensitivity Market
Others
Smart Home and Office Market
Others
Transportation Lighting Market
Others
Global Duty-Free Retailing Market
Others
Global Injectable Nanomedicine Market
Others
Inflight Entertainment Solutions Market
Others
Mobile Computing Devices Market
Others
Middle East & Africa Air Insulated Switchgear Market
Others
Global Military Lighting Market
Others
Radar Speed Signs Market
Others
Binoculars and Mounting Solutions Market
Others
Global Transparent Plastics Market
Others
Versatile Video Coding Market
Others
Global Platform Trolley Market