
 Global Duty-Free Retailing Market | 2026-2036
Global Duty-Free Retailing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Duty-Free Retailing Market Analysis
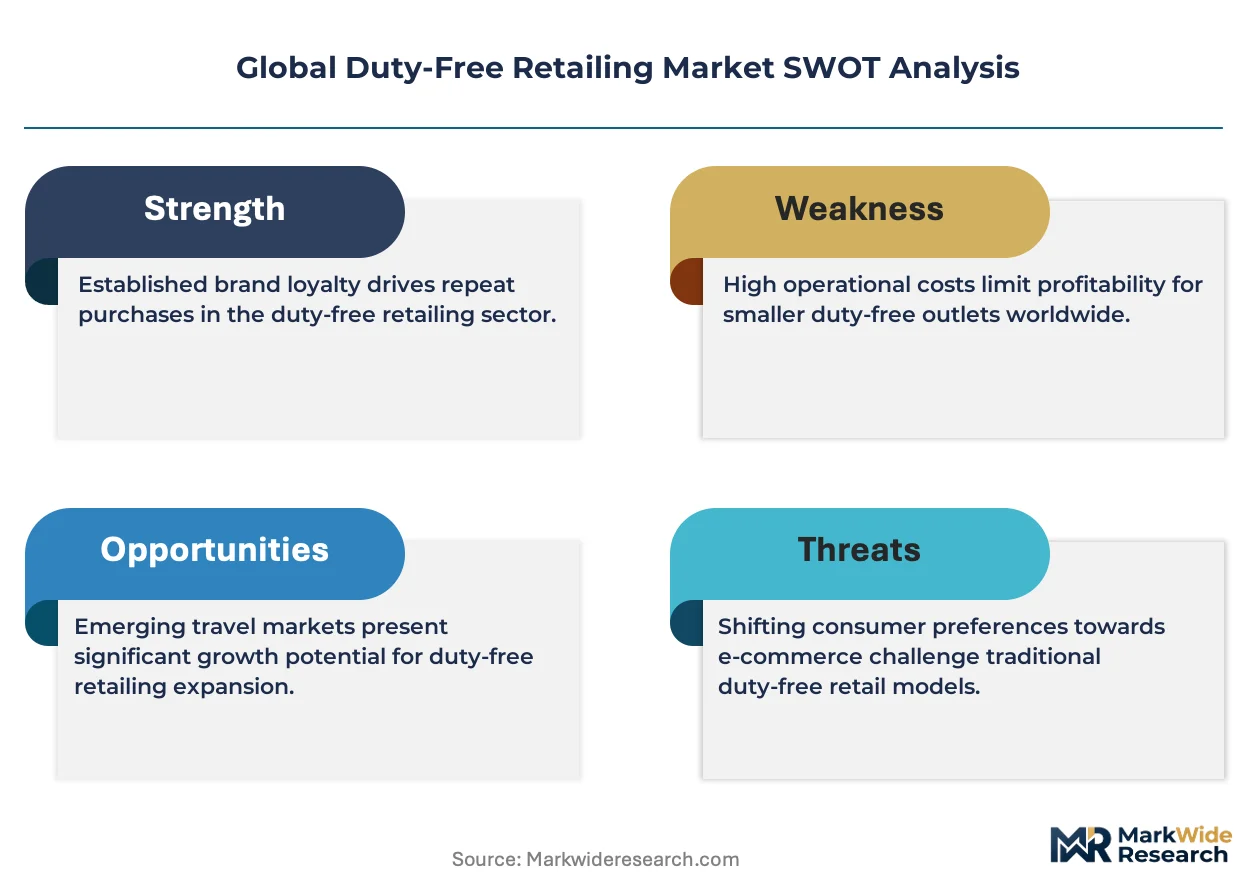
Airport concession fees is narrowing as a share of total retail economics, pressuring operators to extract margin from in-store productivity and exclusive brand partnerships. Avolta leverages its global travel retail network to sustain premium positioning across multiple continents. Lotte Duty Free anchors its competitive stance through dominance in Korean airport concessions and downtown duty-free complexes. Gebr. Heinemann SE & Co. KG specializes in curated luxury portfolios that differentiate its European and Middle Eastern operations.
Duty-free retailing constitutes commercial transactions of goods exempt from certain local or national taxes and duties, contingent upon removal from the purchasing jurisdiction by qualifying travelers, with product assortments governed by customs volume limits and origin-verification protocols. The primary commercial purpose centers on capturing discretionary spending from captive, time-constrained consumers within secured transit zones where alternative retail access is restricted. Cosmetics and alcoholic beverages command the deepest margin pools among product categories, reflecting brand premiumization and traveler gifting behavior. Airport sales channels generate the dominant revenue share, though downtown duty-free shops in Seoul and Dubai represent the fastest-expanding format by customer reach.
EU customs authorities enforce strict intra-European duty-free eligibility rules under the Union Customs Code, while the US CBP and TTB regulate inbound passenger allowances for alcohol and tobacco at American ports of entry. China's customs administration operates real-time passenger purchase tracking through integrated digital declaration systems, tightening enforcement of cross-border shopping limits. South Korea's customs service mandates foreign visitor verification for downtown duty-free purchases, linking passport data to transaction records. Stakeholders must monitor evolving digital border control integration and its implications for passenger dwell time and spending conversion.
Market Dynamics
Digital customs pre-clearance systems are compressing passenger dwell times at aviation hubs, forcing duty-free operators to accelerate conversion rates through frictionless payment architectures and predictive inventory positioning.
Growth Catalysts
- Cross-border mobility normalization:Post-pandemic international passenger volumes at Chinese and South Korean airports are restoring captive retail audiences. China's customs administration tracks purchases through integrated digital declaration systems, tightening enforcement while legitimizing transaction flows.
- REACH compliance premiumization:EU cosmetic brands leverage regulatory adherence as a quality signal in airport retail environments, commanding shelf space through verified ingredient transparency.
- Biometric passenger processing:Facial recognition boarding at Dubai International and Singapore Changi is collapsing queue times, extending available shopping windows for transit passengers.
Market Restraints
- Aviation fuel cost volatility:Jet fuel price spikes transmit directly to airline ticket pricing, suppressing discretionary travel budgets and airport foot traffic.
- Concession fee compression:Airport authorities in the United Arab Emirates and Qatar extract fixed-rent minimums regardless of passenger throughput, eroding operator margins during demand troughs.
- Alcohol allowance fragmentation:Divergent inbound passenger limits between the US TTB, EU Union Customs Code, and China's customs administration complicate inventory planning for spirits categories.
Strategic Opportunities
- Vietnam airport privatization:New terminal concessions at Ho Chi Minh City and Hanoi offer first-mover positioning before incumbent saturation.
- Pre-order mobile platforms:Reservation apps allowing duty-free pickup at boarding gates capture passengers who bypass traditional retail zones.
- South Korea's foreign visitor verification system:Passport-linked transaction records downtown enable seamless airport collection, expanding the addressable customer base beyond transit passengers.
Industry Challenges
- Luxury brand authorization complexity:Exclusive distribution agreements with LVMH, Richemont, and Estée Lauder portfolios require multi-year negotiation cycles and performance guarantees.
- Real-time inventory synchronization:Legacy ERP systems at mid-tier operators struggle to reconcile stock levels across airport, downtown, and border shop formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Duty-Free Retailing Market |
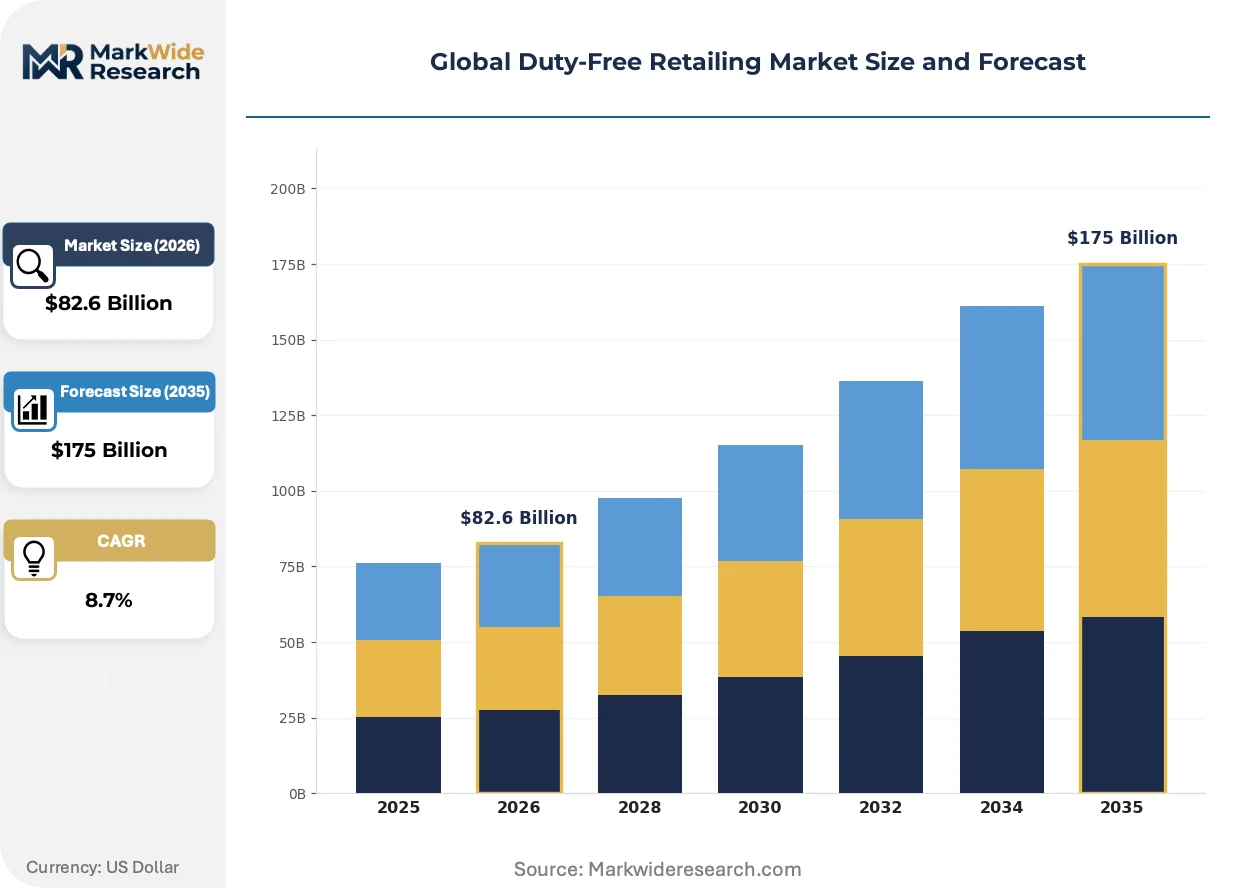
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $175 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alcoholic Beverages, Tobacco Products, Cosmetics, Confectionery Customer Type: Travelers, Expatriates, Tourists, Business Travelers Sales Channel: Airports, Cruise Ships, Border Shops, Downtown Duty-Free Shops Brand: Luxury Brands, Emerging Brands, Established Brands, Local Crafts |
| Companies Covered | China Duty Free Group, Avolta, Lotte Duty Free, Gebr. Heinemann SE & Co. KG, Lagardère Travel Retail, DFS Group, Dubai Duty Free, The Shilla Duty Free, Duty Free Americas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Duty-Free Retailing Market Emerging Trajectories
Frictionless commerce architectures are displacing traditional browse-and-buy patterns, with biometric identification and AI-driven personalization converging to reshape how captive travelers discover and purchase duty-free merchandise.
Computer vision shelf monitoring is collapsing stockout incidents at high-velocity airport stores. Cameras integrated with weight sensors track SKU depletion in real time, triggering automated replenishment orders to on-site backrooms. Avolta and Lotte Duty Free deploy these systems across Asian hub terminals, compressing restock cycles from hours to minutes.
China's customs administration mandates real-time passenger purchase tracking through integrated digital declaration systems, tightening enforcement of cross-border shopping limits. This regulatory architecture forces operators to pre-validate customer eligibility at point of sale, embedding compliance into transaction workflows. Cosmetics and alcoholic beverage categories face the strictest scrutiny, with automatic flagging of allowance exceedances.
Chinese travelers now pre-research duty-free assortments through Xiaohongshu and Douyin before airport arrival, collapsing in-store decision timeframes. This behavioral shift pressures operators to optimize mobile discovery and reserve-and-collect functionality. Seoul's downtown duty-free complexes and Dubai Mall adjacent shops capture this planning behavior through geo-targeted promotions during pre-trip phases.
Global Duty-Free Retailing Market Segmentation
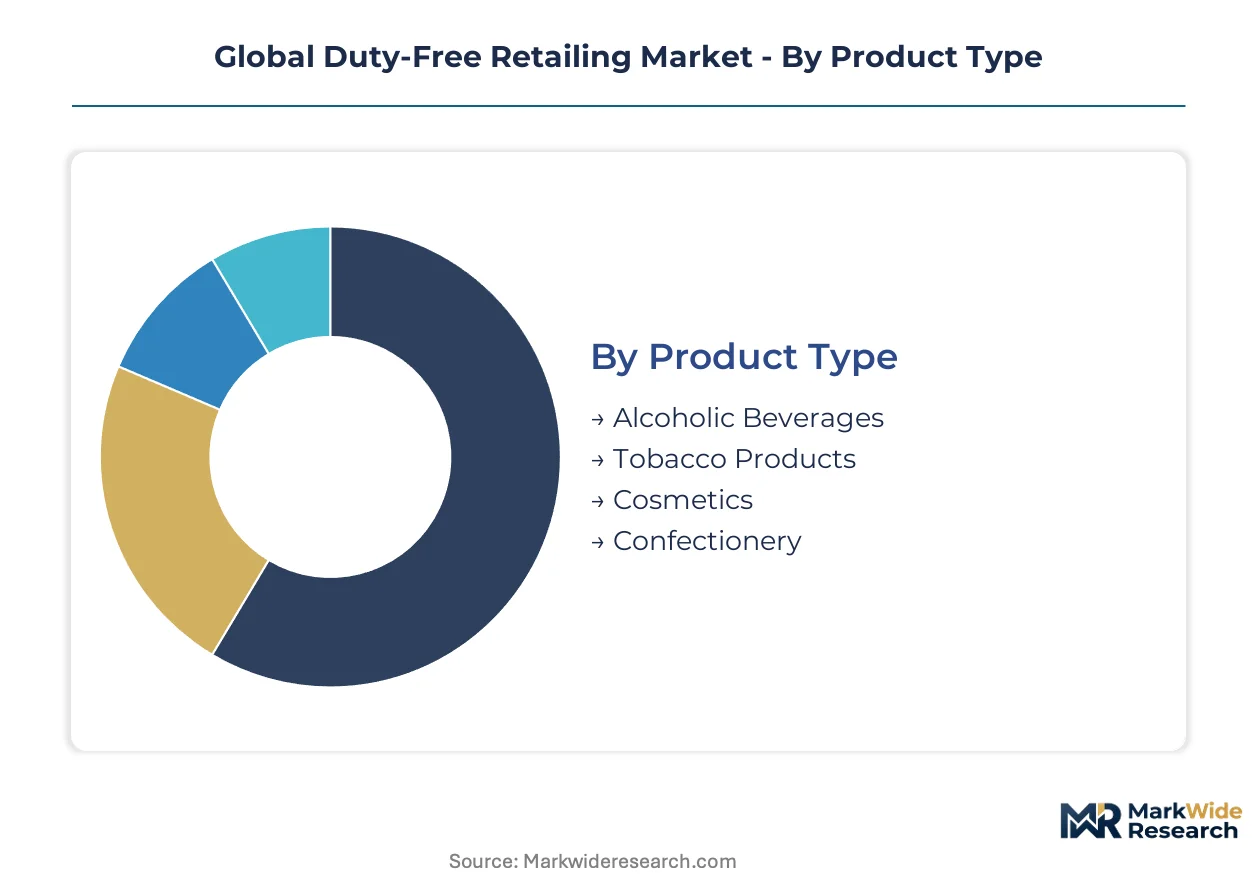
Duty-free retailing demands precise segmentation because passenger profiles, dwell times, and spending patterns vary dramatically across transit environments. Operators must align inventory depth, price positioning, and brand mix to each channel's captive audience characteristics.
Product Type:
Mature categories dominate revenue pools while emerging segments reshape margin structures.
- Alcoholic Beverages:Spirits and wines command premium shelf space through gifting rituals and inbound allowance optimization. Demand concentrates at Dubai International and Singapore Changi where transit passengers maximize duty-free quotas before final destinations.
- Cosmetics:Skincare and fragrance portfolios leverage regulatory compliance as quality signaling, with EU REACH adherence driving brand selection. South Korea's downtown duty-free complexes and Chinese airport terminals absorb the deepest volume as travelers stockpile prestige beauty products.
- Tobacco Products:Cigarette and cigar sales face tightening customs enforcement across China, the EU, and the US, compressing allowable quantities per passenger.
- Confectionery:Premium chocolate and regional specialty sweets capture impulse purchases from time-constrained flyers at European hub terminals.
Alcoholic beverages handles the majority of throughput; cosmetics is expanding most quickly on share.
Customer Type:
Volume concentration diverges sharply between transit-captive and destination-oriented travelers.
- Travelers:Transit passengers with sub-three-hour layovers drive conversion urgency, requiring frictionless payment and pre-order platforms to complete transactions.
- Tourists:Leisure visitors extending trips through Seoul, Dubai, and Bangkok generate downtown duty-free traffic before airport departure, expanding the addressable window beyond traditional retail zones.
- Business Travelers:Frequent flyers prioritize convenience and loyalty program integration over price comparison.
- Expatriates:Long-term foreign residents exploit recurring departure privileges for bulk personal consumption.
Travelers contributes the dominant transaction count; tourists is gaining share fastest through downtown format expansion.
Sales Channel:
Physical format economics determine concession fee structures and inventory turnover requirements.
- Airports:Aviation hubs in China, South Korea, and the UAE generate captive foot traffic with restricted alternative retail access, commanding the steepest concession rents.
- Downtown Duty-Free Shops:Seoul's Gangnam complexes and Dubai Mall-adjacent stores capture pre-trip planning behavior, with passport-linked collection smoothing airport logistics.
- Cruise Ships:Onboard retail operates under maritime customs protocols with limited SKU breadth and high impulse conversion.
- Border Shops:Land crossing locations serve regional vehicle traffic with lower per-transaction values but steadier throughput.
Airports absorbs the bulk of revenue; downtown duty-free shops is climbing the fastest as operators expand beyond transit constraints.
Brand:
Authorization tier determines margin capture and exclusivity positioning.
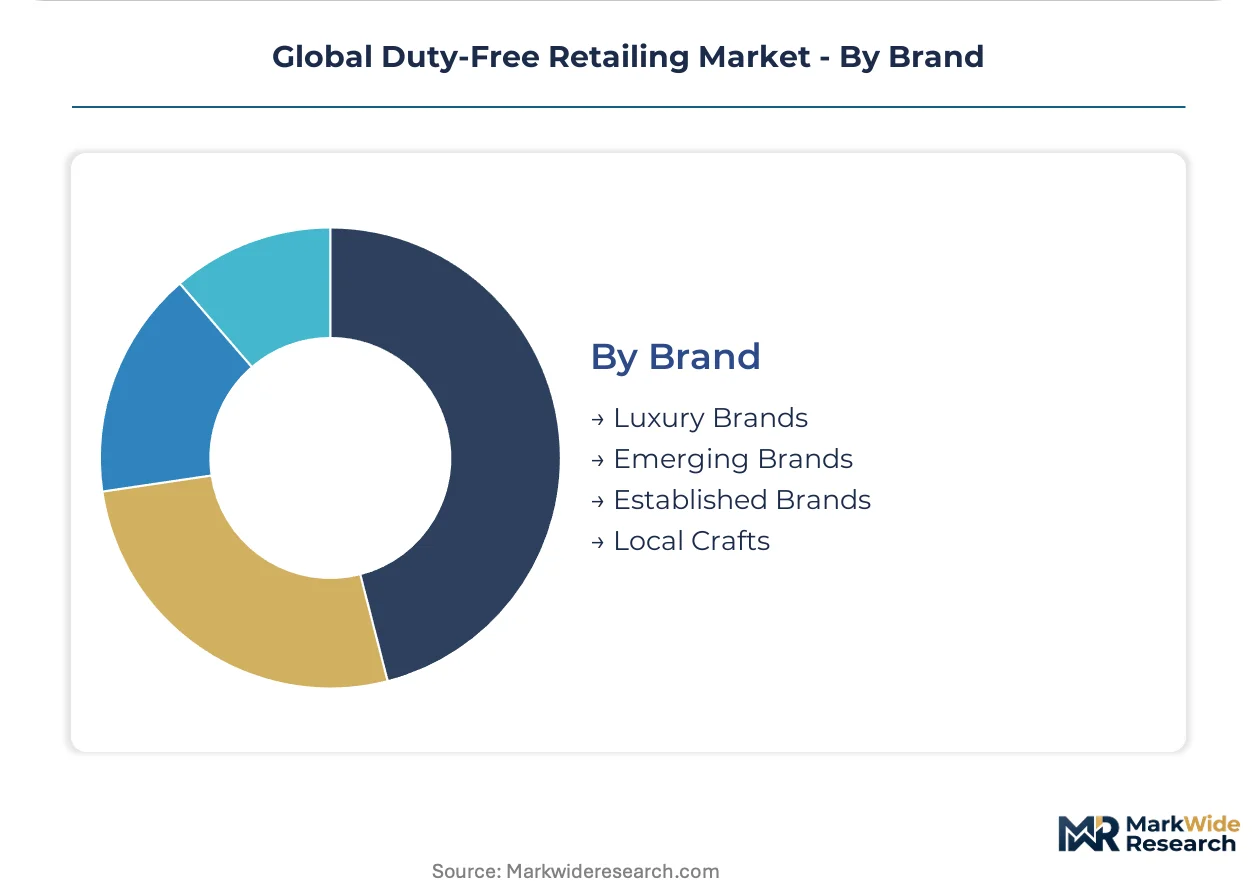
- Luxury Brands:LVMH, Richemont, and Estée Lauder portfolios require multi-year distribution agreements with performance guarantees, anchoring premium positioning at major aviation hubs.
- Established Brands:Mid-tier global labels balance recognition with accessible price points for broader passenger segments.
- Emerging Brands:Niche skincare and craft spirit labels exploit social media discovery on Chinese platforms to secure trial placements.
- Local Crafts:Regional artisans and specialty food producers differentiate location-specific assortments at secondary airports.
Luxury brands commands the deepest margin pool; emerging brands is the fastest mover on share through digital-native customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese travelers stockpile prestige cosmetics and spirits before departure, while European transit passengers favor impulse confectionery and tobacco, and Middle Eastern hubs capture maximum allowance optimization for alcohol categories.
China
Mainland travelers drive pre-trip planning through Xiaohongshu and Douyin, collapsing in-store decision windows at Shanghai Pudong and Beijing Capital. SAMR's real-time purchase tracking through integrated digital declaration systems tightens cross-border enforcement while legitimizing transaction flows. Hainan's offshore duty-free island anchors domestic consumption diversion, with Sanya's Haitang Bay complexes capturing spend that previously exited through overseas airports.
South Korea
Foreign visitor verification systems linking passport data to transaction records enable seamless downtown-to-airport collection, expanding the addressable customer base beyond transit passengers. MFDS mandates cosmetic ingredient disclosure that REACH-compliant EU brands leverage as quality signaling. Seoul's Gangnam duty-free complexes and Incheon International's consolidated retail zones concentrate the deepest volume for prestige beauty stockpiling.
United Arab Emirates
Dubai International's biometric boarding systems collapse queue times, extending available shopping windows for transit passengers maximizing alcohol allowances before final destinations. MOHAP oversees customs protocols while airport authorities extract fixed-rent minimums regardless of passenger throughput. Dubai Mall-adjacent downtown shops and Abu Dhabi International's terminal concessions capture both pre-trip planning and last-minute impulse conversion.
Germany
EU REACH compliance serves as a quality differentiator for cosmetic brands commanding shelf space at Frankfurt and Munich hubs. The Union Customs Code enforces strict intra-European duty-free eligibility rules that constrain passenger qualification pools. Frankfurt Airport's central European positioning captures connecting traffic from North America, Asia, and intra-European routes with diverse allowance optimization behaviors.
Singapore
Changi Airport's facial recognition boarding infrastructure extends dwell time for transit passengers with sub-three-hour layovers requiring frictionless payment completion. The country's customs administration operates integrated digital declaration systems tightening enforcement of inbound allowance limits. Terminal retail clusters concentrate conversion urgency through predictive inventory positioning and AI-driven personalization at high-velocity touchpoints.
Global Duty-Free Retailing Market Vendor Landscape
Capability concentration sits with operators mastering exclusive brand authorization negotiations; scale advantage sits with those controlling multiple mega-hub concessions across continents. The market structures around three tiers: integrated travel retail networks spanning aviation and maritime channels, regional specialists dominating single-country airport ecosystems, and downtown duty-free complex operators capturing pre-departure planning behavior. Dominant competitive moves include concession portfolio diversification across airport, downtown, and border formats, and technology licensing for frictionless biometric payment architectures.
Within the integrated network tier, Avolta and Lotte Duty Free exemplify archetypes of geographic diversification versus single-country dominance. Avolta leverages multi-continent positioning to sustain premium brand relationships, while Lotte Duty Free anchors competitive stance through Korean airport concessions and downtown complex control. Gebr. Heinemann SE & Co. KG occupies a specialist position, curating luxury portfolios that differentiate European and Middle Eastern operations through exclusive distribution relationships.
| Leading Market Players |
|---|
| China Duty Free Group |
| Avolta |
| Lotte Duty Free |
| Gebr. Heinemann SE & Co. KG |
| Lagardère Travel Retail |
| DFS Group |
| Dubai Duty Free |
| The Shilla Duty Free |
| Duty Free Americas |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoint exposure at Chinese and South Korean customs authorities determines both margin compression patterns and inventory positioning strategies across duty-free operators. SAMR's real-time purchase tracking systems and MFDS cosmetic disclosure mandates force tiered compliance investments that widen pricing spreads between authorized and non-authorized brand tiers.
Pricing Analysis
Long-term concession agreements with fixed-rent minimums dominate contract structures at Dubai International and Incheon International, locking operators into obligations regardless of passenger throughput volatility. Price differentiation rests on exclusive brand authorization tiers and biometric payment integration depth, with LVMH and Richemont portfolios commanding premium positioning. Pricing pressure stems from airport authority rent escalation, compressing margins for mid-tier operators lacking scale leverage. Price-sensitive segments cluster in tobacco and confectionery categories, while luxury cosmetics buyers exhibit minimal elasticity.
Supply Chain Analysis
Tariff exposure between EU member states and post-Brexit United Kingdom dominates supply chain risk for spirits and beauty categories moving through Heathrow and Frankfurt hubs. Manufacturing concentration in France, Switzerland, and Italy anchors luxury goods sourcing, with component dependencies on glass packaging from Germany and fragrance compounds from Grasse. Single-source vulnerability permeates exclusive distribution agreements with prestige houses. Distribution runs through airport bonded warehouses with just-in-time replenishment to terminal retail floors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Duty-free retailing operates as a regulatory moat business where concession tenure and customs compliance entrenchment create defensible competitive positioning. Network effects concentrate with operators controlling multiple mega-hub footprints that sustain exclusive brand relationships.
For Market Incumbents: Build exclusive brand portfolio moats through multi-year performance guarantees with Estée Lauder and LVMH houses, securing shelf space priority against emerging competitors. Deepen biometric payment infrastructure at Singapore Changi and Dubai International to extend dwell-time capture. Counter threat from pre-order mobile platforms by integrating reserve-and-collect functionality into existing terminal operations. Prioritize vertical integration into downtown duty-free complexes in Seoul and Dubai to intercept pre-trip planning behavior.
For New Entrants and Emerging Players: Pursue Vietnam airport privatization opportunities at Ho Chi Minh City and Hanoi before incumbent saturation locks concession availability. Target craft spirits and niche skincare segments where social media discovery on Xiaohongshu enables trial placement without legacy authorization barriers. Exploit underpenetrated border shop formats in Southeast Asian land crossings with lower concession barriers. Anchor go-to-market strategy through digital-native customer acquisition rather than competing for prime terminal real estate.
For Investors and Strategic Acquirers: China's customs administration digital declaration expansion reshapes the acquisition landscape by elevating compliance infrastructure value in target screening. Long-term viability favors operators with multi-continent concession diversification buffering single-market regulatory shifts. Prioritize acquisition targets possessing integrated downtown-to-airport logistics platforms and passport-linked transaction systems. Monitor biometric boarding rollout pace at major aviation hubs as inflection indicator for dwell-time extension potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Brand Authorization Renewal | Multi-year LVMH and Richemont agreements anchor premium positioning at Changi and Dubai International. |
| Biometric Payment Infrastructure Deployment | Facial recognition boarding integration at Incheon and Changi collapses transaction friction for transit passengers. |
| Downtown Duty-Free Complex Expansion | Seoul Gangnam and Dubai Mall-adjacent stores capture pre-trip planning beyond terminal constraints. |
| Pre-Order Mobile Platform Launch | Reservation apps with boarding gate pickup intercept passengers bypassing traditional retail zones. |
| Computer Vision Inventory Systems | Real-time shelf monitoring at Avolta and Lotte Duty Free locations compresses restock cycles to minutes. |
Methodological Framework
Cross-validation between executive interviews and customs regulatory filings anchors the qualitative findings in this study. Primary fieldwork engaged duty-free operators, airport concession directors, luxury brand distribution heads, and customs technology vendors across China, South Korea, the UAE, and Singapore. Secondary sources incorporated SAMR digital declaration protocols, EU Union Customs Code amendments, MFDS cosmetic ingredient mandates, and Dubai International passenger flow data. Bottom-up concession revenue modeling and top-down regional passenger volume estimates were triangulated to validate market sizing.
Calibration against historical passenger recovery patterns and concession fee structures shaped the analytical framework across the projection horizon. Segmentation dimensions included product category, sales channel format, customer travel purpose, and brand authorization tier. CAGRs were derived from passenger volume elasticity modeling and per-capita spending trend analysis. Industry-specific forecast inputs encompassed biometric boarding rollout schedules and downtown duty-free regulatory expansion in Seoul.
Sensitivities concentrate around aviation fuel cost volatility, Chinese outbound travel policy shifts, and EU customs rule amendments. Forecasts reflect assumptions regarding post-pandemic mobility normalization and concession fee negotiation outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Tobacco Packaging Market
Others
Chip Card Scanners Market
Others
Singapore Retail Market
Others
Sound Reinforcement Market
Others
Banknote Printing Machine Market
Others
Printing Machines Market
Others
Fresh Durian Market
Others
UK Automotive LED Lighting Market
Others
Canada 3D Printing Construction Market
Others
Australia Content Services Platform Market
Others
Port Replicator Market
Others
Fiberglass Storage Tanks Market
Others
Managed Video As a Service Market
Others
Global on-Demand Laundry Service Market
Others
Cloud Gaming Baas Market
Others
Badminton Apparel Market