
 Global Platform Trolley Market | 2026-2036
Global Platform Trolley Market Size, Share, and Industry Trends Forecast 2026-2036
Global Platform Trolley Market Foresight
Direct-to-facility supply channels is reshaping how platform trolleys reach end users, bypassing traditional distributor markups and compressing lead times. Still GmbH leverages its captive German manufacturing base to sustain premium positioning across European warehouse accounts. Toyota Industries anchors Asia-Pacific volume through integrated castor and frame production. Jungheinrich AG competes on modular platform configurations that adapt to narrow-aisle environments.
A platform trolley is a wheeled material-handling device comprising a flat load-bearing deck, four or more castors, and a push handle, typically rated for loads between 150 kg and 500 kg depending on frame construction. Steel-deck variants with polyurethane castors dominate industrial applications where durability and floor protection converge. Heavy-duty trolleys command the widest margin pools due to specialized welding and reinforced undercarriage requirements, while folding trolleys are gaining fastest in last-mile delivery fleets where vehicle space constraints dictate collapsible equipment. Plastic platforms occupy the value tier in retail and hospital settings where corrosion resistance and sanitization protocols outweigh load-capacity demands.
OSHA mandates load-plate visibility and caster-lock testing for warehouse equipment sold into US facilities, while EU machinery directives enforce CE marking and risk-assessment documentation for trolleys deployed in member-state manufacturing plants. ISO 2283 dimensional standards further constrain design freedom for exporters serving multiple jurisdictions. Stakeholders must monitor how emerging battery-trolley electrification intersects with FCC electromagnetic emissions rules and IEC 61000 compliance before committing platform development roadmaps.
Market Dynamics
E-commerce fulfillment velocity is compressing equipment replacement cycles as warehouse operators in Germany, the United States, and Japan prioritize throughput over asset longevity. This structural pressure is reconfiguring supplier-buyer relationships and accelerating specification standardization across national markets.
Growth Catalysts
- OSHA load-rating mandates:US warehouse certification requirements are forcing fleet upgrades toward visible load-plate designs and tested caster-lock assemblies, expanding replacement demand for compliant equipment.
- Automotive parts distribution:German intralogistics retrofits are concentrating procurement of reinforced platform trolleys capable of handling powertrain components in narrow-aisle configurations.
- Polyurethane castor adoption:Floor protection specifications in healthcare and retail facilities are displacing rubber and nylon alternatives, favoring hybrid wheel materials that reduce facility maintenance costs.
Market Restraints
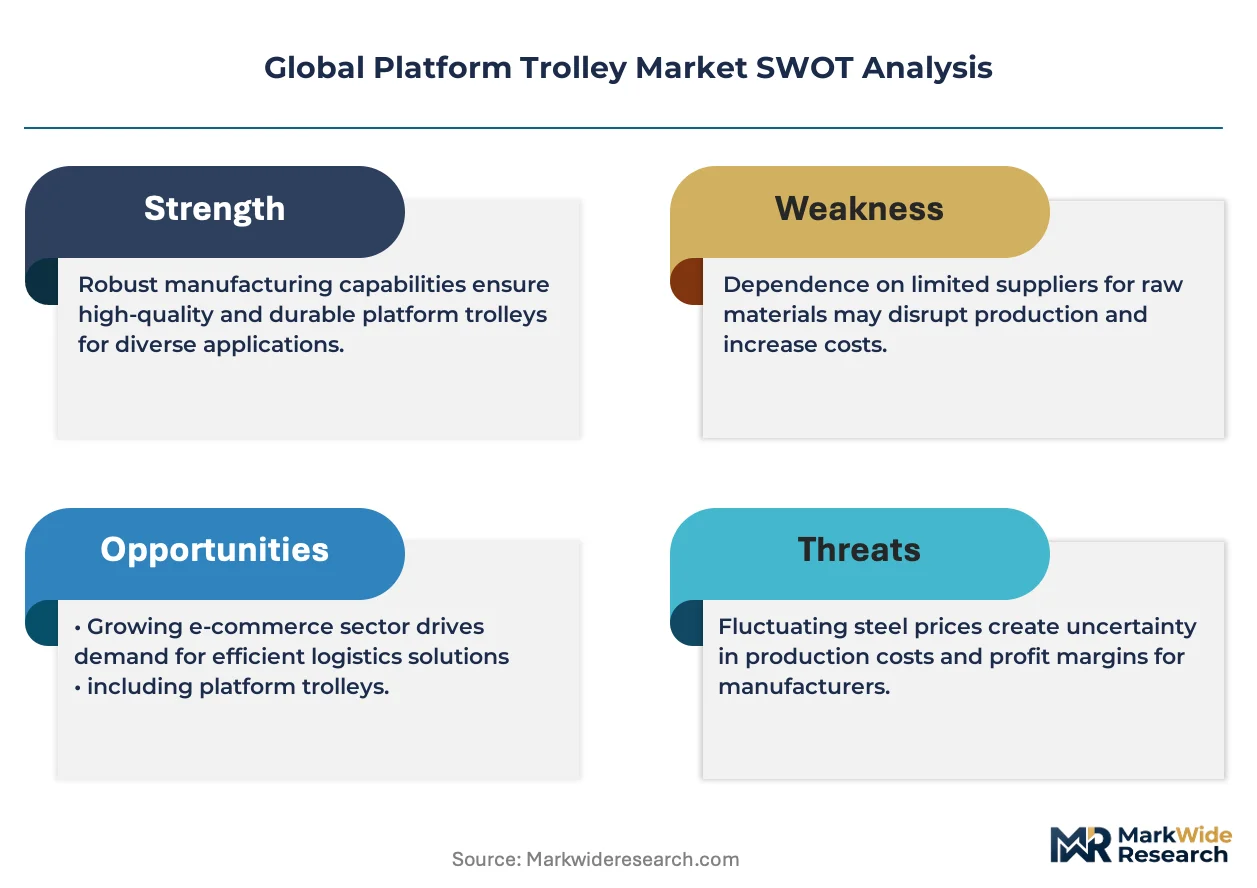
- Steel price volatility:Frame weldment costs fluctuate with raw material inputs, compressing margin pools for mid-tier manufacturers without captive steel supply or long-term hedging contracts.
- CE marking documentation burden:EU machinery directives impose risk-assessment protocols that extend product launch timelines by four to eight months for exporters serving multiple member states.
- Manual trolley substitution:Low-cost pallet jacks and automated guided vehicles are displacing basic platform trolley configurations in high-throughput environments where labor cost arbitrage favors mechanization.
Strategic Opportunities
- India warehouse buildout:PLI scheme incentives for logistics infrastructure are creating first-mover advantages for suppliers establishing local assembly operations ahead of domestic certification harmonization.
- Battery-trolley electrification:Convergence of lithium-ion powertrains with platform chassis designs opens motorized segments previously served by forklifts, subject to FCC electromagnetic emissions compliance.
- Direct-to-facility channels:Bypassing distributor markups through manufacturer-owned digital procurement platforms compresses lead times and captures margin previously allocated to wholesale intermediaries.
Industry Challenges
- Welder certification scarcity:Frame fabrication requires qualified pressure-vessel welders, and talent pipelines in Germany and the United States are failing to match fleet expansion timelines.
- ISO 2283 dimensional reconciliation:Exporters serving multiple jurisdictions face design constraints that limit platform standardization and inflate SKU complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Platform Trolley Market |
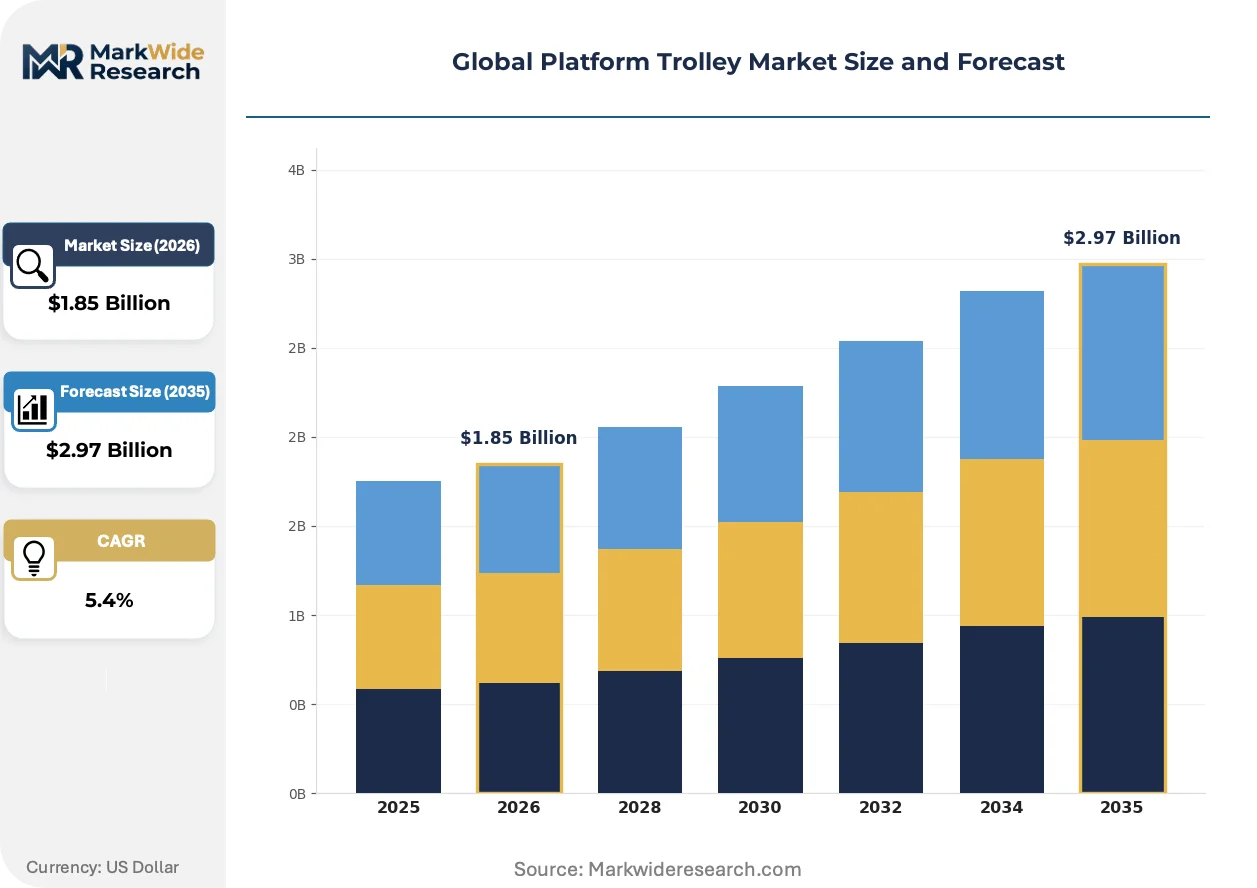
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Trolleys, Utility Trolleys, Heavy-Duty Trolleys, Specialty Trolleys Material: Plastic, Steel, Aluminum, Wood End User: Retail Stores, Warehouses, Hospitals, Manufacturing Facilities Feature: Foldable, Adjustable Height, Multi-Level, Heavy Load Capacity |
| Companies Covered | Still GmbH, Toyota Industries, Jungheinrich AG, Wanzl, Rubbermaid Commercial Products, STANLEY, InterMetro, Wesco Industrial Products, Vestil Manufacturing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Platform Trolley Market Shifts & Advancements
Equipment intelligence and regulatory convergence are transforming platform trolleys from passive transport assets into integrated data nodes within warehouse management systems. These shifts are compressing traditional product lifecycles and redefining supplier value propositions.
Sensor-embedded castor assemblies are digitizing fleet tracking capabilities by transmitting load weight, travel distance, and maintenance intervals to centralized facility software. Third-party logistics operators in the United States are deploying these units at scale to optimize asset utilization rates and predictive replacement scheduling. This connectivity infrastructure is digitizing procurement decisions, as buyers now specify telemetry compatibility alongside mechanical load ratings.
EU machinery directives are tightening documentation requirements for risk assessment and CE conformity, particularly for motorized variants entering German and French manufacturing plants. Industrial consequence includes mandatory third-party verification of brake systems and emergency-stop functionality. Heavy-duty motorized segments face the steepest compliance cost escalation, prompting suppliers to consolidate certification resources around high-volume chassis platforms.
Hospital procurement departments are unbundling after-sales service contracts from equipment purchases, shifting toward per-use maintenance agreements with penalty clauses for downtime. This behavioral change disrupts traditional distributor models that bundled spare parts margins into upfront pricing. The United Kingdom's National Health Service procurement frameworks exemplify this shift, where sanitization-protocol compliance now drives vendor selection more than initial capital cost.
Global Platform Trolley Market Segmentation
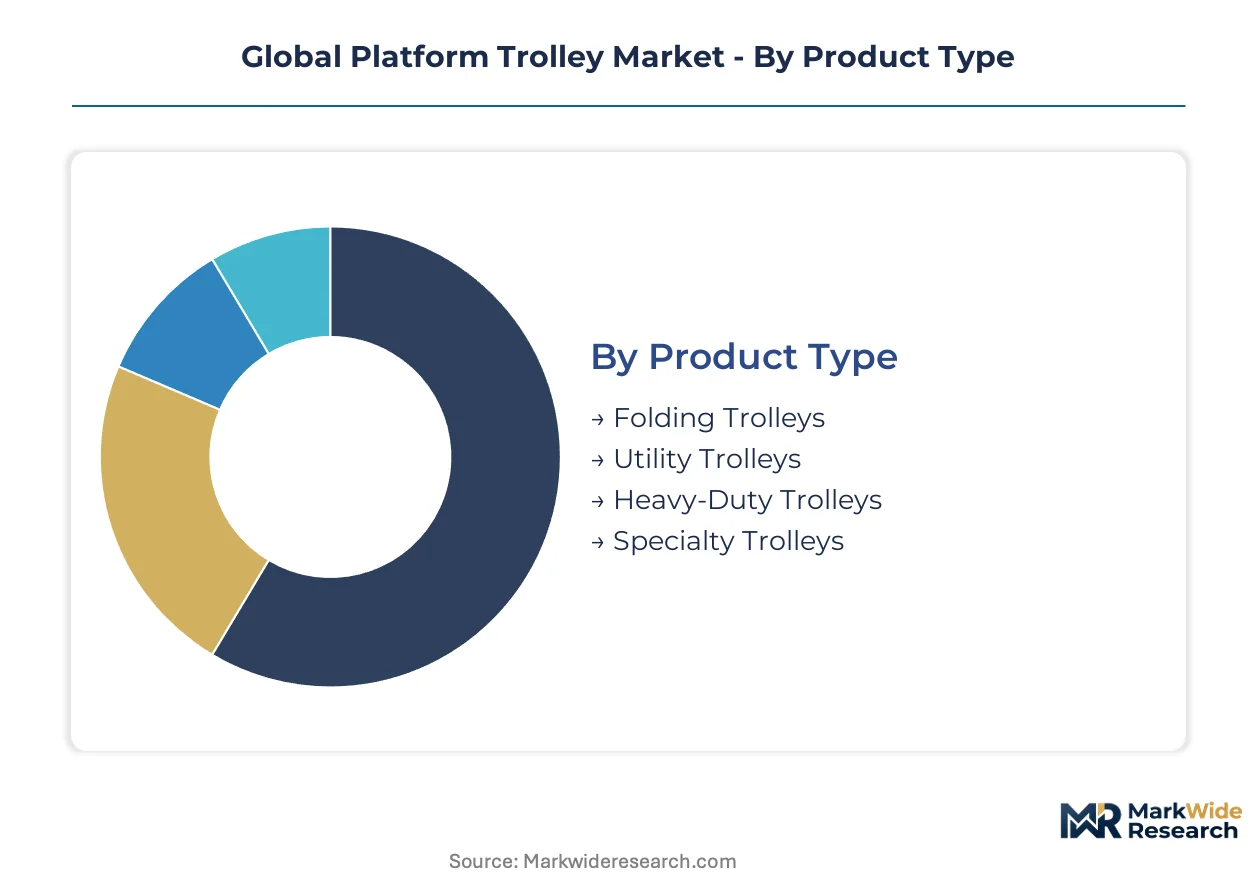
Platform trolley procurement varies sharply by operational intensity. Replacement cycles range from months in high-velocity e-commerce hubs to decades in static manufacturing installations. Understanding these velocity differentials shapes supplier portfolio construction and regional market entry sequencing.
Product Type:
Folding trolleys turn over fastest due to mechanical wear in frequent collapse cycles, while heavy-duty units persist for years under constant load. Cycle time compression in last-mile fleets is reshaping supplier revenue recognition patterns.
- Heavy-Duty Trolleys:Reinforced steel frame construction with welded undercarriage supports loads exceeding 500 kg. Automotive parts distribution centers in Germany specify these for powertrain component transport in narrow-aisle configurations where structural integrity outweighs maneuverability.
- Folding Trolleys:Collapsible chassis designs reduce storage footprint by 70% when stowed. Last-mile delivery fleets across the United States and Japan are standardizing on these units to maximize vehicle cube utilization, driving replacement demand as hinge mechanisms fatigue under daily cycling.
- Utility Trolleys:General-purpose platforms with 150-300 kg ratings serve retail backrooms and hospital supply closets where load variability demands flexibility.
- Specialty Trolleys:Custom configurations for cleanroom, cold-chain, or hazardous material applications carry premium positioning due to certification requirements.
Heavy-duty trolleys dominate installed base in manufacturing. Folding trolleys are where expansion concentrates.
Material:
Raw material selection tracks facility environment demands and total cost of ownership calculations. Corrosion exposure, sanitization protocols, and floor protection requirements drive specification divergence across end-use verticals.
- Steel:Welded carbon or stainless construction delivers maximum load capacity and impact resistance. Warehouse operators in the United States favor steel-deck variants with polyurethane castor assemblies to satisfy OSHA load-plate visibility mandates while protecting concrete flooring.
- Plastic:Polypropylene or HDPE platforms resist chemical corrosion and enable steam sanitization. Hospital procurement departments in the United Kingdom specify these for clinical environments where infection control protocols override load-capacity optimization.
- Aluminum:Lightweight corrosion-resistant framing reduces operator fatigue in high-frequency transport applications.
- Wood:Traditional hardwood platforms persist in artisanal and specialty retail settings where aesthetic presentation complements functional utility.
Steel commands the largest revenue pool. Plastic is gaining share fastest in healthcare and food service.
End User:
Procurement authority and specification complexity vary dramatically across buyer types. Hospital purchasing committees impose documentation burdens that exclude smaller suppliers, while warehouse operators prioritize volume pricing and lead-time compression.
- Warehouses:High-velocity fulfillment centers require fleet standardization to minimize training and maintenance overhead. E-commerce operators in Germany and Japan are retrofitting intralogistics equipment with sensor-embedded castor assemblies to enable predictive replacement scheduling.
- Hospitals:Clinical supply chains demand corrosion resistance, quiet operation, and sanitization compatibility. National Health Service procurement frameworks in the United Kingdom now weight after-sales service agreements more heavily than upfront capital cost.
- Retail Stores:Backroom restocking and customer-facing displays drive demand for compact, maneuverable platforms with aesthetic neutrality.
- Manufacturing Facilities:Heavy component transport and line-side feeding require reinforced construction and integration with production scheduling systems.
Warehouses generate the highest unit volumes. Hospitals are where margin expansion concentrates.
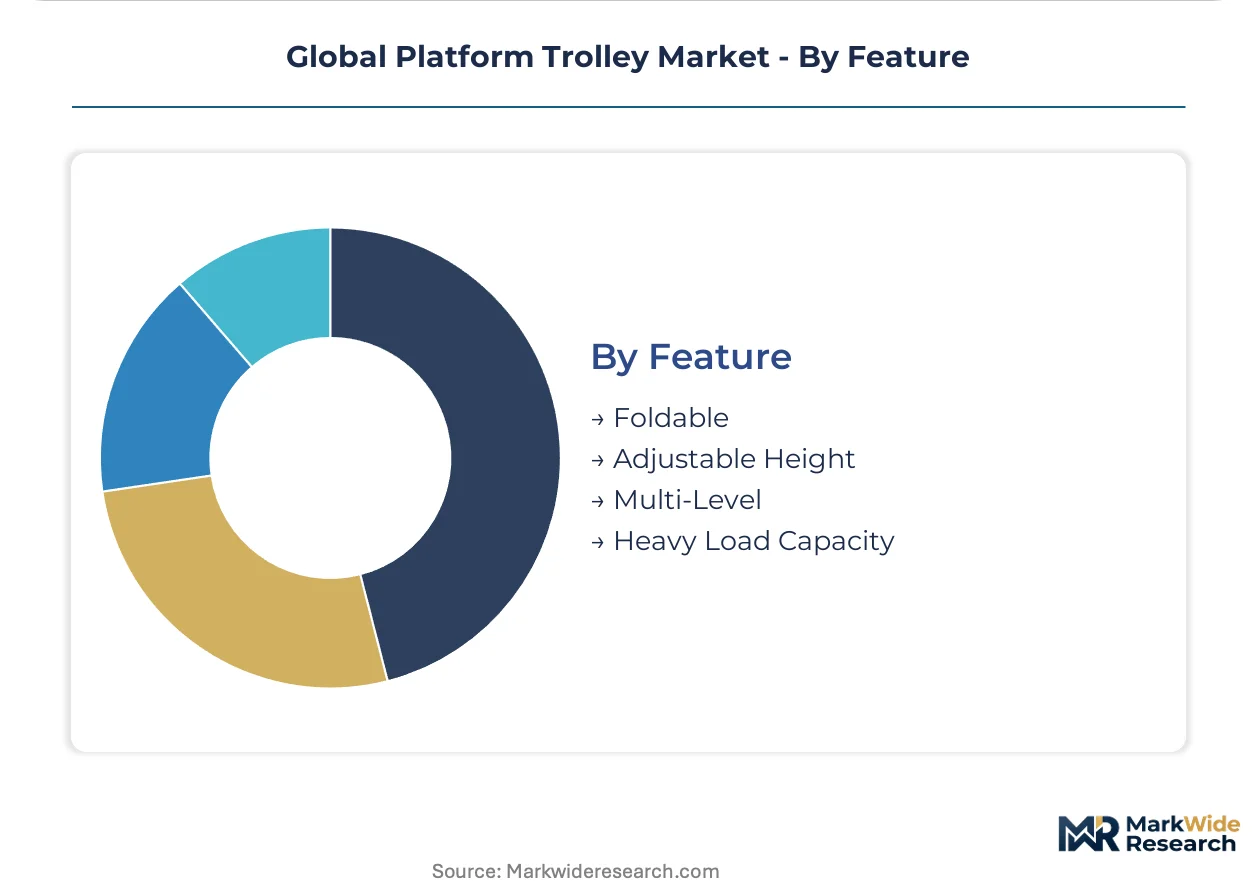
Feature:
Functional differentiation increasingly determines vendor selection as basic transport utility commoditizes. Buyers now specify telemetry compatibility and ergonomic adjustability alongside mechanical load ratings.
- Heavy Load Capacity:Reinforced chassis and upgraded castor assemblies rated beyond standard thresholds. Automotive suppliers in Germany require these specifications for engine block and transmission transport.
- Foldable:Collapsible mechanisms enabling vertical storage. Third-party logistics operators in the United States deploy these at scale to optimize asset utilization across variable demand patterns.
- Adjustable Height:Telescoping handle and platform mechanisms reduce operator strain and accommodate diverse user anthropometrics.
- Multi-Level:Tiered deck configurations separate inventory classes and improve picking efficiency in high-SKU environments.
Heavy load capacity anchors industrial procurement. Foldable designs are expanding most quickly in delivery and service applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PLI scheme incentives in India are accelerating warehouse infrastructure buildouts, while OSHA mandates in the United States and EU machinery directives in Germany reshape certification requirements for material-handling equipment across major economies.
United States
E-commerce fulfillment velocity is compressing equipment replacement cycles for warehouse operators. OSHA load-plate visibility mandates and caster-lock testing requirements are forcing fleet upgrades toward compliant designs. Third-party logistics operators in California and Texas are deploying sensor-embedded castor assemblies at scale.
Germany
Automotive parts distribution centers are retrofitting intralogistics equipment with reinforced platform configurations. EU machinery directives enforce CE marking and risk-assessment documentation for trolleys deployed in manufacturing plants. Stuttgart and Wolfsburg clusters concentrate procurement of narrow-aisle capable units for powertrain component transport.
Japan
Last-mile delivery fleets are standardizing on folding trolleys to maximize vehicle cube utilization. METI industrial standards govern load-rating verification and material specifications for domestic equipment sales. Tokyo and Osaka metropolitan areas drive replacement demand as hinge mechanisms fatigue under daily cycling.
India
Logistics infrastructure expansion under the PLI scheme is creating first-mover advantages for suppliers establishing local assembly operations. BIS certification requirements are harmonizing with international standards for material-handling equipment. Mumbai and Delhi-NCR warehouse buildouts concentrate demand for utility-grade platforms in high-SKU fulfillment environments.
China
Domestic e-commerce operators are prioritizing throughput over asset longevity in fulfillment center equipment procurement. GB standards and SAMR regulations constrain design parameters for castor assemblies and frame welds. Yangtze River Delta manufacturing clusters are integrating platform trolley production into broader intralogistics equipment supply chains.
Global Platform Trolley Market Competitive Landscape
On the supply side, the industry is structured around three distinct tiers: integrated industrial conglomerates with captive manufacturing bases, specialized material-handling equipment manufacturers with regional density, and diversified commercial products suppliers serving retail and healthcare verticals. Strategic archetypes include premium-positioned European fabricators with certified welding capabilities, Asia-Pacific volume producers with integrated castor and frame operations, and North American distributors leveraging direct-to-facility digital channels. Dominant competitive moves center on backward integration into polyurethane castor production and geographic expansion through local assembly partnerships in high-growth warehouse markets.
Among Germany-based fabricators, Still GmbH and Jungheinrich AG exemplify the premium-tier archetype through their positioning in European warehouse accounts. Toyota Industries occupies a scale-driven position within Asia-Pacific production networks. Wanzl represents the specialized retail and commercial equipment segment with concentration in European markets.
| Leading Market Players |
|---|
| Still GmbH |
| Toyota Industries |
| Jungheinrich AG |
| Wanzl |
| Rubbermaid Commercial Products |
| STANLEY |
| InterMetro |
| Wesco Industrial Products |
| Vestil Manufacturing Corporation |
| Others |
Supply & Pricing Matrix
Undercapacity in German pressure-vessel welder certification pipelines is compressing heavy-duty frame production schedules and elevating pricing power for qualified fabricators serving automotive distribution centers. This utilization squeeze propagates through supply chains as buyers accept longer lead times and reduced volume-discount leverage to secure compliant equipment.
Pricing Analysis
Volume-discount tiering structures separate heavy-duty motorized platforms from standard utility configurations based on certification grade and after-sales service bundling. Three-tier pricing stratification across premium CE-marked, standard OSHA-compliant, and economy non-certified tiers reflects divergent compliance investment requirements. Cost compression in the economy tier is intensifying as Asian volume producers expand polyurethane castor in-house production. Warehouse operators exhibit the highest price sensitivity due to fleet standardization mandates, while hospital procurement committees prioritize sanitization-protocol compliance over capital cost minimization.
Supply Chain Analysis
Tariff exposure between China and the United States is rerouting steel-deck component sourcing toward Mexican and Vietnamese fabrication hubs. Raw material supply draws from Chinese carbon steel mills, German stainless steel specialists, and South Korean polyurethane polymer producers. Single-source vulnerability concentrates in European castor bearing assemblies where qualified suppliers are limited. Distribution runs through manufacturer-owned digital procurement platforms that bypass traditional wholesale intermediaries and compress lead times for direct-to-facility fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform trolley procurement is shifting toward service-attach models where predictive maintenance contracts and per-use uptime agreements expand faster than hardware unit sales, particularly in NHS hospital frameworks and third-party logistics fleet management.
For Market Incumbents: Harden certification resource concentration around high-volume chassis platforms to amortize EU machinery directive compliance costs across broader production runs. Deepen backward integration into polyurethane castor production to capture margin pools threatened by raw material volatility and protect against emerging Asian volume competitors with captive wheel manufacturing. For New Entrants and Emerging Players: Build out local assembly operations in India ahead of BIS certification harmonization to capture PLI scheme warehouse infrastructure incentives. Target utility-grade folding trolley segments in last-mile delivery fleets where hinge mechanism replacement cycles create recurring revenue attachment opportunities and incumbent service networks remain underdeveloped. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-embedded castor assembly suppliers with telemetry compatibility specifications. Long-term viability over a multi-year horizon favors acquisition targets with established hospital service contract penetration and digital fleet management platform integration. Monitor battery-trolley electrification certification timelines as an inflection indicator for motorized segment margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Castor Production | Captive polyurethane wheel supply protects margin pools from steel price volatility affecting German and US fabricators. |
| Sensor-Embedded Platform Deployment | Telemetry-enabled castor assemblies transform procurement specifications toward data compatibility alongside mechanical ratings. |
| Direct-to-Facility Digital Channel Expansion | Manufacturer-owned procurement platforms capture distributor margins and compress lead times for warehouse accounts. |
| Local Assembly Partnership in India | PLI scheme logistics infrastructure incentives reward first-mover suppliers ahead of domestic certification harmonization. |
| Predictive Maintenance Contract Unbundling | Per-use service agreements with downtime penalties displace traditional bundled spare parts pricing in NHS procurement frameworks. |
Research Methodology
A standing panel of warehouse operations directors, hospital procurement managers, aftermarket service heads, and OEM sourcing leads provided ongoing calibration throughout primary fieldwork. Secondary validation drew from OSHA enforcement databases, EU machinery directive notification files, customs trade records for material-handling equipment, and SEC filings of listed industrial conglomerates. Bottom-up unit demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Scenario-bracketing around steel price volatility bands, certification timeline delays, and e-commerce fulfillment velocity assumptions shaped the analytical framework. Segmentation dimensions included product type, material construction, end-user vertical, and feature configuration. CAGRs were derived from installed base turnover rates and replacement cycle compression patterns observed in high-velocity fulfillment environments.
Stress conditions across raw material cost spikes, welder certification bottlenecks, and regulatory documentation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electrification adoption curves and hospital procurement behavioral shifts. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cathode Battery Material Market
Others
Global Mobile Gambling Market
Others
Tote Bags Market
Others
Military 4D Printing Market
Others
Hotel Wardrobe Market
Others
GCC Cigarette Market
Others
Textile Composites Market
Others
Global Enterprise Mobility in Healthcare Market
Others
Wearable Translator Market
Others
Indoor LBS Market
Others
Depth Gauge Market
Others
Mini Pcs Market
Others
Folding Screen Mobile Phone Market
Others
Middle East Smart Home Market
Others
Voice Controlled Devices Market
Others
United States Indoor LBS Market