
 North America Industrial Wearable Devices Market | 2026-2036
North America Industrial Wearable Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Wearable Devices Market Intelligence
The EPA's tightened industrial emissions monitoring mandates is decoupling wearable adoption from purely voluntary safety programs across North American factories. Microsoft Corporation leverages its mixed-reality headset ecosystem to anchor enterprise training deployments in heavy manufacturing. Vuzix Corporation specializes in monocular smart glasses that dominate hands-free maintenance workflows in aviation and energy sectors. RealWear Inc. controls the ruggedized voice-controlled segment where dust, noise, and chemical exposure disqualify conventional touch interfaces.
North America Industrial Wearable Devices encompass sensor-integrated hardware worn on the body to capture biometric, environmental, or positional data in industrial settings, typically featuring IP67+ ingress protection, multi-day battery architectures, and edge-computing chipsets that process data locally before cloud transmission. These systems primarily reduce incident rates, compress training cycles, and enable real-time expert guidance across distributed facilities. Smart Glasses currently occupy the largest revenue pool due to established use cases in remote assistance and guided assembly, while Wearable Sensors represent the fastest-expanding category as predictive fatigue and heat-stress algorithms mature. The End User segmentation tilts toward Manufacturing and Energy, where union-negotiated safety premiums and insurance rate incentives create immediate payback visibility for fleet rollouts.
OSHA, the FCC, and Health Canada jointly shape device certification pathways, with OSHA dictating workplace exposure thresholds that sensor networks must monitor, the FCC governing unlicensed spectrum for short-range industrial connectivity, and Health Canada enforcing electrical safety standards for battery-powered wearables in hazardous locations. This regulatory triad forces vendors to maintain parallel compliance documentation across the United States and Canada, raising barriers for smaller entrants. Stakeholders must track evolving state-level workers' compensation reforms that increasingly subsidize connected PPE investments through premium reduction programs.
Market Dynamics
OSHA's sensor-embedded PPE mandates are compressing adoption timelines across hazardous industries, converting voluntary safety investments into compliance-driven procurement cycles that favor certified vendors with established regulatory documentation.
Growth Catalysts
- EPA emissions monitoring mandates:The EPA's tightened industrial emissions standards are decoupling wearable adoption from voluntary programs, forcing continuous environmental sensing across North American factories.
- Texas oil and gas remote inspection:Head-mounted display deployments for equipment inspection are accelerating in the Permian Basin, creating concentrated demand for ruggedized voice-controlled units.
- Great Lakes manufacturing corridor concentration:Union-negotiated safety premiums across Michigan, Ohio, and Illinois are generating immediate payback visibility for fleet rollouts in automotive and heavy machinery sectors.
Market Restraints
- Battery chemistry cost volatility:Lithium-ion cell price fluctuations are compressing margins on multi-day battery architectures that industrial wearables require for shift-long operation.
- Parallel compliance documentation burden:The OSHA-FCC-Health Canada regulatory triad forces vendors to maintain separate certification pathways, raising fixed costs that disadvantage smaller entrants.
- Legacy SCADA integration friction:Proprietary protocols in existing industrial control systems create technical barriers for seamless wearable data ingestion at brownfield facilities.
Strategic Opportunities
- Canadian workers' compensation premium reforms:Provincial programs in Ontario and Alberta are piloting connected PPE subsidies that reduce insurance rates for compliant employers.
- Predictive fatigue algorithm maturation:Wearable Sensors category expansion is creating white space for biometric heat-stress monitoring in foundries and chemical processing plants.
- Aviation MRO channel innovation:Third-party maintenance providers are adopting hands-free smart glasses for guided assembly, bypassing traditional distributor networks.
Industry Challenges
- Industrial IoT cybersecurity certification:NIST framework compliance for edge-computing chipsets is extending product launch timelines by eight to fourteen months.
- Union workforce training capacity:Collective bargaining agreements in steel and petrochemical sectors are limiting vendor access to pilot programs without joint labor-management approval.
- IP67+ ingress protection testing backlog:Certified laboratory capacity constraints in the United States are delaying hardware validation for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Wearable Devices Market |
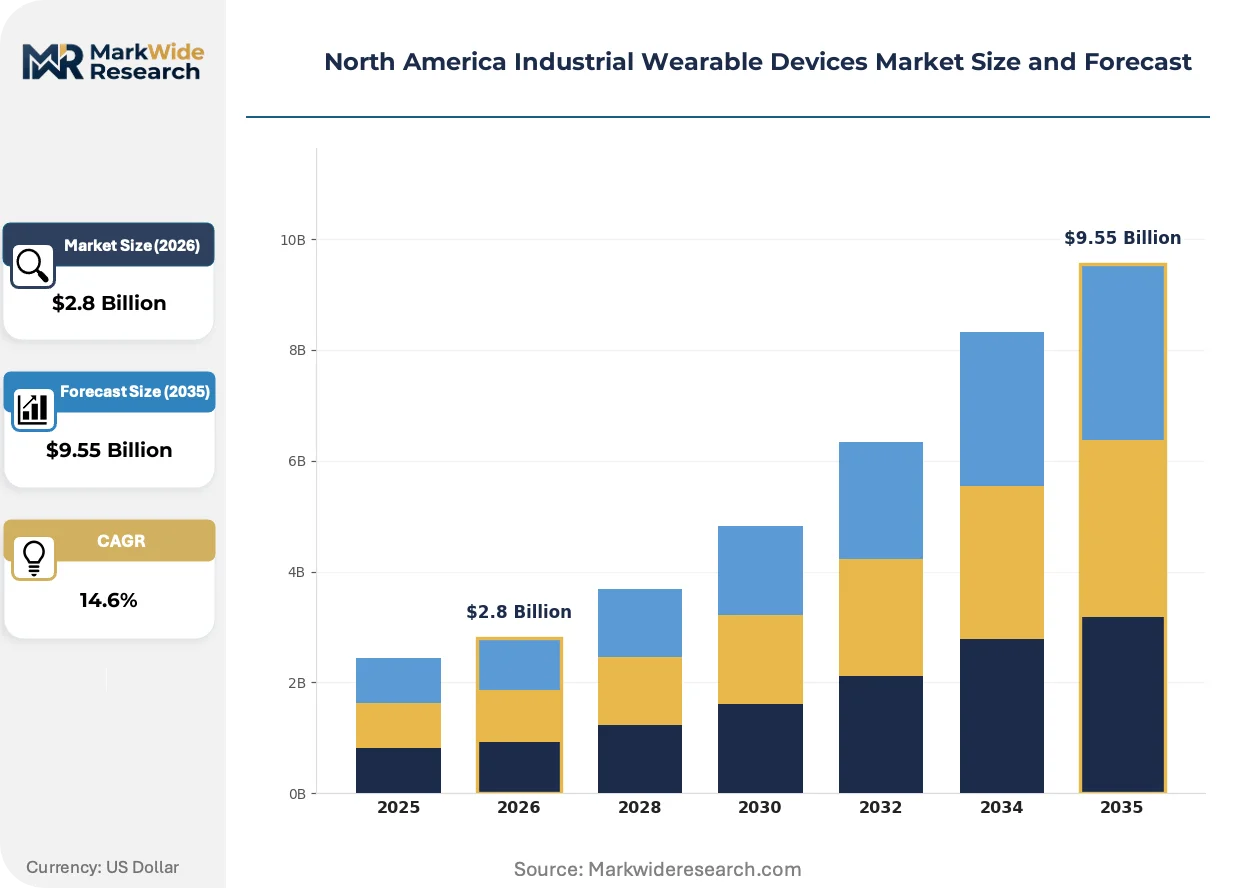
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Glasses, Smart Helmets, Wearable Sensors, Smart Clothing Technology: Augmented Reality, Virtual Reality, IoT, Bluetooth Application: Safety Monitoring, Equipment Maintenance, Training, Performance Tracking End User: Manufacturing, Construction, Logistics, Energy |
| Companies Covered | Samsung Electronics, Vuzix Corporation, Apple Inc., 3M Company, RealWear Inc., Alphabet Inc., Microsoft Corporation, Trimble Inc., Garmin Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Wearable Devices Market Strategic Shifts & Innovations
Edge-computing architectures are redistributing processing loads from cloud to device, enabling real-time hazard alerts without latency-dependent connectivity in subterranean or shielded industrial environments.
Multi-day battery architectures with localized inference engines are expanding into underground mining operations where surface connectivity is unavailable for twelve-hour shifts. Canadian potash and copper producers in Saskatchewan are piloting these systems at twice the pace of surface facilities. This expansion is compressing the addressable market for cloud-dependent alternatives in geographically isolated extraction sites.
OSHA workplace exposure threshold updates are mandating continuous personal monitoring for respirable crystalline silica in construction and foundry operations. The directive forces sensor network upgrades that capture biometric and environmental data streams simultaneously. Manufacturing facilities in Illinois and Ohio are responding with fleet-wide wearable sensor deployments ahead of enforcement deadlines.
After-sales service unbundling is fragmenting traditional hardware-plus-support contracts into separate device, software, and analytics subscriptions. Aviation maintenance providers in Texas and California are driving this shift, preferring per-seat licensing for remote expert guidance platforms over capital-intensive hardware purchases. The model is most visible in energy sector deployments where OpEx treatment improves project approval velocity.
North America Industrial Wearable Devices Market Segmentation
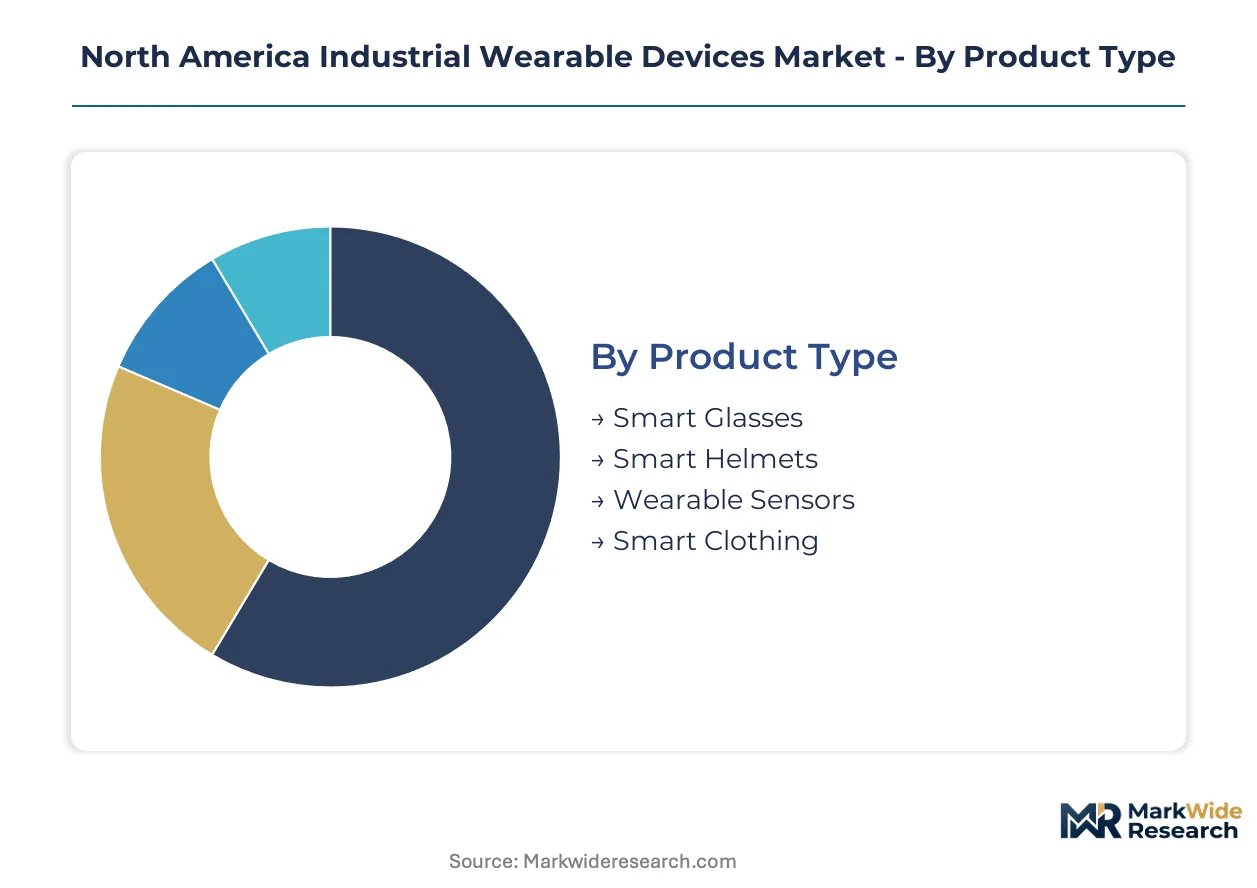
Industrial wearable procurement in North America follows distinct technical and operational logics. Buyers prioritize ingress protection ratings, battery endurance, and regulatory certification depth over feature breadth. Segmentation reveals where capital allocation concentrates and which technology trajectories reshape competitive positioning.
Product Type:
Capital deployment intensity varies sharply across hardware form factors, with ruggedization requirements and shift-length battery architectures driving total cost of ownership calculations.
- Smart Glasses:Binocular and monocular head-mounted displays with IP67+ sealing anchor remote assistance and guided assembly workflows. Demand clusters in Texas oil and gas operations and Great Lakes automotive plants where hands-free equipment inspection reduces downtime. OSHA-compliant voice control interfaces dominate specifications.
- Wearable Sensors:Biometric and environmental monitoring bands, patches, and badges with edge-computing chipsets process heat-stress and fatigue data locally. Illinois foundries and Ohio steel mills deploy fleet-wide ahead of respirable crystalline silica enforcement deadlines. Predictive algorithm maturation is accelerating replacement cycles.
- Smart Helmets:Integrated hard hats with proximity sensors and heads-up displays target construction and underground mining where impact protection merges with situational awareness.
- Smart Clothing:Sensor-embedded uniforms and exoskeleton textiles address ergonomic load monitoring in warehousing and repetitive assembly environments.
Smart Glasses leads on scale; Wearable Sensors leads on momentum.
Technology:
Connectivity architecture selection determines deployment feasibility in shielded industrial environments and underground facilities with intermittent surface links.
- Augmented Reality:Spatial computing overlays delivering real-time schematics and expert guidance dominate maintenance applications. Michigan heavy machinery manufacturers and California aviation MRO providers standardize on AR platforms for technician training compression.
- IoT:Mesh-networked sensor arrays with localized inference engines enable continuous environmental monitoring without cloud dependency. Saskatchewan potash mines and Alberta oil sands operations pilot twelve-hour-shift systems where surface connectivity is unavailable.
- Virtual Reality:Immersive simulation environments concentrate in high-hazard training scenarios including chemical plant emergency response and electrical safety certification.
- Bluetooth:Short-range personal area networks support proximity alerts and equipment pairing in congested factory floors where unlicensed spectrum avoids FCC coordination delays.
Augmented Reality captures the largest installed base; IoT is climbing the fastest as edge-computing architectures mature.
Application:
Return-on-investment visibility determines adoption sequencing, with compliance-driven deployments outpacing discretionary productivity investments.
- Safety Monitoring:Continuous personal exposure tracking for respirable crystalline silica, heat stress, and chemical vapor integrates biometric and environmental data streams. EPA emissions mandates and OSHA threshold updates are converting voluntary programs into mandatory fleet rollouts across Illinois construction and Ohio foundry operations.
- Equipment Maintenance:Remote expert guidance and augmented work instructions reduce mean-time-to-repair in distributed facilities. Texas Permian Basin operators deploy ruggedized voice-controlled units for wellhead inspection without shutdown.
- Training:Accelerated competency certification through immersive simulation and guided assembly reduces onboarding duration in unionized manufacturing environments.
- Performance Tracking:Ergonomic load monitoring and motion analysis optimize workforce deployment in logistics and warehousing operations.
Safety Monitoring leads on contract value; Equipment Maintenance leads on expansion velocity.
End User:
Industry-specific regulatory exposure and insurance incentive structures create divergent procurement timelines across verticals.
- Manufacturing:Union-negotiated safety premiums across Michigan, Ohio, and Illinois generate immediate payback visibility for connected PPE fleet investments. Automotive and heavy machinery sectors prioritize smart glasses for assembly guidance.
- Energy:Oil and gas operators in Texas and Alberta drive ruggedized wearable demand where explosive atmosphere certification and voice control are non-negotiable. Remote inspection use cases dominate capital allocation.
- Construction:Silica exposure monitoring mandates are accelerating sensor deployments ahead of enforcement deadlines in Illinois and California infrastructure projects.
- Logistics:Ergonomic optimization and warehouse safety applications concentrate in Midwest distribution corridors serving e-commerce fulfillment networks.
Manufacturing leads on volume deployment; Energy leads on unit value and specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The industrial wearable sector first achieved commercial scale in United States manufacturing corridors during the early 2010s, when automotive and aerospace producers piloted hands-free assembly guidance systems in Michigan and Ohio facilities.
United States
OSHA silica exposure mandates are converting voluntary safety programs into mandatory fleet rollouts across Illinois construction sites and Ohio foundry operations. The EPA's tightened emissions monitoring standards force continuous environmental sensing in Great Lakes manufacturing plants. Texas Permian Basin oil and gas operators deploy ruggedized voice-controlled head-mounted displays for remote wellhead inspection without production shutdowns.
Canada
Provincial workers' compensation reforms in Ontario and Alberta subsidize connected PPE investments through premium reduction programs for compliant employers. Health Canada enforces electrical safety standards for battery-powered wearables in hazardous locations, creating parallel certification requirements with U.S. regulators. Saskatchewan potash and copper producers pilot twelve-hour-shift edge-computing systems at twice the pace of surface facilities.
Mexico
Maquiladora automotive assembly plants in Nuevo León and Baja California adopt smart glasses for technician training compression and quality assurance workflows. Mexico's federal labor inspectorate aligns occupational safety protocols with U.S. OSHA frameworks to maintain export market access. Guanajuato's aerospace manufacturing cluster sources augmented reality platforms from cross-border distributors serving the Texas industrial corridor.
North America Industrial Wearable Devices Market Key Industry Players
Premium-margin players sit above commodity-margin players across regulatory certification depth and ruggedization specification intensity. The vendor base organizes into three tiers: diversified technology conglomerates with mixed-reality ecosystems, specialized wearable hardware fabricators with vertical industry focus, and component suppliers licensing sensor and connectivity modules. Consolidation pressures favor established players with parallel OSHA-FCC-Health Canada documentation capabilities. Strategic moves concentrate on strategic partnerships with industrial automation vendors and portfolio diversification into predictive analytics software layers.
Within the specialized hardware tier, Vuzix Corporation and RealWear Inc. exemplify divergent ruggedization philosophies for hazardous industrial environments. Microsoft Corporation anchors the enterprise software-integrated segment through mixed-reality platform licensing. Samsung Electronics and Apple Inc. occupy consumer-electronics-adjacent positions where industrial variants leverage existing supply chain scale. Alphabet Inc. and Trimble Inc. represent geospatial and connectivity-specialized entrants with construction and logistics sector alignment.
| Leading Market Players |
|---|
| Samsung Electronics |
| Vuzix Corporation |
| Apple Inc. |
| 3M Company |
| RealWear Inc. |
| Alphabet Inc. |
| Microsoft Corporation |
| Trimble Inc. |
| Garmin Ltd. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between OSHA-compliant ruggedized units and consumer-electronics-adapted alternatives splits pricing power across parallel supply ecosystems. Premium-tier vendors command sustained margins through Health Canada electrical safety documentation and IP67+ validation, while commodity players absorb lithium-ion cell volatility through volume scale in Great Lakes manufacturing corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors procurement decisions, with OSHA-FCC-Health Canada certification depth and shift-length battery endurance as primary price differentiation drivers. Cost compression in the economy tier is intensifying because lithium-ion chemistry volatility squeezes multi-day architecture margins. Union-negotiated safety premiums in Michigan and Ohio make manufacturing buyers least price-sensitive, while logistics operators in Midwest distribution corridors exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese edge-computing chipsets and South Korean lithium-ion cell suppliers, with final assembly concentrating in Mexico and China. Raw material dependencies span rare-earth magnets for haptic motors, gallium nitride semiconductors for power management, and flame-retardant polymers for IP67+ housings. Tariff exposure on Chinese-sourced sensor modules threatens margin stability at smaller fabricators. Distribution runs through industrial automation distributors and direct enterprise sales teams serving Texas oil operators and Great Lakes automotive plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America Industrial Wearable Devices functions as a stable compounder, with regulatory compliance mandates converting voluntary safety spending into recurring procurement cycles across hazardous industries.
For Market Incumbents: Cement regulatory documentation advantages by deepening parallel OSHA-FCC-Health Canada certification portfolios before provincial workers' compensation reforms expand subsidy eligibility. Prioritize backward integration into edge-computing chipsets to offset Taiwanese foundry concentration risk from emerging IoT cybersecurity certification delays. For New Entrants and Emerging Players: Enter via Canadian provincial premium reduction programs in Ontario and Alberta, where connected PPE subsidies create immediate payback visibility without entrenched vendor relationships. Target predictive fatigue algorithm development for foundry and chemical processing applications, partnering with third-party aviation MRO providers bypassing traditional distributor networks. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized wearable hardware fabricators holding vertical industry focus and established regulatory documentation. Five-to-ten-year viability favors vendors with predictive analytics software layer expansion and strategic partnerships with industrial automation vendors. Watch for NIST framework compliance acceleration as inflection signal for product launch timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Mixed-reality ecosystem licensing anchors enterprise training deployments in Michigan heavy machinery manufacturing. |
| Strategic Partnership | Industrial automation vendor alliances compress SCADA integration friction at brownfield Great Lakes facilities. |
| Acquisition of Specialist Firm | Predictive fatigue algorithm targets expand biometric heat-stress monitoring in Illinois foundry operations. |
| Geographic Expansion | Saskatchewan potash mine pilots for twelve-hour-shift edge-computing systems outpace surface facility adoption. |
| Product Launch | Ruggedized voice-controlled units capture Texas Permian Basin wellhead inspection without production shutdowns. |
Research Approach
Multiple input streams — primary interviews with plant engineers and maintenance directors, regulatory filings from OSHA and Health Canada, and customs trade data on lithium-ion cell imports — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from FCC equipment authorization databases, EPA emissions monitoring directives, and provincial workers' compensation program disclosures across Ontario and Alberta.
Historical shipment patterns were cross-referenced against panel input from industrial automation distributors and enterprise procurement leads to build the analytical framework across the modeling period. Segmentation dimensions included product type ruggedization tier, connectivity architecture, end-user industry regulatory exposure, and regional insurance incentive structure. CAGRs were derived from fleet rollout velocity curves calibrated to silica enforcement deadline proximity and union contract renewal cycles.
Inputs from OSHA enforcement calendars and Health Canada certification backlogs were available through the study window; gaps in real-time lithium-ion contract pricing introduce uncertainty bands around battery cost assumptions. Forecasts reflect documented assumptions on regulatory timeline adherence and provincial subsidy program expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Safety Critical Software Testing Market
Others
Latin America 3D Printing Construction Market
Others
Latin America Travel Retail Market
Others
Ceramic Machinery Market
Others
Global Hair Loss Treatment Products Market
Others
Europe Indoor Air Purification Market
Others
Military Sensors Market
Others
Powder Coating Equipment Market
Others
Air Separation Unit Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
HPHT Diamond Cubic Press Market
Others
Next Gen Video Codecs Market
Others
Mobile Retina Services Market
Others
Kuwait Retail Market
Others
North America Printed Signage Market
Others
Spain Feed Additives Market