
 Japan Automotive LED Lighting Market | 2026-2036
Japan Automotive LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive LED Lighting Market Insights
Japanese tier-1 lighting suppliers is repositioning production toward adaptive and matrix LED modules as domestic OEMs raise technical specifications. Koito Manufacturing leverages its captive semiconductor partnerships to secure chip supply for intelligent headlamp systems. Stanley Electric anchors its competitive stance through deep R&D investment in laser-excited phosphor architectures. Nichia Corporation dominates the upstream LED chip segment, supplying both captive and external module makers with high-luminance dies.
Japan Automotive LED Lighting encompasses solid-state illumination systems using gallium nitride-based emitters for exterior and interior vehicle applications, typically operating between 12V and 48V electrical architectures with luminous efficacy exceeding 130 lumens per watt. These systems replace halogen and xenon sources to reduce energy draw, extend service life, and enable dynamic beam shaping through electronic control. Front lighting modules command the largest value pool due to complexity in adaptive driving beam and matrix configurations, while interior lighting grows fastest as OEMs integrate human-centric circadian and RGB ambient systems. Factory-installed channels sustain the dominant volume share, though aftermarket providers compete aggressively on replacement cycles for aging vehicle fleets.
METI enforces minimum energy performance standards that effectively mandate LED conversion across new vehicle platforms, while JIS D 5500 and JIS D 5801 define photometric and durability benchmarks for automotive lamps. PMDA-aligned vehicle type approval processes, administered through Japan's Ministry of Land, Infrastructure, Transport and Tourism, require lighting subsystem certification before market release. Stakeholders must monitor the convergence of autonomous vehicle sensor fusion requirements with lighting module design, as LiDAR-transparent headlamp covers and integrated DRL-communication elements reshape procurement criteria.
Market Dynamics
The transition from halogen and xenon to solid-state illumination is compressing supplier margins while forcing module makers to absorb semiconductor content costs. METI efficiency mandates and JIS photometric standards are accelerating platform redesign cycles across Toyota, Honda, and Nissan production networks.
Growth Catalysts
- METI Energy Performance Standards:Minimum efficacy requirements now effectively prohibit non-LED headlamp designs on new vehicle platforms, eliminating halogen and xenon alternatives from factory specifications.
- Kanto Industrial Corridor Concentration:Dense supplier ecosystems surrounding Toyota City, Honda's Takanezawa R&D center, and Nissan's Yokohama headquarters enable rapid prototype-to-production cycles for adaptive lighting modules.
- Matrix LED Architectures:Dynamic beam shaping capabilities satisfy JIS D 5500 glare limitations while enabling premium feature differentiation for domestic luxury nameplates.
Market Restraints
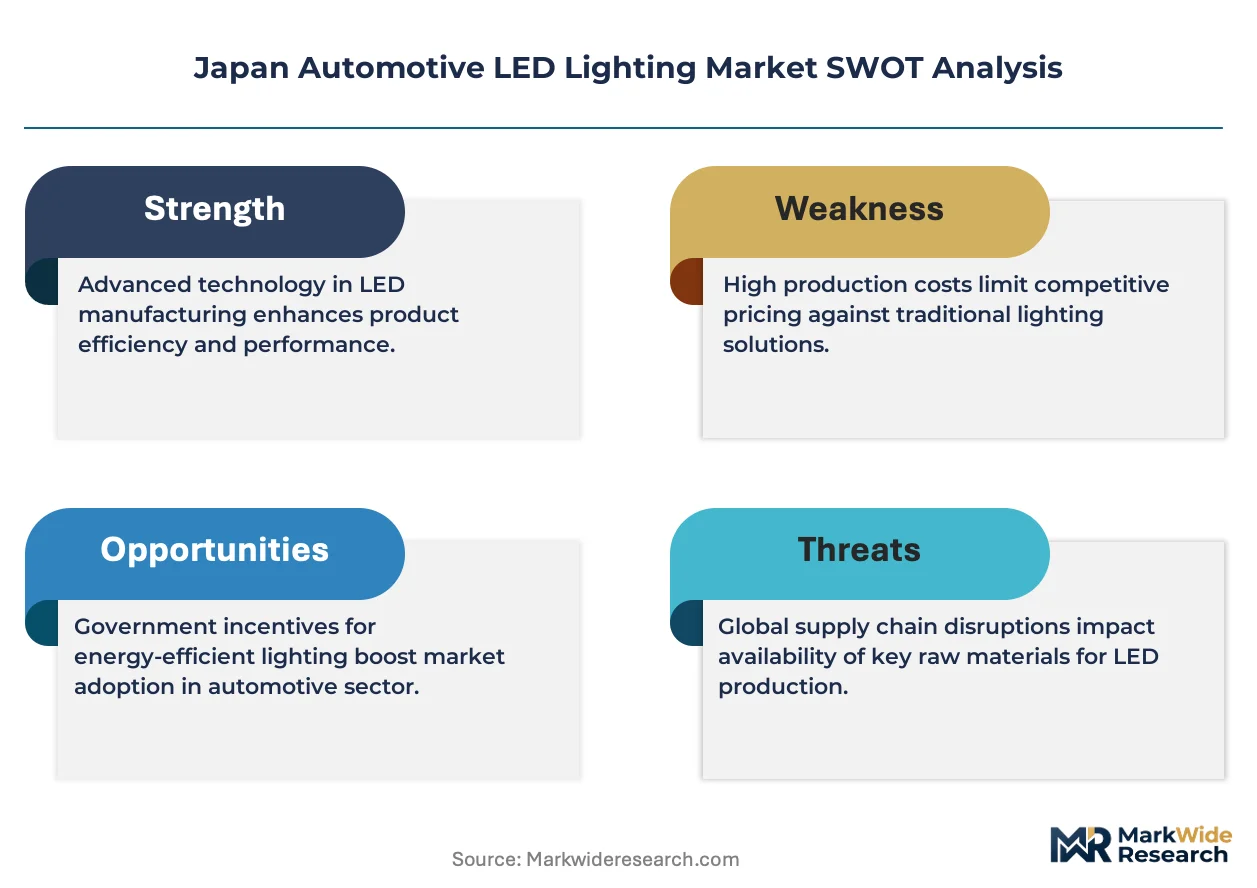
- Gallium Nitride Substrate Costs:Epitaxial wafer prices remain elevated due to limited sapphire and silicon carbide substrate supply, constraining module maker gross margins despite volume scaling.
- Upstream Chip Concentration:Nichia Corporation dominates high-luminance die supply for Japanese automotive applications, creating single-source dependency risks for tier-1 module assemblers.
- Legacy Fleet Replacement Cycles:Extended vehicle ownership patterns in Japan's aging demographic slow aftermarket LED conversion velocity relative to new vehicle installation rates.
Strategic Opportunities
- Human-Centric Interior Systems:Circadian rhythm and RGB ambient lighting applications represent underexploited white space as OEMs differentiate cabin experiences in premium segments.
- LiDAR-Transparent Headlamp Covers:Autonomous vehicle sensor fusion requirements are creating procurement specifications for optically engineered cover lenses that accommodate forward-facing perception hardware.
- Chubu and Kansi Manufacturing Bases:Nagoya-Osaka industrial corridors offer alternative production locations to relieve Kanto capacity constraints and diversify geographic risk exposure.
Industry Challenges
- Optomechanical Design Talent Scarcity:Shortage of engineers combining thermal management, optical simulation, and automotive EMC expertise delays adaptive module development timelines.
- PMDA Type Approval Complexity:Vehicle lighting subsystem certification through Japan's Ministry of Land, Infrastructure, Transport and Tourism requires extensive photometric testing that extends product launch schedules.
- Semiconductor Inventory Volatility:Lead time fluctuations for driver ICs and microcontrollers force module makers to carry elevated working capital buffers, compressing cash conversion cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive LED Lighting Market |
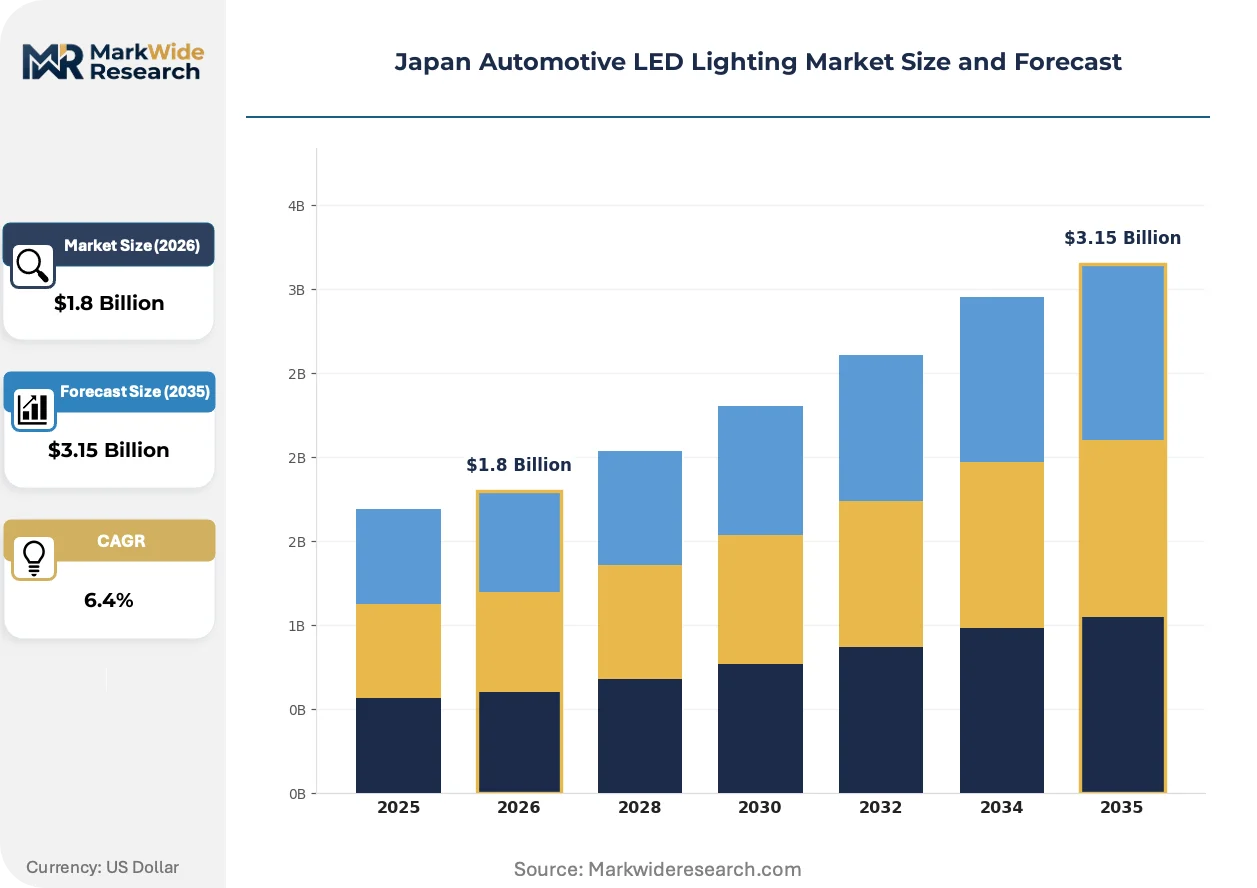
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Lighting, Rear Lighting, Interior Lighting, Indicators Technology: Human Centric, RGB, Adaptive Lighting, Matrix Lighting End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Installation: Factory-installed, Aftermarket, OEM-specific, Custom Installations |
| Companies Covered | Koito Manufacturing Co., Ltd., Stanley Electric Co., Ltd., Ichikoh Industries, Marelli Holdings Co., Ltd., Endo Lighting Corporation, Nichia Corporation, Panasonic Holdings Corporation, HELLA GmbH & Co. KGaA, Toshiba Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive LED Lighting Market Trends and Innovations
Lighting module functionality is expanding beyond illumination into vehicle communication and perception interfaces. Japanese OEM specifications now prioritize electronic control sophistication over raw lumen output.
Laser-excited phosphor architectures are rewriting performance benchmarks for long-range high-beam applications. Stanley Electric's R&D investments in this direction signal adoption acceleration among domestic premium nameplates. The technology is compressing thermal management requirements while extending throw distance beyond conventional LED limits.
JIS D 5801 durability benchmarks are tightening vibration and moisture ingress standards for exterior lamp assemblies. Module suppliers must redesign sealing systems and substrate mounting to satisfy revised test protocols. Front lighting applications face the steepest compliance burden given exposure severity and safety-critical classification.
Buyer consolidation among tier-1 integrators is compressing supplier negotiation leverage. Koito Manufacturing and Stanley Electric now specify die sourcing and optical design parameters that constrain sub-tier flexibility. This concentration is most visible in headlamp procurement for Toyota's Lexus and Nissan's Infiniti luxury divisions.
Japan Automotive LED Lighting Market Segmentation
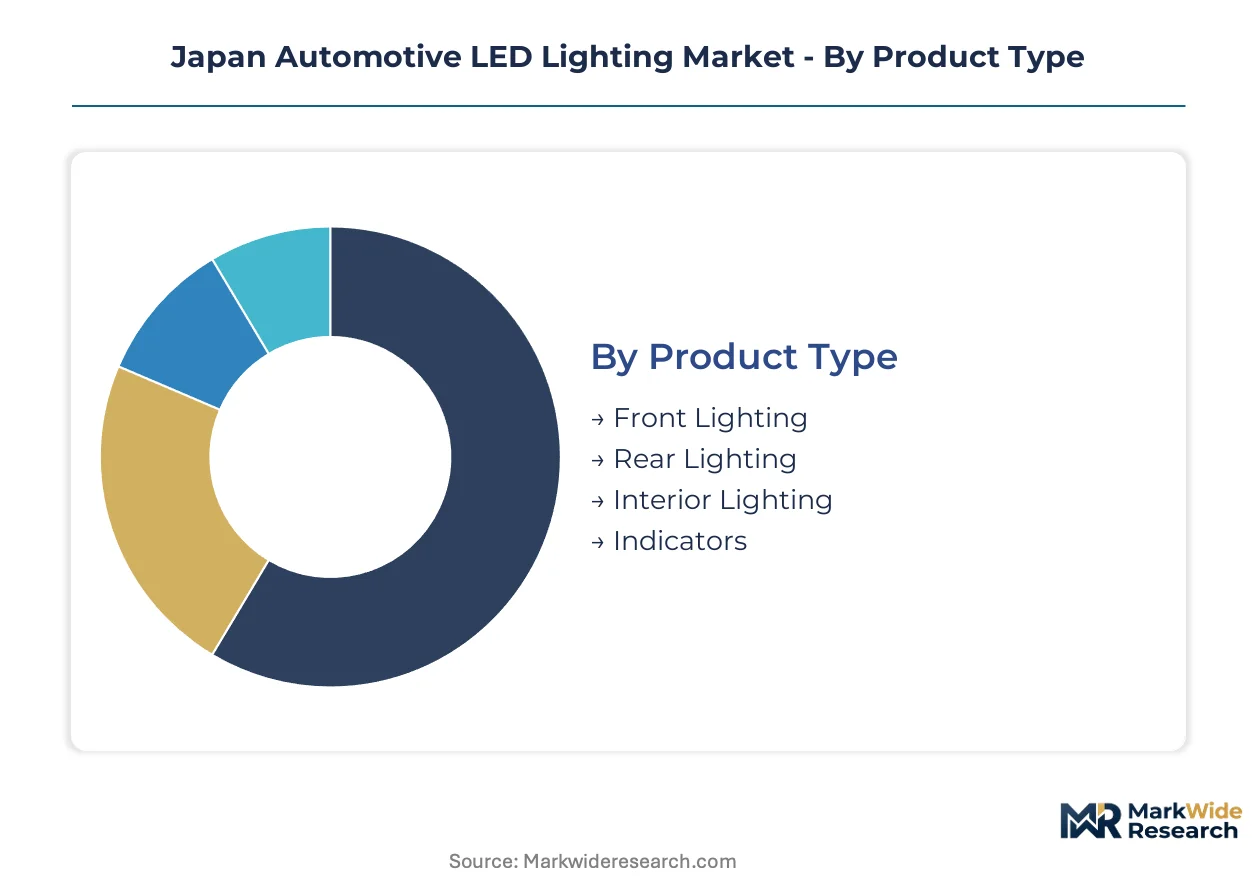
LED lighting segmentation in Japan reflects divergent technical requirements across vehicle zones and procurement channels. Module complexity, regulatory exposure, and OEM integration depth vary sharply by category, reshaping supplier specialization patterns.
Product Type:
Front lighting commands premium positioning due to adaptive beam complexity, while interior systems scale fastest on cabin experience differentiation.
- Front Lighting:Headlamp modules incorporating matrix and adaptive driving beam architectures dominate value capture. Toyota and Nissan specifications for Lexus and Infiniti nameplates concentrate demand in Kanto corridor tier-1 suppliers facing JIS D 5500 glare compliance burdens.
- Interior Lighting:Dashboard, footwell, and ambient systems enable circadian rhythm and RGB customization. Human-centric deployment is climbing the fastest as domestic OEMs differentiate premium cabin experiences against European rivals.
- Rear Lighting:Taillight and brake illumination modules emphasize signature design elements and sequential indicators.
- Indicators:Turn signal and hazard lamp assemblies balance visibility standards with styling integration.
Mature deployment sits with Front Lighting. Newer deployment is concentrated in Interior Lighting.
Technology:
Cost tier stratification separates established illumination from emerging electronic control platforms absorbing semiconductor content.
- Adaptive Lighting:Dynamic beam steering systems adjust intensity and direction based on vehicle speed, steering angle, and oncoming traffic. METI efficiency mandates and JIS glare limitations are accelerating factory fitment across Toyota and Honda mid-tier platforms.
- Matrix Lighting:Pixelated LED arrays enable precise shadow casting around oncoming vehicles. Domestic luxury procurement from Lexus and Infiniti divisions drives specification tightening in Kanto supplier ecosystems.
- Human Centric:Circadian-tuned spectral output adjusts cabin illumination to driver alertness cycles.
- RGB:Multi-zone color-variable ambient systems support brand-specific cabin atmospheres.
Volume concentration favors Adaptive Lighting. Specification advancement is steepest in Matrix Lighting.
End User:
Customer type determines integration depth, with captive OEM channels enforcing stricter validation protocols than aftermarket alternatives.
- OEMs:Toyota, Honda, and Nissan internal lighting divisions specify module architectures and validate subsystem performance. Direct procurement relationships with Koito Manufacturing and Stanley Electric concentrate in Yokohama and Toyota City corridors.
- Tier-1 Suppliers:Independent module assemblers serving multiple OEMs balance standardization against customization demands.
- Aftermarket Providers:Replacement and upgrade specialists target aging fleet conversion with simplified installation protocols.
- Vehicle Assemblers:Contract manufacturers and specialty builders source lighting as complete exterior assemblies.
Procurement leverage concentrates with OEMs. Channel expansion is most visible in Aftermarket Providers.
Installation:
Application timing creates divergent margin structures, with factory integration absorbing validation costs that aftermarket channels avoid.
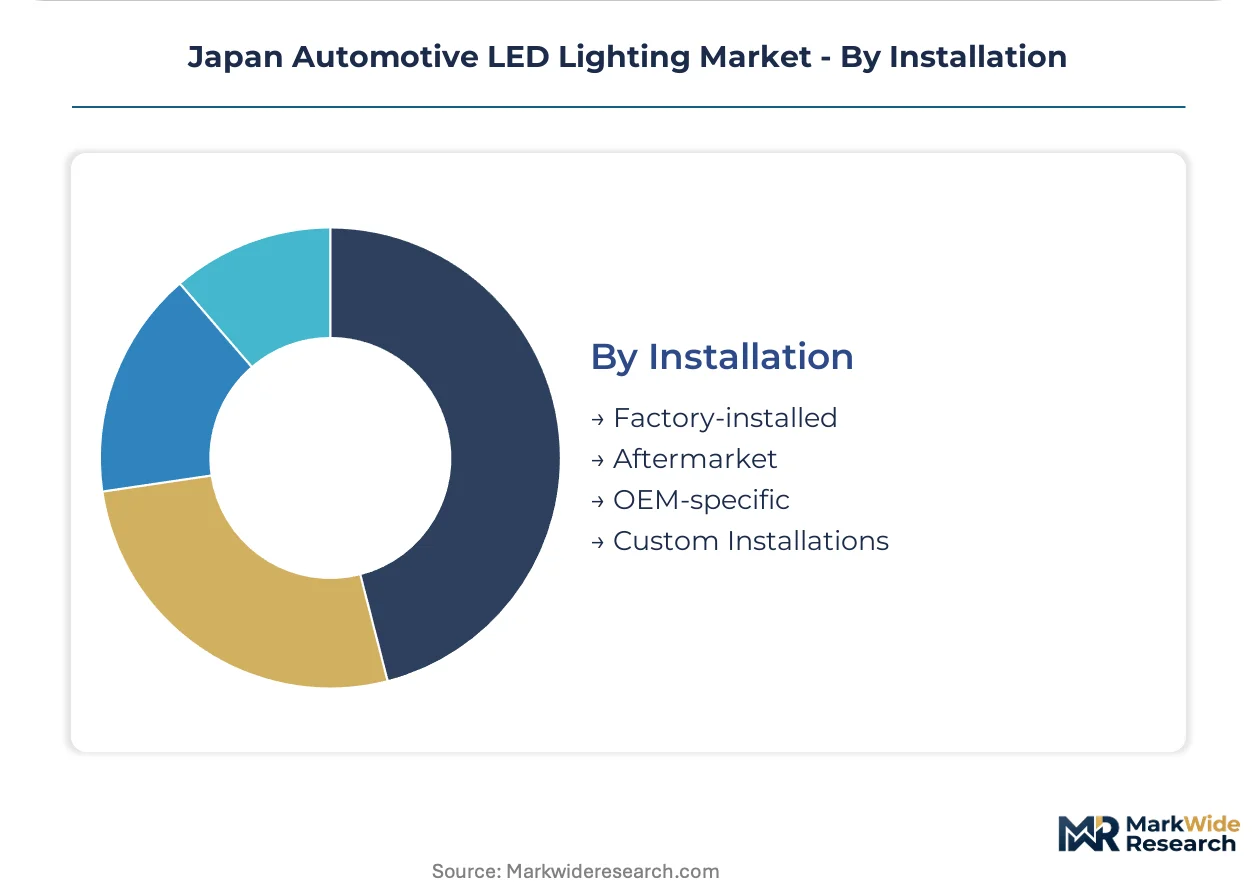
- Factory-installed:Original equipment fitment at vehicle assembly plants requires PMDA-aligned type approval through Japan's Ministry of Land, Infrastructure, Transport and Tourism. METI efficiency standards now effectively mandate LED configurations for new platforms.
- Aftermarket:Post-sale replacement and upgrade installations serve extended ownership cycles in Japan's aging demographic.
- OEM-specific:Captive supplier arrangements for exclusive nameplate programs.
- Custom Installations:Specialty and commercial vehicle modifications outside standard catalog offerings.
Revenue scale favors Factory-installed. Growth acceleration is strongest in Custom Installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride substrate supply from sapphire and silicon carbide sources anchors production economics across Japanese automotive LED corridors. Domestic module assembly concentrates where OEM engineering centers and tier-1 fabricators maintain tight co-location.
Kanto
Toyota City, Yokohama, and Takanezawa host dense supplier ecosystems for adaptive headlamp modules. METI energy performance standards enforce LED conversion timelines that compress prototype-to-production cycles. Koito Manufacturing and Stanley Electric anchor tier-1 capacity in this corridor, feeding Lexus and Infiniti luxury nameplates.
Chubu
Nagoya industrial bases support alternative production locations to relieve Kanto capacity constraints. JIS D 5500 glare compliance testing facilities cluster here alongside thermal management engineering centers. Tier-2 substrate processors and optical component specialists populate Aichi and Gifu prefectures.
Kansai
Osaka-Kobe corridors house Nichia Corporation's high-luminance die fabrication, supplying captive and external module makers. JIS D 5801 durability benchmark testing drives sealing system redesigns among exterior lamp assemblers. Laser-excited phosphor R&D activity concentrates in Kyoto-Nara satellite facilities.
Kyushu
Fukuoka and Nagasaki prefectures host semiconductor packaging operations supporting driver IC supply chains. PMDA-aligned vehicle type approval documentation requirements extend product launch schedules for regional assemblers. Automotive EMC testing laboratories serve tier-1 suppliers from satellite locations.
Tohoku
Sendai technology corridors attract optomechanical design talent for thermal simulation and optical engineering. METI efficiency mandates drive LED module standardization programs among regional component fabricators. Miyagi and Fukushima prefectures host specialty substrate processing for gallium nitride epitaxial growth.
Japan Automotive LED Lighting Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive supply arrangements. The vendor base stratifies into three tiers: integrated OEM-affiliated module makers, independent tier-1 assemblers, and specialized component suppliers. Strategic archetypes include backward-integrated semiconductor controllers, optical design specialists, and scale-driven commodity fabricators. Capacity expansion and strategic partnerships dominate competitive moves as players secure gallium nitride die supply.
Within the integrated module maker tier, Koito Manufacturing Co., Ltd. and Stanley Electric Co., Ltd. occupy positions exemplifying deep OEM relationships and adaptive lighting specialization. Nichia Corporation anchors the upstream segment as a representative of high-luminance die concentration. Among international participants, Marelli Holdings Co., Ltd. and HELLA GmbH & Co. KGaA sit within the tier-1 independent assembler archetype, balancing standardization against customization demands from multiple OEM customers.
| Leading Market Players |
|---|
| Koito Manufacturing Co., Ltd. |
| Stanley Electric Co., Ltd. |
| Ichikoh Industries |
| Marelli Holdings Co., Ltd. |
| Endo Lighting Corporation |
| Nichia Corporation |
| Panasonic Holdings Corporation |
| HELLA GmbH & Co. KGaA |
| Toshiba Corporation |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride epitaxial wafer pricing from sapphire and silicon carbide substrate suppliers cascades through Japanese automotive LED tiers, compressing margins at module assemblers while concentrating pricing power among Nichia Corporation and captive semiconductor controllers. METI efficiency mandates force rapid platform redesigns that absorb cost increases into factory-installed channels, leaving aftermarket providers exposed to raw material volatility without volume scale buffers.
Pricing Analysis
Extended warranty bundling for adaptive headlamp modules separates premium Lexus and Infiniti procurement from unbundled aftermarket replacement cycles. Three-tier pricing structure across premium, standard, and economy levels reflects JIS D 5500 certification grade, volume scale with Toyota and Honda, and vertical integration depth at Koito Manufacturing. Cost compression in tier-2 module assembly is intensifying because gallium nitride substrate prices remain elevated. Aftermarket providers show highest price sensitivity due to aging fleet ownership patterns, while OEM captive channels absorb validation costs with lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Nichia Corporation's dominance of high-luminance die supply for Japanese automotive applications. Geographic concentration centers on Japan for module assembly, Taiwan for semiconductor packaging, and China for sapphire substrate processing. Raw material dependencies include gallium nitride epitaxial wafers, silicon carbide substrates, and automotive-grade driver ICs. Tariff exposure on Chinese-processed substrates creates supply chain risk. Distribution runs through tier-1 integrators directly into Toyota, Honda, and Nissan production networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan Automotive LED Lighting is consolidating around semiconductor-integrated module makers as METI mandates and JIS compliance burdens force sub-tier assemblers without captive chip supply into exit or acquisition.
For Market Incumbents: Anchor competitive position through backward integration into gallium nitride die supply or exclusive semiconductor partnerships with Nichia Corporation. Expand thermal management engineering capacity in Chubu corridor to relieve Kanto bottlenecks. Defend against laser-excited phosphor substitution by accelerating R&D investment in next-generation architectures. For New Entrants and Emerging Players: Tier-2 optical component specialists offer partnership pathways into supply chains constrained by optomechanical design talent scarcity. Target human-centric interior lighting as the most penetrable segment, where circadian and RGB systems lack established supplier relationships. Pursue custom installation channels for specialty vehicle builders outside standard OEM catalog coverage. For Investors and Strategic Acquirers: Distressed-cycle entries favor tier-2 module assemblers with JIS D 5801 certification backlog in Kansai corridor. Long-term viability hinges on semiconductor inventory management capabilities across the analysis window. Watch for PMDA type approval timeline extensions as inflection indicator of regulatory burden intensity affecting smaller players.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Partnership Consolidation | Captive gallium nitride die supply secures module maker margin protection against Nichia price volatility. |
| Chubu Manufacturing Footprint Expansion | Nagoya-Aichi capacity relieves Kanto corridor constraints for Toyota and Honda prototype cycles. |
| Laser-Excited Phosphor R&D Investment | Stanley Electric's Kyoto-Nara development signals next-generation high-beam performance differentiation. |
| Human-Centric Interior System Launch | Circadian-tuned spectral output captures premium cabin experience white space against European rivals. |
| LiDAR-Transparent Cover Lens Development | Optically engineered headlamp covers meet autonomous vehicle sensor fusion procurement specifications. |
Research Methodology
Trade publications, METI regulatory filings, and JIS standard documentation formed the secondary backbone, cross-referenced with primary interviews across tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and semiconductor packaging specialists. Bottom-up and top-down triangulation validated volume estimates against vehicle production databases and customs records for gallium nitride substrate imports.
Bottom-up modeling segmented by vehicle class, propulsion architecture, content per vehicle, and regional production cluster generated install-base estimates. Top-down cross-checks applied macroeconomic assumptions across the analysis window. CAGRs derived from regression against historical LED penetration rates and METI mandate implementation timelines, with inputs from thermal management engineering cost curves and semiconductor lead time volatility indices.
Caveats apply where gallium nitride substrate price spikes, PMDA approval delays, or autonomous vehicle sensor fusion specification changes could materially shift the outlook. Forecasts reflect documented assumptions about JIS D 5500 compliance burden trajectory and tier-1 supplier consolidation velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
United States Smart Homes Market
Others
Taiwan Retail Market
Others
Lepidolite Market
Others
Fresh Apples Market
Others
Industrial PC Market
Others
Global OTA Testing Market
Others
Server Market
Others
Global Microcontroller Embedded Systems Market
Others
US Luxury Travel Market
Others
Bird Food Market
Others
Industrial Hooters Market
Others
India Foundry Market
Others
Aerospace Tester Market
Others
Industrial Personal Computer Market
Others
China Online Gambling Market