
 Hypersensitivity Market | 2026-2036
Hypersensitivity Market Size, Share, and Industry Trends Forecast 2026-2036
Hypersensitivity Market Outlook
A shortage of trained allergists and immunology specialists is redrawing how care networks deploy hypersensitivity diagnostics and treatments across major markets. Pfizer Inc. leverages its respiratory and inflammation portfolio to sustain commercial momentum in biologic therapies for severe allergic conditions. Sanofi anchors European market access through its established immunotherapy manufacturing footprint and primary care channel relationships. AstraZeneca competes aggressively in the asthma and allergic rhinitis overlap with targeted biologic development programs.
Hypersensitivity encompasses exaggerated immune responses to otherwise harmless environmental antigens, proteins, or pharmaceutical agents, mediated through IgE, T-cell, or complement activation pathways with measurable biomarker thresholds. The condition's primary commercial purpose centers on preventing life-threatening anaphylaxis, controlling chronic allergic inflammation, and enabling graded desensitization protocols in clinical settings. Biologics command the most attractive margin pool among product types as targeted monoclonal antibodies displace broad-spectrum corticosteroids in moderate-to-severe patient populations. Allergic rhinitis and asthma together dominate therapy area revenue due to their high prevalence and chronic treatment profiles, while food allergy represents the fastest-expanding segment driven by oral immunotherapy advances. Diagnostic laboratories and hospital systems capture disproportionate value in the end-user landscape through centralized testing infrastructure and specialist referral networks.
FDA, EMA, and WHO standards collectively govern allergen extract potency, biologic biosimilar equivalence, and anaphylaxis emergency kit specifications across regulated markets. These frameworks shape demand by mandating controlled clinical trial endpoints for immunotherapy approval and restricting direct-to-consumer diagnostic claims. Stakeholders must monitor evolving pharmacovigilance requirements for novel biologics and anticipate reimbursement recalibration as outcome-based contracts gain traction in public payer systems.
Market Dynamics
Biologics development pipelines are compressing traditional corticosteroid revenue streams as hospital systems reallocate formulary budgets toward targeted monoclonal antibodies with superior efficacy profiles in severe allergic populations.
Growth Catalysts
- FDA Accelerated Approval Pathways:Streamlined clinical trial endpoints for sublingual immunotherapy products are shortening registration timelines and expanding therapeutic access for seasonal allergy patients.
- Oral Immunotherapy Protocols:Standardized desensitization regimens for peanut and egg allergies are creating new treatment modalities in pediatric allergy clinics and academic medical centers.
- Japan:METI-funded biomanufacturing initiatives are strengthening domestic production capacity for recombinant allergen extracts and reducing import dependency for critical immunotherapy components.
Market Restraints
- Recombinant Protein Input Costs:Fermentation-grade growth media and cell line licensing fees impose fixed cost burdens on biologic developers regardless of batch scale.
- Specialist Concentration:Allergist training programs in the United States and Germany produce insufficient graduates to match patient referral volumes, creating appointment backlogs.
- EMA Biosimilar Equivalence Requirements:Immunogenicity testing mandates for follow-on biologics extend development timelines and elevate regulatory compliance expenditures.
Strategic Opportunities
- At-Home Epinephrine Auto-Injector Training:Digital therapeutics platforms paired with connected devices are opening direct-to-patient channels outside traditional pharmacy distribution.
- India:CDSCO harmonization with ICH guidelines is attracting contract manufacturing investment for allergen extract production serving Asian markets.
- AI-Assisted Phenotyping:Machine learning integration with multiplex IgE testing is enabling precision matching of biologic therapies to endotype-defined patient subgroups.
Industry Challenges
- Immunotherapy Administration Training:Nurse practitioners and primary care physicians require supervised competency certification before independent desensitization protocol management.
- Cold Chain Integrity:Temperature excursion risks during biologics distribution necessitate redundant monitoring infrastructure and contingency logistics planning.
- Legacy EHR Integration:Allergy-specific clinical decision support modules face interoperability barriers with hospital system enterprise platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hypersensitivity Market |
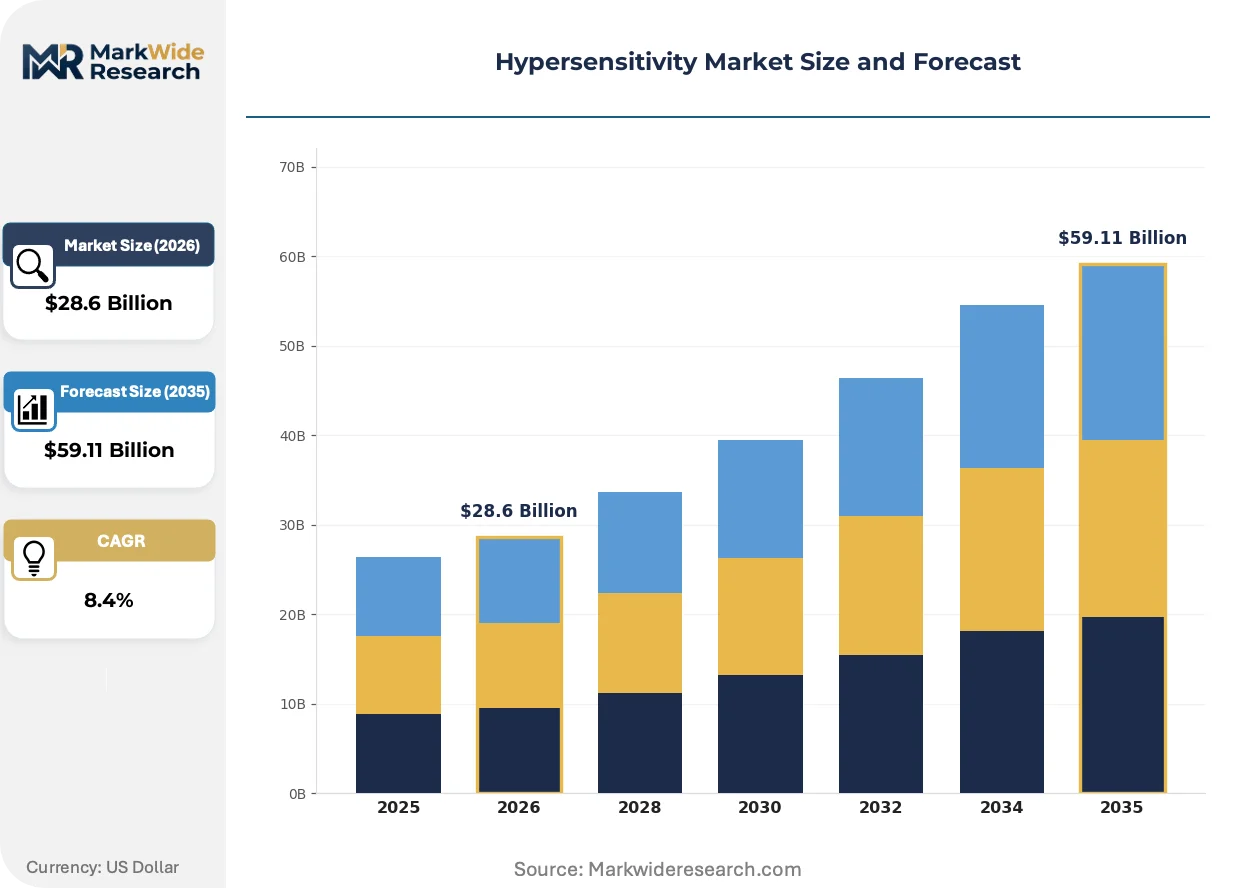
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antihistamines, Corticosteroids, Immunotherapy, Biologics Therapy Area: Allergic Rhinitis, Asthma, Food Allergy, Dermatological Reactions Application: Intradermal Tests, Skin Prick Tests, Blood Tests, Patch Tests End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories |
| Companies Covered | Pfizer Inc., Sanofi, Merck KGaA, GSK plc, AstraZeneca, AbbVie Inc, Teva Pharmaceutical Industries Ltd., Bristol-Myers Squibb Company, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hypersensitivity Market Strategic Shifts
Precision medicine approaches are fragmenting the traditional one-size-fits-all immunotherapy model as biomarker stratification enables tailored dosing regimens and risk-adjusted treatment pathways.
Multiplex component-resolved diagnostics are decomposing crude allergen extract testing into discrete molecular allergen profiles. Academic referral centers in Germany and the United States are adopting these platforms at accelerating pace. This granularity is decomposing the market for broad-spectrum immunotherapy mixtures into targeted single-allergen protocols with improved risk-benefit ratios.
EMA's revised Medical Device Regulation classification for in-vitro diagnostic platforms is elevating analytical validation requirements for multiplex IgE assays. Manufacturers must demonstrate traceability to WHO reference preparations and establish post-market surveillance systems. The diagnostic laboratory segment is responding through consolidation with larger reference networks capable of absorbing compliance infrastructure costs.
Patient self-administration preferences are compressing the traditional clinic-based injection model for biologic therapies. Home health nursing networks and specialty pharmacy distribution are displacing hospital infusion center visits for maintenance-phase patients. This channel rotation is most visible in the United States where payer pressure on site-of-care costs coincides with patient convenience demands.
Hypersensitivity Market Segmentation
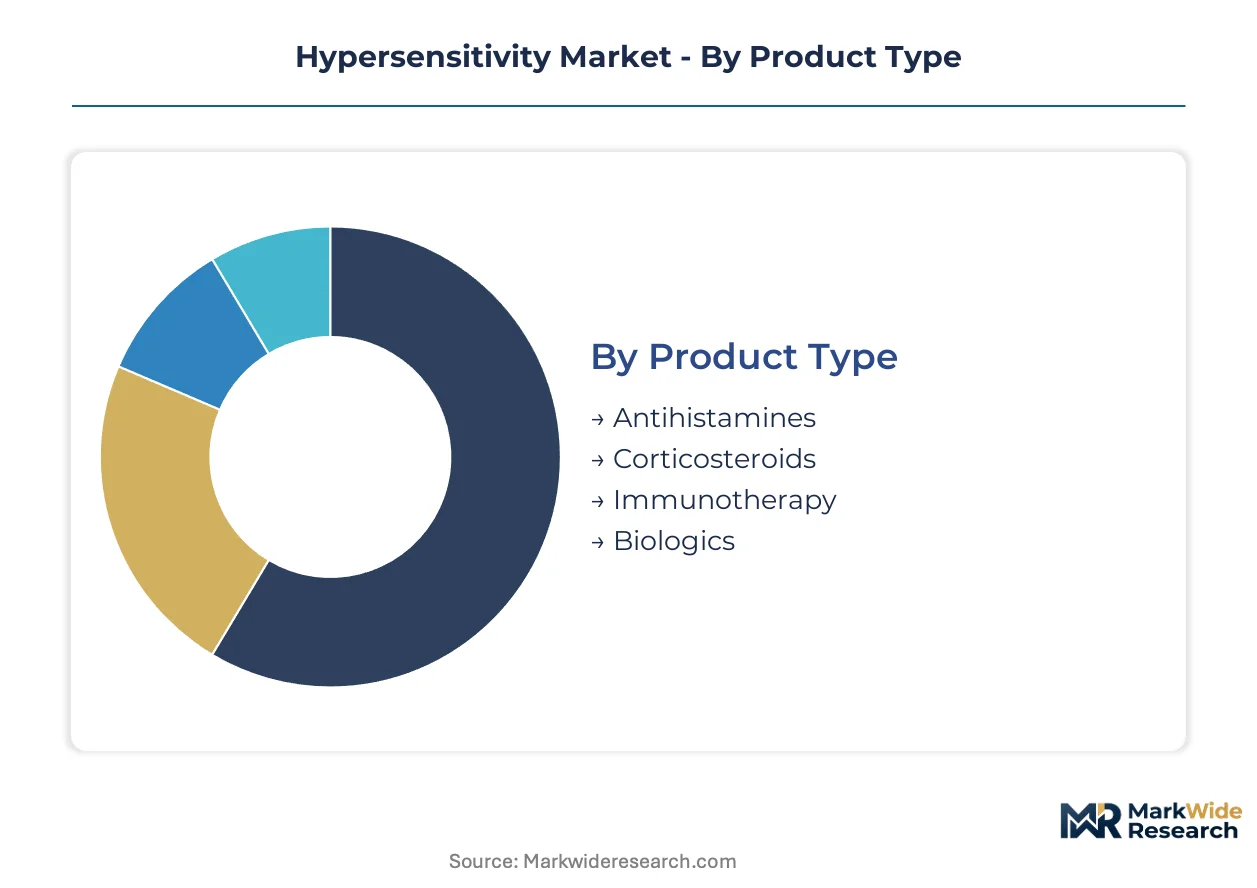
Hypersensitivity treatment selection hinges on severity stratification, with biologics displacing corticosteroids in refractory cases while oral immunotherapy protocols reshape pediatric food allergy management. Diagnostic modality choice reflects specialist availability and reimbursement density across hospital systems and ambulatory networks.
Product Type:
Biologics exert the strongest substitution pressure on legacy segments, with targeted monoclonal antibodies capturing formulary share from broad-spectrum immunosuppressants in severe allergic populations.
- Biologics:Engineered monoclonal antibodies targeting IgE, IL-4/IL-13, or IL-5 pathways deliver precision blockade of type 2 inflammation. Demand concentrates in United States academic medical centers where prior authorization pathways favor step-up therapy protocols. Omalizumab and dupilumab biosimilar entry will compress originator pricing within three years.
- Immunotherapy:Sublingual tablets and subcutaneous allergen extracts induce tolerance through controlled antigen exposure. European markets in Germany and France sustain volume leadership through pharmacy-dispensed SLIT protocols. EMA accelerated approval pathways are shortening registration timelines for grass and dust mite formulations.
- Corticosteroids:Inhaled and intranasal glucocorticoids remain first-line for chronic rhinitis and asthma maintenance.
- Antihistamines:Second-generation H1 antagonists dominate OTC seasonal allergy management with minimal sedation profiles.
Corticosteroids retain volume leadership across prescription fills; biologics hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates chronic maintenance indications from acute intervention segments, with food allergy commanding premium pricing for risk-mitigation therapies.
- Allergic Rhinitis:Perennial and seasonal nasal inflammation drives the largest patient addressable market. United States pollen belt states generate concentrated demand for immunotherapy and combination antihistamine-intranasal steroid products. Payer step therapy requirements delay biologic access in this segment.
- Food Allergy:IgE-mediated reactions to peanut, tree nut, milk, and egg proteins create acute anaphylaxis risk. Pediatric allergy clinics in Boston, Philadelphia, and London are expanding oral immunotherapy capacity faster than specialist supply. FDA-approved peanut allergen powder protocols are establishing reimbursement precedents.
- Asthma:Allergic asthma overlaps with rhinitis in the type 2 inflammatory endotype.
- Dermatological Reactions:Contact dermatitis and urticaria span acute and chronic presentation patterns.
Allergic rhinitis sustains the highest prescription volume; food allergy is climbing the fastest.
Application:
Diagnostic volume clusters where specialist referral networks and laboratory infrastructure overlap, with component-resolved testing penetrating academic centers first.
- Blood Tests:Serum-specific IgE quantification and basophil activation assays enable safe testing in antihistamine-treated patients. United States reference laboratories in North Carolina and California process high-throughput multiplex panels. EMA in-vitro diagnostic regulation is elevating analytical validation requirements for commercial assays.
- Skin Prick Tests:Epicutaneous allergen application with histamine and saline controls remains the standard of care for inhalant allergy diagnosis. German dermatology and allergy practices maintain high per-capita utilization rates. Nurse practitioner scope expansion is extending access in underserved United States counties.
- Intradermal Tests:Dermal allergen injection detects lower-specificity sensitization for venom and drug allergy.
- Patch Tests:Extended occlusive application identifies delayed-type hypersensitivity to metals and preservatives.
Skin prick testing dominates procedure counts; blood testing is gaining share fastest.
End User:
Site-of-care economics and reimbursement differentials concentrate high-value biologic administration in hospital outpatient settings while pushing maintenance therapy toward home channels.
- Hospitals:Academic medical centers and community hospital systems capture biologic infusion revenue and manage severe anaphylaxis episodes. United States 340B pricing programs distort site-of-care incentives toward hospital-owned clinics. Emergency department epinephrine administration protocols drive formulary standardization.
- Diagnostic Laboratories:Centralized reference networks achieve scale economies in multiplex IgE and molecular allergen testing. Quest Diagnostics and LabCorp consolidation in the United States limits regional competitor viability. CAP proficiency testing requirements maintain quality barriers.
- Clinics:Allergy specialist and primary care sites handle initiation and monitoring.
- Home Care:Self-administered epinephrine auto-injectors and oral immunotherapy maintenance are expanding.
Hospitals retain the highest revenue per patient encounter; diagnostic laboratories are expanding throughput fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor United States market expansion, while EMA regulatory harmonization and Japan's METI biomanufacturing initiatives reshape regional competitive dynamics across the major hypersensitivity therapy markets.
United States
Pollen belt states generate concentrated seasonal allergy demand, with Texas and Georgia expanding oral immunotherapy clinic capacity faster than specialist supply growth. FDA streamlined endpoints for sublingual immunotherapy compress registration timelines for grass and dust mite formulations. Boston and Philadelphia pediatric allergy centers establish reimbursement precedents for peanut allergen powder protocols.
Germany
Pharmacy-dispensed sublingual immunotherapy protocols sustain European volume leadership in perennial and seasonal rhinitis management. EMA accelerated approval pathways shorten market entry timelines for recombinant allergen extracts. Munich and Heidelberg academic referral centers adopt multiplex component-resolved diagnostics at accelerating pace, fragmenting broad-spectrum immunotherapy demand.
Japan
Domestic biomanufacturing initiatives reduce import dependency for critical immunotherapy components and recombinant allergen extracts. METI-funded production capacity expansion strengthens supply security for biologic therapies targeting severe allergic populations. Osaka and Tokyo hospital systems concentrate specialist care infrastructure and prior authorization pathways for step-up therapy protocols.
United Kingdom
London and Manchester allergy centers face appointment backlogs as training programs produce insufficient allergist graduates to match pediatric food allergy referral volumes. NHS outcome-based contracting pilots recalibrate reimbursement for biologic therapies in moderate-to-severe asthma populations. Cambridge diagnostic laboratory networks achieve scale economies in multiplex IgE testing infrastructure.
India
CDSCO harmonization with ICH guidelines attracts contract manufacturing investment for allergen extract production serving Asian markets. Hyderabad and Bangalore reference laboratories expand centralized testing infrastructure for serum-specific IgE quantification. Mumbai and Delhi hospital systems build specialist referral networks for graded desensitization protocol management.
Hypersensitivity Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the hypersensitivity therapy landscape, with biologic developers commanding premium positioning while generic manufacturers capture volume in legacy corticosteroid and antihistamine segments. The market structure fragments across three strategic tiers: multinational pharmaceutical conglomerates with respiratory and inflammation portfolios, specialized immunotherapy manufacturers with established European distribution networks, and emerging biologic developers targeting precision medicine niches. Dominant competitive moves include strategic partnerships between diagnostic platform developers and reference laboratory networks, alongside geographic expansion through localized allergen extract manufacturing in high-growth Asian markets.
Among the multinational pharmaceutical conglomerates, Pfizer Inc., Sanofi, and AstraZeneca occupy positions exemplifying distinct competitive archetypes within the hypersensitivity therapy ecosystem. Pfizer represents the respiratory and inflammation portfolio consolidator leveraging commercial infrastructure across severe allergic indications. Sanofi anchors European market access through immunotherapy manufacturing footprint and primary care channel relationships. AstraZeneca sits within the asthma-allergic rhinitis overlap segment with targeted biologic development positioning. These three companies collectively illustrate how scale, geographic concentration, and therapeutic focus differentiate strategic positioning across the competitive landscape.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Sanofi |
| Merck KGaA |
| GSK plc |
| AstraZeneca |
| AbbVie Inc |
| Teva Pharmaceutical Industries Ltd. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Batch-scale fermentation economics in recombinant allergen production create steep minimum efficient scale thresholds that concentrate biologics manufacturing among a handful of multi-product facilities and establish price floors resistant to small-volume competition. This cost structure funnels margin capture toward integrated developers with captive cell line libraries and long-term growth media contracts, while fragmenting extract-based immunotherapy supply across regional compounding networks with divergent cost bases.
Pricing Analysis
United States biologic infusion pricing runs 40-60% above German hospital procurement rates for equivalent anti-IgE and IL-4/IL-13 pathway inhibitors, reflecting 340B program distortions and site-of-care reimbursement differentials. Pricing stratifies across premium, standard, and economy tiers: originator monoclonal antibodies command premium positioning, biosimilar entrants capture standard tier share, and legacy corticosteroids occupy economy positioning. Price erosion runs through the corticosteroid segment as formulary step-therapy protocols delay biologic access. Pediatric allergy clinics demonstrate highest price sensitivity due to cash-pay oral immunotherapy protocols, while academic medical centers show lowest sensitivity given bundled reimbursement for severe asthma populations.
Supply Chain Analysis
Germany and the United States anchor recombinant allergen extract production through specialized fermentation facilities serving European and North American immunotherapy markets. Critical inputs include fermentation-grade growth media, proprietary cell line licenses, and purified allergen source materials. Single-source vulnerability concentrates in Chinese-manufactured cell culture media components subject to export licensing variability. Distribution runs through cold-chain specialty pharmacy networks for biologics, with oral immunotherapy tablets flowing through wholesale-to-retail pharmacy channels in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated United States hospital systems and integrated German pharmacy networks, squeezing standalone immunotherapy manufacturers without captive distribution or formulary placement guarantees.
For Market Incumbents: Shield biologic revenue streams through backward integration into cell line development and fermentation capacity expansion in METI-subsidized Japanese facilities. Lock in hospital system formulary placement through outcome-based risk-sharing contracts that offset biosimilar price competition. Prioritize EMA accelerated approval pathway investment for sublingual tablet formulations to compress generic substitution windows.
For New Entrants and Emerging Players: FDA breakthrough therapy designation fast-tracks offer the most penetrable regulatory entry point for novel biologic mechanisms in food allergy. Target pediatric oral immunotherapy maintenance protocols in United States pollen belt states where specialist shortages create access gaps. Pursue reference laboratory partnerships for AI-assisted phenotyping platforms that enable precision matching to underserved endotype-defined subgroups.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic platform developers with multiplex IgE capabilities and established CAP proficiency testing infrastructure. Long-term viability hinges on consolidation capture as EMA in-vitro diagnostic regulation elevates compliance costs beyond mid-tier laboratory reach. Watch for inflection in oral immunotherapy reimbursement precedent expansion beyond peanut to multi-allergen protocols as signal for segment acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Accelerated Approval Pathway Investment | Shortens registration timelines for grass and dust mite sublingual formulations in European markets. |
| CDSCO Harmonization Compliance | Enables contract manufacturing investment for allergen extract production serving Asian markets. |
| AI-Assisted Phenotyping Platform Integration | Matches biologic therapies to endotype-defined patient subgroups in academic referral centers. |
| Cold Chain Infrastructure Expansion | Reduces temperature excursion risks during biologics distribution to hospital outpatient settings. |
| Oral Immunotherapy Clinic Capacity Buildout | Captures pediatric food allergy demand in Boston, Philadelphia, and London referral networks. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with biologics development executives, regulatory affairs leads at EMA and FDA, hospital formulary directors, and allergy specialist clinic administrators; and secondary validation through FDA 510(k) filings, EMA centralized procedure assessments, ClinicalTrials.gov protocol registries, and United States hospital procurement databases. Bottom-up patient population modeling triangulated against top-down pharmaceutical revenue segmentation.
Across the analysis window, the forecasting framework modeled treatment line stratification, administration route differentiation, regional regulatory cluster dynamics, and patient severity segmentation. CAGRs derived from spline interpolation of historic approval velocity and patent expiry schedules, with inputs including biosimilar entry timelines and oral immunotherapy protocol adoption curves in pediatric allergy networks.
Decision-makers should treat outputs as directional under assumptions of sustained FDA accelerated approval pathway utilization and stable EMA immunogenicity testing requirements; material deviation in regulatory stringency or reimbursement recalibration would warrant model refresh. Recalibration cycles align with material shifts in biosimilar equivalence determinations and oral immunotherapy reimbursement precedent expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Fabric Based Computing Market
Others
Augmented Reality in Energy and Utilities Market
Others
Metal Ore Mining Market
Others
Mobile Computer Cart Market
Others
Pet Care Packaging Market
Others
Surface Green Mining Market
Others
Cryogenic Storage Tanks Market
Others
Advanced Combat Helmet Market
Others
Cloud-Based Streaming Services Market
Others
Global Pregnancy Tracker Apps Market
Others
Bimodal Identity Management Solutions Market
Others
Wearable Solar Devices Market
Others
Aircraft Lighting Market
Others
India Data Center Physical Security Market
Others
Finished Leather Market
Others
Global Optical Coordinate Measuring Machine Market