
 Inflight Entertainment Solutions Market | 2026-2036
Inflight Entertainment Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Inflight Entertainment Solutions Market Insights
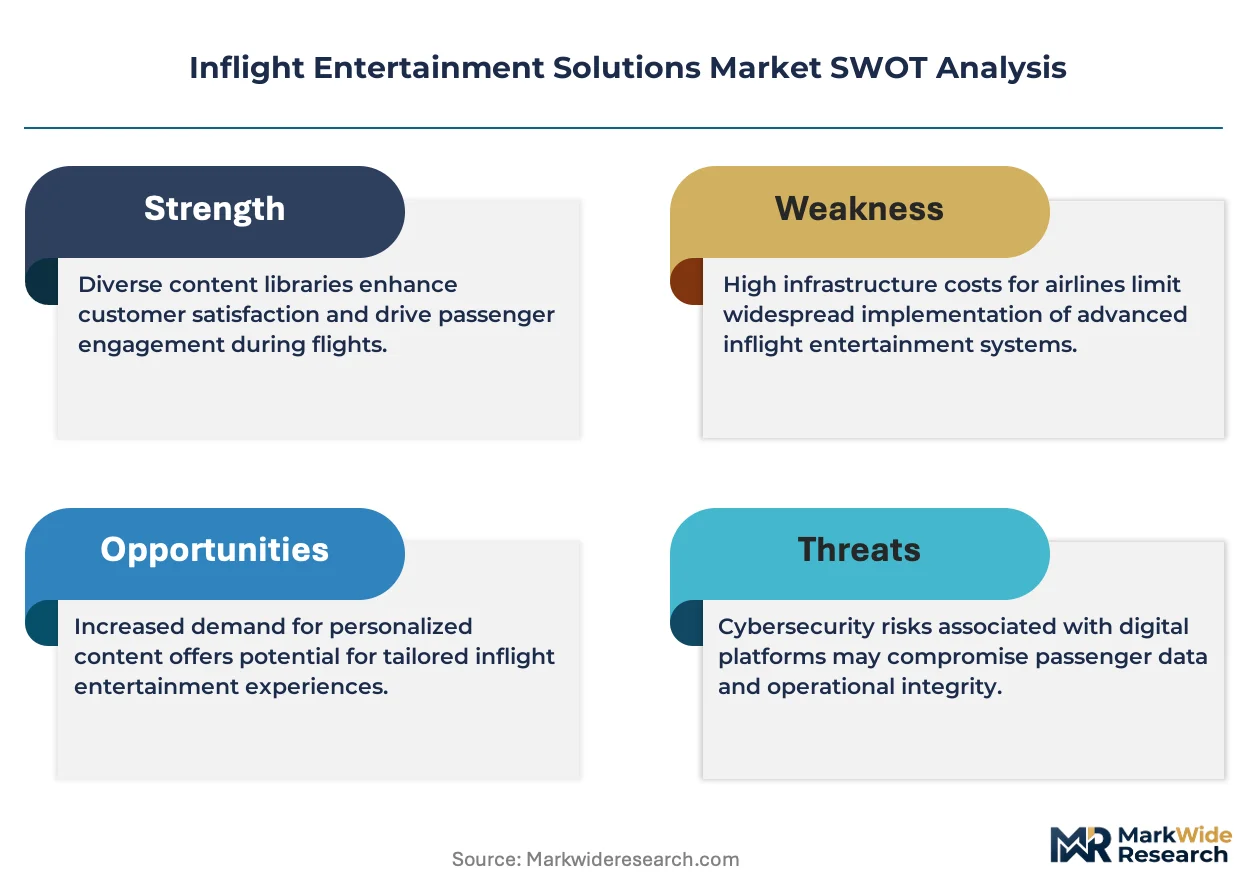
Low-cost carriers is unwinding the historical dominance of legacy full-service airlines as the primary buyer archetype for new inflight entertainment deployments. Panasonic Avionics Corporation leverages its embedded screen manufacturing scale to anchor premium wide-body contracts. Thales Group competes through vertically integrated satellite connectivity and cybersecurity-hardened avionics. Gogo LLC specializes in air-to-ground network density across North American routes.
Inflight entertainment solutions encompass the hardware, software, and connectivity infrastructure that delivers media, internet access, and interactive services to aircraft occupants at altitudes up to 40,000 feet. These systems integrate seat-back displays, wireless access points, satellite or terrestrial modems, and content management platforms to generate ancillary revenue and differentiate airline brands. Wireless video streaming and BYOD systems are capturing the fastest expansion as airlines shed seat-back screen weight and maintenance burden. Embedded systems retain the largest installed base but face margin compression from longer replacement cycles on aging wide-body fleets. Hybrid networks combining satellite and air-to-ground links are emerging as the preferred deployment architecture for transcontinental routes.
The FAA certifies all inflight connectivity hardware under Technical Standard Orders, while EASA enforces cybersecurity resilience through its EU AI Act and MDR-aligned avionics guidelines. The FCC governs spectrum allocation for Ku- and Ka-band satellite links over US airspace, directly constraining bandwidth economics for streaming-heavy architectures. Stakeholders must weigh the capital efficiency of cloud-managed content delivery against the operational control of onboard server architectures as passenger data volumes surge.
Market Dynamics
Low-cost carriers are systematically dismantling the embedded-screen hardware model through BYOD-first architectures, forcing incumbent suppliers to restructure around wireless streaming platforms and satellite connectivity rather than seat-back display manufacturing.
Growth Catalysts
- Ku- and Ka-band satellite expansion:High-throughput orbital constellations are slashing per-megabyte delivery costs for streaming-heavy deployments across transoceanic routes.
- EASA cybersecurity certification:The EU AI Act and MDR-aligned avionics guidelines are creating qualified vendor pools that airlines trust for passenger data protection at altitude.
- Low-cost carrier fleet modernization:Narrow-body operators in Southeast Asia and Latin America are retrofitting aircraft with lightweight wireless access points to capture ancillary revenue.
Market Restraints
- Satellite bandwidth cost volatility:Ku-band lease rates fluctuate with orbital slot scarcity, compressing margins on streaming-centric business models.
- Hardware supplier concentration:Three vendors control embedded screen manufacturing for wide-body retrofits, extending lead times during fleet upgrade cycles.
- FAA Technical Standard Order friction:Certification timelines for new connectivity hardware stretch 18-24 months, freezing architecture decisions until approval.
Strategic Opportunities
- India's aviation infrastructure buildout:The country's PLI scheme for electronics manufacturing is attracting system integrators to establish local MRO and content hosting capabilities.
- Hybrid air-to-ground/satellite networks:Converging terrestrial cell towers with LEO satellite links enables seamless handoffs on transcontinental US routes.
- Cloud-native content management:Edge computing architectures reduce onboard server weight while enabling real-time personalization based on passenger profiles.
Industry Challenges
- Cybersecurity engineering talent scarcity:Airlines and vendors compete for avionics software engineers capable of hardening airborne systems against intrusion.
- Legacy embedded system integration:Retrofitting 15-year-old wide-body IFE architectures with wireless streaming requires custom middleware development.
- Multi-jurisdiction certification complexity:Simultaneous FAA, EASA, and CAAC approvals for new hardware extend time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflight Entertainment Solutions Market |
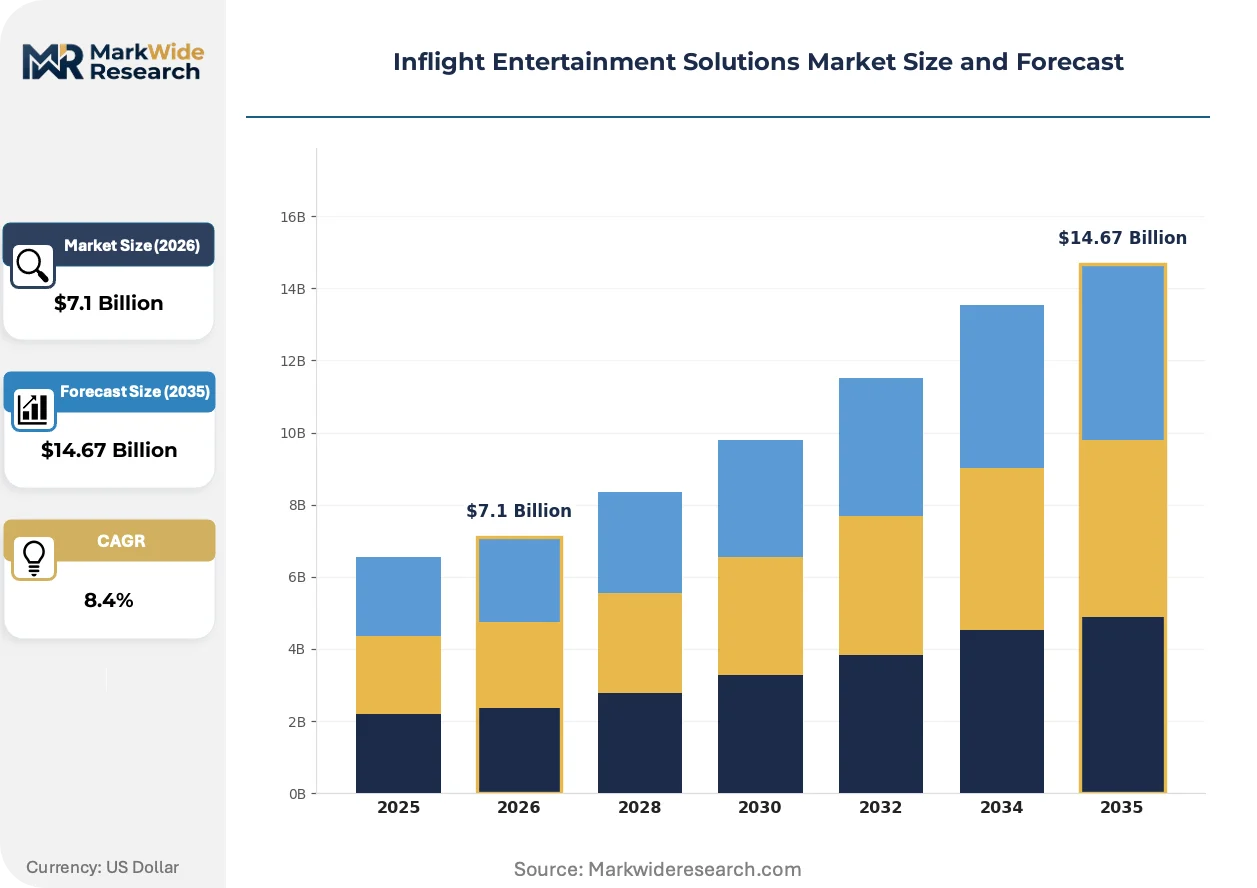
| Market Size in 2026 | $7.1 Billion |
| Market Size in 2035 | $14.67 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Wireless Video Streaming, Embedded Systems, BYOD Systems, Live TV, Audio Playback, Interactive Screens Deployment Mode: Satellite-Based, Air-to-Ground, Hybrid Networks, Onboard Servers, Cloud-Managed, Edge Computing Application: Passenger Entertainment, Crew Communication, Flight Data Management, Advertising, Real-Time News, Gaming Customer Type: Legacy Airlines, Low-Cost Carriers, Business Aviation, Charter Operators, Cargo Fleets |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Collins Aerospace, Gogo LLC, Anuvu Operations LLC, Viasat Inc., Astronics Corporation, Global Eagle Entertainment Inc., Lufthansa Systems GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflight Entertainment Solutions Market Trends and Innovations
Wireless streaming architectures are fragmenting the historical hardware-centric supply chain, while regulatory pressure on data security and passenger connectivity rights is reshaping vendor qualification criteria across all buyer segments.
LEO satellite constellations are fragmenting the traditional geostationary satellite connectivity model for inflight entertainment. Starlink and OneWeb terminals deliver sub-100ms latency that enables real-time gaming and video conferencing on narrow-body aircraft. Low-cost carriers in the United States and Brazil are adopting these terminals faster than legacy full-service airlines, compressing the addressable market for traditional Ku-band providers.
EU AI Act and MDR-aligned cybersecurity mandates from EASA are forcing avionics suppliers to reengineer software architectures for airborne systems. These frameworks require continuous vulnerability monitoring and incident reporting that legacy codebases cannot satisfy. Wide-body operators serving European routes face the steepest compliance costs, driving consolidation among vendors with pre-certified security stacks.
Airline procurement teams are unbundling hardware acquisition from content licensing and connectivity service contracts. Low-cost carriers now source wireless access points from specialist vendors while negotiating streaming rights directly with studios, bypassing traditional integrated system providers. This pattern is most pronounced in the United States, where Delta and United have established in-house content acquisition functions.
Inflight Entertainment Solutions Market Segmentation
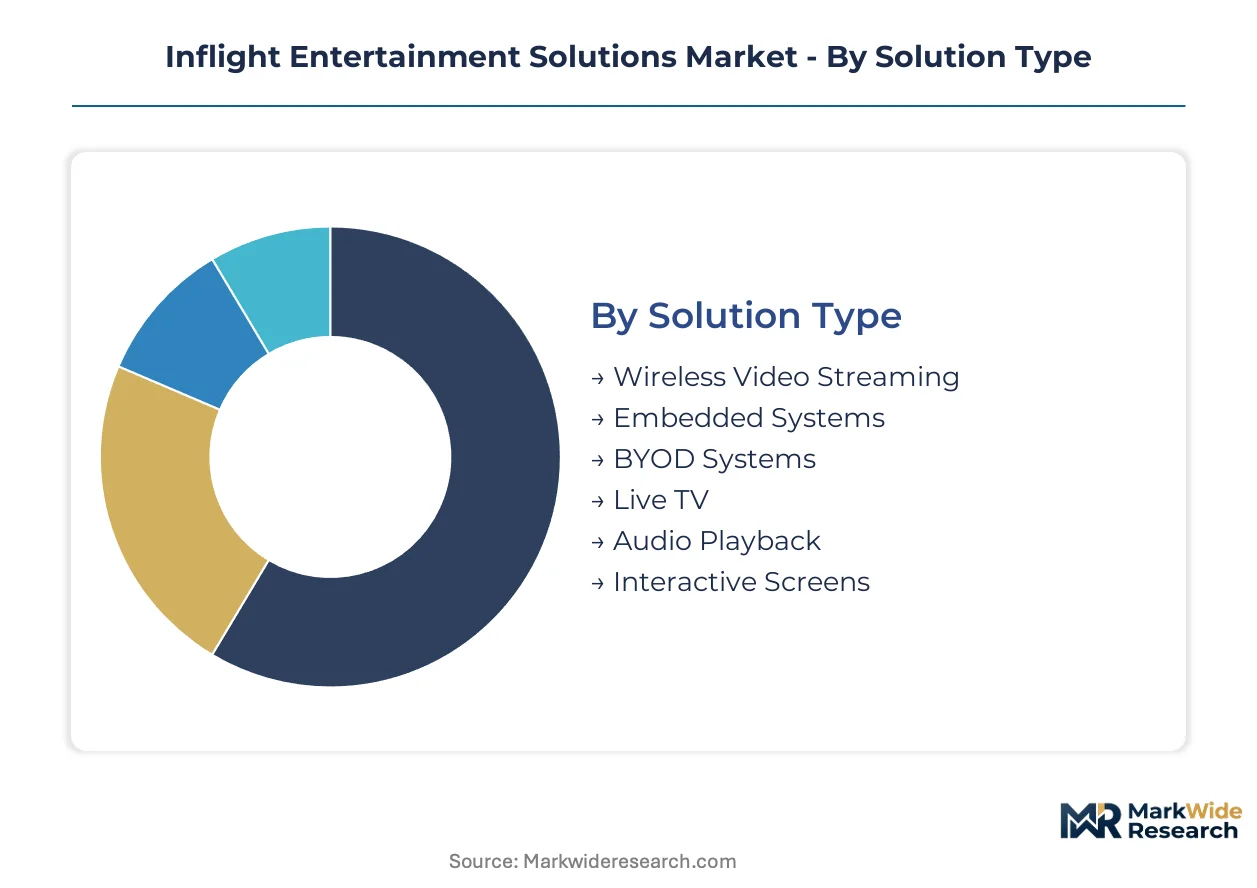
Inflight entertainment architectures fragment across hardware intensity, connectivity topology, and buyer procurement models. Segment boundaries blur as airlines unbundle integrated systems and vendors reposition around specialized layers.
Solution Type:
Margin pools concentrate in wireless streaming platforms where hardware-light deployments reduce certification friction and accelerate fleet retrofit cycles.
- Wireless Video Streaming:Content delivery via aircraft-installed wireless access points to passenger-owned devices. Low-cost carriers in the United States and Brazil are retrofitting narrow-body fleets with these architectures to shed seat-back screen weight and capture ancillary revenue from premium streaming tiers.
- Embedded Systems:Seat-back displays with integrated processors, storage, and content servers built into aircraft seats. Legacy full-service airlines serving transoceanic routes retain these for premium cabin differentiation, though replacement cycles extend as wide-body fleets age and capital allocation shifts to connectivity infrastructure.
- BYOD Systems:Passenger device-centric platforms with minimal onboard hardware beyond wireless access points and content gateways.
- Live TV:Real-time broadcast television feeds delivered via satellite or terrestrial links to seat-back or personal screens.
- Audio Playback:Music and podcast streaming through dedicated channels or on-demand libraries.
- Interactive Screens:Touch-enabled displays supporting passenger-initiated services including meal ordering, duty-free shopping, and destination information.
Embedded Systems holds installed capacity. Wireless Video Streaming is rotating up the share rankings.
Deployment Mode:
Connectivity economics vary sharply with orbital architecture and spectrum licensing, concentrating margin in hybrid configurations that optimize handoff performance across route profiles.
- Satellite-Based:Ku-band and Ka-band links to geostationary or LEO constellations for oceanic and remote airspace coverage. Southeast Asian carriers expanding into secondary cities are adopting LEO terminals from Starlink and OneWeb to bypass terrestrial infrastructure gaps and enable real-time gaming and video conferencing.
- Air-to-Ground:Cellular tower networks communicating with aircraft-mounted transceivers over continental landmasses. North American operators leverage dense terrestrial infrastructure for cost-efficient streaming on domestic routes, with Gogo LLC maintaining network density advantages across the United States.
- Hybrid Networks:Converged satellite and air-to-ground links with intelligent traffic routing.
- Onboard Servers:Local content storage and processing hardware installed within aircraft avionics bays.
- Cloud-Managed:Centralized content delivery platforms with edge caching and real-time personalization engines.
- Edge Computing:Distributed processing nodes reducing latency for interactive applications and data-intensive services.
Onboard Servers retains legacy fleet penetration. Hybrid Networks is climbing the fastest as procurement teams prioritize seamless connectivity handoffs.
Application:
Revenue per passenger diverges widely across use cases, with advertising and gaming commanding premium pricing against commoditized baseline entertainment.
- Passenger Entertainment:Core media consumption including movies, television, and music delivered to seat-back or personal devices. Full-service airlines in Europe are retrofitting wide-body cabins with streaming-centric architectures as EASA cybersecurity mandates reshape vendor qualification timelines and content licensing negotiations.
- Crew Communication:Internal messaging, operational alerts, and passenger service coordination tools for flight attendants.
- Flight Data Management:Real-time aircraft performance monitoring and predictive maintenance data transmission.
- Advertising:Targeted brand placements and sponsored content integrated into entertainment interfaces.
- Real-Time News:Live information feeds including financial data, sports scores, and breaking headlines.
- Gaming:Interactive single-player and multiplayer experiences enabled by low-latency connectivity.
Passenger Entertainment dominates current deployment value. Advertising is expanding most quickly as airlines build in-house sales functions and unbundle content from hardware procurement.
Customer Type:
Procurement sophistication and capital availability separate buyer tiers, with low-cost carriers driving standardization and legacy operators preserving customization.
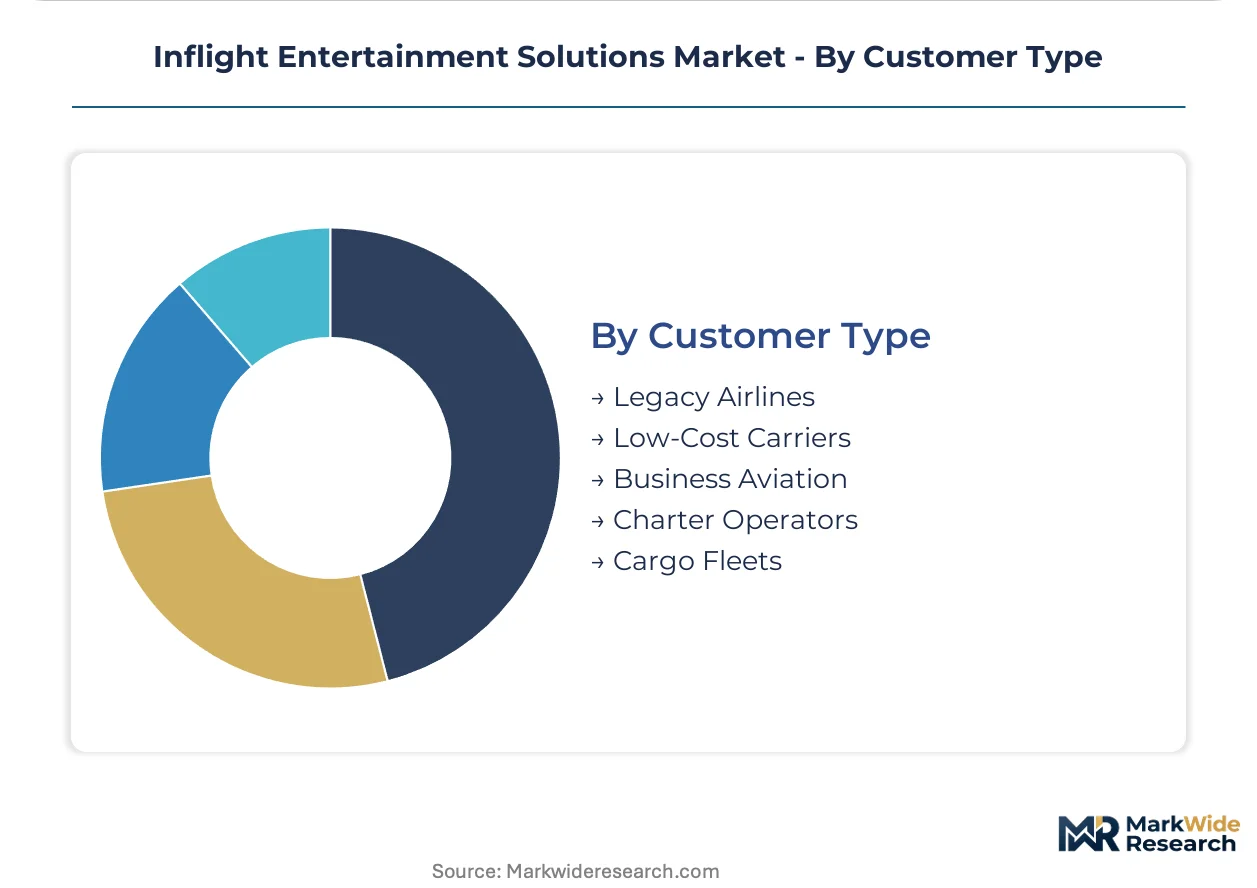
- Legacy Airlines:Full-service network carriers operating mixed fleets across hub-and-spoke systems. United States majors including Delta and United are establishing direct studio relationships and in-house content acquisition functions, bypassing traditional integrated system providers to reduce per-passenger licensing costs.
- Low-Cost Carriers:Point-to-point operators with standardized narrow-body fleets and unbundled service pricing. Southeast Asian and Latin American operators are accelerating BYOD-first adoption to minimize hardware weight, reduce fuel burn, and compress maintenance burden across high-utilization aircraft.
- Business Aviation:Private and corporate aircraft operators with customized cabin configurations.
- Charter Operators:Ad-hoc flight providers serving tour groups, sports teams, and event-specific demand.
- Cargo Fleets:Dedicated freighter operators with minimal passenger-facing requirements but crew welfare and operational data needs.
Legacy Airlines retains contract value concentration. Low-Cost Carriers is gaining share fastest as fleet expansion in emerging markets outstributes mature network growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Legacy airlines in the United States dominate procurement contract value, while low-cost carriers across Southeast Asia and Latin America accelerate fleet retrofit cycles with BYOD-first architectures.
United States
Delta and United have established in-house content acquisition functions, bypassing traditional integrated system providers to reduce per-passenger licensing costs. The FAA certifies all inflight connectivity hardware under Technical Standard Orders, stretching certification timelines to 18-24 months. Dallas-Fort Worth and Seattle-Tacoma anchor major airline operational hubs where fleet upgrade decisions concentrate.
Germany
Lufthansa Systems exemplifies European procurement sophistication, with full-service carriers prioritizing cybersecurity-hardened avionics for transoceanic routes. EASA enforces cybersecurity resilience through EU AI Act and MDR-aligned guidelines, reshaping vendor qualification timelines. Hamburg and Munich host concentrated aviation engineering clusters where system integration expertise pools.
India
Low-cost carriers including IndiGo and SpiceJet are retrofitting narrow-body fleets with lightweight wireless access points to capture ancillary revenue from price-sensitive travelers. The country's PLI scheme for electronics manufacturing attracts system integrators to establish local MRO and content hosting capabilities. Bangalore and Hyderabad concentrate software development talent for aviation cybersecurity applications.
Brazil
GOL and Azul accelerate BYOD-first adoption faster than legacy full-service airlines, compressing the addressable market for traditional Ku-band providers. ANVISA alignment with international avionics standards streamlines certification for imported connectivity hardware. São Paulo anchors Latin America's largest aviation MRO cluster where fleet modernization decisions concentrate.
United Kingdom
British Airways and Virgin Atlantic retrofit wide-body cabins with streaming-centric architectures as EASA cybersecurity mandates reshape content licensing negotiations. The CAA coordinates with EASA on dual certification pathways for satellite connectivity terminals. London Heathrow and Gatwick concentrate procurement decision-making for transatlantic fleet deployments.
Inflight Entertainment Solutions Market Competitive Landscape
Player mix skews toward integrated system providers with captive satellite connectivity assets and specialist wireless platform vendors. The vendor base separates into three strategic archetypes: full-stack avionics conglomerates with embedded screen manufacturing, connectivity-focused network operators, and modular hardware specialists. Competitive intensity centers on M&A activity to secure orbital spectrum rights and strategic partnerships between airlines and LEO constellation operators.
Among the integrated-system tier, Panasonic Avionics Corporation and Thales Group exemplify full-stack positioning through vertically integrated satellite connectivity and avionics manufacturing. Gogo LLC occupies a specialist position focused on air-to-ground network density. These three anchors represent distinct competitive vectors: hardware scale, security certification depth, and terrestrial infrastructure density respectively.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Collins Aerospace |
| Gogo LLC |
| Anuvu Operations LLC |
| Viasat Inc. |
| Astronics Corporation |
| Global Eagle Entertainment Inc. |
| Lufthansa Systems GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Manufacturing scale in embedded screen production anchors price floors across hardware tiers, concentrating supply leverage among three dominant vendors while compressing margins for mid-tier connectivity specialists competing on satellite bandwidth contracts.
Pricing Analysis
Cost-plus contracts with Ku-band lease rate indexation dominate connectivity service agreements, tying margins to orbital slot scarcity rather than fixed pricing. Three-tier pricing structure across premium, standard, and economy levels separates cybersecurity-certified avionics from uncertified alternatives, with EASA compliance commanding substantial premiums. Pricing pressure stems from LEO constellation entrants slashing latency benchmarks and forcing legacy geostationary providers into defensive repricing. Low-cost carriers exhibit highest price sensitivity, squeezing hardware procurement through BYOD-first mandates, while legacy full-service airlines absorb premium tiers for wide-body differentiation.
Supply Chain Analysis
Just-in-time inventory strategies prevail for wireless access point components, though strategic stockpiling of satellite modems buffers against FAA certification timeline volatility. Manufacturing concentrates in the United States, Germany, and China, with final assembly gravitating toward Dallas-Fort Worth and Hamburg aviation clusters. Supply chains draw from specialized semiconductor foundries for airborne-rated processors, LEO terminal manufacturers for next-generation antennas, and cloud infrastructure providers for edge computing nodes. Single-source vulnerability concentrates in embedded display panel supply, where three vendors control wide-body retrofit capacity. Distribution runs through airline procurement consortiums and direct OEM relationships with fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inflight entertainment solutions sit in early-cycle expansion as LEO satellite constellations unlock real-time interactive applications previously impossible under geostationary latency constraints, accelerating replacement demand across narrow-body fleets.
For Market Incumbents: Consolidate satellite spectrum holdings through exclusive orbital partnerships before LEO terminal commoditization erodes bandwidth pricing power. Lock in cybersecurity certification depth under EASA frameworks to create switching costs against modular competitors. Acquire specialist wireless access point vendors to defend against airline unbundling trends that bypass integrated system providers. For New Entrants and Emerging Players: EASA cybersecurity fast-track programs offer the most penetrable regulatory pathway for software-native vendors lacking avionics heritage. Target Southeast Asian low-cost carriers retrofitting narrow-body fleets with lightweight BYOD architectures, where incumbent relationships remain unsettled. Lead with cloud-native content management platforms that reduce onboard server weight and accelerate fleet retrofit cycles compared to legacy embedded systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among connectivity service providers with long-term airline contracts indexed to passenger volume rather than hardware shipment cycles. Five-to-ten-year viability favors vendors with captive LEO satellite partnerships and pre-certified security stacks under EU AI Act mandates. Watch LEO constellation coverage expansion across transoceanic routes as the inflection signal for traditional Ku-band provider displacement.| Strategic Initiative | Industry Significance |
|---|---|
| LEO Satellite Partnership | Starlink and OneWeb alliances enable sub-100ms latency for real-time gaming and video conferencing applications. |
| Cybersecurity Certification Investment | EASA EU AI Act compliance creates qualified vendor pools that airlines trust for passenger data protection. |
| Cloud-Native Content Platform Development | Edge computing architectures reduce onboard server weight while enabling real-time personalization based on passenger profiles. |
| BYOD-First Hardware Unbundling | Wireless access point specialization bypasses traditional integrated system providers and captures ancillary revenue streams. |
| Hybrid Network Architecture Deployment | Converged satellite and air-to-ground links optimize handoff performance across transcontinental US route profiles. |
Research Methodology
Initial hypotheses were tested against primary input from airline procurement executives, avionics engineering directors, satellite connectivity specialists, and fleet modernization program managers, and refined through secondary validation against FAA Technical Standard Order filings, EASA certification databases, SEC 10-K disclosures from listed connectivity providers, and airline fleet upgrade announcements. Bottom-up triangulation across installed base estimates and top-down reconciliation against ancillary revenue disclosures anchored market sizing.
Variance decomposition across the projection horizon isolates satellite bandwidth cost trajectories, regulatory certification timeline shifts, and fleet retrofit cycle acceleration as primary uncertainty sources. Segmentation modeling spans solution type, deployment mode, application use case, and customer procurement archetype. CAGRs derive from logistic penetration curves fitted to historical adoption patterns in comparable aviation technology transitions, with inputs including LEO constellation deployment schedules and narrow-body order backlogs at major OEMs.
Decision-makers should treat outputs as directional under assumptions of sustained FAA-EASA regulatory harmonization and LEO constellation service launch timelines; material deviation would warrant model refresh. Revision becomes warranted when LEO satellite coverage gaps persist beyond projected fill dates or cybersecurity certification backlogs extend vendor qualification timelines beyond fleet retrofit windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Virtual Keyboard Market
Others
GCC Shisha Tobacco Market
Others
North America Astrology Market
Others
Europe Polycarbonate Sheets Market
Others
Crystal Growth Equipment Market
Others
Europe Air Separation Unit Market
Others
Europe Smart Homes Market
Others
Fresh Durian Market
Others
Security Bottles Market
Others
Bicycle Panniers Market
Others
AI in Precision Medicine Market
Others
Video-As-A-Service (Vaas) Market
Others
Cloud DVR Market
Others
Storm Surge Barriers Market
Others
China Online Gambling Market
Others
Halogen Free Flame Retardant Bopet Films Market