
 Global Injectable Nanomedicine Market | 2026-2036
Global Injectable Nanomedicine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Injectable Nanomedicine Market Intelligence
Modular formulation kits that pair nanoparticle carriers with interchangeable active pharmaceutical ingredients are broadening procurement options for hospital pharmacies. Pfizer Inc. leverages its manufacturing scale to supply lipid nanoparticle platforms across multiple therapeutic areas. Hoffmann-La Roche Ltd. anchors its position through deep specialization in oncology-targeted nanocarriers. Amgen Inc. competes by extending its biologic expertise into polymer-based injectable formulations.
Injectable nanomedicine comprises therapeutically active agents encapsulated within or conjugated to nanoscale carriers, typically ranging from 1 to 100 nanometers in diameter, engineered for intravenous, subcutaneous, or intramuscular administration to achieve targeted biodistribution, controlled release, or enhanced solubility of poorly water-soluble compounds. Liposomes dominate current revenue pools due to established manufacturing infrastructure and broad regulatory familiarity, while metallic nanoparticles represent the fastest-expanding category driven by diagnostic-therapeutic combination applications. Among therapy areas, oncology commands the largest share of clinical trials and commercial revenue, though immunology applications are gaining momentum as mRNA vaccine platforms validate nanoparticle delivery mechanisms.
The FDA's Center for Drug Evaluation and Research maintains specialized review pathways for nanotechnology-based products, while the EMA's Committee for Medicinal Products for Human Use applies emerging guidance on nanomaterial characterization that influences European market access requirements. Japan's PMDA has streamlined its consultation framework for nanomedicine developers, reducing pre-submission timelines for novel carrier systems. Stakeholders must monitor evolving bioequivalence standards for generic nanomedicines, as regulatory divergence between major agencies will determine which manufacturing investments yield multi-territory approval.
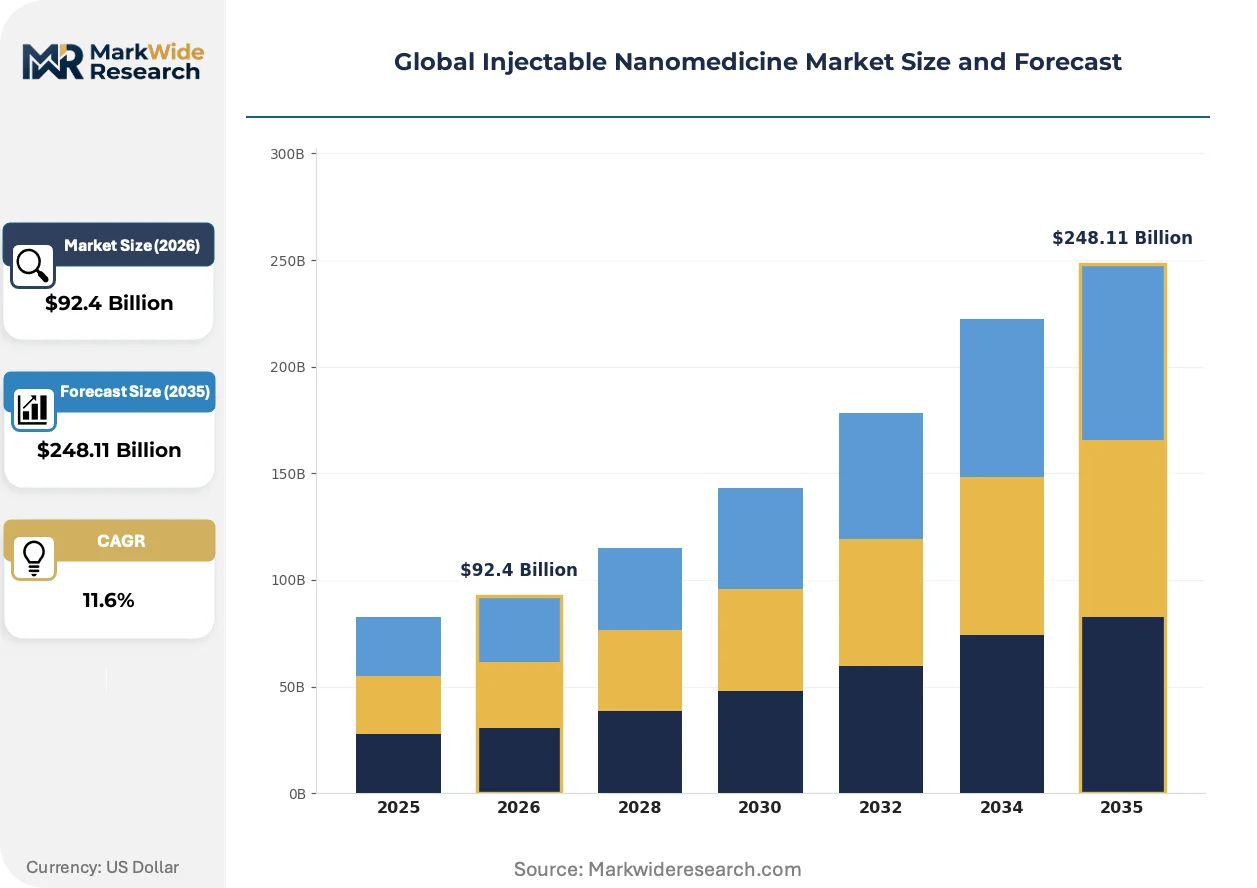
Market Dynamics
FDA accelerated approval pathways for nanotherapeutics are compressing development timelines while simultaneously intensifying competition among formulation platforms as multiple carriers chase identical oncology indications.
Growth Catalysts
- mRNA Platform Validation:COVID-19 vaccine success with lipid nanoparticle delivery has de-risked nucleic acid nanomedicine for infectious disease and oncology applications.
- Japan PMDA Streamlined Consultation:Reduced pre-submission timelines for novel carrier systems attract developers seeking faster Asian market entry alongside US and EU approvals.
- Academic Medical Center Expansion:Oncology departments at major US teaching hospitals are broadening liposomal chemotherapy protocols into earlier treatment lines and combination regimens.
Market Restraints
- High-Purity Lipid Supply Concentration:Ionizable cationic lipids essential for mRNA delivery depend on a limited supplier base concentrated in Germany and Switzerland.
- Complex Bioequivalence Standards:EMA emerging guidance on nanomaterial characterization creates regulatory friction for generic nanomedicine developers seeking European market access.
- Manufacturing Scale-Up Barriers:Microfluidic production methods for uniform particle size distribution require capital-intensive cleanroom infrastructure that constrains batch volumes.
Strategic Opportunities
- Immunology Application White Space:Autoimmune disease indications represent underpenetrated territory as mRNA vaccine platforms validate nanoparticle mechanisms beyond oncology.
- Metallic Nanoparticle Convergence:Diagnostic-therapeutic combinations combining imaging agents with drug delivery create new revenue pools in precision medicine workflows.
- Modular Formulation Kits:Hospital pharmacies seek interchangeable active pharmaceutical ingredients paired with standardized nanoparticle carriers to simplify procurement and inventory management.
Industry Challenges
- Analytical Methodology Gaps:Characterization of complex nanostructures including surface charge heterogeneity and drug loading uniformity lacks standardized protocols accepted across FDA, EMA, and PMDA.
- Specialized Talent Scarcity:Formulation scientists combining polymer chemistry, pharmacokinetics, and regulatory science command premium compensation that strains mid-cap development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Injectable Nanomedicine Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $248.11 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liposomes, Polymer Nanoparticles, Metallic Nanoparticles, Dendrimers, Carbon Nanotubes Therapy Area: Oncology, Neurology, Cardiovascular, Infectious Diseases, Immunology End User: Research Laboratories, Biopharmaceutical Companies, Contract Manufacturing Organizations, Specialized Clinics Delivery Technology: Targeted Drug Delivery, Controlled Release Systems, Passive Targeting, Active Targeting, Stimuli-Responsive Systems |
| Companies Covered | Merck & Co. Inc., Pfizer Inc., Amgen Inc., Pacira Pharmaceuticals Inc., Lupin, Janssen Biotech Inc., Johnson & Johnson Services Inc., Hoffmann-La Roche Ltd., Teva Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Injectable Nanomedicine Market Strategic Shifts & Innovations
Active pharmaceutical ingredient solubility challenges are driving carrier innovation while regulatory convergence pressures force simultaneous multi-agency compliance strategies.
Polymer-based injectable nanocarriers are absorbing development investment from conventional liposomal approaches as Amgen and specialized biotech firms extend biologic expertise into synthetic delivery systems. Academic research centers in Germany and Japan are adopting these platforms for protein and peptide stabilization. The shift is absorbing capital previously allocated to incremental liposome improvements, redirecting talent toward controlled-release polymer architectures.
REACH nanomaterial registration requirements in Europe are forcing characterization investments that exceed prior small-molecule standards. EMA Committee for Medicinal Products for Human Use guidance on physiochemical properties now demands extensive stability data. Oncology-focused developers are responding by front-loading analytical development to secure centralized EU approval alongside US FDA submissions.
Hospital pharmacy procurement of modular nanomedicine kits is consolidating supplier relationships around platforms supporting multiple active ingredients. Academic medical centers in the United States and Germany favor carriers with established reimbursement codes over novel systems requiring health technology assessment. This preference rotation favors incumbents with regulatory precedent over disruptive entrants.
Global Injectable Nanomedicine Market Segmentation
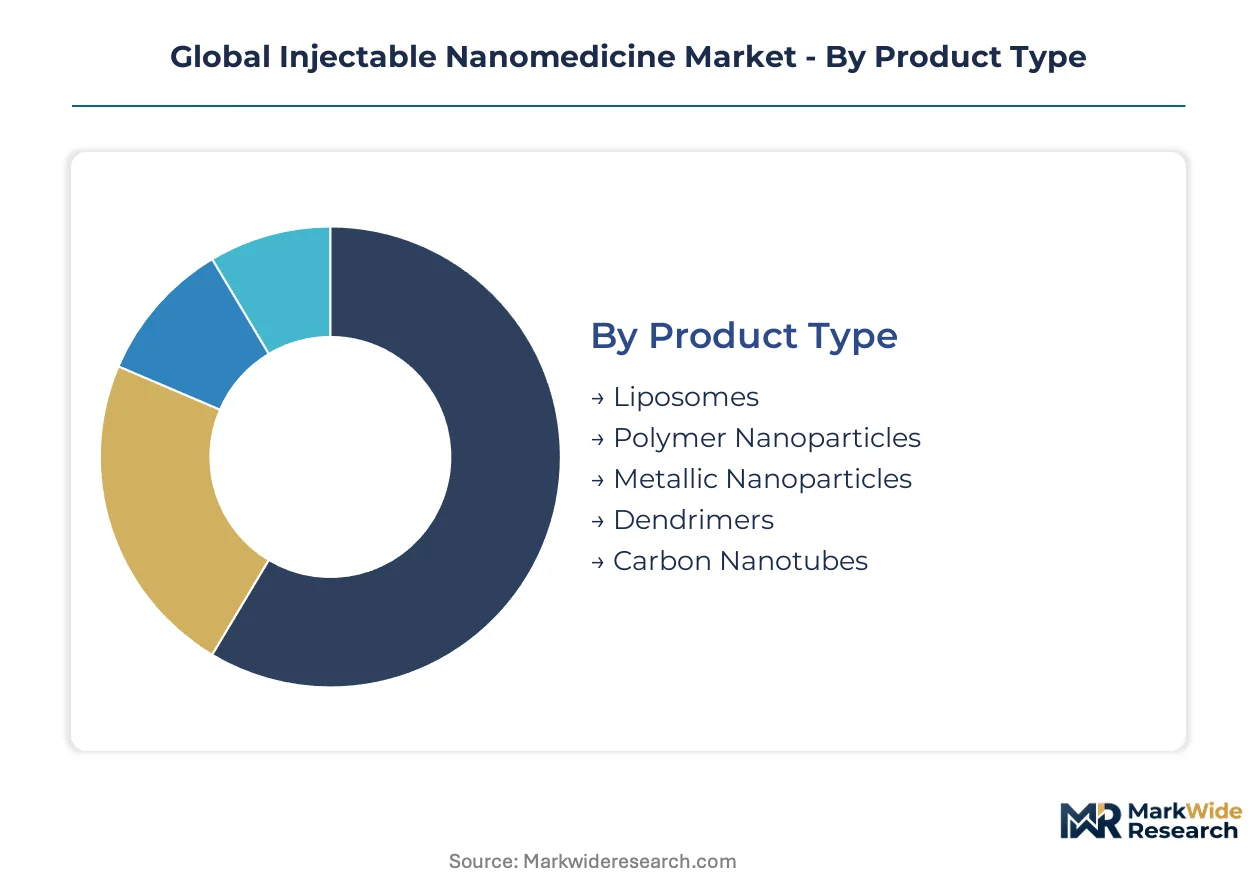
Injectable nanomedicine procurement varies sharply across carrier chemistry, therapeutic application, and manufacturing maturity. Buyers prioritize regulatory precedent for near-term adoption while positioning for next-generation platform flexibility.
Product Type:
Hospital pharmacy formularies weight manufacturing reliability and bioequivalence documentation above novel performance claims.
- Liposomes:Phospholipid bilayer vesicles encapsulating hydrophilic cores and hydrophobic membranes dominate commercial revenue due to established FDA approval pathways and scalable production infrastructure. Academic medical centers in the United States and Germany concentrate procurement here, constrained by limited ionizable cationic lipid suppliers in Central Europe.
- Metallic Nanoparticles:Gold and iron oxide cores functionalized with targeting ligands enable simultaneous diagnostic imaging and therapeutic delivery. Precision medicine workflows at Japanese university hospitals absorb volume fastest, though analytical methodology gaps across FDA, EMA, and PMDA delay multi-territory launches.
- Polymer Nanoparticles:Synthetic biodegradable matrices including PLGA and PEG-PLA extend protein half-life for biologic drugs.
- Dendrimers:Highly branched synthetic macromolecules with defined molecular weights enable precise drug loading ratios.
- Carbon Nanotubes:Cylindrical carbon allotropes with exceptional surface area for hydrophobic compound solubilization.
Volume sits with liposomes; growth tilts toward metallic nanoparticles.
Therapy Area:
Reimbursement code density determines hospital adoption velocity more than clinical efficacy differentiation.
- Oncology:Liposomal doxorubicin and paclitaxel formulations command the largest share of commercial revenue and active clinical trials. United States teaching hospitals are expanding protocols into earlier treatment lines, though EMA nanomaterial characterization guidance creates friction for European market access.
- Immunology:mRNA vaccine platform validation with lipid nanoparticle carriers is redirecting development investment from oncology toward autoimmune disease applications. German and Japanese academic centers are piloting tolerogenic nanoparticle protocols for rheumatoid arthritis, attracted by streamlined PMDA consultation timelines.
- Neurology:Blood-brain barrier penetration challenges limit current commercial penetration despite high unmet need.
- Cardiovascular:Statin and anticoagulant nanocarrier formulations target improved bioavailability profiles.
- Infectious Diseases:Nucleic acid vaccines and antimicrobial peptide delivery absorb post-COVID platform investment.
Revenue concentrates in oncology; pipeline velocity favors immunology.
End User:
Capital intensity and regulatory capability stratify the buyer base into platform-scale manufacturers versus specialized service providers.
- Biopharmaceutical Companies:Integrated developers including Pfizer and Hoffmann-La Roche leverage captive manufacturing scale across multiple therapeutic areas. Internal lipid nanoparticle platforms reduce dependency on contract suppliers, though high-purity ionizable cationic lipid concentration in Germany and Switzerland creates supply vulnerability.
- Contract Manufacturing Organizations:CDMOs with microfluidic production capabilities capture outsourced formulation demand from mid-cap biotech firms lacking cleanroom infrastructure. Japanese and German CMOs benefit from PMDA and EMA regulatory precedents that accelerate client market access.
- Research Laboratories:Academic institutions drive early-stage carrier innovation with limited commercial procurement volume.
- Specialized Clinics:Outpatient infusion centers administer approved liposomal chemotherapy with established reimbursement pathways.
Procurement scale sits with biopharmaceutical companies; service outsourcing tilts toward contract manufacturing organizations.
Delivery Technology:
Intellectual property estate breadth and manufacturing reproducibility determine platform selection more than theoretical targeting efficiency.
- Targeted Drug Delivery:Ligand-functionalized carriers achieving cell-specific uptake through receptor binding dominate development investment. Oncology applications at United States academic medical centers drive clinical validation, though surface charge heterogeneity analytical gaps complicate regulatory submissions.
- Controlled Release Systems:Polymer-based depot formulations extending therapeutic exposure over weeks to months gain traction in immunology. Amgen's biologic expertise extension into synthetic polymers exemplifies this shift, with German research centers adopting platforms for protein stabilization.
- Passive Targeting:Enhanced permeability and retention effect exploitation in tumor vasculature underpins established liposome efficacy.
- Active Targeting:Antibody and peptide-directed carrier localization remains preclinical for most indications.
- Stimuli-Responsive Systems:pH, temperature, or enzyme-triggered drug release mechanisms are advancing through academic partnerships.
Clinical deployment sits with targeted drug delivery; pipeline expansion tilts toward controlled release systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts' Life Sciences Tax Incentive Program and North Carolina's Biotechnology Center grants have concentrated injectable nanomedicine manufacturing investment along the US East Coast. Germany's High-Tech Gründerfonds and Japan's PMDA consultation streamlining attract parallel development clusters. These fiscal architectures determine where lipid nanoparticle production scales fastest.
United States
Academic medical centers in Boston and Durham are expanding liposomal chemotherapy protocols into earlier treatment lines. The FDA's accelerated approval pathways for nanotherapeutics compress development timelines for developers seeking oncology indications. The Research Triangle Park in North Carolina hosts contract manufacturing organizations scaling microfluidic production for uniform particle size distribution.
Germany
High-purity ionizable cationic lipid suppliers concentrate in Frankfurt and Basel-adjacent territories, creating supply vulnerability for mRNA platform developers. EMA nanomaterial characterization guidance demands extensive stability data that exceeds prior small-molecule standards. The Rhine-Main biotech corridor anchors lipid nanoparticle platform manufacturing for European market access.
Japan
PMDA's streamlined consultation framework reduces pre-submission timelines for novel carrier systems, attracting developers seeking faster Asian market entry. Tokyo and Osaka university hospitals pilot tolerogenic nanoparticle protocols for rheumatoid arthritis applications. The Kanto region absorbs metallic nanoparticle volume fastest for diagnostic-therapeutic combination workflows.
Switzerland
Swissmedic maintains specialized review pathways that align with EMA standards while offering faster procedural timelines for nanotechnology-based products. Basel and Zurich host formulation scientists commanding premium compensation for polymer chemistry and pharmacokinetics expertise. The country's central European position enables multi-territory supply coordination for German and French developers.
India
CDSCO's evolving bioequivalence standards for generic nanomedicines create regulatory friction that delays market access for domestic developers. Mumbai and Hyderabad concentrate contract research organizations supporting polymer-based injectable formulation development. The country's pharmaceutical manufacturing base is repositioning toward complex generic nanocarriers requiring advanced analytical capabilities.
Global Injectable Nanomedicine Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across formulation platform development, creating a tiered competitive structure. Large-cap pharmaceutical companies leverage captive manufacturing scale across multiple therapeutic areas, while mid-cap biotech firms depend on contract manufacturing organizations for microfluidic production capabilities. Three strategic archetypes dominate: integrated platform developers with internal lipid nanoparticle capabilities, specialized oncology nanocarrier companies, and polymer-based formulation extenders from biologic expertise. Competitive moves concentrate on strategic partnerships for high-purity lipid supply security and technology licensing for metallic nanoparticle diagnostic-therapeutic convergence.
Among US-based integrated developers, Pfizer Inc. and Amgen Inc. occupy positions at opposite ends of the carrier chemistry spectrum, with the former representing lipid nanoparticle platform scale and the latter exemplifying polymer-based biologic extension. Hoffmann-La Roche Ltd. anchors the European specialized oncology tier through deep concentration in targeted nanocarrier development. These three entities collectively represent the competitive tension between diversified manufacturing scale and focused therapeutic specialization that defines procurement dynamics for hospital pharmacy formularies.
| Leading Market Players |
|---|
| Merck & Co. Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Pacira Pharmaceuticals Inc. |
| Lupin |
| Janssen Biotech Inc. |
| Johnson & Johnson Services Inc. |
| Hoffmann-La Roche Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Others |
Cost & Logistics Intelligence
Captive lipid nanoparticle production anchors both supply security and pricing power for integrated biopharmaceutical developers, while outsourced formulation dependence exposes mid-cap firms to ionizable cationic lipid scarcity concentrated in Germany and Switzerland. This structural split between in-house platform control and contract manufacturing reliance shapes procurement negotiations across hospital pharmacy formularies.
Pricing Analysis
Short lead-time premiums for high-purity ionizable cationic lipids command substantial markups over contract-scheduled volumes, reflecting the concentrated supplier base in Central Europe. Three-tier pricing structure across GMP-certified, research-grade, and compounding-pharmacy tiers separates regulated clinical supply from preclinical development material. Pricing pressure stems from EMA nanomaterial characterization requirements that extend analytical development timelines and inflate qualification costs. Academic medical centers exhibit highest price sensitivity due to fixed reimbursement codes, while integrated developers with captive manufacturing absorb cost volatility through internal transfer pricing.
Supply Chain Analysis
FDA and EMA GMP certification gates restrict viable lipid nanoparticle manufacturing to facilities with validated microfluidic production and documented particle size distribution controls. High-purity phospholipid and ionizable cationic lipid supply concentrates in Germany, Switzerland, and the United States, with raw material sourcing drawing from specialized chemical synthesis and plant-derived extraction pathways. Single-source vulnerability in ionizable cationic lipid supply creates exposure to regional regulatory disruptions or manufacturing contamination events. Distribution runs through qualified cold-chain logistics networks serving biopharmaceutical company captive facilities and contract manufacturing organizations with established regulatory precedents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The injectable nanomedicine market operates as a vertical-integration race, with control over high-purity lipid supply and microfluidic manufacturing capacity determining competitive endurance. Players are pursuing backward integration into ionizable cationic lipid production to escape supplier concentration risk.
For Market Incumbents: Deepen captive manufacturing scale in lipid nanoparticle platforms to reduce dependency on German and Swiss ionizable cationic lipid suppliers. Secure long-term offtake agreements with academic medical centers expanding liposomal chemotherapy protocols into earlier treatment lines. Invest in polymer-based formulation capabilities to hedge against metallic nanoparticle analytical methodology gaps that delay multi-territory regulatory submissions. For New Entrants and Emerging Players: Enter via tolerogenic nanoparticle protocols for rheumatoid arthritis applications in Japan, where PMDA streamlined consultation reduces pre-submission timelines relative to FDA and EMA pathways. Target German research centers adopting polymer-based platforms for protein stabilization, leveraging the country's High-Tech Gründerfonds funding architecture. Position modular formulation kits for hospital pharmacy procurement consolidation, emphasizing interchangeable active pharmaceutical ingredients with standardized carrier systems. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated biopharmaceutical developers seeking lipid nanoparticle platform scale or specialized oncology nanocarrier expertise. Long-term viability favors entities with demonstrated regulatory precedents across FDA, EMA, and PMDA jurisdictions, insulating against evolving bioequivalence standards for generic nanomedicines. Watch for inflection signals in immunology application pipeline velocity as mRNA platform validation redirects development investment from oncology toward autoimmune disease indications.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA accelerated approval for nanotherapeutics compresses development timelines for oncology indications. |
| Manufacturing Scale-Up | Microfluidic production capabilities for uniform particle size distribution constrain batch volumes and capital deployment. |
| Backward Integration | In-house ionizable cationic lipid production reduces exposure to German and Swiss supplier concentration. |
| Licensing Agreement | Technology licensing for metallic nanoparticle diagnostic-therapeutic convergence creates new revenue pools. |
| Pipeline Diversification | Immunology applications for autoimmune disease represent underpenetrated territory beyond oncology saturation. |
Research Approach
Multi-period observation of FDA nanotechnology product approvals, EMA nanomaterial characterization guidance evolution, and PMDA consultation timeline trends anchored the trend analysis, supplemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from FDA filings, EMA Committee for Medicinal Products for Human Use guidance documents, ClinicalTrials.gov protocol registrations, and Japanese pharmaceutical reimbursement databases. Bottom-up segmentation modeling triangulated against top-down market sizing from identified biopharmaceutical company manufacturing disclosures and contract manufacturing organization capacity announcements.
Segment-weighting approaches distributed value across liposomal, metallic nanoparticle, and polymer-based carrier chemistries, with therapy area splits between oncology, immunology, neurology, cardiovascular, and infectious disease applications. End-user stratification captured biopharmaceutical company captive manufacturing, contract manufacturing organization outsourcing, research laboratory procurement, and specialized clinic administration. CAGRs were derived from trajectory fitting across the projection horizon, incorporating mRNA platform validation effects, reimbursement code density shifts, and regulatory pathway compression factors specific to nanotherapeutic development.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of EMA-FDA regulatory divergence on nanomaterial bioequivalence standards or sustained ionizable cationic lipid supply disruption. Forecasts reflect assumptions regarding PMDA consultation streamlining continuity, academic medical center protocol expansion velocity, and metallic nanoparticle analytical methodology standardization progress. A model refresh is warranted upon material change in FDA accelerated approval pathway criteria or REACH nanomaterial registration requirement enforcement intensity in Europe.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cathode Battery Material Market
Others
Gesture Recognition for Smart TV Market
Others
PC As a Service Market
Others
Green Technologies Market
Others
Smart-Connected Power Plug Socket Market
Others
South America Halal Food and Beverages Market
Others
Cloud Gaming Baas Market
Others
Air Purification Systems Market
Others
Tanned Fish Skin Leather Market
Others
Wearable Translator Market
Others
Cat Food and Snacks Market
Others
China Packaging Primers Market
Others
Education and Learning Analytics Market
Others
Asia-Pacific 3D Printing Construction Market
Others
Transportation Lighting Market
Others
Fenoxanil Market