
 North America Halal Food and Beverage Market | 2026-2036
North America Halal Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Halal Food and Beverage Market Analytics
Premium certification tiers including dual halal-organic and hand-slaughter zabiha labels is redrawing competitive boundaries across North American shelves. Saffron Road leverages its USDA Organic plus halal positioning to command shelf space in mainstream grocers. Cargill Incorporated anchors industrial-scale halal protein supply through its integrated beef and poultry processing networks. Nestlé S.A. extends its infant nutrition and confectionery portfolios with halal-compliant formulations tailored to North American Muslim households.
Halal food and beverage encompasses consumable products prepared according to Islamic dietary law, requiring permissible ingredients, ritual slaughter where applicable, and supply chain segregation from alcohol and pork derivatives; certification mandates traceability from farm to fork with documented ingredient provenance. The primary commercial purpose centers on serving faith-observant consumers while capturing adjacent health-conscious and ethical-buyer segments that associate halal with cleanliness and animal welfare standards. Meat dominates current value generation given slaughter compliance complexity and protein price premiums, while Beverages represents the fastest-expanding category as functional drinks and alcohol-free alternatives attract crossover consumers. Distribution through Supermarkets has matured into a structural margin pool as chains dedicate permanent halal sections, though Online Retail is capturing the highest growth velocity through subscription meat boxes and direct-to-consumer spice imports.
USDA slaughter inspection protocols intersect with halal certifying body standards to create a dual-compliance burden that favors processors with dedicated halal production lines. CFIA enforcement of Safe Food for Canadians Regulations shapes import pathways for BRF S.A. and other international suppliers entering Canadian retail. Stakeholders must monitor evolving state-level labeling requirements and certifier fragmentation, as inconsistent standards across Islamic authorities risk consumer confusion and retailer hesitation in shelf allocation decisions.
Market Dynamics
USDA slaughter inspection protocols intersect with halal certifying body standards to create a dual-compliance burden that favors processors with dedicated halal production lines. CFIA enforcement of Safe Food for Canadians Regulations shapes import pathways for international suppliers entering Canadian retail.
Growth Catalysts
- USDA-FSIS Slaughter Modernization:Updated inspection frameworks permit simultaneous halal-organic line certification, reducing compliance overhead for multi-label processors in the United States.
- Greater Toronto Area demand density:South Asian and Middle Eastern population clusters support dedicated halal retail corridors with sufficient volume to justify specialized distribution infrastructure.
- Cell-cultured protein maturation:Cultivated meat production eliminates ritual slaughter complexity while satisfying Islamic permissibility debates, opening new formulation pathways for beverage and ingredient suppliers.
Market Restraints
- Feed cost volatility:Corn and soybean price swings compress margins for halal poultry processors operating on fixed-price retail contracts in the United States.
- Certifier fragmentation:Inconsistent standards across Islamic authorities in Canada and the United States create consumer confusion and retailer hesitation in permanent shelf allocation decisions.
- Hand-slaughter labor scarcity:Zabiha-certified operations face constrained qualified slaughterman availability, capping throughput at dedicated facilities in Ontario and Texas.
Strategic Opportunities
- Subscription meat box channels:Direct-to-consumer halal protein delivery bypasses conventional retail slotting fees while capturing younger Muslim households in Chicago and Houston suburbs.
- CFIA import pathway optimization:Streamlined Safe Food for Canadians Regulations compliance for pre-certified international suppliers reduces time-to-shelf for Brazilian and Australian beef entrants.
- Functional beverage convergence:Alcohol-free adaptogenic and probiotic drinks align with halal compliance while attracting health-conscious crossover consumers beyond faith-observant segments.
Industry Challenges
- Blockchain traceability implementation:Farm-to-fork documentation requirements for dual halal-organic claims demand capital-intensive ERP upgrades at mid-scale processors.
- Cross-contamination protocol enforcement:Supply chain segregation from pork derivatives and alcohol requires dedicated storage, transport, and co-packing arrangements that inflate operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Halal Food and Beverage Market |
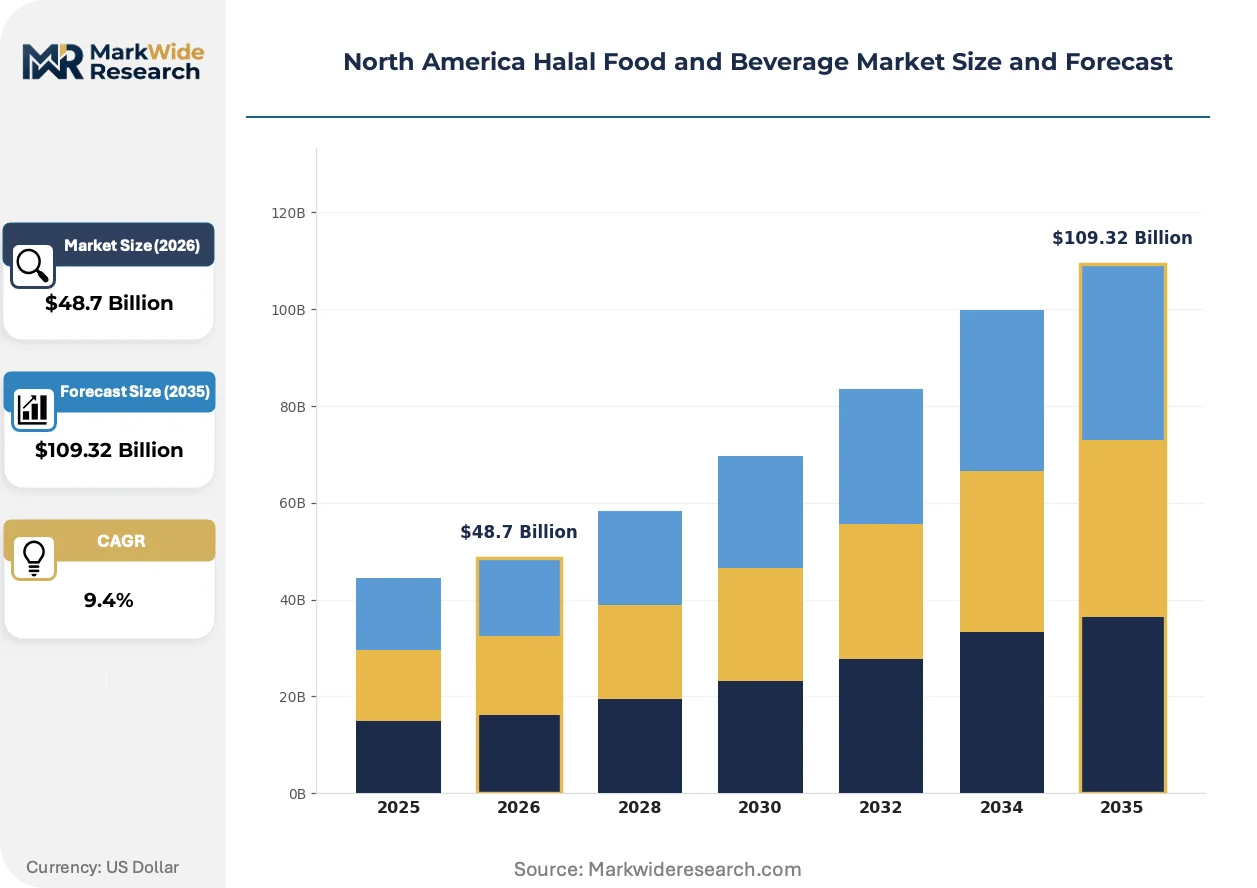
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $109.32 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Meat, Dairy, Beverages, Snacks Certification Type: Halal Certifying Bodies, Government Regulations, Employee Training, Quality Standards Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Foodservice Consumer Segment: Muslim Consumers, Health Conscious, Vegetarian Options, Non-Muslim Preferences |
| Companies Covered | JBS S.A., Saffron Road, Cargill Incorporated, BRF S.A., Midamar Corporation, Crescent Foods, Inc., Nestlé S.A., Al Islami Foods, American Foods Group, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Halal Food and Beverage Market Evolving Landscape
Blockchain-enabled supply chain verification is actively reshaping how halal integrity is demonstrated to retailers and end consumers. Three interconnected developments are compressing traditional assurance models while opening new competitive terrain.
Blockchain traceability infrastructure is decomposing paper-based halal certification into immutable, queryable transaction records. Mid-scale processors in Ontario and Texas are piloting distributed ledger systems to satisfy Costco and Walmart vendor compliance portals. This shift compresses audit cycles from quarterly site visits to real-time ingredient provenance queries, favoring suppliers with integrated ERP-to-blockchain data pipelines.
CFIA enforcement of updated Safe Food for Canadians Regulations is tightening import documentation requirements for halal-labeled products entering Canadian retail. The regulation mandates certifier accreditation alignment with federal food safety frameworks, disqualifying several overseas Islamic authorities previously accepted by provincial inspectors. Brazilian beef exporters and Malaysian ingredient suppliers are restructuring their Canadian market entry through CFIA-recognized certification bodies to maintain shelf presence.
Younger Muslim households in the United States and Canada are consolidating grocery purchasing through ethnic e-commerce platforms and subscription services rather than conventional supermarket halal sections. Platforms like WeHalal and specialized butcher-box subscriptions capture protein and spice purchases previously fragmented across independent retailers. This channel shift concentrates demand data with digital-native intermediaries, compressing traditional distributor margins and forcing legacy wholesalers to develop direct fulfillment capabilities or accept disintermediation.
North America Halal Food and Beverage Market Segmentation
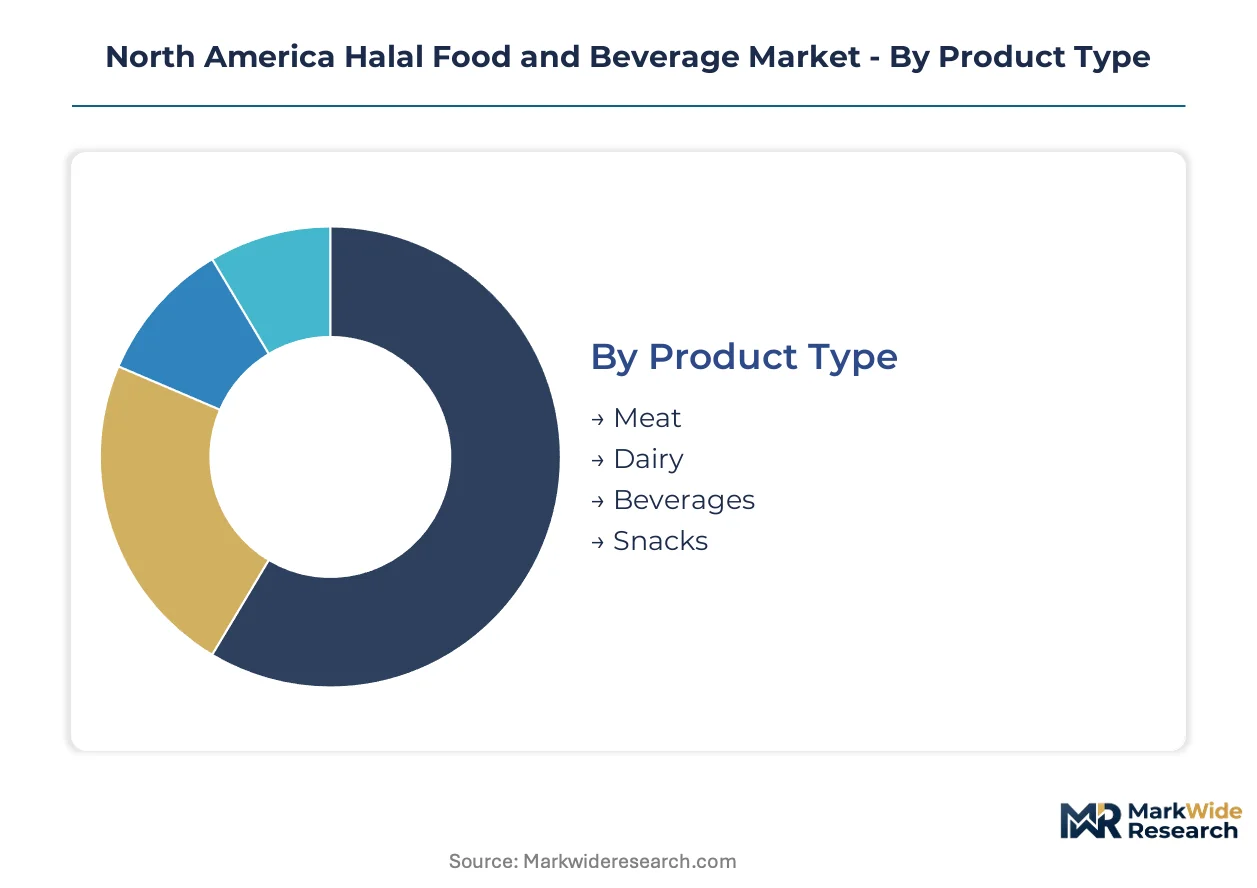
Halal food and beverage segmentation in North America reflects layered compliance obligations that reshape procurement priorities across protein processors, dairy cooperatives, and beverage formulators. Understanding how certification tiers, channel structures, and consumer profiles intersect determines where capital deploys for shelf access and margin capture.
Product Type:
USDA-FSIS slaughter inspection protocols create divergent compliance burdens across animal-derived versus plant-based categories, with ritual slaughter requirements concentrating regulatory scrutiny on specific product classes.
- Meat:Beef, lamb, and poultry products requiring zabiha-compliant slaughter with documented chain of custody from farm to fabrication. USDA-inspected facilities in Texas and Ontario handle the bulk of certified throughput, though hand-slaughter labor scarcity constrains expansion at dedicated halal plants.
- Dairy:Milk, cheese, and yogurt formulations free from animal-derived rennet and alcohol-based flavor carriers. Demand clusters in the Greater Toronto Area where South Asian households prioritize enzyme-compliant cheese varieties for home cooking.
- Beverages:Alcohol-free functional drinks, juices, and probiotic formulations. Steepest expansion trajectory as adaptogenic and nootropic products attract crossover health-conscious buyers beyond faith-observant segments.
- Snacks:Confectionery, savory items, and prepared foods with verified ingredient provenance and production line segregation.
Meat handles the majority of throughput; Beverages is the fastest mover on share.
Certification Type:
Cost tier differentiation separates premium-positioned products with multi-label claims from baseline halal-certified alternatives competing primarily on price.
- Halal Certifying Bodies:Islamic authorities such as ISNA, HFSAA, and regional councils provide religious compliance verification. Fragmentation across standards creates retailer hesitation in permanent shelf allocation decisions.
- Government Regulations:USDA-FSIS and CFIA oversight intersects with religious certification to create dual-compliance pathways. Updated inspection frameworks permit simultaneous halal-organic line certification, reducing overhead for multi-label processors.
- Employee Training:Slaughterman qualification programs and facility handler certification ensure ritual compliance and cross-contamination prevention.
- Quality Standards:ISO and sector-specific hygiene protocols augment religious requirements for export-facing production.
Government Regulations absorb the heaviest compliance investment; Halal Certifying Bodies generate the most procurement friction for new market entrants.
Distribution Channel:
Customer type concentration varies sharply between faith-observant households seeking provenance assurance and convenience-oriented buyers prioritizing accessibility over certification depth.
- Online Retail:Subscription meat boxes, ethnic e-commerce platforms, and direct-to-consumer spice imports. Digital-native intermediaries like WeHalal concentrate demand data and compress traditional distributor margins.
- Supermarkets:Permanent halal sections in mainstream chains including Costco and Walmart. Mature channel with structural margin pools but high slotting fees and vendor compliance portal requirements.
- Specialty Stores:Independent halal butchers and ethnic grocers in Chicago and Houston suburbs. Fragmented footprint losing share to consolidated retail and digital channels.
- Foodservice:Restaurant chains, institutional catering, and QSR halal menu expansions. Younger Muslim demographics drive chain adoption across the United States and Canada.
Supermarkets dominate current value generation; Online Retail is climbing the fastest as younger households consolidate purchasing through digital platforms.
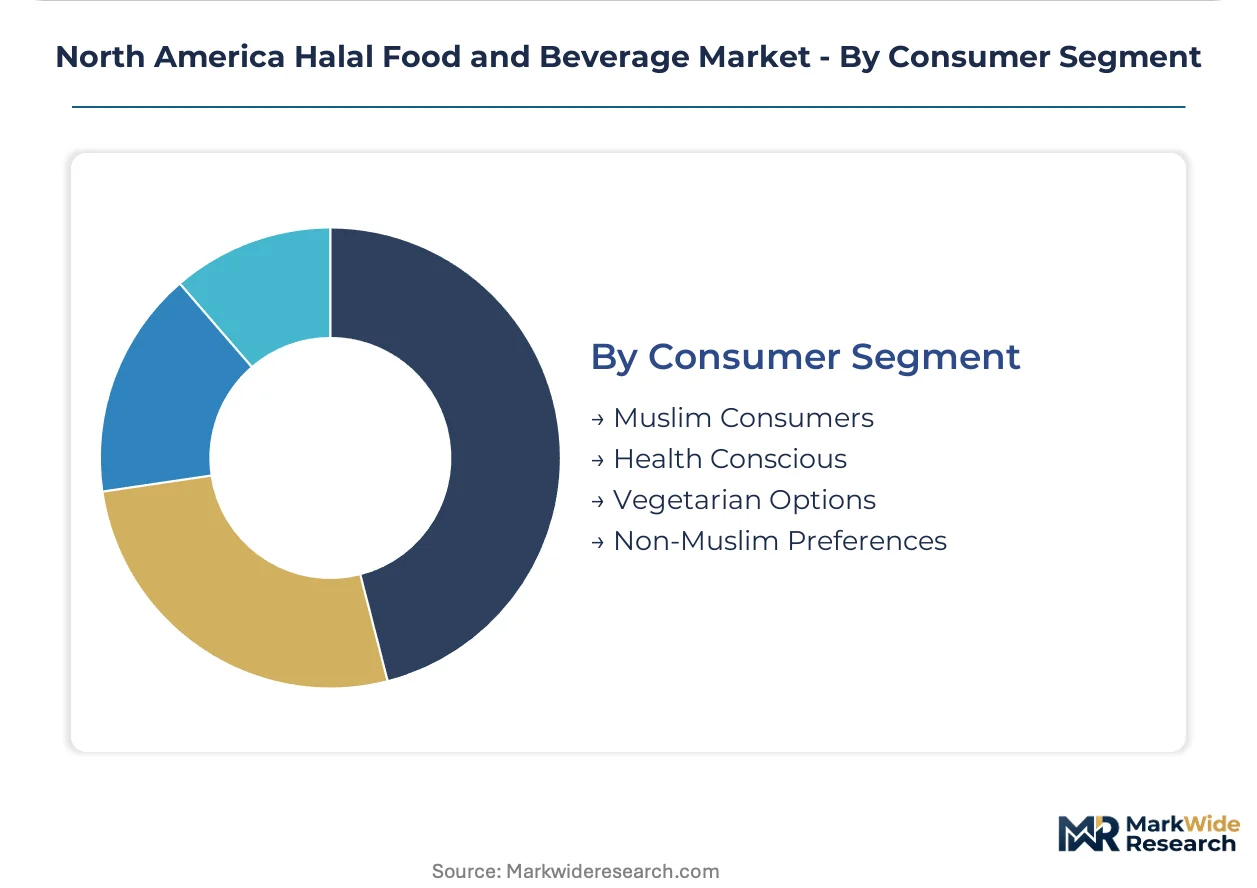
Consumer Segment:
Application focus determines formulation priorities, with faith-based requirements governing ingredient selection while adjacent segments emphasize health claims and ethical positioning.
- Muslim Consumers:Faith-observant households requiring verified halal compliance for daily protein and prepared food purchases. Core demand base with highest certification sensitivity and lowest price elasticity on ritual slaughter products.
- Health Conscious:Buyers associating halal with cleanliness, animal welfare, and absence of certain additives. Crossover segment expanding fastest as organic and halal claims converge on single labels.
- Vegetarian Options:Plant-based and meat-alternative seekers utilizing halal certification as a proxy for ethical production standards.
- Non-Muslim Preferences:General population buyers encountering halal products through mainstream retail placement without active certification seeking.
Muslim Consumers anchor volume commitment; Health Conscious buyers are gaining share fastest as dual halal-organic positioning penetrates conventional grocers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian beef exporters ship halal-certified protein to Canadian and U.S. retail chains under CFIA and USDA import protocols. Mexican processors increasingly serve cross-border demand clusters in Texas and California.
United States
Chicago and Houston suburbs concentrate younger Muslim households driving subscription meat box adoption. USDA-FSIS slaughter modernization permits simultaneous halal-organic line certification, reducing compliance overhead for multi-label processors. Dallas-Fort Worth anchors industrial-scale poultry processing with dedicated halal production lines serving national retail chains.
Canada
The Greater Toronto Area supports dedicated halal retail corridors with sufficient volume for specialized distribution infrastructure. CFIA enforcement of Safe Food for Canadians Regulations mandates certifier accreditation alignment with federal food safety frameworks. Ontario processors face hand-slaughter labor scarcity constraining throughput at zabiha-certified facilities.
Mexico
Northern border states supply cross-border halal protein to California and Texas markets. The country's national food safety regulator oversees slaughter standards for export-bound production. Baja California and Chihuahua host processing clusters targeting U.S. Muslim consumer concentrations in San Diego and El Paso.
North America Halal Food and Beverage Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and channel access. The vendor base stratifies into three layers: multinational protein conglomerates with integrated halal lines, mid-scale regional processors serving ethnic retail corridors, and digital-native brands built on subscription direct-to-consumer models. Dominant competitive moves include backward integration into captive slaughter capacity and partnership formations with CFIA-recognized certification bodies for streamlined Canadian market entry.
Within the multinational tier, JBS S.A. and BRF S.A. represent Brazilian-origin protein exporters navigating North American import compliance. Cargill Incorporated anchors industrial-scale supply through integrated beef and poultry networks. Nestlé S.A. occupies a position exemplifying packaged goods diversification into halal-compliant infant nutrition and confectionery portfolios.
| Leading Market Players |
|---|
| JBS S.A. |
| Saffron Road |
| Cargill Incorporated |
| BRF S.A. |
| Midamar Corporation |
| Crescent Foods, Inc. |
| Nestlé S.A. |
| Al Islami Foods |
| American Foods Group, LLC |
| Others |
Value Network & Pricing Analysis
Hand-slaughter labor substitution by mechanized processing lines in Texas and Ontario simultaneously redraws supply geography toward capital-intensive facilities and compresses pricing premiums for zabiha-certified protein. This shift concentrates margin capture among processors with captive slaughter capacity while squeezing smaller hand-slaughter operations unable to absorb fixed-cost amortization.
Pricing Analysis
Current-generation hand-slaughter zabiha commands sustained premiums over prior-generation conventional halal and next-generation cell-cultured alternatives still awaiting regulatory clarity. Three-tier pricing structure across premium dual halal-organic, standard machine-slaughter halal, and economy conventional protein segments stratifies buyer access. Price differentiation rests on certification depth, with USDA Organic plus halal combinations extracting maximum shelf positioning fees at Costco and Walmart. Pricing pressure stems from feed cost volatility compressing poultry processor margins under fixed retail contracts. Health-conscious crossover buyers exhibit lowest price sensitivity on dual-labeled products, while budget-focused Muslim households in Chicago suburbs drive volume through promotional cycles.
Supply Chain Analysis
Inventory cycles for ritual-slaughter protein stretch longer than conventional equivalents due to certifier documentation requirements and dedicated line scheduling constraints. Geographic supply concentration centers on Brazil, Australia, and domestic U.S. production clusters in Texas and the Midwest. Raw material dependencies include corn and soybean feed inputs, specialized halal-certifying labor pools, and segregated cold-chain logistics. Supply chain risk concentrates on single-source vulnerability for hand-slaughter qualified personnel in Ontario and Texas facilities. Distribution runs through supermarket permanent halal sections, ethnic e-commerce platforms, and direct-to-consumer subscription channels serving younger Muslim households.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified slaughterman availability constrains throughput expansion at dedicated zabiha facilities, creating a bottleneck that separates processors with captive labor pipelines from competitors facing throughput caps. This scarcity dynamic rewards early investment in training infrastructure and mechanized alternatives.
For Market Incumbents: Shield market position by securing exclusive hand-slaughter labor contracts in Greater Toronto Area and Dallas-Fort Worth corridors before competitor expansion. Backward integration into captive feed sourcing mitigates corn and soybean price volatility threatening margin stability. Invest in blockchain-enabled ERP systems to satisfy Costco and Walmart vendor compliance portals ahead of certifier fragmentation resolution.
For New Entrants and Emerging Players: Lead with subscription meat box channels bypassing conventional retail slotting fees while capturing younger Muslim households in Houston and Chicago suburbs. Target functional beverage convergence as the most penetrable white space, where alcohol-free adaptogenic formulations attract crossover health-conscious buyers beyond faith-observant segments. Deploy direct-to-consumer digital-native positioning to concentrate demand data and compress legacy distributor margins.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors processors with integrated halal production lines and CFIA-recognized certification partnerships. Long-term viability across the projection horizon rests on regulatory compliance infrastructure rather than brand equity alone. Acquisition targets should demonstrate established vendor portal access at mainstream retail chains. Monitor CFIA enforcement actions against non-accredited overseas certifiers as the critical inflection signal for import pathway restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Slaughter Capacity | Secures throughput control against hand-slaughter labor scarcity constraining Ontario and Texas competitors. |
| CFIA-Recognized Certification Partnership | Streamlines Canadian market entry for Brazilian and Australian beef exporters facing tightened Safe Food for Canadians Regulations. |
| Blockchain-Enabled Supply Chain Verification | Satisfies Costco and Walmart vendor compliance portals demanding real-time ingredient provenance documentation. |
| Direct-to-Consumer Subscription Launch | Bypasses supermarket slotting fees while concentrating demand data with digital-native intermediaries like WeHalal. |
| Dual Halal-Organic Label Investment | Captures premium positioning at mainstream grocers serving health-conscious crossover buyers beyond core Muslim segments. |
Research Methodology
Cross-validation between primary interviews with halal certifying body officials, USDA-FSIS compliance officers, and supermarket category buyers anchors the qualitative findings against secondary validation. Procurement leads at protein processors, supply chain managers at ethnic e-commerce platforms, and facility handlers at dedicated halal plants provided operational perspective. Secondary sources include USDA slaughter inspection records, CFIA Safe Food for Canadians Regulations documentation, and customs data on Brazilian and Australian beef imports. Bottom-up channel volume estimates triangulate against top-down consumer expenditure models.
Sensitivity analysis across feed cost volatility scenarios, certifier accreditation changes, and channel shift velocities stress-tests base-case projections. Segmentation dimensions modeled encompass product type, certification tier, distribution channel, and consumer segment stratification. CAGRs derive from trend-line extrapolation adjusted for regulatory inflection points and technology maturation curves. Ritual slaughter labor availability and blockchain adoption rates at mid-scale processors constitute key industry-specific forecast inputs.
Underlying assumptions cover sustained Muslim population growth in target metropolitan corridors, stable USDA-FSIS inspection frameworks, and continued CFIA enforcement consistency, with deviation risk concentrated in certifier fragmentation resolution and cell-cultured protein regulatory clarity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Social Networks Market
Others
Bimodal Identity Management Solutions Market
Others
Europe Intercom Devices Market
Others
Global Phablets and Superphones Market
Others
Hypersensitivity Market
Others
Global Bio-Based Chemicals Market
Others
Global Mobile Gambling Market
Others
Port Replicator Market
Others
Managed Testing Services Market
Others
Spain Automotive LED Lighting Market
Others
Reduced-Risk Products (Rrps) Market
Others
Industrial Computers Market
Others
Belt Loader Market
Others
Mobile Computer Cart Market
Others
US Luxury Travel Market
Others
Refractometer Market