
 Mobile Computing Devices Market | 2026-2036
Mobile Computing Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Computing Devices Market Foresight
Semiconductor fabrication talent scarcity is unwinding capacity expansion timelines for mobile chip foundries. Apple Inc. leverages captive silicon design to differentiate performance-per-watt across its device portfolio. Samsung Electronics anchors display panel supply through backward integration into OLED substrate manufacturing. Lenovo competes on commercial laptop configurability, sustaining enterprise procurement relationships across price-elastic segments.
Mobile computing devices encompass portable electronic systems integrating microprocessors, solid-state storage, lithium-polymer cells, and wireless modems within sub-two-kilogram form factors, engineered to execute general-purpose computation without fixed power tethering. Smartphones and laptops occupy the dominant revenue positions, while convertibles capture margin pools in hybrid productivity segments where professionals demand tablet-to-keyboard modality switching. Android and iOS operating systems structure the platform duopoly, with Chrome OS gaining institutional traction in education procurement cycles where administrators prioritize cloud-native manageability and per-unit acquisition cost.
FCC equipment authorization mandates govern radio frequency emissions for devices sold in the United States, while EU RoHS and REACH directives restrict hazardous substance content in batteries and solder joints across European distribution channels. Ecodesign regulations under the EU Green Deal framework are forcing modular battery architectures and standardized charging port harmonization, directly impacting original equipment manufacturer bill-of-material decisions. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens platform economies of scale and influences regional product variant strategies.
Market Dynamics
Gallium nitride charging architectures and production-linked incentive frameworks in India are compressing cost curves while fragmenting manufacturing geography away from legacy East Asian concentration.
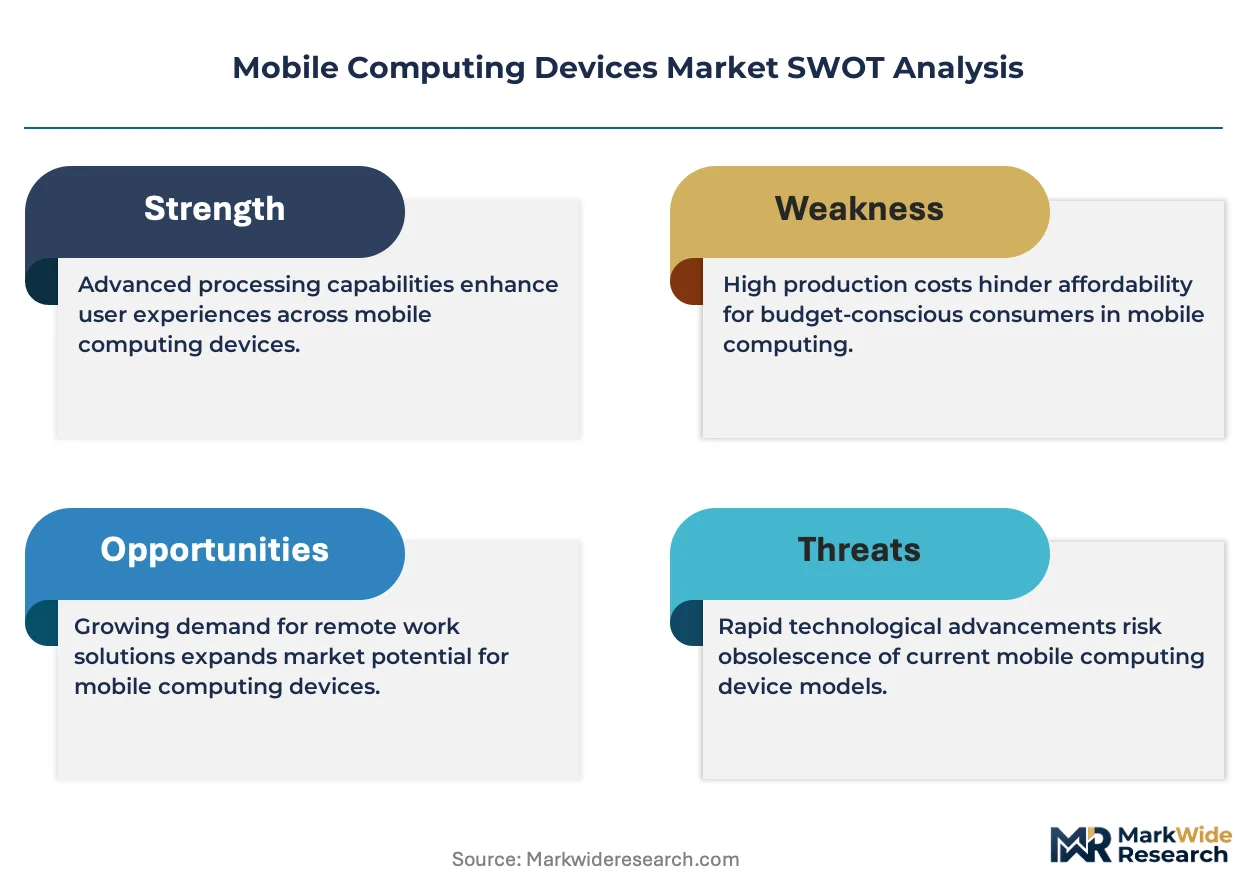
Growth Catalysts
- Healthcare enterprise mobility:Hospital delivery networks deploy ruggedized tablets and clinical smartphones to enable bedside data capture, driving replacement cycles for legacy workstation-on-wheels infrastructure.
- India PLI scheme:Production-linked incentive frameworks scale domestic assembly capacity for export-oriented smartphone and laptop manufacturing, attracting component suppliers to co-locate.
- Battery energy density gains:Silicon-anode lithium-polymer cells extend runtime expectations for ultrabook form factors, reducing tethering anxiety in field workforce deployments.
Market Restraints
- Semiconductor fabrication talent scarcity:Foundry expansion timelines unwind as specialized process engineering expertise concentrates in Taiwan and South Korea.
- EU Ecodesign mandates:Modular battery architecture requirements and USB-C harmonization rules inflate bill-of-material costs for multi-jurisdiction product variants.
- Display substrate supply concentration:OLED driver IC and flexible substrate capacity anchors in Korean and Chinese suppliers, creating single-source vulnerability.
Strategic Opportunities
- Chrome OS education procurement:Cloud-native manageability and per-unit acquisition cost priorities open institutional laptop segments in North American K-12 districts.
- Convertible modality convergence:Hybrid tablet-keyboard form factors capture margin pools from professionals demanding single-device productivity across office and mobile contexts.
- EU Green Deal circularity requirements:Right-to-repair mandates and extended producer responsibility frameworks create aftermarket service and refurbishment revenue streams.
Industry Challenges
- RF certification fragmentation:FCC equipment authorization, EU CE marking, and India BIS testing timelines diverge, forcing redundant compliance expenditure for simultaneous multi-market launches.
- Legacy system integration friction:Enterprise mobility deployments confront on-premise ERP and patient record systems requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Computing Devices Market |
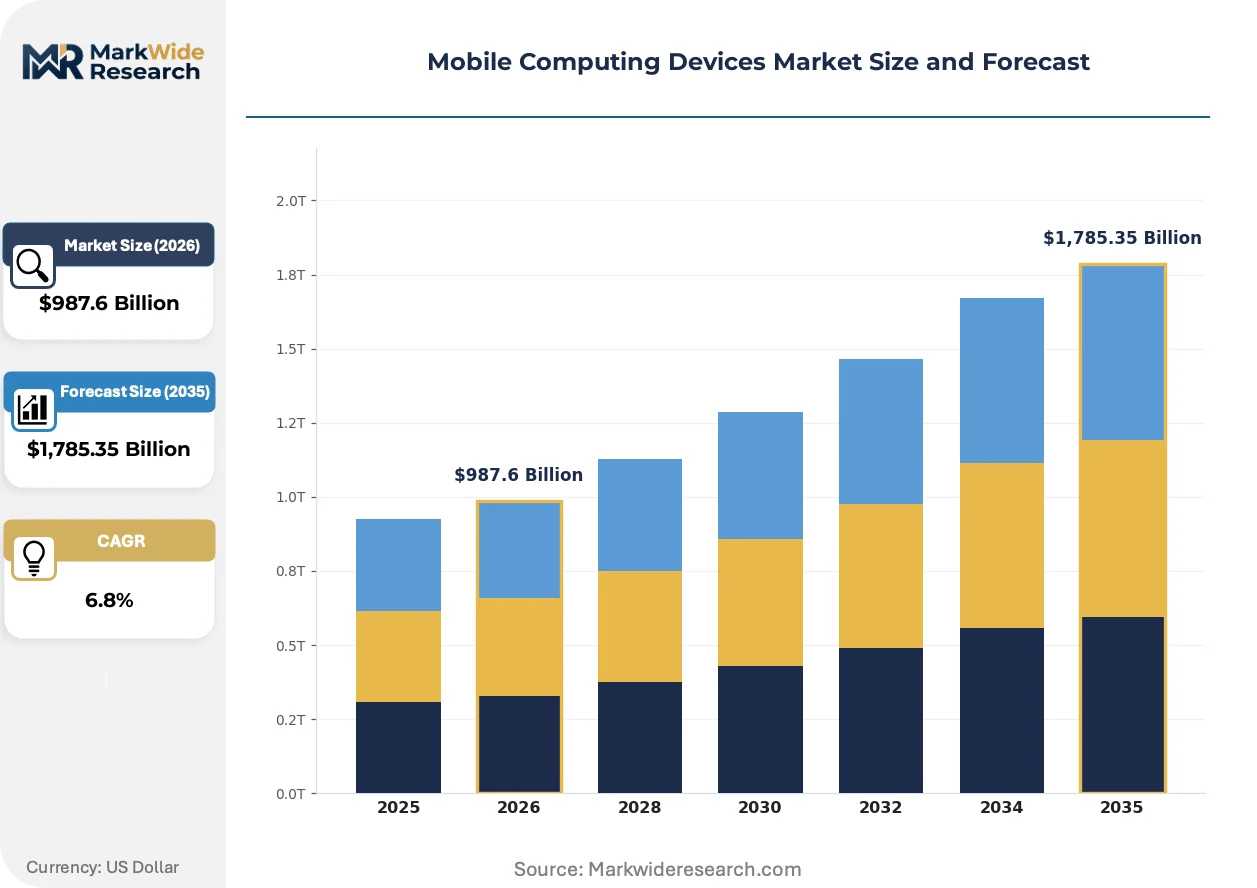
| Market Size in 2026 | $987.6 Billion |
| Market Size in 2035 | $1,785.35 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Tablets, Laptops, Convertibles Operating System: Android, iOS, Windows, Chrome OS End User: Students, Professionals, Gamers, Creatives Connectivity: Wi-Fi, Bluetooth, Cellular, NFC |
| Companies Covered | Apple Inc., Samsung Electronics, Lenovo, Dell Technologies, Hewlett-Packard Development Company, ASUSTeK Computer Inc., Acer, Sony Corporation, Xiaomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Computing Devices Market Shifts & Advancements
Compute architectures, power delivery standards, and procurement modalities are decomposing the traditional laptop-smartphone dichotomy into fluid, task-optimized device categories.
Arm-based system-on-chip designs are decomposing the x86 dominance in thin-and-light laptops. Chromebook and Windows-on-Arm OEMs accelerate platform diversification as battery life benchmarks stretch past fifteen hours. Qualcomm and MediaTek silicon is decomposing Intel's historical grip on mobile productivity segments.
EU Ecodesign regulations under the Green Deal framework mandate standardized charging ports and modular battery replacement by 2027. OEMs must redesign internal layouts and thermal systems to accommodate user-serviceable cells. Premium ultrabook lines face the steepest reengineering costs as sealed-unibody aesthetics confront repairability mandates.
Enterprise buyers now unbundle device acquisition from lifecycle management services. IT departments in financial services and healthcare verticals contract independent mobility management platforms rather than OEM bundled offerings. This procurement fragmentation is most visible in US and German markets where procurement autonomy and data sovereignty requirements intersect.
Mobile Computing Devices Market Segmentation
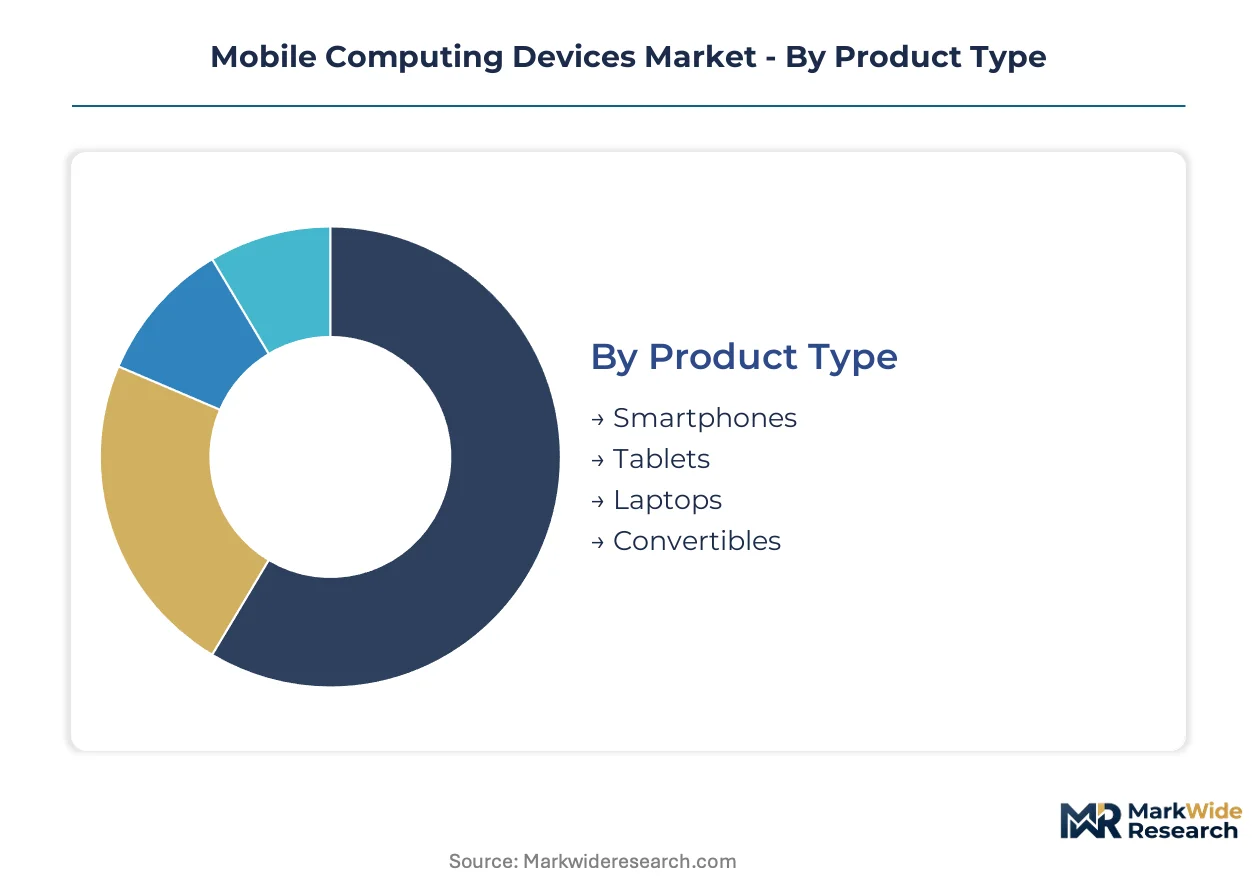
Device substitution pressures reshape category boundaries as smartphones absorb tablet functionality and convertibles erode traditional laptop procurement. Understanding where substitution threat concentrates guides portfolio allocation and R&D prioritization across overlapping form factors.
Product Type:
Substitution pressure runs strongest against tablets as smartphones enlarge displays and laptops shed weight, compressing the middle ground.
- Smartphones:Pocket-sized systems integrating cellular modems, multi-camera arrays, and Arm-based application processors within sub-200-gram enclosures. India PLI assembly capacity scales export volumes while silicon-anode batteries extend field workforce tethering intervals.
- Laptops:Clamshell form factors with x86 or Arm SoCs, full-travel keyboards, and active-cooling thermal systems above 1.2 kilograms. Enterprise procurement in German financial services and US healthcare delivery networks prioritizes fifteen-hour battery benchmarks and Thunderbolt docking compatibility.
- Tablets:Slate devices with touch-first interfaces, stylus digitizers, and detachable keyboard accessories spanning 9-13 inch diagonals. Education procurement cycles in North American K-12 districts favor Chrome OS variants for cloud-native manageability.
- Convertibles:360-degree hinge designs enabling tablet-to-laptop modality switching through rotating or detachable mechanisms. Hybrid professionals in creative and consulting verticals drive margin capture for premium magnesium-alloy unibody constructions.
Smartphones retain volume leadership; convertibles hold the steepest expansion curve.
Operating System:
Platform economics stratify across hardware-software integration depth and enterprise manageability requirements.
- Android:Open-source Linux kernel with Google Mobile Services licensing tiered across premium and entry-level device portfolios. Indian and Southeast Asian OEMs leverage AOSP forks to avoid service fees while domestic brands capture price-elastic segments.
- iOS:Closed-source Unix derivative with vertically integrated silicon optimization and App Store distribution control. Captive chip design at Apple extends performance-per-watt differentiation in premium smartphone and tablet tiers.
- Windows:NT kernel architecture supporting x86 legacy application compatibility and Active Directory enterprise policy enforcement. Enterprise IT departments in US healthcare and German manufacturing sustain procurement despite Arm-based battery life advantages.
- Chrome OS:Linux-based cloud-native platform with automatic security patching and Google Admin console fleet management. North American education institutions prioritize per-unit acquisition cost and zero-touch enrollment over local storage capacity.
Android commands absolute shipment scale; Chrome OS climbs fastest in institutional procurement.
End User:
Performance requirements and price elasticity diverge sharply across productivity, entertainment, and content creation use cases.
- Students:Price-sensitive demand prioritizing durability, keyboard comfort, and cloud storage integration over local compute throughput. Ruggedized Chromebooks with spill-resistant keyboards dominate US K-12 one-to-one device programs.
- Professionals:Enterprise and knowledge-worker segments demanding security certifications, docking ecosystem compatibility, and IT manageability platforms. Financial services procurement in Frankfurt and London specifies TPM 2.0 modules and Windows Hello biometric authentication.
- Gamers:Thermal headroom and discrete GPU performance prioritize thick chassis designs with vapor chamber cooling and high-refresh displays. Mobile esports titles in South Korea and China drive demand for 120Hz OLED panels and Snapdragon 8-series silicon.
- Creatives:Color-accurate displays, stylus latency below 10 milliseconds, and video encoding acceleration for 4K timelines. Adobe Creative Cloud workflows in Los Angeles and Mumbai post-production houses require P3 gamut coverage and Thunderbolt external GPU support.
Professionals anchor enterprise ASPs; creatives expand fastest as remote production workflows proliferate.
Connectivity:
Radio frequency integration costs and regulatory certification burdens fragment feature bundling across price tiers.
- Wi-Fi:IEEE 802.11ax/6E standards enabling 160MHz channel bonding and sub-3-millisecond latency in dense office environments. Enterprise access point upgrades in Singapore and Dallas data centers drive Wi-Fi 6E client refresh cycles.
- Bluetooth:Low-energy audio and HID profiles for wireless peripheral attachment with sub-10mW standby consumption. Hearing aid compatibility mandates from FCC govern US smartphone implementations.
- Cellular:5G NR sub-6GHz and mmWave modems with carrier aggregation enabling 1Gbps peak throughput. TRAI spectrum allocation in India and FCC C-band auctions in the US shape regional band support requirements.
- NFC:13.56MHz contactless interface for payment tokenization and access credential emulation. EU PSD2 strong customer authentication rules and RBI tokenization guidelines in India govern secure element implementations.
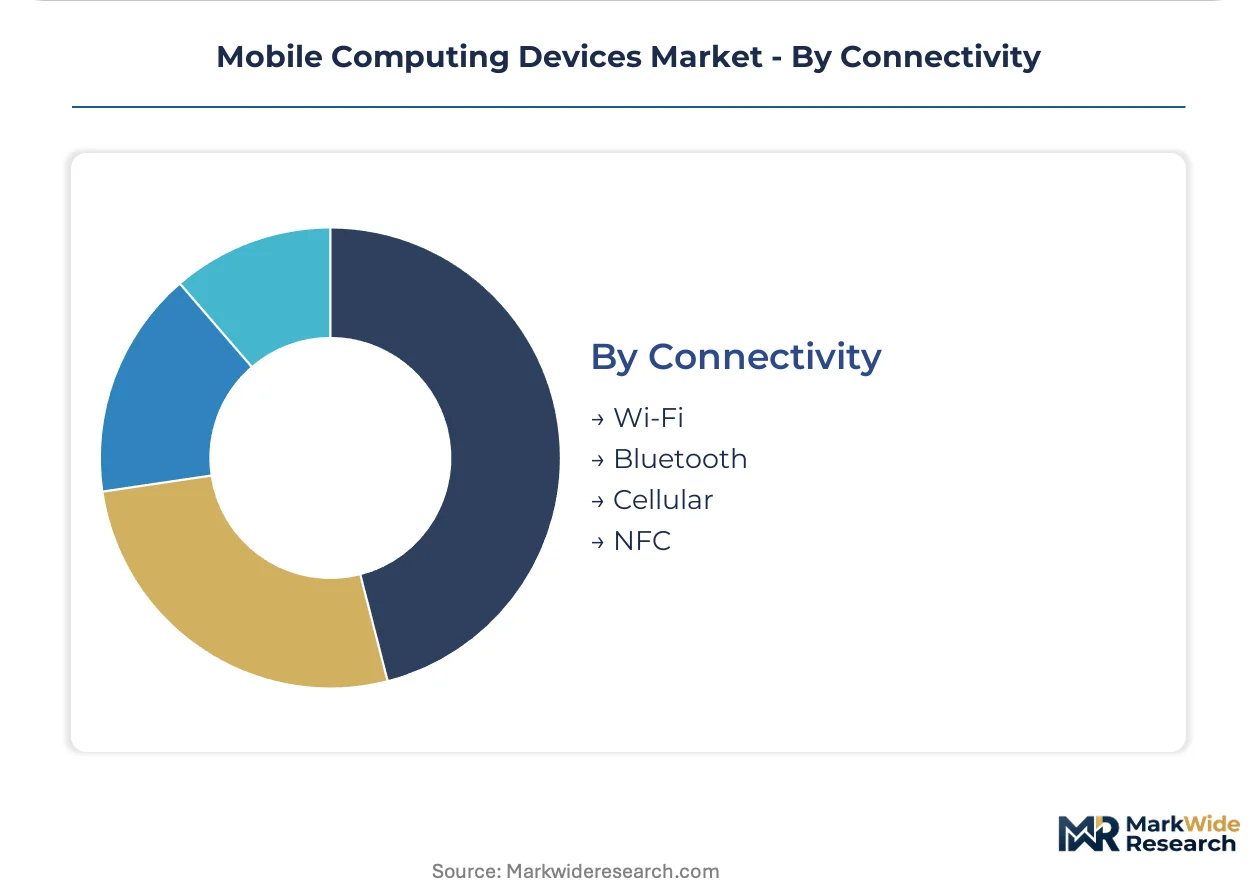
Wi-Fi retains ubiquitous integration; cellular expands most quickly as 5G modems penetrate mid-tier price bands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC equipment authorization mandates govern radio frequency emissions for devices sold in the United States, while divergent certification timelines across jurisdictions force redundant compliance expenditure for multi-market launches.
United States
Enterprise mobility deployments in healthcare delivery networks and financial services drive replacement cycles for clinical smartphones and ruggedized tablets. FCC equipment authorization and HIPAA security rule enforcement shape procurement specifications for devices handling protected health information. Dallas and Seattle data center clusters anchor Wi-Fi 6E infrastructure upgrades that pull client device refresh cycles.
China
Domestic OEMs leverage MIIT spectrum allocation frameworks and GB standards compliance to accelerate 5G modem penetration into mid-tier price bands. Dual carbon goals under MEE oversight push gallium nitride charging architectures and silicon-anode battery cell adoption. Shenzhen and Dongguan manufacturing corridors concentrate flexible OLED substrate capacity and display driver IC packaging operations.
Germany
Frankfurt and Munich financial services procurement prioritizes TPM 2.0 modules, Windows Hello biometric authentication, and Thunderbolt docking compatibility for knowledge-worker deployments. EU Ecodesign regulations under the Green Deal framework mandate modular battery architectures and USB-C harmonization by 2027. Baden-Württemberg industrial clusters host precision tooling suppliers for magnesium-alloy unibody convertible chassis.
India
Production-linked incentive frameworks scale domestic assembly capacity for export-oriented smartphone and laptop manufacturing, attracting component suppliers to co-locate with OEMs. TRAI spectrum allocation shapes 5G NR band support requirements for devices targeting the subcontinent. Tamil Nadu and Karnataka electronics manufacturing corridors concentrate surface-mount technology lines and lithium-polymer cell packaging operations.
South Korea
Mobile esports titles drive demand for 120Hz OLED panels and Snapdragon 8-series silicon in the consumer segment. MFDS and KCC certification requirements govern device safety and electromagnetic compatibility testing timelines. Seoul and Suwon metropolitan clusters anchor OLED driver IC design houses and flexible substrate material suppliers.
Mobile Computing Devices Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in mobile computing devices. The upper tier controls captive silicon design, display substrate manufacturing, and global distribution logistics. Specialist players compete on commercial laptop configurability, education procurement relationships, and regional price-elastic segments. Dominant competitive moves include backward integration into component supply and strategic partnerships with carrier channels for 5G device certification.
Within the integrated leader tier, Apple Inc. and Samsung Electronics exemplify vertical control over silicon and display supply chains. Lenovo occupies a position bridging enterprise configurability and consumer accessibility across multiple operating system platforms. These three anchors represent divergent strategic archetypes: captive ecosystem lock-in, component supply dominance, and commercial procurement flexibility.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Lenovo |
| Dell Technologies |
| Hewlett-Packard Development Company |
| ASUSTeK Computer Inc. |
| Acer |
| Sony Corporation |
| Xiaomi |
| Others |
Supply & Pricing Matrix
Wafer fab utilization rates above 90 percent in Taiwan and South Korea concentrate bargaining power among foundry operators, compressing margin pools for fabless chip designers and establishing price floors for mid-tier smartphones and laptops that OEMs cannot negotiate below without sacrificing component quality or delivery priority.
Pricing Analysis
Geographic price spreads between India-assembled devices and legacy China-manufactured equivalents compress as PLI subsidies offset logistics differentials. Three-tier pricing structure across premium, standard, and economy levels segments on silicon node sophistication and display panel technology, with OLED-equipped flagships commanding substantial premiums over LCD-based configurations. Pricing pressure stems from gallium nitride charger commoditization and standardized USB-C mandates eliminating proprietary accessory revenue. Education procurement officers exhibit highest price sensitivity, while enterprise IT departments in financial services prioritize total cost of ownership over per-unit acquisition cost.
Supply Chain Analysis
Strategic stockpiling of display driver ICs and battery cells supplanted just-in-time preferences after 2021-2022 shortages, with OEMs now carrying 8-12 weeks of critical component inventory. Manufacturing concentrates in China, Vietnam, and India for final assembly, while Taiwan and South Korea anchor advanced semiconductor fabrication. Raw material dependencies center on lithium carbonate from Chile and Australia, rare earth elements from China, and high-purity silicon wafers from Japan and Germany. Single-source vulnerability in flexible OLED substrate supply creates concentration risk. Distribution runs through carrier-certified retail channels and enterprise direct procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against smartphone-laptop convergence as convertibles and large-format phablets absorb tasks previously requiring dedicated computing devices, eroding category boundaries that historically protected margin pools.
For Market Incumbents: Secure captive silicon design capabilities to differentiate performance-per-watt as Arm-based platforms displace x86 dominance in thin-and-light segments. Backward integration into battery cell packaging mitigates supply interruption risks from concentrated Asian suppliers. Prioritize modular architecture investments ahead of EU Ecodesign repairability mandates to avoid punitive reengineering costs.
For New Entrants and Emerging Players: BIS certification fast-track in India unlocks access to PLI-subsidized manufacturing corridors and export-oriented production capacity. White-space concentration sits in ruggedized clinical tablets for Southeast Asian hospital networks and Chrome OS education devices for African ministries of education pursuing one-to-one computing programs. Partner with regional carrier channels to accelerate 5G device authorization timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component suppliers with in-house gallium nitride and silicon-anode capabilities rather than assembly-heavy OEMs facing margin compression. Long-term viability hinges on circular economy service revenue streams from refurbishment and battery replacement operations. Watch EU Green Deal enforcement intensity as the inflection signal determining which OEMs absorb compliance costs versus passing through to enterprise buyers.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Silicon Design Investment | Apple's A-series and M-series chips demonstrate performance-per-watt differentiation that sustains premium pricing. |
| Modular Battery Architecture Transition | EU Ecodesign mandates force redesign of sealed-unibody ultrabooks to accommodate user-serviceable cells. |
| India PLI Manufacturing Scale-Up | Tamil Nadu and Karnataka corridors attract component suppliers co-locating with export-oriented OEM assembly. |
| Chrome OS Education Procurement Capture | North American K-12 districts prioritize cloud-native manageability and zero-touch enrollment over local storage. |
| Enterprise Mobility Management Unbundling | Financial services and healthcare IT departments contract independent platforms rather than OEM bundled offerings. |
Research Methodology
Operator-level perspectives from semiconductor foundry executives, display panel procurement managers, OEM product planning directors, and enterprise IT mobility administrators anchored the qualitative base. Secondary validation drew from FCC equipment authorization databases, EU Ecodesign regulatory filings, TRAI spectrum allocation notices, and India PLI scheme beneficiary disclosures. Bottom-up shipment estimates by form factor and operating system triangulated against top-down semiconductor wafer starts and display panel area forecasts.
Sensitivity analysis tested forecast robustness across battery energy density improvement trajectories, gallium nitride penetration rates, and India PLI scheme extension scenarios. Segmentation modeling spanned product type, operating system platform, end-user archetype, and connectivity configuration across the analysis window. CAGRs derived from logistic diffusion curves fitted to historical replacement cycle data and enterprise procurement survey responses. Specific inputs included healthcare mobility deployment timelines and education institution refresh cadences.
The analysis sits within stated boundaries; outcomes outside sustained India manufacturing scale-up or EU regulatory enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding component cost curves and enterprise procurement autonomy trends. Revision becomes warranted when semiconductor fabrication talent scarcity crosses thresholds that unwind foundry expansion timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Triathlon Clothing Market
Others
AI in Precision Medicine Market
Others
France 3D Printing Construction Market
Others
Smartphone Gimbal Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Tunnel Lighting Market
Others
Massive Machine Type Communication in Healthcare Market
Others
Asia Pacific Video Conferencing Hardware Market
Others
Europe Meditation Market
Others
Middle East 3D Printing Construction Market
Others
Vacuum Evaporators Market
Others
Post Consumer Recycled Bottles Market
Others
Baking Paper Market
Others
Propanil Market
Others
Global Cryogenic Tanks Market