
 Global Military Lighting Market | 2026-2036
Global Military Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Lighting Market Foresight
Naval platform electrification is repositioning procurement priorities across maritime defense programs. Honeywell International Inc. leverages its aerospace heritage to dominate shipboard lighting retrofits, while Oxley Group specializes in ruggedized LED assemblies for submarine compartments. Collins Aerospace sustains its position through backward integration into fiber optic illumination for cockpit and command environments.
Military lighting encompasses electroluminescent and solid-state illumination systems engineered to MIL-STD-3009 night vision compatibility standards, with primary purpose being operational visibility across contested electromagnetic environments. LED technology leads installed base conversions due to thermal efficiency and spectral tunability for night vision goggle compatibility, while infrared lights represent the fastest-expanding segment as signature management protocols tighten across special operations forces. Fiber optic technology occupies premium margin pools in platform-integrated architectural lighting where electromagnetic interference immunity proves decisive.
The US Department of Defense enforces MIL-STD-810H environmental resilience certification, while NATO's STANAG 4370 standardizes climatic testing protocols for coalition interoperability; both frameworks compel manufacturers to maintain multi-standard testing infrastructure that smaller competitors cannot replicate. The EU AI Act and emerging autonomous platform directives will extend compliance burdens into intelligent adaptive lighting systems. Stakeholders must monitor how electromagnetic spectrum dominance doctrines reshape spectral output requirements before committing to fixed-wavelength production architectures.
Market Dynamics
Platform electrification across naval and ground vehicle fleets is compressing legacy incandescent replacement cycles and forcing spectral compatibility recertification at unprecedented velocity. Defense procurement offices now mandate MIL-STD-3009 night vision interoperability as a gate criterion, disqualifying suppliers lacking multi-spectral testing infrastructure.
Growth Catalysts
- MIL-STD-810H Certification Mandates:US Department of Defense environmental resilience requirements accelerate LED retrofit programs across Army ground vehicle fleets, eliminating incandescent suppliers unable to replicate thermal shock and vibration testing protocols.
- Special Operations Forces Procurement:Infrared signature management protocols tighten across NATO special operations commands, pulling demand for covert illumination systems with tunable spectral output beyond visible wavelengths.
- Bundeswehr Vehicle Modernization:Germany's armored vehicle retrofit contracts sustain specialist LED manufacturers with multi-year platform integration programs requiring electromagnetic interference immunity certification.
Market Restraints
- Rare Earth Magnet Supply Concentration:Neodymium and dysprosium dependency on Chinese processing infrastructure creates input cost volatility for high-performance LED driver assemblies.
- Multi-Standard Testing Infrastructure:Simultaneous compliance with MIL-STD-810H, NATO STANAG 4370, and EU electromagnetic compatibility directives imposes capital barriers that smaller tier-two suppliers cannot surmount.
- Incandescent Legacy Installations:Decades-old platform wiring specifications limit voltage regulation compatibility, forcing expensive harness redesigns or power converter insertion.
Strategic Opportunities
- Submarine Compartment Electrification:Underpenetrated demand for fiber optic illumination in pressure hull environments offers premium margin pools where electromagnetic immunity proves decisive.
- EU AI Act Compliance Pathways:Intelligent adaptive lighting systems for autonomous ground vehicles face emerging regulatory frameworks that first-movers can architect into competitive moats.
- Urban Warfare Training Infrastructure:Spectrally tunable LED arrays for mock village and tunnel complexes represent a civilian-military crossover segment with compressed procurement cycles.
Industry Challenges
- Spectral Engineering Talent Scarcity:Night vision goggle compatibility optimization requires specialized photometric expertise concentrated in defense-adjacent research institutes.
- Platform Integration Complexity:Legacy vehicle electrical architectures force custom power conditioning module development for each major ground system variant.
- Certification Timeline Compression:Accelerated modernization programs compress environmental qualification from 18-month cycles to 9-month gates, straining test facility capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Lighting Market |
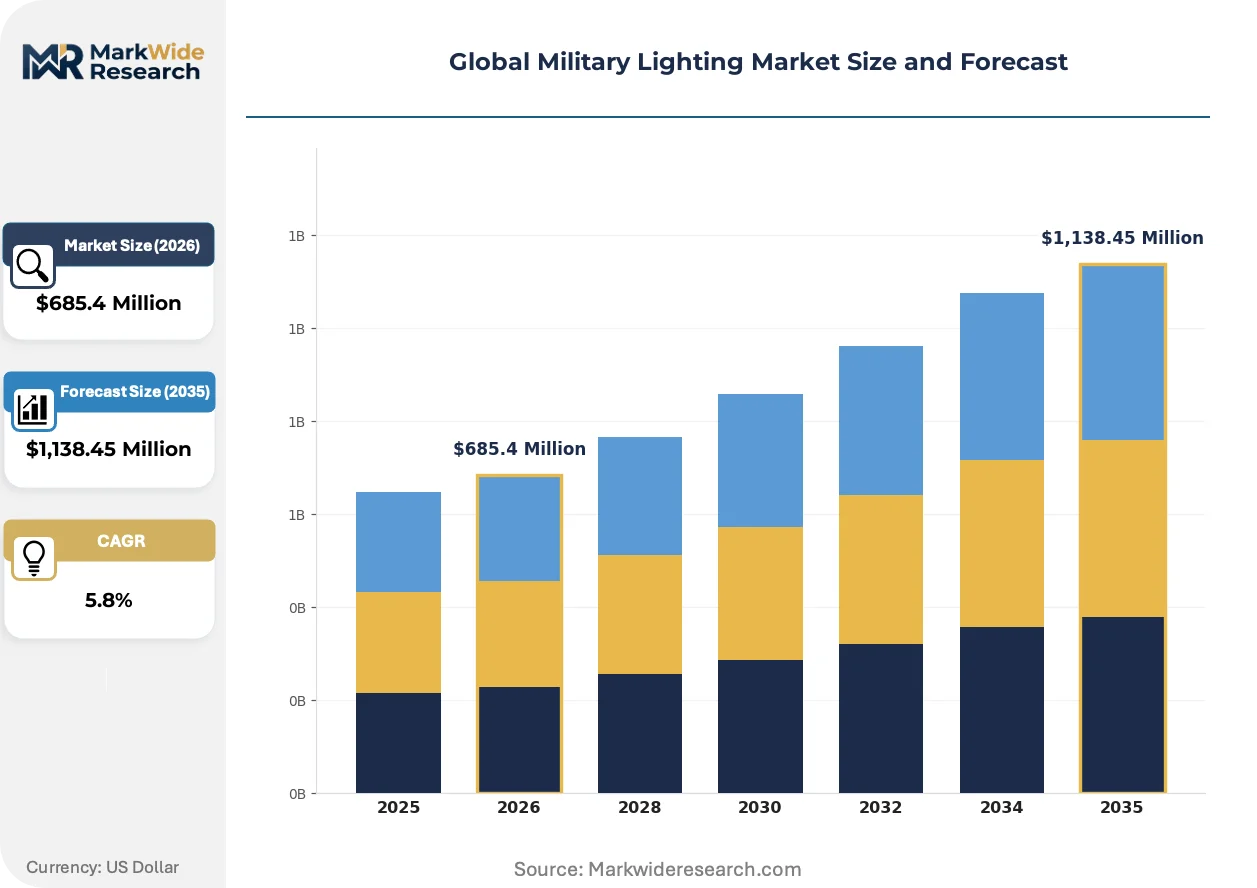
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flashlights, Spotlights, Tactical Lights, Infrared Lights, Signal Lights Technology: LED, OLED, Halogen, Xenon, Fiber Optic Application: Surveillance, Navigation, Combat Operations, Search & Rescue, Training Exercises End User: Armed Forces, Defense Contractors, Security Agencies, Paramilitary Groups, Peacekeeping Units |
| Companies Covered | Astronics Corporation, Honeywell International Inc., Oxley Group, Collins Aerospace, Orion Energy Systems, Glamox, Dialight plc, Carmanah Technologies Corporation, Luminator Technology Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Lighting Market Shifts & Advancements
Spectral tunability and intelligent power management are displacing fixed-wavelength architectures across tactical illumination procurement. Defense contractors now prioritize systems enabling real-time output adjustment for varying operational environments.
Adaptive LED arrays with integrated thermal feedback loops are integrating spectral management directly into luminaire control electronics. Special operations vehicle integrators adopt these systems fastest, compressing supplier qualification to single-source relationships with backward-compatible firmware architectures. This integration is enabling platform-level power budget optimization previously impossible with discrete component designs.
The EU AI Act's risk classification framework is extending compliance burdens into autonomous vehicle lighting systems with decision-making capabilities. Manufacturers must now document algorithmic transparency for adaptive beam pattern adjustment, forcing documentation infrastructure investments that favor incumbent defense primes. Maritime patrol aircraft programs in Germany and France face the steepest recertification timelines under these emerging requirements.
Defense procurement offices increasingly unbundle lighting system specification from platform prime contracts, creating direct vendor relationships with subsystem specialists. This disintermediation compresses price discovery cycles and transfers integration risk to lighting suppliers. The United States Army's ground vehicle modernization program exhibits this pattern most visibly, with separate RFP streams for luminaire hardware and software control layers.
Global Military Lighting Market Segmentation
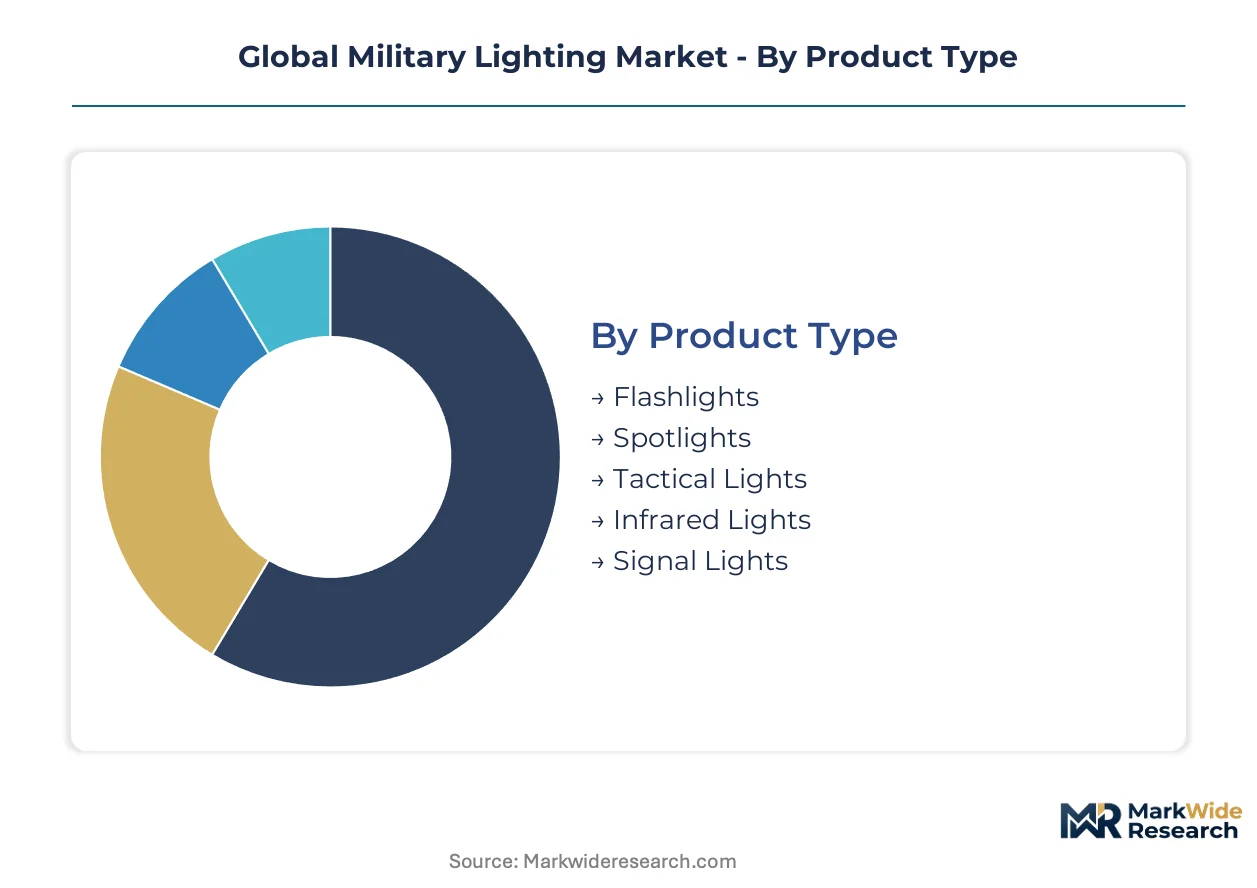
Military lighting procurement divides across technical specifications, operational contexts, and institutional buyers. Each segmentation axis reveals distinct certification requirements and procurement pathways that shape supplier competitive position.
Product Type:
Form factor determines environmental resilience specifications and platform integration complexity across ground, maritime, and airborne deployments.
- Flashlights:Handheld units engineered to MIL-STD-810H shock and immersion standards dominate individual soldier equipment programs. Demand concentrates in US Army modernization contracts where night vision goggle compatibility gates supplier qualification.
- Infrared Lights:Covert illumination systems with spectral output beyond visible wavelengths serve special operations signature management protocols. NATO special operations commands in Germany and France pull procurement volume as electromagnetic spectrum dominance doctrines tighten.
- Spotlights:High-intensity fixed-mount systems for vehicle and vessel perimeter illumination.
- Tactical Lights:Weapon-mounted systems with momentary activation interfaces for close-quarters combat.
- Signal Lights:Strobe and beacon systems for identification and distress signaling across coalition forces.
Mature deployment sits with flashlights. Newer deployment is concentrated in infrared lights.
Technology:
Light generation architecture determines thermal efficiency, spectral tunability, and electromagnetic compatibility profiles for contested operational environments.
- LED:Solid-state arrays with tunable spectral output and minimal thermal signature drive platform electrification retrofits. Bundeswehr vehicle contracts in Germany sustain specialist manufacturers with multi-year integration programs requiring EMI immunity certification.
- Fiber Optic:Illumination systems immune to electromagnetic interference command premium margins in submarine pressure hull and aircraft cockpit applications. Maritime patrol programs in France face extended recertification timelines under emerging EU adaptive system directives.
- OLED:Organic diode panels for flexible display-integrated lighting in next-generation helmet systems.
- Halogen:Legacy incandescent technology retained in cost-constrained platform sustainment contracts.
- Xenon:High-intensity discharge systems for searchlight applications requiring extended range illumination.
Volume concentration favors LED. Margin expansion is steepest in fiber optic.
Application:
Operational use case dictates spectral requirements, mobility constraints, and integration depth with platform command systems.
- Combat Operations:Dynamic illumination with real-time spectral adjustment for varying ambient conditions. US special operations vehicle integrators adopt adaptive LED arrays fastest, compressing supplier relationships to single-source firmware-compatible architectures.
- Surveillance:Covert observation systems requiring infrared and near-infrared output compatibility with sensor suites. German naval modernization programs generate sustained demand for pressure-hull qualified fiber optic assemblies.
- Navigation:Chart house and bridge illumination with preserved dark adaptation.
- Search & Rescue:High-output visible and strobe systems for extraction operations.
- Training Exercises:Spectrally tunable LED arrays for mock village and tunnel complex simulation.
Procurement velocity is highest for combat operations. Training infrastructure represents the civilian-military crossover segment with compressed cycles.
End User:
Institutional buyer type determines contract scale, specification authority, and compliance burden distribution across defense procurement frameworks.
- Armed Forces:National military services with platform-integrated procurement mandates and MIL-STD certification requirements. US Department of Defense environmental resilience standards accelerate LED retrofit programs across Army ground vehicle fleets.
- Defense Contractors:Prime integrators unbundling lighting subsystems from platform contracts, creating direct vendor relationships that compress price discovery cycles.
- Security Agencies:Domestic law enforcement and border control with simplified procurement pathways.
- Paramilitary Groups:State-affiliated forces operating under modified commercial acquisition frameworks.
- Peacekeeping Units:Multinational formations requiring NATO STANAG 4370 interoperability certification.
Specification authority concentrates with armed forces. Disintermediation momentum is strongest through defense contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement tax incentives in the United States accelerate LED retrofit concentration, while German Bundeswehr modernization contracts sustain specialist manufacturing clusters across Bavaria and Lower Saxony.
United States
Army ground vehicle modernization and special operations vehicle integrators drive volume demand for MIL-STD-810H certified LED systems. The Department of Defense enforces environmental resilience testing that eliminates incandescent suppliers lacking thermal shock protocols. Huntsville, Alabama anchors prime contractor lighting subsystem integration for ground combat platforms.
Germany
Bundeswehr armored vehicle retrofit contracts sustain multi-year platform integration programs requiring electromagnetic interference immunity certification. NATO STANAG 4370 climatic testing protocols standardize coalition interoperability requirements for German manufacturers. Bavaria hosts specialist LED manufacturers serving submarine pressure-hull and maritime patrol aircraft programs.
France
Maritime patrol aircraft programs generate sustained demand for fiber optic illumination systems in cockpit and command environments. The EU AI Act extends compliance burdens into autonomous vehicle adaptive lighting systems with algorithmic transparency requirements. Toulouse aerospace clusters face extended recertification timelines for intelligent beam pattern adjustment documentation.
United Kingdom
Naval platform electrification repositioning drives shipboard lighting retrofit procurement for submarine compartment applications. Ministry of Defence standardization agreements align with NATO interoperability frameworks for multi-spectral testing infrastructure. South West England maritime manufacturing clusters specialize in ruggedized LED assemblies for pressure hull environments.
Japan
Next-generation helmet system development creates demand for OLED-integrated flexible display lighting in defense applications. METI industrial policy supports domestic LED driver assembly production to reduce rare earth magnet supply dependencies. Nagoya aerospace manufacturing clusters develop fiber optic illumination for maritime self-defense force platforms.
Global Military Lighting Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense primes unbundling lighting subsystems from platform contracts to create direct vendor relationships. The vendor base concentrates around three strategic archetypes: aerospace heritage conglomerates with backward integration into fiber optic systems, specialist LED manufacturers with multi-year Bundeswehr integration experience, and ruggedized illumination fabricators serving submarine pressure-hull applications. Competitive moves center on certification infrastructure expansion to compress environmental qualification timelines, and firmware architecture standardization to capture single-source supplier relationships with special operations vehicle integrators.
Among aerospace heritage conglomerates, Honeywell International Inc. and Collins Aerospace exemplify the backward-integrated archetype with in-house fiber optic production capabilities. Oxley Group occupies a specialist position within the ruggedized LED segment, representing UK-based manufacturers with submarine compartment electrification expertise. These three companies anchor the competitive structure across the MIL-STD-3009 night vision compatibility and MIL-STD-810H environmental resilience certification vectors.
| Leading Market Players |
|---|
| Astronics Corporation |
| Honeywell International Inc. |
| Oxley Group |
| Collins Aerospace |
| Orion Energy Systems |
| Glamox |
| Dialight plc |
| Carmanah Technologies Corporation |
| Luminator Technology Group |
| Others |
Supply & Pricing Matrix
Neodymium and dysprosium processing costs in Chinese rare earth facilities cascade through LED driver assembly pricing tiers, with premium-certified MIL-STD-810H components commanding substantial markups over commercial-grade alternatives due to multi-standard testing infrastructure requirements.
Pricing Analysis
Short lead-time premiums for MIL-STD-3009 recertification compress procurement cycles for special operations vehicle integrators. Three-tier pricing structure across premium, standard, and economy levels separates fiber optic submarine assemblies from ground vehicle LED retrofits and commercial-grade security lighting. Cost compression in standard-tier LED retrofit programs intensifies as defense primes unbundle subsystem specifications and transfer integration risk downstream. Armed forces procurement offices exhibit lowest price sensitivity due to platform-integrated mandates, while security agencies face highest budget constraints.
Supply Chain Analysis
Freight costs for electromagnetic interference shielding materials from Germany and Japan amplify landed costs for North American defense contractors. Manufacturing concentrates in China for rare earth processing, Germany for precision LED assemblies, and the United Kingdom for submarine pressure-hull fiber optic systems. Raw material dependencies center on neodymium magnets, gallium nitride substrates, and borosilicate glass fiber. Single-source vulnerability in Chinese rare earth refining creates structural exposure. Distribution runs through defense prime contractor integration facilities with direct vendor relationships to subsystem specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military lighting sector sits in a technology-transition phase as solid-state LED arrays displace legacy incandescent architectures across NATO platform electrification programs.
For Market Incumbents: Deploy certification infrastructure expansion to compress environmental qualification timelines from eighteen-month cycles to nine-month gates. Incumbent defense primes must backward integrate into fiber optic production to defend margin pools in submarine compartment applications against aerospace heritage conglomerates. Threat from emerging specialist LED manufacturers with multi-year Bundeswehr integration experience demands firmware architecture standardization to lock in single-source supplier relationships.
For New Entrants and Emerging Players: Defense contractor procurement offices unbundling lighting subsystems from platform contracts represent the most penetrable channel partner type for subsystem specialists lacking prime contractor scale. White-space targets include urban warfare training infrastructure spectrally tunable LED arrays and EU AI Act-compliant adaptive lighting systems for autonomous ground vehicles. Go-to-market angle should emphasize electromagnetic interference immunity certification for maritime patrol aircraft programs in France and Germany.
For Investors and Strategic Acquirers: Accelerated NATO STANAG 4370 recertification timelines for coalition interoperability are the leading indicator that testing infrastructure assets will command strategic premiums. Long-term viability favors acquisition targets with captive multi-standard testing facilities and backward-compatible firmware architectures. Signal to watch is Department of Defense unbundling of lighting system specifications from platform prime contracts, which transfers integration risk and margin capture downstream.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Infrastructure Expansion | Compresses MIL-STD-810H and NATO STANAG 4370 qualification timelines to capture special operations procurement. |
| Firmware Architecture Standardization | Enables single-source supplier relationships with US Army ground vehicle modernization program integrators. |
| Backward Integration into Fiber Optic Production | Captures premium margins in submarine pressure-hull applications where Oxley Group currently dominates. |
| EU AI Act Compliance Pathway Development | Creates competitive moats in intelligent adaptive lighting for autonomous French and German military platforms. |
| Rare Earth Magnet Supply Diversification | Mitigates Chinese processing concentration risk for high-performance LED driver assemblies. |
Research Methodology
Independent corroboration across defense procurement officers, platform integration engineers, and subsystem manufacturing executives underwrites the qualitative findings. Primary interviews with MIL-STD certification specialists, Bundeswehr contract managers, and special operations vehicle program directors combined with secondary validation from NATO standardization agreement documentation, US Department of Defense environmental resilience test records, and EU AI Act regulatory filings. Bottom-up segment sizing and top-down macroeconomic anchoring triangulate volume estimates.
Historical reference periods spanning platform electrification retrofit cycles and night vision goggle compatibility standard transitions anchored the forecast window. Segmentation modeling across product type, technology architecture, operational application, and institutional buyer category generated granular outputs. CAGRs derived from weighted platform deployment schedules and defense budget authorization trajectories. Industry-specific inputs included rare earth magnet price volatility indices and electromagnetic spectrum dominance doctrine implementation timelines.
Caveats apply where NATO STANAG 4370 protocol revisions or EU AI Act enforcement intensity could materially shift the outlook. Forecasts reflect assumptions about defense modernization program continuity and coalition interoperability mandate adherence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
8K Technology Market
Others
Global Optical Comparator Market
Others
Pollen Allergy Market
Others
Molybdenum-99 Market
Others
Rope Market
Others
Technical Films Market
Others
Middle East 3D Printing Construction Market
Others
Global Tobacco Market
Others
Cloud Advertising Market
Others
Asia-Pacific Adtech Market
Others
Billet Market
Others
Italy Smart Home Market
Others
Europe Travel Retail Market
Others
Germany 3D Printing Construction Market
Others
Storage Dewars Market
Others
Europe Tablet PC Market