
 Fiberglass Storage Tanks Market | 2026-2036
Fiberglass Storage Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Storage Tanks Market Foresight
North American filament winding operations is recalibrating output schedules as resin supply chains stabilize post-volatility. Xerxes Corporation leverages its underground tank engineering heritage to dominate municipal water authority contracts across the Midwest. National Oilwell Varco anchors oilfield chemical containment demand through specialized corrosion-resistant designs for Permian Basin operators. LF Manufacturing competes on delivered-unit flexibility, offering on-site fabrication capabilities that reduce transport costs for remote agricultural buyers.
Fiberglass storage tanks are cylindrical vessels constructed from glass-fiber-reinforced thermoset resins, typically utilizing isophthalic or vinylester resin matrices with 5-15 mm wall thicknesses designed to resist chemical attack and structural fatigue. These tanks serve primarily to contain corrosive liquids, petroleum products, and process chemicals in environments where steel would degrade prematurely. Vertical tanks command the largest product type position due to their footprint efficiency and standardized foundation requirements in industrial facilities. Water treatment represents the fastest-expanding end user channel as municipalities replace aging concrete and steel infrastructure with zero-maintenance alternatives. Above ground installations retain the dominant installation share, though double-wall configurations are gaining specification preference where secondary containment regulations apply.
EPA underground storage tank regulations and NSF/ANSI 61 drinking water system standards shape product certification requirements and market access conditions for domestic manufacturers. OSHA workplace safety directives and DOT hazardous materials transport rules further constrain design parameters and fabrication protocols. ISO 9001 quality management and ASTM D3299 filament-wound vessel specifications provide the baseline compliance framework for export competitiveness. Stakeholders must monitor evolving state-level PFAS containment standards and resin raw material availability to align capacity investments with specification shifts.
Market Dynamics
EPA underground storage tank integrity mandates are forcing wholesale replacement of aging steel infrastructure across municipal water systems, creating sustained procurement pull for corrosion-resistant alternatives as utilities confront lead contamination liabilities and zero-leak performance requirements.
Growth Catalysts
- NSF/ANSI 61 Certification:Drinking water system standards now mandate fiberglass tank specifications for potable water containment, locking in material preference as municipalities modernize distribution infrastructure.
- Permian Basin Chemical Storage:Oilfield operators in West Texas and southeastern New Mexico require double-wall fiberglass containment for produced water and stimulation chemicals, generating specialized demand for high-pressure vessel designs.
- Vinylester Resin Formulations:Advanced corrosion-resistant matrices extend tank service life beyond 30 years in sulfuric acid and sodium hypochlorite environments, displacing concrete in wastewater treatment facilities.
Market Restraints
- Epoxy Resin Price Volatility:Petrochemical feedstock fluctuations and benzene derivative supply constraints create margin compression for filament winding operations dependent on thermoset raw materials.
- Filament Winding Equipment Concentration:German and Italian machinery suppliers control 70% of precision winding system manufacturing, exposing North American fabricators to extended lead times and currency risk.
- Concrete Tank Substitution:Pre-stressed concrete remains cost-competitive for above-ground municipal storage above 50,000 gallons, limiting fiberglass penetration in bulk water reservoir applications.
Strategic Opportunities
- PFAS Containment Standards:Emerging state-level regulations for per- and polyfluoroalkyl substance storage and treatment are creating specification demand for chemically inert tank systems in remediation applications.
- On-Site Fabrication Services:Remote agricultural and mining operations in the Mountain West require field-wound large-diameter tanks that eliminate transport dimensional constraints and reduce freight costs.
- IRA Water Infrastructure Funding:Federal appropriations for lead service line replacement and treatment plant upgrades are channeling capital toward zero-maintenance storage assets in disadvantaged communities.
Industry Challenges
- Composite Technician Shortage:Specialized filament winding and laminate fabrication skills require 18-24 month apprenticeship periods, constraining capacity expansion for regional manufacturers.
- ASTM D3299 Certification Timelines:Third-party vessel qualification testing for seismic and hydrostatic load ratings extends product development cycles by 4-6 months, delaying contract awards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Storage Tanks Market |
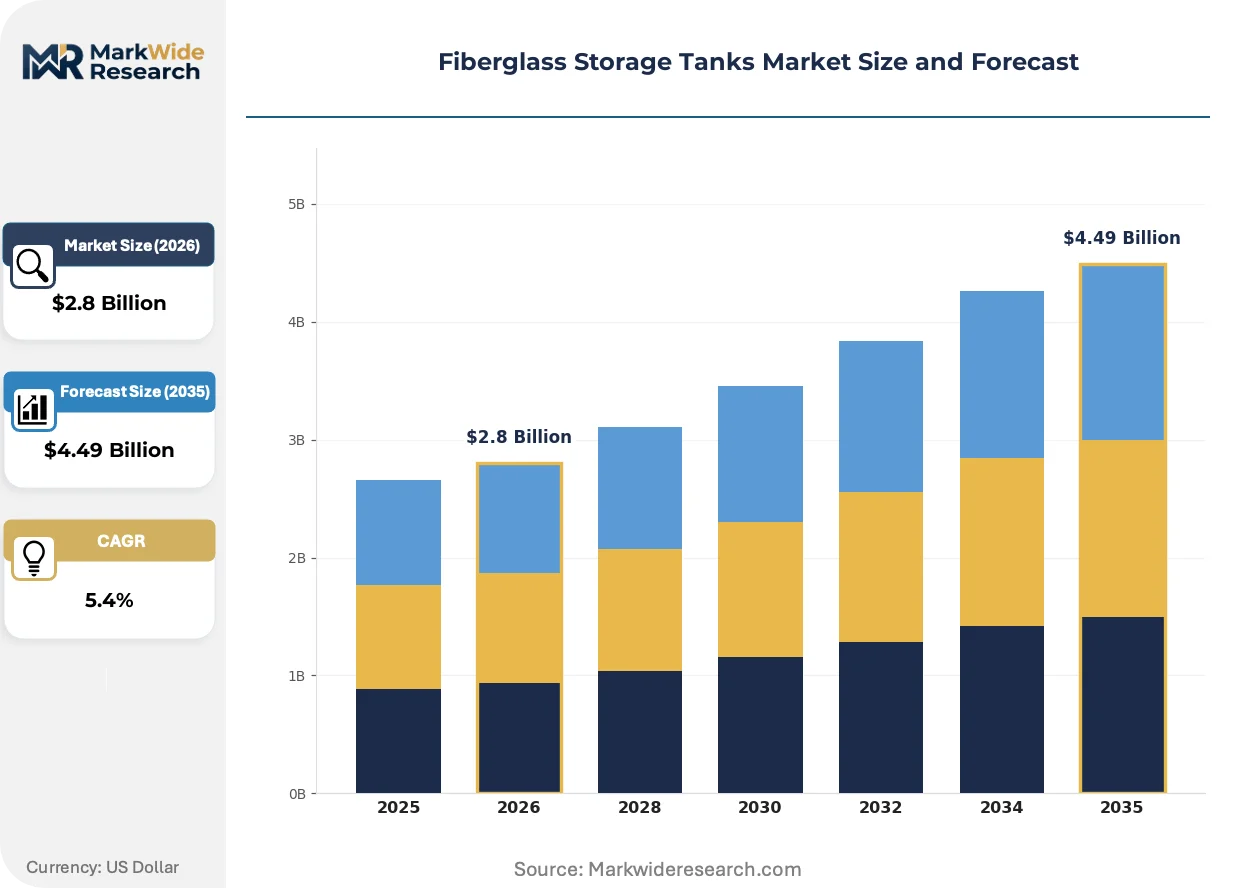
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Tanks, Horizontal Tanks, Double-Wall Tanks, Cone Bottom Tanks End User: Agriculture, Chemicals, Oil & Gas, Water Treatment Installation: Above Ground, Underground, On-site Fabricated, Delivered Units Application: Storage, Transport, Waste Management, Industrial Processes |
| Companies Covered | National Oilwell Varco, Xerxes Corporation, Design Tanks, KBK Industries, GSC Tank, Belding Tank Technologies, LF Manufacturing, Augusta Fiberglass, Granby Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Storage Tanks Market Shifts & Advancements
Digital design tools and automated manufacturing systems are compressing vessel development cycles while regulatory pressure on legacy materials accelerates specification migration toward engineered composites.
Automated robotic filament winding is rewriting production economics for large-diameter tanks. Municipal water authorities in California and Texas now specify robotically wound vessels for consistency-critical applications. The technology is compressing labor content per unit by half while enabling complex head geometries previously requiring hand layup.
REACH chemical authorization protocols in the European Union are restricting certain phthalic anhydride-based resin systems used in legacy tank manufacturing. German and French fabricators are reformulating with bio-based alternatives to maintain market access. The regulatory friction is accelerating R&D investment in sustainable thermoset chemistry across export-oriented North American producers.
Asset lifecycle contracting is displacing traditional capital purchase models for municipal buyers. Water treatment utilities in Florida and Arizona now procure storage capacity through 20-year service agreements bundling installation, inspection, and replacement. The shift transfers residual value risk to manufacturers while locking in recurring revenue streams for vertically integrated tank suppliers.
Fiberglass Storage Tanks Market Segmentation
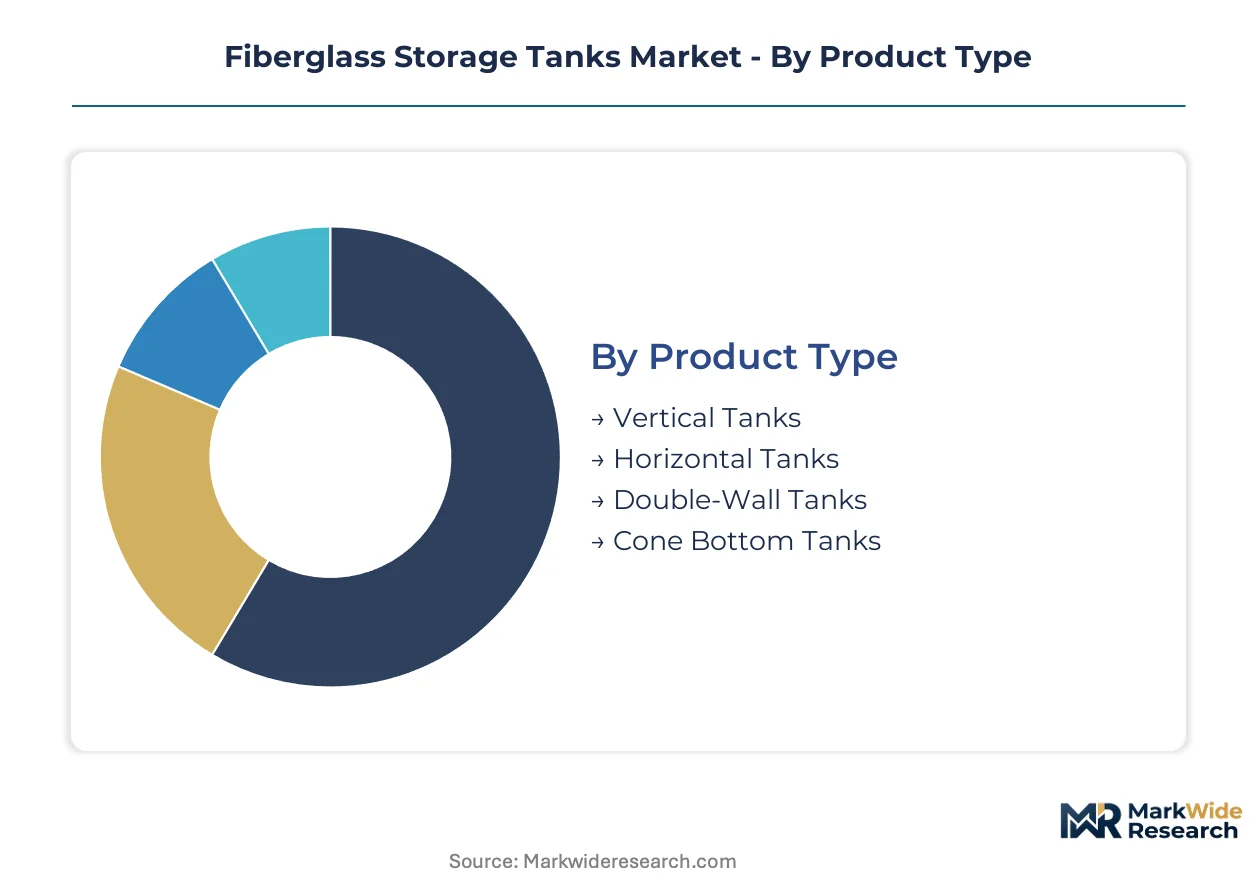
Segmentation in fiberglass storage tanks reveals how engineering specifications, regulatory environments, and customer operational constraints fragment demand across distinct procurement channels. Buyers prioritize corrosion resistance, footprint efficiency, or installation flexibility depending on their containment chemistry and site conditions.
Product Type:
Cost tier separates municipal buyers seeking standardized vertical vessels from oilfield operators demanding specialized double-wall configurations with secondary containment.
- Vertical Tanks:Cylindrical vessels with flat or dished heads maximize storage density per square foot of industrial pad space. Water treatment utilities in Texas and California specify these for footprint-constrained treatment plants where real estate premiums dominate site planning.
- Double-Wall Tanks:Nested vessel designs incorporate interstitial monitoring systems for leak detection compliance. EPA underground storage tank mandates are accelerating procurement for petroleum and chemical service in the Permian Basin where zero-discharge requirements apply.
- Horizontal Tanks:Low-profile configurations suit transport-mounted applications and space-restricted equipment yards. Chemical distributors favor these for tanker truck offloading stations.
- Cone Bottom Tanks:Tapered base geometries enable complete drainage of viscous or settling slurries. Agricultural fertilizer operations and mining leachate facilities specify these for solids-handling duty.
Vertical tanks lead volumes today; double-wall configurations are gaining share fastest.
End User:
Application maturity drives specification divergence — established water utilities demand NSF-certified longevity while emerging oilfield chemical containment prioritizes rapid deployment.
- Water Treatment:Potable water and wastewater facilities require NSF/ANSI 61 certified vessels with 30-plus year service life projections. Municipal infrastructure replacement programs across the United States are channeling capital toward zero-maintenance alternatives as lead contamination liabilities force system upgrades.
- Oil & Gas:Produced water, stimulation chemicals, and completion fluids demand corrosion-resistant containment in high-pressure environments. West Texas operators specify vinylester resin matrices for sulfuric acid and sodium hypochlorite exposure in Permian Basin extraction operations.
- Chemicals:Acid, caustic, and solvent storage applications favor isophthalic and vinylester formulations over concrete or steel. Process manufacturers prioritize vessel compatibility databases when specifying materials of construction.
- Agriculture:Remote fertilizer and pesticide storage drives demand for on-site fabrication capabilities that eliminate transport dimensional constraints. Mountain West farming cooperatives negotiate delivered-unit flexibility to reduce freight costs.
Water treatment leads volumes today; oil and gas is climbing the fastest as drilling activity intensifies.
Installation:
Supply chain configuration determines whether buyers accept factory delivery or require field-wound solutions for access-constrained sites.
- Above Ground:Standardized foundation requirements and crane-accessible placement dominate industrial facility planning. These installations retain the dominant share due to simplified inspection protocols and lower civil engineering costs.
- Underground:Buried configurations with cathodic protection elimination suit petroleum retail and environmental remediation sites. EPA leak prevention regulations are tightening material specifications for secondary containment applications.
- On-site Fabricated:Field-wound construction eliminates transport diameter limits for large-diameter agricultural and mining storage. LF Manufacturing and regional fabricators compete on delivered-unit flexibility for remote buyers.
- Delivered Units:Factory-complete vessels with quality-controlled laminate schedules suit standardized municipal and industrial procurement. Highway transport dimensional limits constrain maximum diameter for this channel.
Above ground installations lead volumes today; on-site fabricated solutions are expanding most quickly in remote resource extraction regions.
Application:
Volume scale and containment duration separate static storage demand from transport and waste handling applications with specialized regulatory burdens.
- Storage:Long-duration containment of process chemicals, petroleum products, and potable water represents the core value proposition. Industrial facilities and municipal utilities specify filament-wound vessels for corrosion resistance where steel degradation would trigger premature replacement.
- Waste Management:Hazardous and industrial wastewater containment requires chemically inert systems for PFAS remediation and leachate handling. Emerging state-level regulations for per- and polyfluoroalkyl substance storage are creating specification demand for specialized tank designs.
- Transport:DOT-regulated mobile containment for chemicals and petroleum products requires impact-resistant laminate schedules. Tanker-mounted horizontal configurations dominate this niche.
- Industrial Processes:Reaction vessels, surge tanks, and buffer storage integrate into continuous manufacturing flows. Chemical processors specify custom head geometries and nozzle configurations for process integration.
Storage applications lead volumes today; waste management is gaining share fastest as environmental remediation spending accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands procurement volumes for corrosion-resistant municipal storage, while Germany anchors European filament-winding capacity for chemical process applications. Demand trajectories diverge sharply between EPA-driven infrastructure replacement in North America and REACH-compliant resin reformulation pressures across European fabrication centers.
United States
Texas and California concentrate municipal water authority procurement as utilities confront lead contamination liabilities and zero-leak performance mandates. EPA underground storage tank integrity standards are tightening material specifications for secondary containment applications nationwide. The Permian Basin generates specialized demand for double-wall vessels among West Texas oilfield operators managing produced water and stimulation chemicals.
Germany
Chemical processors and automotive suppliers specify vinylester resin matrices for sulfuric acid containment and process integration. ECHA REACH authorization protocols are restricting phthalic anhydride-based resin systems, accelerating reformulation investment toward bio-based thermoset alternatives. Bavarian and North Rhine-Westphalian fabricators are recalibrating export-oriented production schedules to maintain market access under evolving chemical compliance frameworks.
China
Industrial wastewater treatment expansion and petrochemical infrastructure buildout drive specification demand for large-diameter vertical vessels. MIIT standards and GB certification requirements shape domestic procurement protocols for corrosion-resistant containment systems. Yangtze River Delta manufacturing clusters are scaling automated filament-winding capacity to serve process industries in Shanghai and Jiangsu provinces.
Canada
Municipal water systems in Ontario and Alberta are replacing aging concrete reservoirs with NSF-certified fiberglass alternatives for potable storage. Health Canada drinking water guidelines and PMMA environmental standards influence material selection for underground installations. Alberta oil sands operators require specialized containment for bitumen processing chemicals and tailings management applications.
India
Agricultural fertilizer distribution networks and pharmaceutical manufacturing expansion create procurement pull for chemical-resistant storage solutions. BIS certification requirements and state-level pollution control mandates are formalizing quality standards for thermoset vessel fabrication. Gujarat and Maharashtra industrial corridors are attracting regional manufacturing investment to serve domestic process industries and reduce import dependency.
Fiberglass Storage Tanks Market Competitive Landscape
North American producers anchor one tier; European specialists hold process-chemistry expertise in another. The vendor base organizes around three strategic archetypes: municipal water authority contractors with NSF certification depth, oilfield chemical containment specialists with pressure-vessel engineering heritage, and regional fabricators competing on delivered-unit flexibility for remote agricultural buyers. Consolidation pressure concentrates among municipal-channel incumbents, while capacity expansion dominates oilfield-facing operations and strategic partnerships link resin suppliers to filament-winding operations.
Among North American fabricators, Xerxes Corporation, National Oilwell Varco, and LF Manufacturing occupy distinct positioning vectors. Xerxes exemplifies the municipal-contractor archetype through underground tank engineering heritage. National Oilwell Varco represents oilfield-chemical specialization with corrosion-resistant design capabilities. LF Manufacturing sits within the regional-flexibility tier, offering on-site fabrication services that reduce transport costs for access-constrained buyers.
| Leading Market Players |
|---|
| National Oilwell Varco |
| Xerxes Corporation |
| Design Tanks |
| KBK Industries |
| GSC Tank |
| Belding Tank Technologies |
| LF Manufacturing |
| Augusta Fiberglass |
| Granby Industries |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up municipal contractors anchor supply discipline across the United States, concentrating filament-winding capacity in Texas and California while enforcing standardized pricing tiers for NSF-certified potable water storage. Their consolidated procurement leverage compresses margins for regional fabricators competing on delivered-unit flexibility, while resin feedstock volatility feeds through to double-wall vessel premiums in oilfield chemical applications.
Pricing Analysis
Capacity additions in Texas are reshaping price floors for standardized vertical tanks as automated robotic winding compresses labor content per unit. Three-tier pricing structure across premium NSF-certified, standard industrial-grade, and economy agricultural tiers separates municipal utilities from remote mining operations. Cost compression in the economy tier is intensifying because epoxy resin price volatility squeezes filament winding operations dependent on benzene derivatives. Agricultural cooperatives in the Mountain West exhibit the highest price sensitivity, while Permian Basin oilfield operators prioritize corrosion-resistant vinylester formulations over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from municipal water authorities mandate multi-supplier qualification for NSF/ANSI 61 certified vessels, fragmenting procurement across Xerxes Corporation, LF Manufacturing, and regional fabricators. Raw material supply draws from German and Italian precision winding equipment manufacturers, domestic epoxy and vinylester resin compounders, and glass fiber roving producers. Single-source vulnerability concentrates in filament winding machinery where European suppliers control seventy percent of precision system manufacturing. Distribution runs through direct municipal contracting for large-diameter vertical tanks and specialized oilfield channel partners for Permian Basin chemical containment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA underground storage tank integrity mandates create sustained replacement demand for aging steel infrastructure across municipal water systems.
For Market Incumbents: Lock in municipal water authority relationships through NSF/ANSI 61 certification depth and 20-year service agreement bundling that transfers residual value risk from utilities. Defend against concrete tank substitution in bulk storage above 50,000 gallons by emphasizing zero-maintenance lifecycle economics. Prioritize backward integration into vinylester resin compounding to secure margin control against petrochemical feedstock volatility. For New Entrants and Emerging Players: Begin with on-site fabrication capabilities for remote agricultural and mining operations in the Mountain West where transport dimensional constraints eliminate factory-delivered competition. Target PFAS containment remediation applications where emerging state-level regulations create specification demand for chemically inert tank systems. Pursue field-wound construction partnerships with regional distributors to bypass highway transport limits for large-diameter vessels. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fabricators competing on delivered-unit flexibility without municipal certification depth or oilfield pressure-vessel engineering heritage. The five-to-ten year viability window favors vertically integrated suppliers controlling resin formulation through filament winding. Monitor IRA water infrastructure funding disbursement velocity as the inflection signal for capital deployment into zero-maintenance storage assets in disadvantaged communities.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Filament Winding Scale-Up | California and Texas municipal authorities now specify robotically wound vessels for consistency-critical potable water applications. |
| Vinylester Resin Backward Integration | Captive supply of corrosion-resistant matrices insulates margins from benzene derivative feedstock volatility in chemical containment. |
| NSF/ANSI 61 Certification Investment | Drinking water system standards lock in material preference as utilities modernize distribution infrastructure nationwide. |
| On-Site Fabrication Capability Expansion | Field-wound construction eliminates transport diameter limits for remote agricultural buyers in access-constrained Mountain West regions. |
| PFAS Containment System Development | Emerging state-level regulations for per- and polyfluoroalkyl substance storage create specification demand in remediation applications. |
Research Methodology
Bottom-up water treatment utility modeling reconciled against top-down filament winding capacity tracking forms the analytical core of this study. Primary interviews with municipal procurement officers, oilfield chemical containment engineers, composite fabrication plant managers, and resin supplier technical directors combined with secondary validation from EPA regulatory filings, NSF certification databases, ASTM standards documentation, and customs trade data. Triangulation across stakeholder inputs and documentary sources ensures segment-level accuracy for corrosion-resistant vessel demand.
Historical trendline analysis of municipal infrastructure replacement cycles and oilfield drilling activity patterns informed the projection framework across the analysis window. Segmentation dimensions modeled include product type configuration, end-use industry vertical, installation methodology, and regional regulatory cluster. CAGRs were derived from regression analysis of replacement demand drivers and capacity expansion announcements. Industry-specific forecast inputs incorporate EPA underground storage tank enforcement timelines and IRA water infrastructure appropriation trajectories.
Several conditions sit outside the modeled scope, including unforeseen resin raw material supply disruptions, accelerated concrete tank substitution in bulk storage applications, and geopolitical friction affecting German and Italian winding equipment imports. Forecasts reflect assumptions about regulatory enforcement continuity and municipal capital budget stability. Deviation in EPA underground storage tank integrity mandate implementation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
DIY Smart Home Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Software Synthesizers Market
Others
Latin America Domestic CEP Market
Others
Floor Cleaning and Mopping Machine Market
Others
Safety Critical Software Testing Market
Others
Fluid Bed Systems Market
Others
Interference Mitigation Filters Market
Others
Sports Events Market
Others
Asia-Pacific Professional Scalp Treatment Products Market
Others
Cremation Furnace Market
Others
India 3D Printing Construction Market
Others
Surface Green Mining Market
Others
Mobile MRI Services Market
Others
Small Office Home Office (SOHO) Servers Market
Others
Nanomedicine for Drug Delivery Market