
 Transportation Lighting Market | 2026-2036
Transportation Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Lighting Market Analytics
Software-defined lighting subscriptions is repositioning how transportation OEMs monetize exterior illumination systems. Cree Lighting leverages its SiC substrate expertise to sustain high-lumen-density LED architectures for electric vehicle headlamp modules. Signify NV anchors its mobility division through digital services that extend beyond hardware sales into predictive maintenance contracts for rail and aviation operators.
Transportation lighting encompasses engineered luminaire assemblies designed to provide visibility, signaling, and aesthetic illumination across vehicles operating on road, rail, water, and air; these systems integrate semiconductor emitters, thermal management substrates, and polycarbonate or glass optics rated for vibration, moisture, and thermal cycling between minus forty and eighty-five degrees Celsius. The LED product category dominates value contribution due to its efficacy advantage and regulatory tailwinds phasing out halogen across EU and North American type-approval frameworks. Adaptive lighting technology captures premium positioning as camera fusion and matrix beam control migrate from luxury automotive into commercial fleet and rail applications.
The US National Highway Traffic Safety Administration enforces FMVSS 108 photometric requirements that dictate minimum and maximum luminous intensity for headlamps, brake lamps, and turn signals, while the United Nations Economic Commission for Europe administers ECE regulations that harmonize type-approval testing across signatory markets including Germany, France, and Italy. China's Ministry of Industry and Information Technology issues GB standards that mandate domestic certification for LED modules used in public transport and commercial vehicle applications. Stakeholders must monitor how cybersecurity provisions in emerging automotive lighting software update protocols reshape supplier qualification criteria and aftermarket access permissions.
Market Dynamics
Software-defined lighting architectures are compressing hardware replacement cycles as transportation OEMs monetize illumination through over-the-air update subscriptions rather than discrete component sales.
Growth Catalysts
- ECE R48 Harmonization:European type-approval standards for photometric performance and durability accelerate LED retrofits across commercial fleets operating cross-border routes.
- Heavy-Duty Electrification:Battery-electric truck platforms demand thermal-optimized headlamp modules that reduce auxiliary power draw and extend range.
- Silicon Carbide Substrates:SiC thermal management materials enable lumen-density thresholds that halogen architectures cannot achieve, forcing technology turnover.
Market Restraints
- Polycarbonate Resin Volatility:Optical-grade polymer feedstock prices fluctuate with petrochemical capacity, squeezing margin on high-volume lamp housing production.
- German Supplier Concentration:Tier-one engineering centers cluster around Stuttgart and Munich, creating single-source risk for matrix-beam control module procurement.
- Halogen Aftermarket Persistence:Low-cost replacement bulbs retain share in aging vehicle parcs across Eastern European and Southeast Asian markets.
Strategic Opportunities
- Rail Predictive Maintenance:Digital lighting service contracts for rolling stock operators bundle sensor diagnostics with luminaire replacement schedules.
- Aviation Exterior LED:Runway taxi and anti-collision systems present untapped retrofit volume as airports decarbonize ground operations.
- China GB Standard Alignment:Domestic certification mandates for LED modules in public transport create captive demand for locally manufactured optics.
Industry Challenges
- Embedded Software Talent Scarcity:Functional safety engineering for ISO 26262-compliant lighting control systems outpaces vocational training pipeline output.
- Homologation Timeline Compression:Parallel FMVSS 108 and ECE R48 testing cycles extend product launch windows for multi-market vehicle programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Lighting Market |
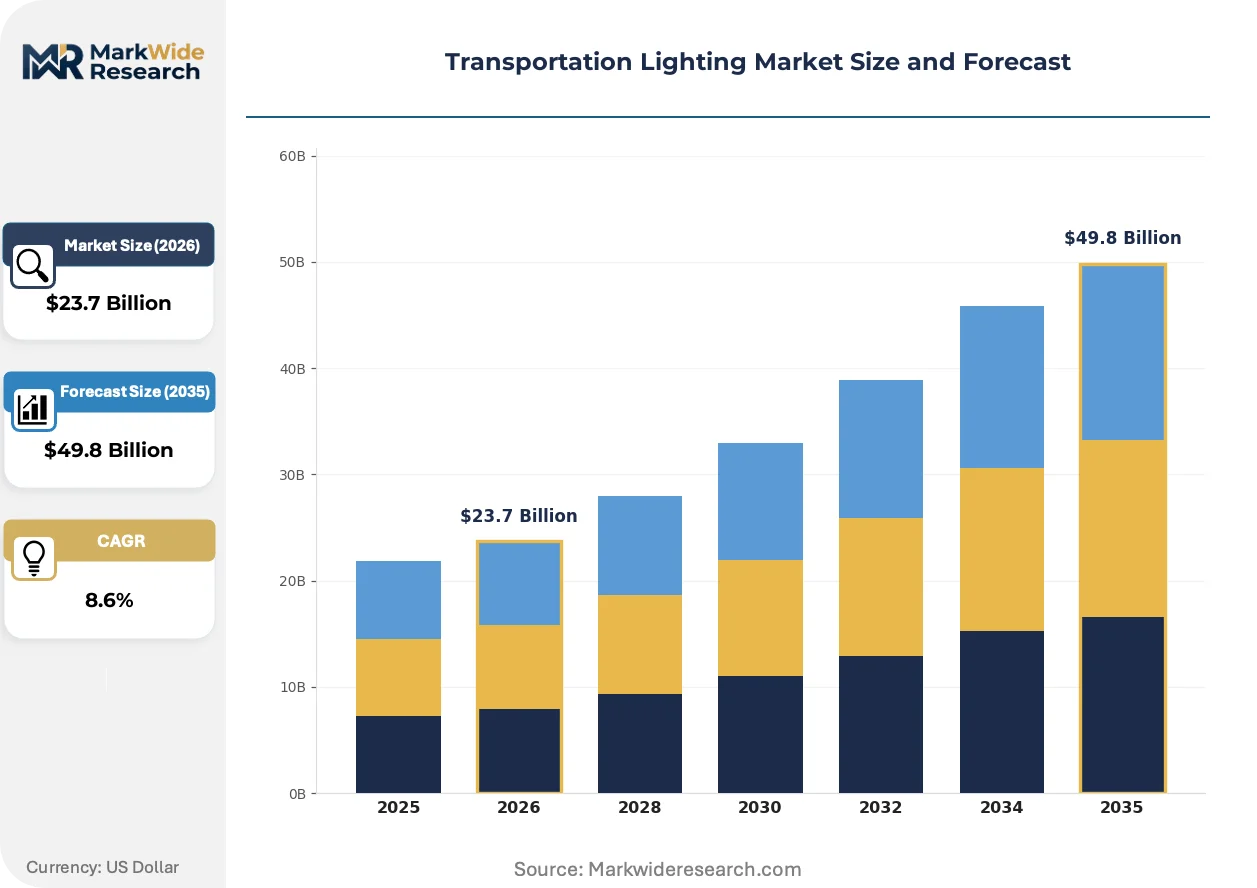
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Neon Application: Automotive, Aviation, Marine, Rail Technology: Adaptive Lighting, Daytime Running Lights, Directional Lighting, Ambient Lighting End User: OEMs, Aftermarket Providers, Fleet Operators, Public Transport Authorities |
| Companies Covered | Cree Lighting, Eaton Corporation, Signify NV, Daktronics Inc., Luminator Technology Group, Acuity Brands Inc., Hubbell Incorporated, GE Current, OSRAM GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Lighting Market Evolving Landscape
Active matrix beam control is migrating from premium automotive into commercial applications, reshaping supplier R&D allocation and tier-one engineering service contracts.
Micro-LED pixel arrays are expanding into adaptive driving beam modules. Commercial fleet operators in long-haul trucking adopt these systems to reduce glare-related incidents on unlit highways. The technology is expanding into mid-range vehicle segments previously served by static projector designs.
FMVSS 108 photometric enforcement has tightened through NHTSA's expanded type-approval audit sampling. Non-compliant headlamp imports face detention at US ports, forcing offshore manufacturers to establish domestic testing partnerships. Aftermarket distributors now demand factory-certified documentation before stocking LED conversion kits.
Fleet procurement teams are unbundling lighting hardware from vehicle purchase agreements. Operators in Germany and the United States negotiate separate service contracts covering predictive replacement and software update entitlements. This purchasing pattern concentrates volume with suppliers offering integrated digital platforms rather than component catalogs.
Transportation Lighting Market Segmentation
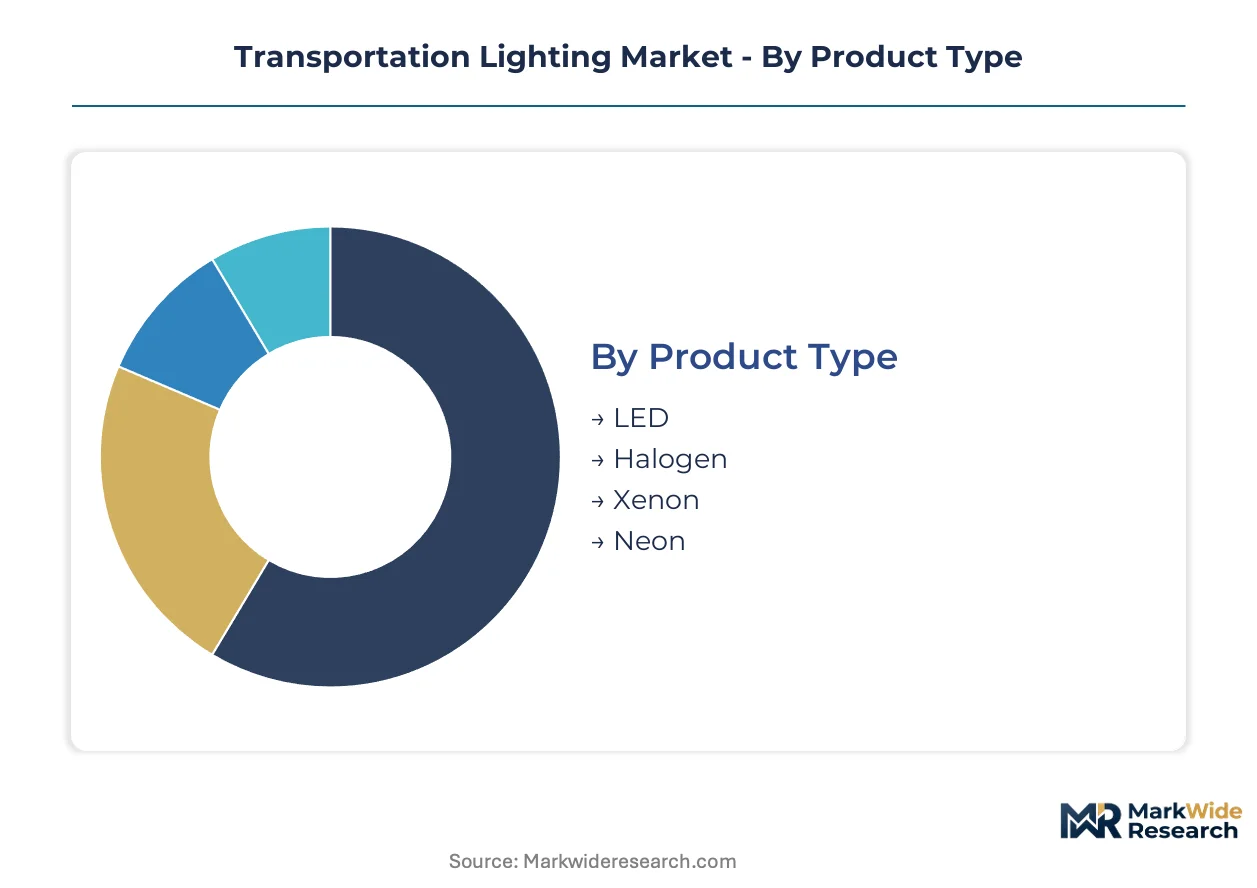
Transportation lighting procurement patterns diverge sharply across technology generations and operational environments. Upgrade cycles for heavy-duty fleets and regulatory phase-outs of legacy lamp architectures reshape how suppliers allocate engineering resources across segment boundaries.
Product Type:
Replacement-cycle timing varies dramatically by emitter technology, with thermal management requirements and lumen-density thresholds driving differential upgrade economics across vehicle platforms.
- LED:Semiconductor emitters mounted on aluminum nitride or silicon carbide substrates deliver luminous efficacy exceeding 150 lumens per watt. Heavy-duty truck fleets in Germany and the United States concentrate procurement here, compelled by ECE R48 durability mandates and FMVSS 108 photometric enforcement that halogen cannot satisfy.
- Halogen:Tungsten-filament lamps with halogen regenerative cycle maintain residual share in aging vehicle parcs and developing markets where type-approval enforcement remains uneven. Eastern European aftermarket distributors still stock replacement inventories, though OEM fitment collapses toward zero.
- Xenon:High-intensity discharge arc lamps produce 3,000-lumen outputs from 35-watt draw, retaining niche positioning in premium automotive retrofit segments where matrix-beam compatibility justifies continued production.
- Neon:Cold-cathode fluorescent assemblies persist in marine and aviation accent lighting applications where color uniformity and shock resistance outweigh efficiency considerations.
LED sits at the top of the volume ranking, with halogen replacement demand climbing the fastest in regulatory lag markets.
Application:
Operational duty cycles and environmental exposure levels determine specification stringency, with aviation and marine applications imposing the most severe thermal cycling and moisture ingress requirements.
- Automotive:Passenger and commercial vehicle platforms absorb the majority of LED module production, with German OEMs and Chinese domestic manufacturers driving matrix-beam adoption into mid-range segments.
- Aviation:Anti-collision beacons, landing lights, and taxiway illumination systems must survive vibration spectra from turbofan harmonics and bird-strike impacts. Airport decarbonization programs in the United States and France accelerate LED retrofit timelines.
- Marine:Navigation lights and deck illumination face salt-fog corrosion and submersion pressure testing under IEC 60598-2-1 marine luminaire standards. Commercial shipping operators prioritize sealed optical assemblies for reduced maintenance intervals.
- Rail:Rolling stock exterior lighting and platform luminaires integrate with predictive maintenance platforms. European operators bundle sensor diagnostics with replacement schedules under long-term service contracts.
Automotive commands the dominant revenue share, while rail digital service contracts expand most quickly as operators unbundle hardware from vehicle procurement.
Technology:
Software-defined functionality is compressing hardware lifecycles, with camera fusion and dynamic beam control migrating from premium positioning into fleet-standard specifications.
- Adaptive Lighting:Matrix LED arrays with pixel-level dimming respond to oncoming vehicle detection, reducing glare incidents on unlit highways. Long-haul trucking fleets in the United States adopt these systems for insurance premium reductions.
- Daytime Running Lights:Low-power LED strips or dedicated lamps improve conspicuity without headlamp filament wear. EU regulatory mandates since 2011 institutionalized fitment across all new passenger vehicles.
- Directional Lighting:Turn signal and cornering lamp modules integrate with steering angle sensors. Commercial vehicle platforms specify these for urban delivery safety compliance.
- Ambient Lighting:Interior cabin illumination with programmable color temperature enhances perceived quality in premium automotive segments. Chinese OEMs differentiate through customizable dashboard and footwell schemes.
Daytime running lights hold the widest installed base, though adaptive lighting gains share fastest as camera costs decline.
End User:
Procurement authority structures determine contract terms, with fleet operators and public transport authorities increasingly demanding performance-based service agreements over component transactions.
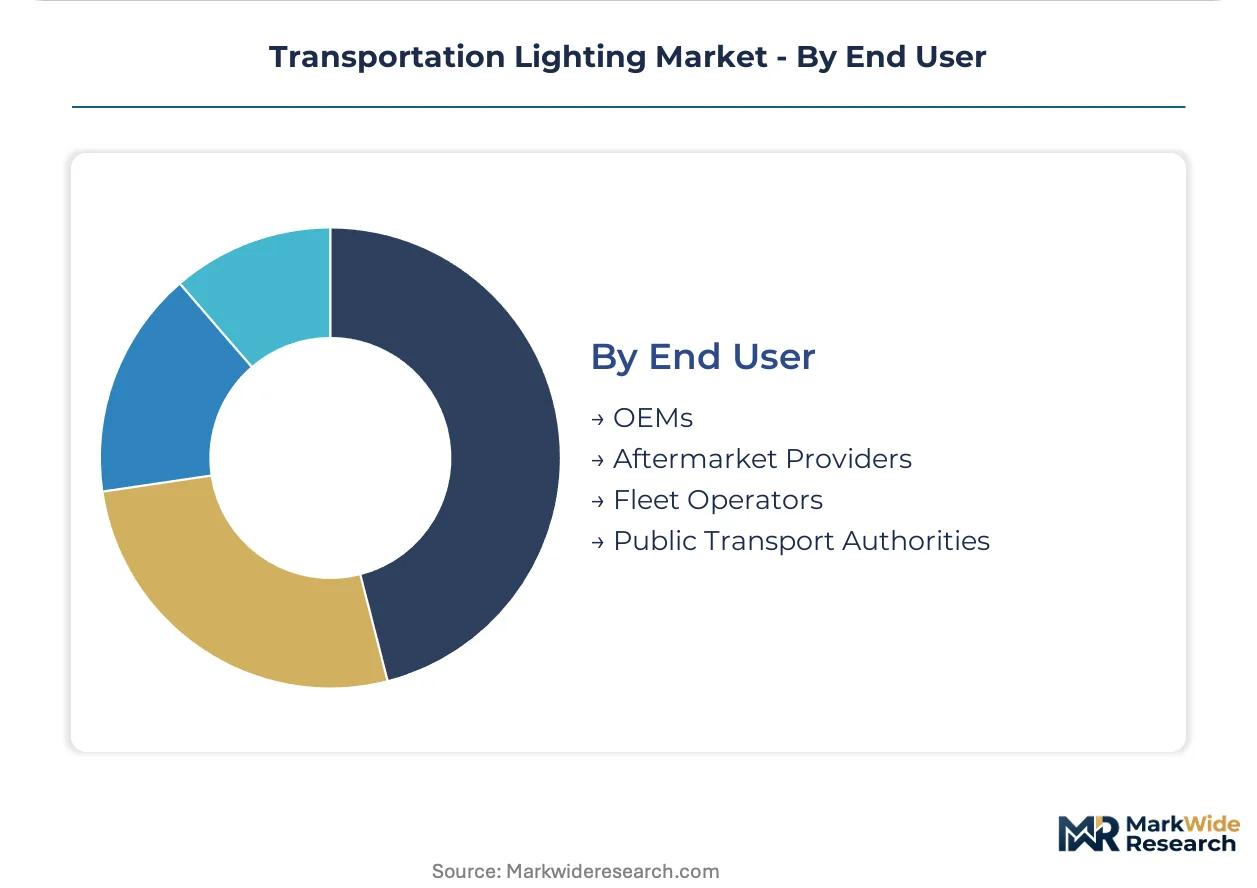
- OEMs:Vehicle manufacturers specify lighting modules during platform development, locking in suppliers for production runs spanning 5-7 years. German and Chinese engineering centers concentrate tier-one supplier relationships.
- Aftermarket Providers:Independent distributors and repair chains source replacement lamps and conversion kits. NHTSA port detention of non-compliant LED imports reshapes sourcing toward factory-certified documentation.
- Fleet Operators:Commercial trucking and bus companies negotiate separate lighting service contracts covering predictive replacement and software updates. This purchasing pattern concentrates volume with integrated digital platform suppliers.
- Public Transport Authorities:Municipal and regional transit agencies procure rail and bus lighting under multi-year maintenance agreements. China's GB standards mandate domestic certification for LED modules in these applications.
OEMs retain the largest direct procurement volume, with fleet operators restructuring purchasing fastest toward outcome-based contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates more tier-one lighting engineering centers than any other country, while China's domestic certification mandates create captive demand corridors that foreign suppliers cannot easily penetrate.
United States
Commercial fleet operators in long-haul trucking dominate LED procurement, driven by insurance premium reductions for adaptive beam systems. NHTSA enforces FMVSS 108 photometric requirements through expanded port detention of non-compliant imports. Detroit and the Midwest manufacturing corridor host dense concentrations of automotive OEM engineering centers that lock in supplier relationships.
Germany
Heavy-duty truck and bus fleets accelerate LED retrofits under ECE R48 harmonization for cross-border routes. The KBA administers type-approval testing that accelerates technology turnover from halogen architectures. Stuttgart and Munich clusters concentrate matrix-beam control module procurement, creating single-source dependencies for tier-one suppliers.
China
Public transport authorities mandate domestic LED module certification under MIIT-issued GB standards for buses and rail applications. The Yangtze River Delta and Pearl River Delta regions concentrate manufacturing of optical-grade polycarbonate housings and aluminum nitride substrates for export markets.
Japan
Automotive OEMs integrate adaptive lighting into mid-range vehicle segments as camera fusion costs decline. METI coordinates industrial standards that align with ECE frameworks for export compatibility. The Nagoya-Chubu corridor sustains precision optics manufacturing for headlamp projector modules.
France
Airport decarbonization programs accelerate LED retrofit timelines for runway taxi and anti-collision systems. ECE regulations administered through national type-approval bodies harmonize testing with German and Italian markets. The Paris-Saclay cluster hosts aviation lighting engineering centers serving Airbus supply chains.
Transportation Lighting Market Competitive Landscape
Top-tier vendors anchor OEM supply relationships through multi-year platform lock-ins, while mid-tier specialists compete on aftermarket conversion kits and fleet service contracts. The vendor base stratifies across three archetypes: semiconductor substrate specialists, integrated digital platform providers, and legacy lamp manufacturers pivoting toward LED modules. M&A activity concentrates on predictive maintenance software capabilities, while capacity expansion targets silicon carbide thermal management substrate production.
Within the integrated digital platform tier, Signify NV and Acuity Brands Inc. exemplify suppliers bundling hardware with predictive maintenance contracts. Cree Lighting occupies a position among semiconductor substrate specialists leveraging silicon carbide expertise. OSRAM GmbH anchors the legacy-transition archetype through European engineering center concentration.
| Leading Market Players |
|---|
| Cree Lighting |
| Eaton Corporation |
| Signify NV |
| Daktronics Inc. |
| Luminator Technology Group |
| Acuity Brands Inc. |
| Hubbell Incorporated |
| GE Current |
| OSRAM GmbH |
| Others |
Value Network & Pricing Analysis
Fleet procurement teams unbundling lighting hardware from vehicle purchase agreements are forcing suppliers toward subscription-based service contracts that compress upfront component margins while extending revenue duration.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for LED module assemblies. Three-tier pricing structure across premium adaptive-beam systems, standard LED retrofits, and economy halogen replacements dominates contract negotiations. Certification tier under ECE R48 and FMVSS 108 creates price differentiation between type-approved OEM modules and uncertified aftermarket imports. Price erosion runs through halogen replacement inventories as regulatory phase-outs accelerate. Aftermarket distributors exhibit highest price sensitivity; fleet operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Functional safety engineering talent scarcity in Stuttgart and Munich constrains matrix-beam control module output. Manufacturing concentrates in Germany, China, and the United States for tier-one optical assemblies. Silicon carbide substrates, aluminum nitride thermal management materials, and optical-grade polycarbonate resins constitute critical input dependencies. Single-source vulnerability concentrates around German engineering centers for adaptive lighting software. Distribution runs through OEM direct procurement channels, aftermarket distributor networks, and integrated digital platform providers serving fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transportation lighting procurement arbitrage exists between European ECE R48 enforcement accelerating premium LED adoption and Southeast Asian markets where halogen aftermarket persistence sustains lower-cost supply corridors.
For Market Incumbents: Anchor OEM platform lock-ins through multi-year engineering service contracts covering predictive maintenance and over-the-air software updates. Deepen backward integration into silicon carbide substrate production to defend margin position against semiconductor supply volatility. Expand certification investment for China's GB standards to preempt domestic competitor capture of public transport authority contracts. For New Entrants and Emerging Players: Capture aviation exterior LED retrofit volume as airport decarbonization programs in France and the United States accelerate runway taxi and anti-collision system replacement timelines. Rail predictive maintenance service contracts present the most penetrable white-space as European operators unbundle hardware from rolling stock procurement. Pursue direct partnerships with fleet procurement teams rather than aftermarket distributor channels to bypass incumbent OEM relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with predictive maintenance software specialists bundling sensor diagnostics with luminaire replacement schedules. Long-term viability favors integrated digital platform providers over component-only manufacturers as software-defined lighting architectures compress hardware replacement cycles. Monitor NHTSA port detention enforcement intensity as inflection indicator for aftermarket import compliance costs and domestic testing partnership valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Rail operators in Germany bundle sensor diagnostics with replacement schedules under long-term service agreements. |
| Silicon Carbide Substrate Capacity Expansion | Cree Lighting leverages SiC expertise to sustain high-lumen-density LED architectures for electric vehicle headlamp modules. |
| Aviation LED Retrofit Certification | Airport decarbonization programs in France accelerate runway taxi and anti-collision system replacement timelines. |
| China GB Standard Compliance Investment | MIIT-issued domestic certification mandates create captive demand corridors for locally manufactured LED modules. |
| Software-Defined Lighting Subscription Launch | Signify NV anchors mobility division through digital services extending beyond hardware into predictive maintenance contracts. |
Research Methodology
Direct dialogue with OEM platform engineers, tier-one supplier procurement leads, fleet operations directors, aftermarket distributor category managers, and regulatory affairs specialists at NHTSA and KBA grounded qualitative assessment. Secondary validation drew from ECE R48 type-approval databases, FMVSS 108 photometric enforcement records, vehicle production registries, and customs trade data for optical-grade polymer feedstocks. Bottom-up segment sizing triangulated against top-down market aggregation across emitter technology, application environment, and end-user procurement authority.
Bottom-up modeling traced LED, halogen, xenon, and neon module shipments through vehicle fitment rates and replacement cycle assumptions across the projection horizon. Segmentation dimensions spanned product type, application, technology generation, and end-user procurement structure. CAGRs derived from regression analysis of historical technology turnover patterns and regulatory phase-out schedules. Industry-specific inputs incorporated ECE R48 harmonization timelines, heavy-duty electrification adoption curves, and silicon carbide substrate cost reduction trajectories.
Underlying measurement precision varies by segment; LED product category and automotive application carry tighter precision than halogen aftermarket and marine niche applications due to data availability. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and fleet procurement pattern shifts. Practitioners should monitor NHTSA port detention sampling expansion, German KBA type-approval acceleration, and China MIIT domestic certification mandate enforcement for early signals of supply chain reconfiguration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Molecular Spectroscopy Market
Others
Cellular-Connected Laptops Market
Others
Corn Fiber Market
Others
Global Injectable Nanomedicine Market
Others
5G Tester Market
Others
Europe Smart Homes Market
Others
Industrial Gauges Market
Others
PCB Laminate Market
Others
Bimodal Identity Management Solutions Market
Others
South America Automotive LED Lighting Market
Others
Server Market
Others
Deflectometer Market
Others
Coalescing Filter Market
Others
Short Video Applications Market
Others
Cloud DVR Market
Others
Duty Free Retail Market