
 Middle East & Africa Air Insulated Switchgear Market | 2026-2036
Middle East & Africa Air Insulated Switchgear Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East & Africa Air Insulated Switchgear Market Insights
Multi-sourcing from regional fabrication hubs is restructuring procurement patterns across the Middle East & Africa air insulated switchgear landscape. Schneider Electric SE anchors its position through localized production partnerships in the Gulf. ABB Ltd. competes on medium-voltage portfolio breadth for utility substations. Siemens AG leverages engineering depth to dominate transformer station installations across North African markets.
Air insulated switchgear employs atmospheric air as the dielectric medium within metal-enclosed assemblies rated from 12 kV through 36 kV, with busbar systems and circuit breakers arranged for direct visibility and maintenance access. The equipment serves primary distribution networks where operational simplicity and environmental tolerance outweigh gas-insulated compactness requirements. Medium voltage configurations occupy the dominant revenue position due to pervasive utility retrofit cycles across aging grids. Renewable energy end-use represents the fastest-expanding segment as wind and solar farms require switchgear compatible with intermittent load profiles and desert climate extremes. Vacuum interruption technology within air-insulated frames captures widening preference as operators seek SF6-free alternatives without sacrificing breaking capacity.
Saudi Arabia's Saudi Standards, Metrology and Quality Organization and South Africa's National Regulator for Compulsory Specifications enforce dielectric withstand and short-circuit certification thresholds that filter import eligibility. The EU F-Gas Regulation's extraterritorial influence on multinational EPC contractors accelerates air-insulated specification for Gulf power projects. Stakeholders must monitor how Gulf Cooperation Council grid codes evolve to accommodate distributed generation interconnection standards.
Market Dynamics
The EU F-Gas Regulation's extraterritorial pressure on multinational EPC contractors is redirecting specification toward air-insulated alternatives across Gulf power projects, compressing the competitive window for SF6-dependent suppliers.
Growth Catalysts
- Grid modernization mandates:Saudi Arabia and the UAE are executing substation buildouts that specify medium-voltage air insulated switchgear for utility-scale renewable integration.
- Saudi Standards, Metrology and Quality Organization certification:Dielectric withstand and short-circuit thresholds filter import eligibility, creating captive demand for compliant regional fabrication.
- Vacuum interruption technology:SF6-free breaking capacity without gas-insulated compactness trade-offs captures widening operator preference in desert climate extremes.
Market Restraints
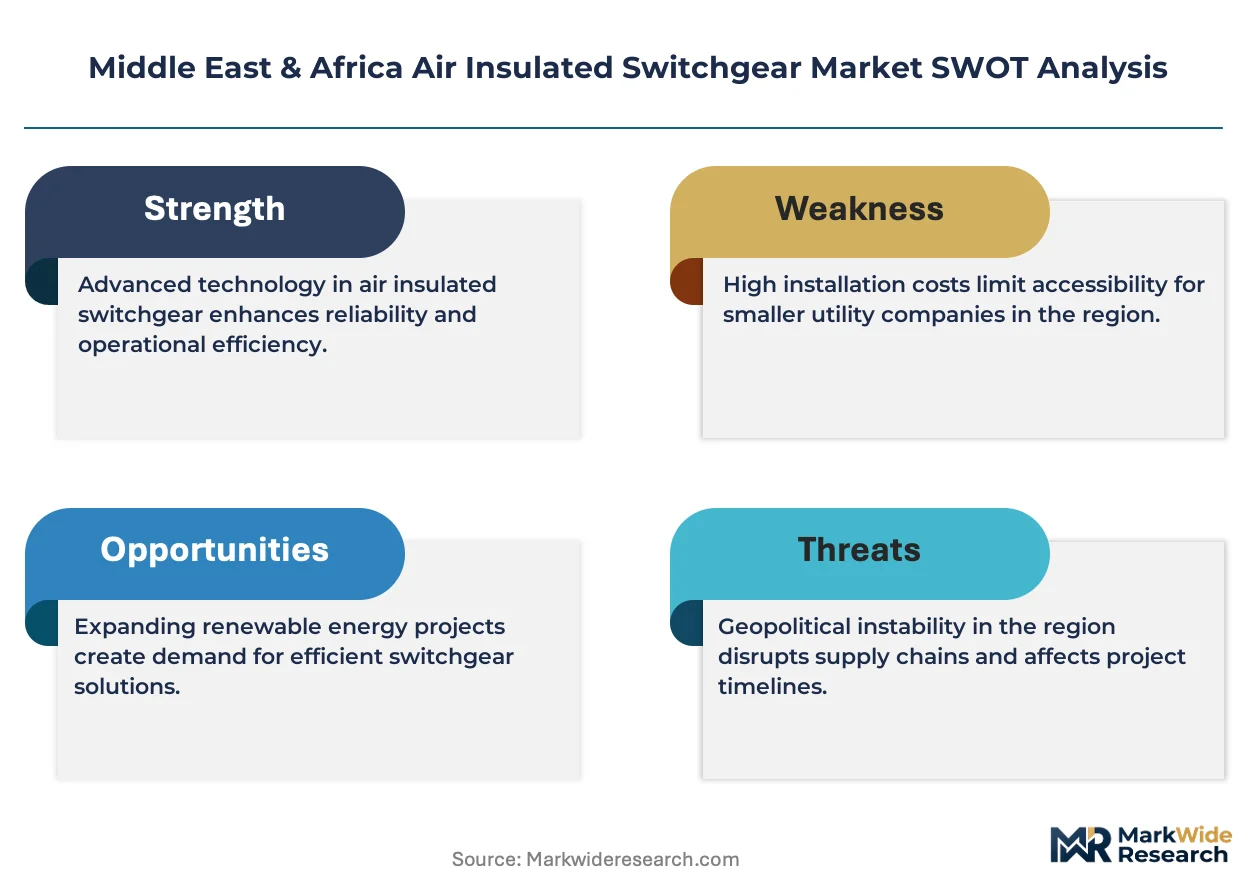
- Copper and aluminum price volatility:Busbar systems constitute substantial material cost exposure for air insulated switchgear fabricators.
- Supply concentration in European component sourcing:Vacuum interrupter manufacturing clusters in Germany and Italy create import dependency for regional assembly hubs.
- Footprint inefficiency versus GIS:Air insulated switchgear requires substantially larger substation real estate in dense urban environments like Dubai and Riyadh.
Strategic Opportunities
- South Africa's renewable auction pipeline:Distributed solar and wind farm interconnection standards are underdeveloped, creating first-mover specification influence.
- Egypt's Suez Canal Economic Zone:Industrial zone electrification projects lack committed switchgear suppliers, opening procurement relationships.
- Digital twin integration:Convergence of asset monitoring sensors with air insulated switchgear maintenance protocols enables predictive service contracts.
Industry Challenges
- Vacuum interrupter testing technician shortage:Gulf Cooperation Council labor markets lack certified personnel for dielectric validation protocols.
- Legacy oil-immersed switchgear replacement sequencing:Utility budget cycles compress upgrade timelines against operational continuity requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East & Africa Air Insulated Switchgear Market |
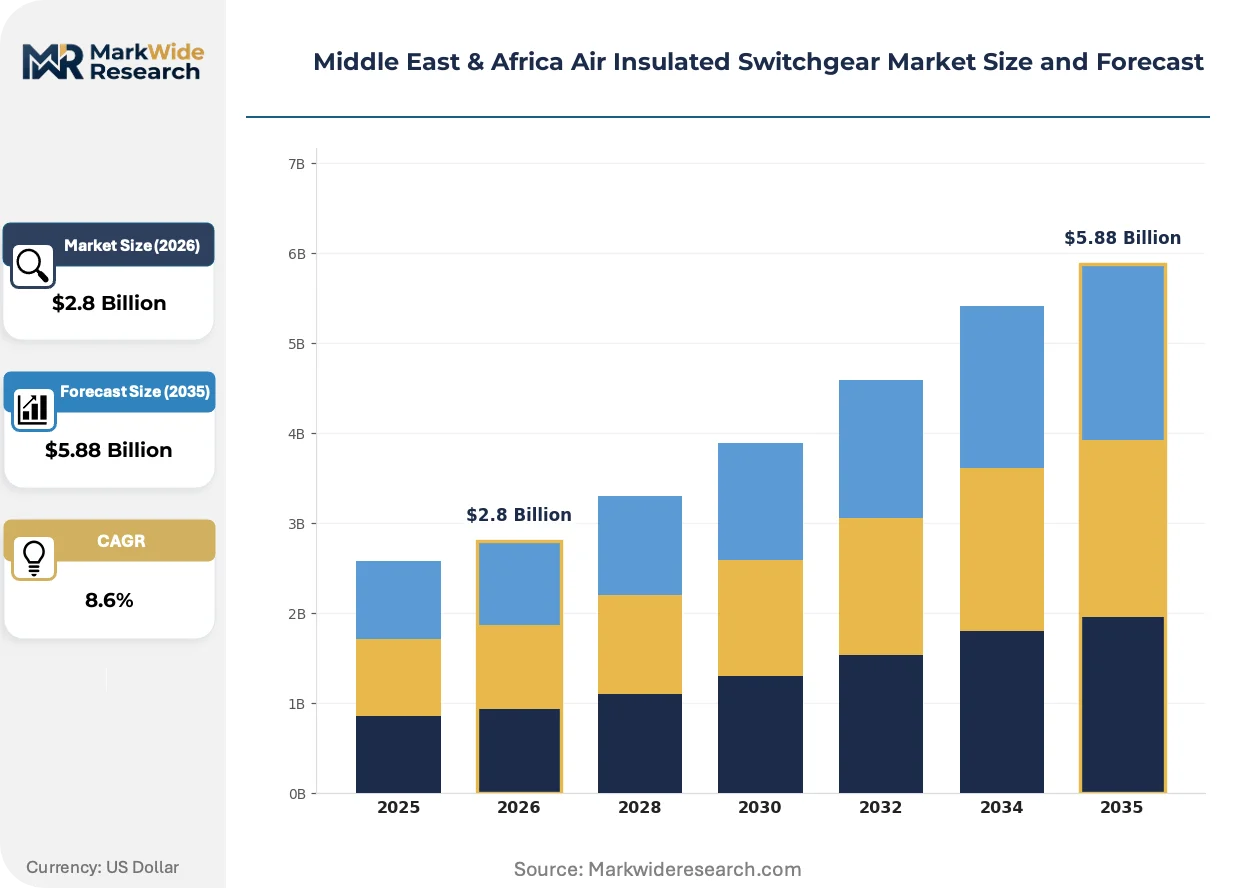
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medium Voltage, High Voltage, Compact, Modular Technology: Vacuum, Air, SF6, Hybrid End User: Utilities, Industrial, Commercial, Renewable Energy Installation: Indoor, Outdoor, Substation, Transformer Station |
| Companies Covered | Eaton Corporation PLC, Toshiba Corporation, Schneider Electric SE, ABB Ltd., Mitsubishi Electric Corporation, Siemens AG, Hitachi Energy Ltd., Al Ahelia Switchgear Co., General Electric Company, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East & Africa Air Insulated Switchgear Market Trends and Innovations
Three parallel developments are compressing the technology adoption cycle across Middle East & Africa switchgear procurement: SF6 phase-down imperatives, modular substation architecture, and digitalized asset management protocols.
Vacuum interruption technology within air-insulated frames is consolidating its position as the default medium-voltage breaking solution. Saudi Aramco and UAE utility procurement specifications now mandate SF6-free alternatives for new substation awards. This technology shift is compressing the addressable market for hybrid gas-insulated designs and forcing portfolio reconfiguration among incumbent suppliers.
The EU F-Gas Regulation's phase-down schedule is reshaping contractor liability exposure across Gulf power projects. Multinational EPC firms face carbon accounting penalties for SF6 leakage over project lifecycles, accelerating air-insured specification in tender documents. North African markets with European contractor presence, particularly Morocco and Egypt, exhibit the fastest regulatory transmission.
Buyers are unbundling after-sales service from equipment procurement, compressing vendor margin structures. Saudi Electricity Company and Dubai Electricity & Water Authority now separate switchgear supply from ten-year maintenance contracts, enabling third-party service competition. This disintermediation is most advanced in the UAE, where specialized maintenance firms are capturing transformer station service revenue previously retained by original equipment providers.
Middle East & Africa Air Insulated Switchgear Market Segmentation
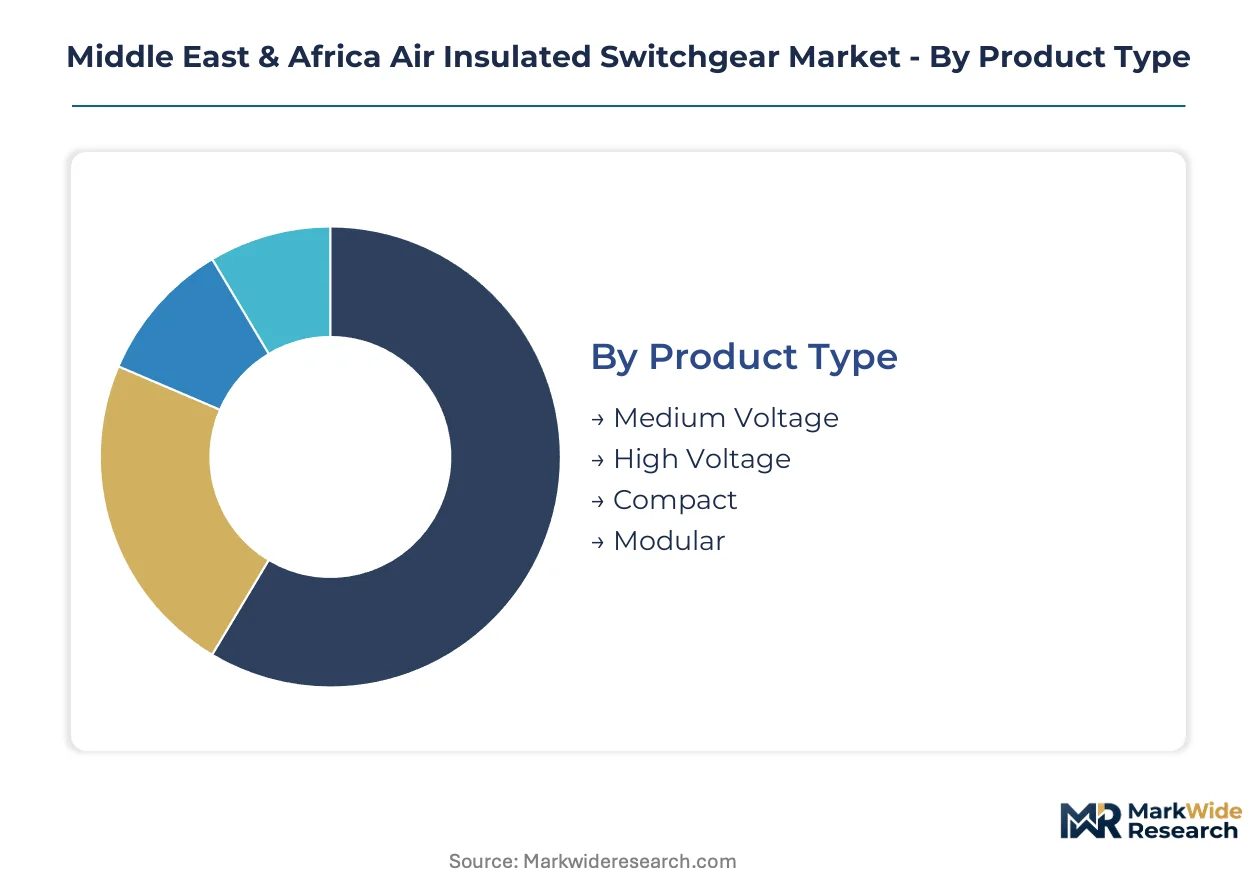
Air insulated switchgear procurement across the Middle East & Africa fragments across voltage thresholds, interruption technologies, and installation environments. Each segment carries distinct certification burdens from Saudi Standards, Metrology and Quality Organization and South Africa's National Regulator for Compulsory Specifications that shape supplier eligibility.
Product Type:
Saudi Standards, Metrology and Quality Organization dielectric withstand thresholds apply differentially across voltage ratings, filtering import eligibility for medium-voltage assemblies while imposing stricter short-circuit certification on high-voltage configurations.
- Medium Voltage:Rated 12 kV through 36 kV with atmospheric air dielectric and visible busbar arrangements. Demand concentrates in Saudi Arabia and UAE utility substation buildouts where grid modernization mandates specify SF6-free alternatives for renewable integration.
- High Voltage:Configurations above 36 kV requiring reinforced insulation clearances and seismic-rated enclosures. Procurement clusters in Egypt's Suez Canal Economic Zone industrial electrification projects where European EPC contractors impose EU F-Gas Regulation compliance on specifications.
- Compact:Space-optimized metal-enclosed designs for dense urban substations in Dubai and Riyadh where footprint constraints challenge conventional air-insulated layouts.
- Modular:Factory-assembled skid-mounted units accelerating deployment timelines for Saudi Aramco renewable interconnection projects.
Leading the category by volume: Medium Voltage. Growing fastest: Modular.
Technology:
Cost tier stratification separates established vacuum interruption from legacy SF6-dependent designs facing regulatory phase-down pressure across Gulf Cooperation Council procurement.
- Vacuum:Ceramic-enclosed arc quenching with zero greenhouse gas leakage liability. Saudi Electricity Company and Dubai Electricity & Water Authority procurement specifications now mandate this technology for new substation awards, compressing the competitive window for gas-insulated alternatives.
- Air:Conventional atmospheric dielectric with direct visibility for maintenance access. Dominates retrofit cycles across aging North African grids where operational simplicity outweighs compactness requirements.
- SF6:Sulfur hexafluoride-insulated designs facing accelerating displacement from EU F-Gas Regulation extraterritorial pressure on multinational EPC contractors.
- Hybrid:Combined air and vacuum configurations targeting transitional specifications in Morocco and Egypt where regulatory transmission from European contractor presence is fastest.
Dominant by installed base: Air. Steepest expansion trajectory: Vacuum.
End User:
Customer type determines maintenance protocol sophistication and contract bundling preferences across the Middle East & Africa.
- Utilities:State-owned transmission and distribution operators with ten-year unbundled maintenance contracts. Saudi Electricity Company separates switchgear supply from service agreements, enabling third-party competition previously retained by original equipment providers.
- Industrial:Petrochemical and mining operations requiring desert climate tolerance and intermittent load compatibility. Demand clusters in Saudi Aramco downstream facilities and South African platinum belt electrification.
- Commercial:Real estate and data center developers prioritizing footprint efficiency in dense urban environments where air-insulated real estate requirements challenge project feasibility.
- Renewable Energy:Solar and wind farm developers seeking switchgear compatible with variable generation profiles. South Africa's renewable auction pipeline creates first-mover specification influence for distributed interconnection standards.
Highest procurement volume: Utilities. Gaining share fastest: Renewable Energy.
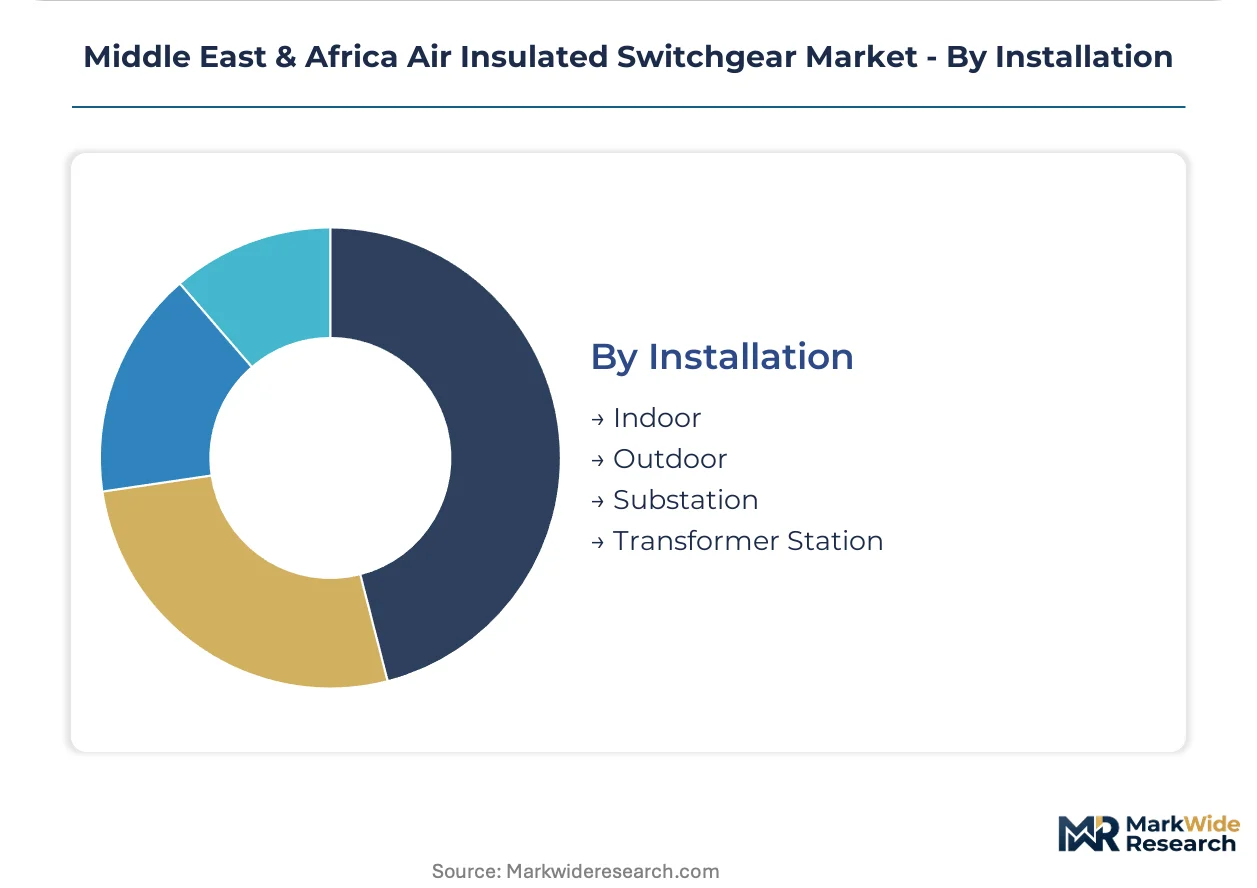
Installation:
Environmental exposure tier shapes enclosure IP ratings and thermal management requirements across the region's climate extremes.
- Indoor:Climate-controlled switchgear rooms in Dubai and Riyadh high-rise developments where dust infiltration risks mandate sealed environments despite air-insulated dielectric.
- Outdoor:Direct-exposure installations across Saudi renewable sites requiring sand-resistant louvers and solar load-rated conductor sizing.
- Substation:Dedicated yard configurations for utility-scale grid nodes. Siemens AG leverages engineering depth to dominate these installations across North African markets.
- Transformer Station:Integrated transformer-switchgear assemblies reducing civil works and commissioning timelines for Egyptian industrial zone electrification.
Most widely deployed: Substation. Expanding most quickly: Transformer Station.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper and aluminum supply corridors from Zambia and Chile anchor the Middle East & Africa air insulated switchgear value chain. Gulf Cooperation Council states concentrate procurement authority for utility-scale substation buildouts. North African markets absorb European regulatory transmission through multinational EPC contractor presence.
Saudi Arabia
Saudi Electricity Company executes substation buildouts specifying vacuum interruption technology for renewable integration. The Saudi Standards, Metrology and Quality Organization enforces dielectric withstand thresholds that filter import eligibility. Riyadh and the Eastern Province cluster demand from Saudi Aramco downstream facilities and NEOM renewable interconnection projects.
United Arab Emirates
Dubai Electricity & Water Authority separates switchgear supply from ten-year maintenance contracts, enabling third-party service competition. The Dubai Supreme Council of Energy mandates SF6-free alternatives for new substation awards. Dubai and Abu Dhabi concentrate petrochemical electrification demand and data center power infrastructure.
South Africa
The renewable auction pipeline creates first-mover specification influence for distributed solar and wind farm interconnection. The National Regulator for Compulsory Specifications enforces short-circuit certification thresholds on medium-voltage assemblies. The platinum belt around Rustenburg and Limpopo drives industrial electrification demand from mining operations.
Egypt
The Suez Canal Economic Zone industrial electrification projects lack committed switchgear suppliers, opening procurement relationships. European EPC contractors impose EU F-Gas Regulation compliance on specifications through extraterritorial pressure. Cairo and the Red Sea coast cluster transformer station installations for manufacturing zone development.
Morocco
European contractor presence transmits regulatory pressure fastest through hybrid air-vacuum configuration specifications. The Moroccan Agency for Sustainable Energy oversees grid code evolution for renewable interconnection standards. Casablanca and Tangier-Med industrial zones concentrate demand from automotive and aerospace manufacturing electrification.
Middle East & Africa Air Insulated Switchgear Market Competitive Landscape
Strategic partnerships dominate the current landscape as suppliers localize fabrication to meet Saudi Standards, Metrology and Quality Organization certification requirements. The vendor base concentrates around three tiers: integrated electrical conglomerates with transformer-switchgear bundling capability, regional fabrication specialists serving Gulf utility procurement, and European technology licensors providing vacuum interrupter cores. Two competitive moves reshape positioning: backward integration into vacuum interrupter manufacturing to reduce German and Italian import dependency, and predictive service contract bundling to recapture revenue from unbundled maintenance markets.
Among European-headquartered electrical conglomerates, Schneider Electric SE, ABB Ltd., and Siemens AG occupy positions across the premium and mid-market tiers. Schneider Electric SE exemplifies the localization archetype through Gulf production partnerships. ABB Ltd. represents portfolio breadth positioning for utility substation specifications. Siemens AG anchors engineering-intensive transformer station installations across North African markets. These three entities collectively illustrate how technology depth and regional fabrication presence determine competitive viability under evolving EU F-Gas Regulation compliance requirements.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Toshiba Corporation |
| Schneider Electric SE |
| ABB Ltd. |
| Mitsubishi Electric Corporation |
| Siemens AG |
| Hitachi Energy Ltd. |
| Al Ahelia Switchgear Co. |
| General Electric Company |
| Others |
Pricing and Supply Chain Analysis
The EU F-Gas Regulation's extraterritorial enforcement gates qualified supply for Gulf power projects, restricting premium-tier pricing access to suppliers with SF6-free certification and regional fabrication partnerships. This environmental mandate compresses the vendor pool while elevating warranty-backed service contracts as the primary price differentiation mechanism across Saudi and UAE utility procurement.
Pricing Analysis
Warranty and maintenance bundling separates premium offerings from unbundled equipment-only transactions across Saudi Electricity Company and Dubai Electricity & Water Authority tenders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service depth. Price erosion runs through the economy tier as regional fabricators compete on stripped-down supply-only contracts. Industrial end-users in Saudi Aramco facilities exhibit lowest price sensitivity due to operational continuity requirements, while commercial developers in dense urban Dubai show highest sensitivity to footprint-related cost premiums.
Supply Chain Analysis
Dual-sourcing requirements from Saudi Standards, Metrology and Quality Organization and Dubai Supreme Council of Energy mandate multi-supplier qualification for vacuum interrupter cores and busbar assemblies. Manufacturing clusters in Germany, Italy, and China supply ceramic-enclosed arc quenching components, while Zambian and Chilean copper feed regional fabrication hubs in the Gulf. Single-source vulnerability concentrates in European vacuum interrupter manufacturing, exposing assembly operations to logistics chokepoints through Mediterranean shipping corridors. Distribution runs through EPC contractor procurement channels with long-term framework agreements dominating utility-scale deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where captive supply of vacuum interrupter cores determines margin defense against unbundled service competition. Players are pursuing backward integration into ceramic-enclosed arc quenching manufacturing to reduce German and Italian import dependency.
For Market Incumbents: Hedge against unbundled maintenance competition by acquiring certified service firms in the UAE and Saudi Arabia. Incumbents should secure Saudi Standards, Metrology and Quality Organization accreditation for in-country vacuum interrupter testing to offset technician shortage risks. Backward integration into busbar fabrication insulates margin positions from copper price volatility. For New Entrants and Emerging Players: The EU F-Gas Regulation in Gulf Cooperation Council states opens a window for SF6-free specialists without legacy gas-insulated portfolio drag. Egypt's Suez Canal Economic Zone industrial electrification presents the most penetrable geography with uncommitted supplier relationships. A go-to-market angle through transformer station bundling with European EPC contractors bypasses direct utility procurement barriers. For Investors and Strategic Acquirers: Saudi Electricity Company's unbundling of maintenance contracts from equipment supply is the leading indicator that predictive service platforms will capture disproportionate value in the medium-term. Acquisition targets should profile as regional fabrication specialists with existing Gulf production partnerships and vacuum interruption technology licenses. Watch for vacuum interrupter testing technician certification programs as the inflection signal for supply-constraint easing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Interrupter Manufacturing | Reduces German and Italian import dependency for Gulf fabrication hubs. |
| Predictive Service Contract Bundling | Recaptures revenue from unbundled maintenance markets in UAE utility procurement. |
| Regional Fabrication Partnership Expansion | Secures Saudi Standards, Metrology and Quality Organization certification eligibility. |
| Digital Twin Integration Development | Enables asset monitoring convergence with air insulated switchgear maintenance protocols. |
| Renewable Energy Segment Specialization | Captures fastest-expanding demand from Saudi Aramco and South African auction pipelines. |
Research Methodology
Trade databases, utility procurement registries, and EPC contractor filings formed the secondary backbone of this analysis, cross-referenced with primary interviews involving substation engineers, utility procurement officers, vacuum interrupter manufacturing specialists, and regulatory compliance consultants. Bottom-up triangulation against top-down grid investment forecasts validated volume estimates across the analysis window.
Historical trendline analysis of Saudi Electricity Company and Dubai Electricity & Water Authority capital expenditure patterns established baseline growth trajectories. The forecast framework models voltage tier, interruption technology, end-user category, and installation environment as primary segmentation dimensions. CAGRs were derived from utility-scale substation buildout timelines and renewable interconnection project pipelines, with vacuum interruption adoption curves and SF6 phase-down schedules as key industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for hybrid air-vacuum configurations would alter the outlook if regulatory transmission from European contractor presence accelerates beyond projected rates. Deviation in Gulf Cooperation Council grid code evolution for distributed generation interconnection would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Cigarette Packaging Market
Others
Underwater Light Market
Others
Synthetic Leather Market
Others
Surface Green Mining Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Reusable Wine Bags Market
Others
Construction Wearables Market
Others
Enterprise Video Content Management Market
Others
Deep Sea Mining Market
Others
Global Contactless Biometrics Technology Market
Others
One-Way Degassing Valve Market
Others
Architectural Fabrics Market
Others
Manometers Market
Others
Duty Free Retail Market
Others
Floor Cleaning and Mopping Machine Market
Others
Radar Speed Signs Market