
 Radar Speed Signs Market | 2026-2036
Radar Speed Signs Market Size, Share, and Industry Trends Forecast 2026-2036
Radar Speed Signs Market Analytics
Electrical engineering talent specializing in radar sensor calibration and solar power integration is reorganizing how manufacturers scale production lines. SWARCO leverages its European traffic infrastructure footprint to dominate continental procurement channels. Carmanah Technologies anchors North American municipal contracts through its solar-powered specialization. LACROIX City competes on R&D intensity in connected vehicle-ready sign systems.
Radar speed signs are traffic control devices that use Doppler radar to detect approaching vehicle velocity and display real-time speed feedback to drivers, typically operating at K-band frequencies with detection ranges of 300-1,500 feet. Their primary purpose is to reduce vehicle speeds in high-risk zones without requiring active law enforcement presence. Fixed speed signs capture the majority of installed base revenue due to permanent municipal budgets, while solar-powered signs represent the fastest-growing product category as off-grid deployment eliminates trenching and electrical connection costs. Wireless communication-enabled units command premium positioning by enabling remote data collection and cloud-based traffic analytics.
Federal Highway Administration (FHWA) Manual on Uniform Traffic Control Devices (MUTCD) compliance shapes product design requirements in the United States, while European Committee for Standardization (CEN) EN 12966 specifications govern display visibility and radar accuracy across EU member states. Local transportation authorities in Australia reference Austroads guidelines for school zone variable speed limit installations. Stakeholders must monitor evolving connected infrastructure standards and procurement shifts toward intelligent transportation system integration.
Market Dynamics
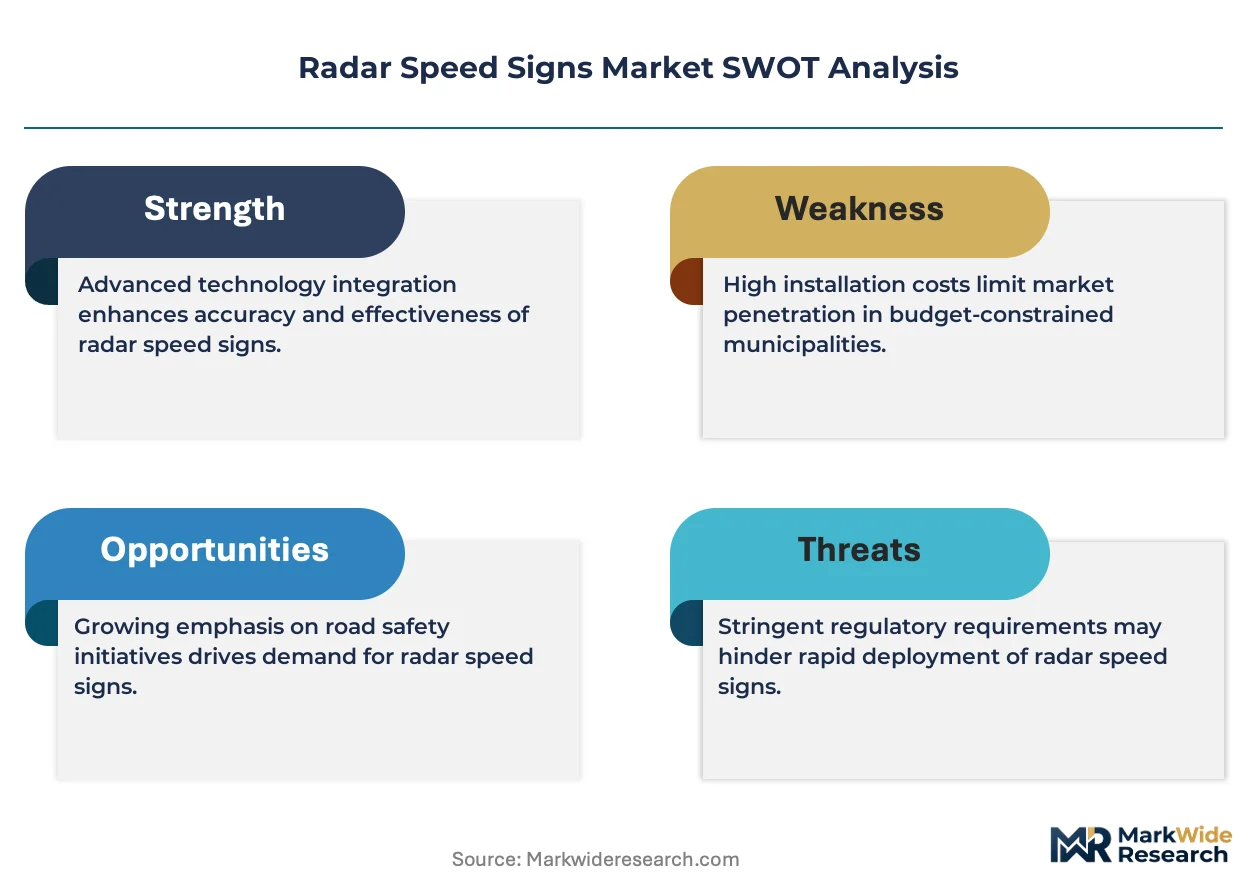
Municipal procurement officers are consolidating vendor relationships around full-service traffic safety contractors capable of delivering solar-powered units with embedded cellular connectivity, compressing margins for standalone equipment manufacturers.
Growth Catalysts
- Vision Zero mandates:Municipal traffic departments in Sweden, the Netherlands, and the United States face binding fatality-reduction targets that require speed feedback installations at documented high-risk corridors.
- K-band radar miniaturization:Advances in solid-state Doppler sensors enable detection ranges exceeding 1,200 feet in units under 15 pounds, expanding portable deployment options for temporary work zones.
- Solar photovoltaic cost curves:Crystalline silicon panel prices have collapsed manufacturing economics for off-grid traffic infrastructure, eliminating trenching and electrical connection expenses in rural deployments.
Market Restraints
- Lithium-ion battery supply concentration:Cell production concentrates in East Asian manufacturing clusters, exposing sign manufacturers to raw material volatility and extended lead times for energy storage subsystems.
- EN 12966 certification timelines:European Committee for Standardization display visibility testing requires 6-12 month validation cycles, gating market entry for new product variants.
- LED driver component shortages:Power management integrated circuits face allocation constraints from automotive and consumer electronics demand, inflating bill-of-materials costs for high-brightness displays.
Strategic Opportunities
- Connected vehicle infrastructure:DSRC and C-V2X protocol integration positions radar speed signs as edge computing nodes capable of broadcasting real-time speed data to autonomous vehicle fleets.
- Australian school zone expansion:Austroads guideline revisions mandate variable speed limit systems outside all primary schools, creating concentrated demand for solar-powered portable units in Queensland and Western Australia.
- Highway maintenance outsourcing:Private toll operators and infrastructure concession holders are assuming responsibility for work zone safety equipment, opening direct procurement channels outside municipal bidding processes.
Industry Challenges
- RF engineer scarcity:Doppler radar calibration and antenna pattern optimization require specialized microwave expertise that traffic equipment manufacturers struggle to recruit against telecommunications and aerospace competitors.
- Legacy traffic controller integration:Existing centralized signal systems use proprietary communication protocols, forcing expensive middleware development for cloud-connected speed sign deployments.
- IP fragmentation in wireless stacks:Cellular modem firmware and antenna design patents concentrate among semiconductor licensors, complicating in-house connectivity development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radar Speed Signs Market |
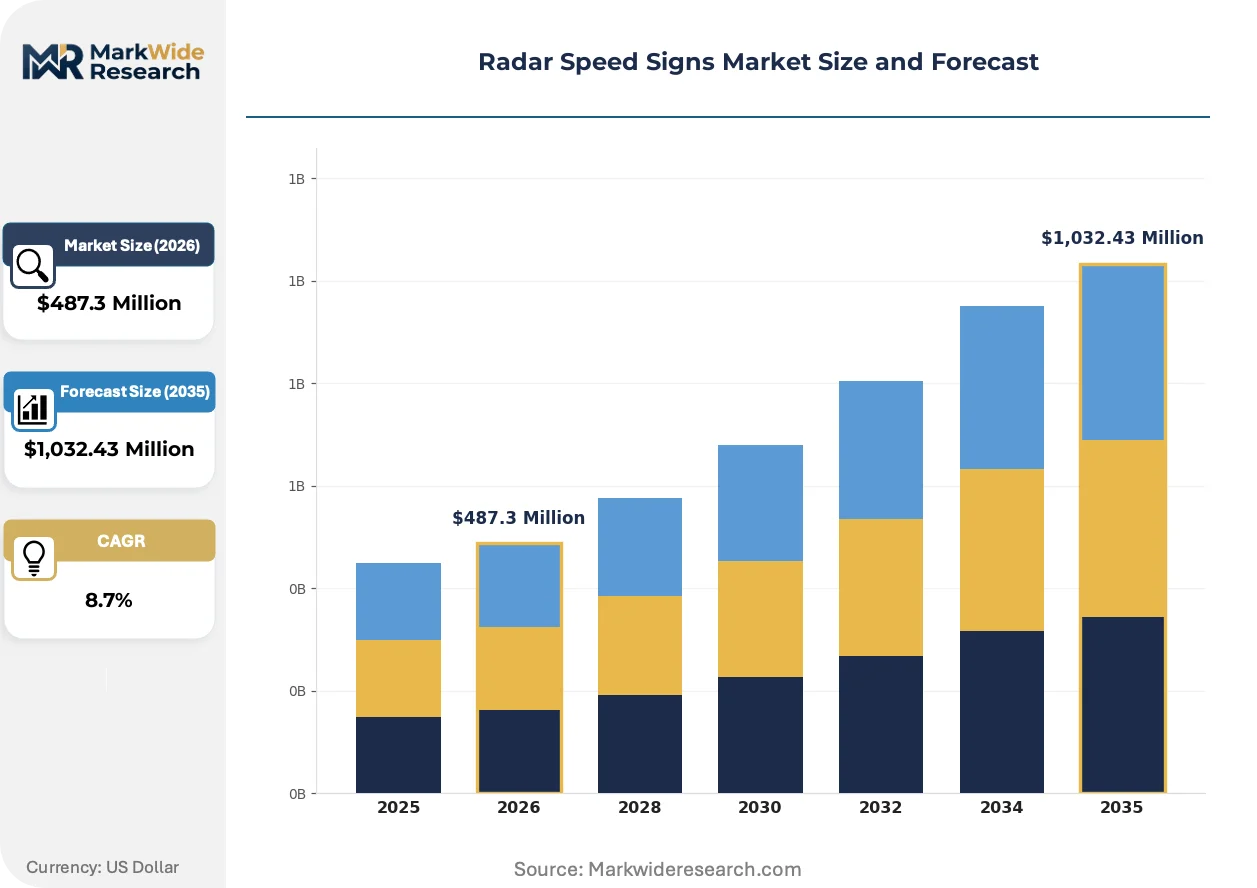
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Speed Signs, Portable Speed Signs, Solar-Powered Signs, Radar Indicators Technology: Digital Display, LED Technology, Analog Display, Wireless Communication End User: Municipalities, Traffic Management Agencies, Construction Sites, School Zones Installation Type: Permanent Installation, Temporary Installation, Pole-Mounted, Vehicle-Mounted |
| Companies Covered | Carmanah Technologies, SWARCO, LACROIX City, Wanco, TAPCO, Ver-Mac, Traffic Logix, Radarsign, TraffiCalm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radar Speed Signs Market Evolving Landscape
Edge computing architectures and low-power wide-area networks are redefining how traffic safety equipment generates, processes, and transmits operational data, shifting value capture from hardware sales toward recurring analytics services.
Software-defined radar is decomposing traditional hardware-defined signal processing chains. K-band transceiver modules now feed raw I/Q data to ARM-based edge processors running Python-deployed detection algorithms. German municipal operators are piloting these configurable systems to distinguish passenger vehicles from heavy trucks. This decomposition enables over-the-air calibration updates and compresses sensor hardware refresh cycles from seven years to three.
CSRD disclosure requirements are mandating lifecycle carbon accounting for public infrastructure procurement. European traffic departments must now document embodied emissions in aluminum enclosures, lithium batteries, and semiconductor components. Solar-powered sign manufacturers with verified supply chain data are capturing premium positioning in French and Danish tenders, while competitors face exclusion from sustainability-scored bidding frameworks.
Performance-based contracting is displacing capital expenditure procurement for school zone safety programs. Texas and Florida transportation authorities now pay vendors per documented speed reduction outcome rather than per installed unit. This restructures vendor cash flow toward multi-year service obligations and concentrates demand among contractors with integrated data analytics platforms capable of proving behavioral impact to audit standards.
Radar Speed Signs Market Segmentation
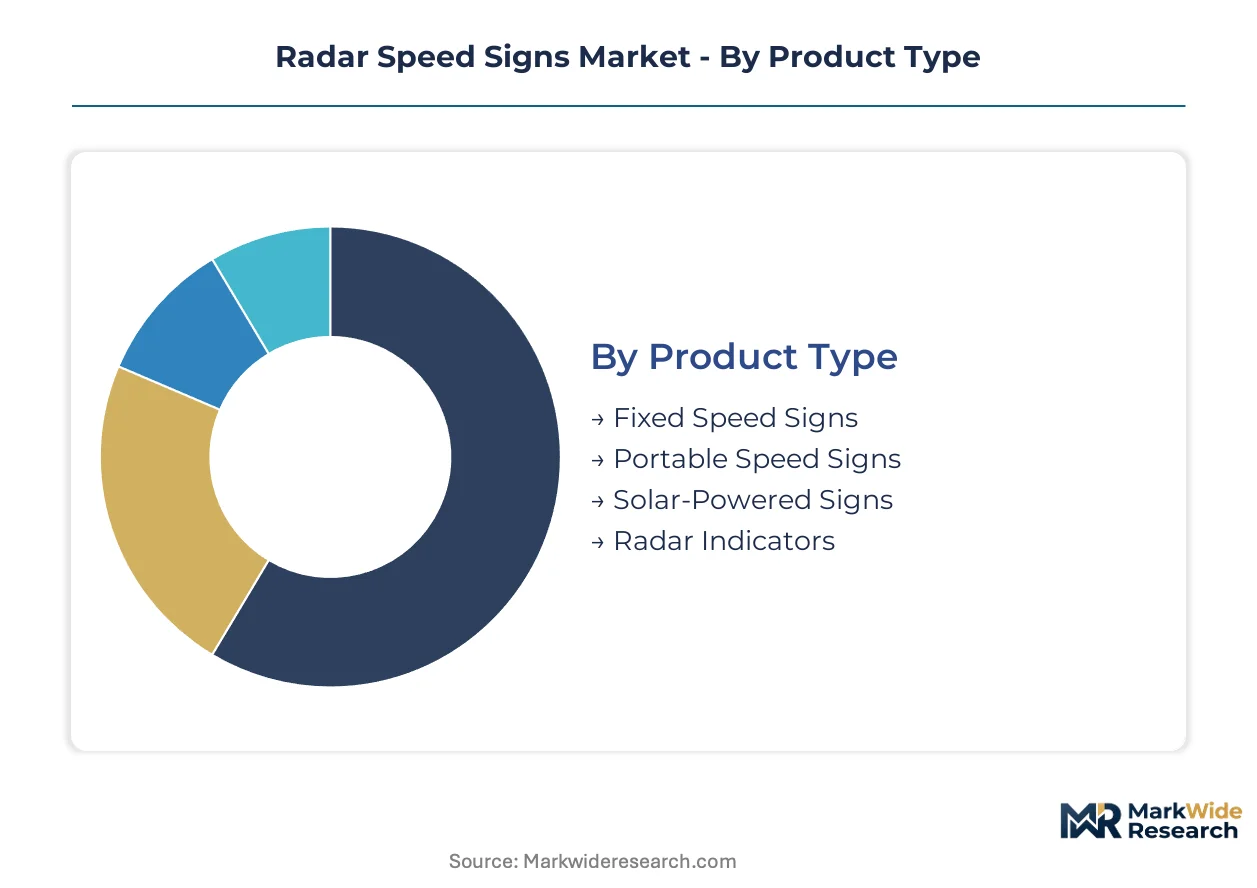
Product differentiation in radar speed signs follows regulatory compliance pathways and installation economics. Municipal procurement specifications increasingly bundle power autonomy with connectivity requirements, reshaping how manufacturers configure hardware platforms across deployment contexts.
Product Type:
FHWA MUTCD compliance in the United States and CEN EN 12966 certification in Europe create divergent product qualification pathways that segment manufacturers by regional regulatory expertise.
- Fixed Speed Signs:These permanent installations anchor municipal traffic department budgets with hardwired electrical connections and integrated signal controller interfaces. Demand concentrates on arterial corridors in Germany and the United States where Vision Zero mandates require documented speed reduction outcomes at high-risk locations.
- Solar-Powered Signs:Crystalline silicon photovoltaic arrays paired with lithium-ion battery subsystems eliminate trenching costs and expand deployment to rural roadways without grid access. Queensland and Western Australia school zone expansions under revised Austroads guidelines are driving concentrated procurement of these off-grid units.
- Portable Speed Signs:Deployed for temporary work zones and event traffic management, these units prioritize rapid deployment over durability.
- Radar Indicators:Compact velocity-only displays without regulatory signage status serve private campus and industrial applications.
Fixed speed signs handle the majority of throughput; solar-powered signs are expanding most quickly on share.
Technology:
Display brightness specifications and wireless protocol choices segment procurement by operational environment and data service requirements.
- LED Technology:High-brightness diode arrays meeting EN 12966 visibility classes dominate European tenders, with power management integrated circuits facing allocation pressure from automotive demand. Texas and Florida transportation authorities specify these units for performance-based contracting programs requiring documented speed reduction metrics.
- Wireless Communication:Embedded cellular modems and DSRC/C-V2X protocol stacks transform speed signs into edge computing nodes for connected vehicle infrastructure. German municipal operators pilot these systems for real-time truck-versus-passenger-vehicle classification.
- Digital Display:Full-matrix LED arrays enable variable message capability beyond speed feedback.
- Analog Display:Electromechanical drum displays persist in cost-constrained legacy installations.
LED technology commands the dominant revenue position; wireless communication is climbing the fastest on technology substitution.
End User:
Budget authority and procurement process complexity segment demand between public agency capital programs and outsourced infrastructure services.
- Municipalities:City and county traffic departments in Sweden, the Netherlands, and the United States deploy permanent installations under binding Vision Zero fatality-reduction targets. Procurement consolidates around full-service contractors capable of delivering solar-powered units with embedded analytics platforms.
- School Zones:Australian primary school variable speed limit mandates under revised Austroads guidelines create concentrated demand for portable solar-powered units in Queensland and Western Australia.
- Traffic Management Agencies:State and provincial departments manage highway corridor deployments.
- Construction Sites:Private contractors and toll operators assume work zone safety equipment responsibility under maintenance outsourcing agreements.
Municipalities account for the largest procurement volume; school zones are gaining share fastest on regulatory mandate expansion.
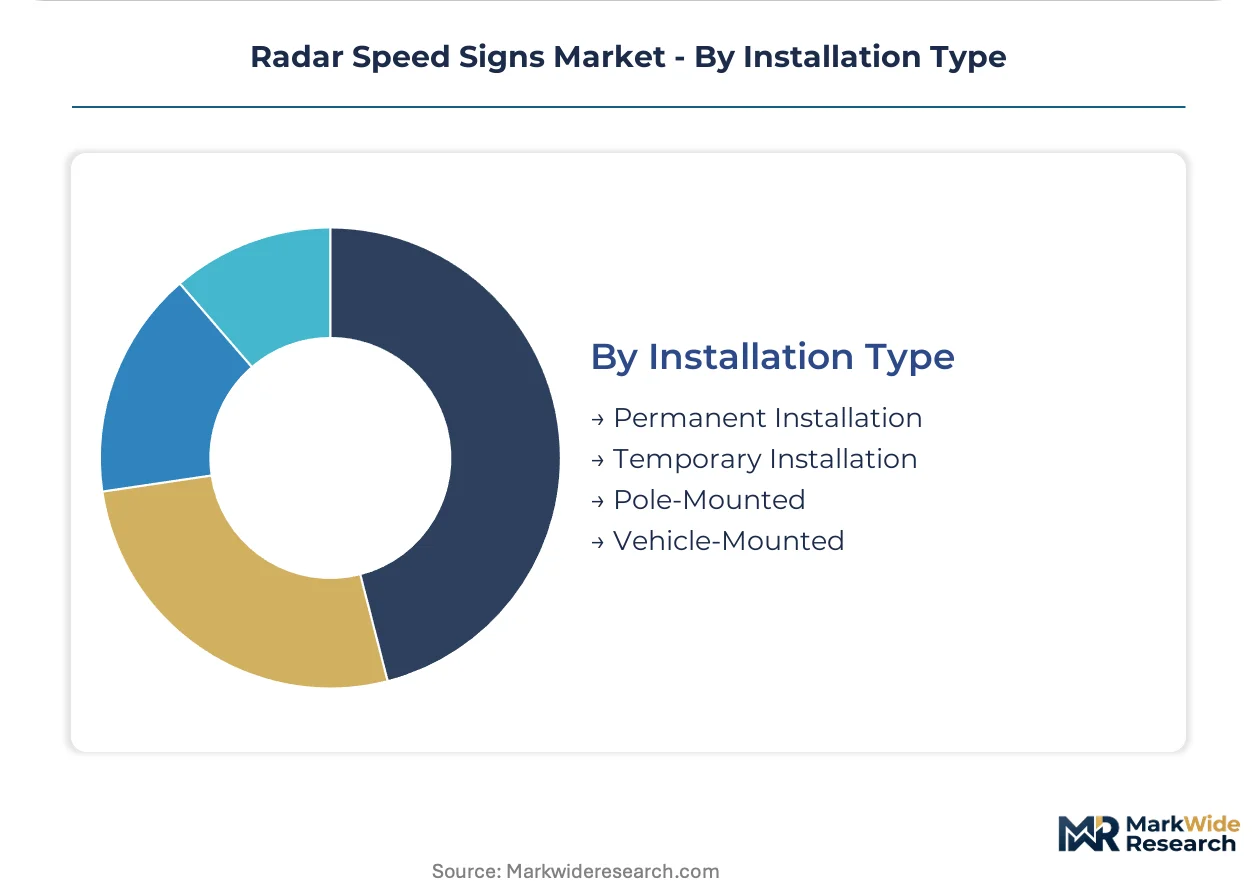
Installation Type:
Mounting configuration and permanence expectations segment manufacturing by structural engineering requirements and deployment logistics.
- Permanent Installation:Foundation-mounted poles with underground electrical service dominate municipal arterial deployments in Germany and the United States. These installations require seven-year hardware refresh cycles and integration with legacy traffic signal controller networks using proprietary protocols.
- Temporary Installation:Trailer-mounted and surface-ballasted units serve highway work zones and event traffic management. Private toll operators and infrastructure concession holders in Texas and Florida procure these through direct channels outside municipal bidding processes.
- Pole-Mounted:Existing infrastructure attachment reduces civil works costs.
- Vehicle-Mounted:Truck-integrated displays support mobile enforcement and emergency response applications.
Permanent installation retains the dominant installed base; temporary installation is accelerating fastest on highway maintenance outsourcing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FHWA MUTCD compliance anchors procurement specifications in the United States, the dominant geography for radar speed sign deployment. Municipal traffic departments across multiple continents are accelerating installations to meet binding road safety mandates, with regulatory frameworks diverging sharply between federal highway standards and EU harmonized technical specifications.
United States
Texas and Florida transportation authorities now deploy performance-based contracting models that pay vendors per documented speed reduction outcome rather than per installed unit. FHWA MUTCD guidelines shape display visibility and radar accuracy requirements for all federal-aid highway projects. School zone deployments concentrate in suburban Dallas-Fort Worth and Miami-Dade corridors where Vision Zero fatality-reduction targets drive concentrated procurement of solar-powered units with embedded cellular connectivity.
Germany
KBA vehicle safety standards intersect with municipal procurement for connected vehicle-ready infrastructure in Baden-Württemberg and Bavaria. EN 12966 certification requirements from the European Committee for Standardization impose 6-12 month validation cycles that gate market entry for new product variants. Stuttgart and Munich traffic authorities pilot software-defined radar systems capable of distinguishing passenger vehicles from heavy trucks for real-time speed limit adjustments.
Australia
Queensland and Western Australia primary school expansions under revised Austroads guidelines mandate variable speed limit systems outside all primary schools. TGA electromagnetic compatibility standards govern radar equipment certification for traffic infrastructure deployment. Brisbane and Perth municipal operators procure portable solar-powered units to eliminate trenching costs in rapidly developing suburban corridors without grid access.
Sweden
Vision Zero fatality-reduction targets bind municipal traffic departments in Stockholm and Gothenburg to documented speed reduction outcomes at high-risk corridors. Transportstyrelsen national transport agency regulations specify radar accuracy tolerances for automated speed feedback systems. Scania and Volvo Group headquarters regions in southern Sweden drive demand for truck-distinguishing radar configurations on industrial access routes.
Netherlands
Rijkswaterstaat national road administration procurement consolidates around full-service contractors capable of delivering solar-powered units with cloud-based traffic analytics. CSRD disclosure requirements mandate lifecycle carbon accounting for aluminum enclosures and lithium batteries in public infrastructure tenders. Rotterdam and Amsterdam port corridor deployments prioritize DSRC and C-V2X protocol integration for connected vehicle infrastructure pilot programs.
Radar Speed Signs Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in the radar speed signs market. The vendor base organizes around three strategic groupings: European traffic infrastructure conglomerates with continental procurement channel dominance, North American solar-powered specialists anchoring municipal contracts, and R&D-intensive connectivity players competing on intelligent transportation system integration. Consolidation pressure is compressing margins for standalone equipment manufacturers while favoring full-service contractors with integrated analytics platforms. Geographic expansion and strategic partnerships represent the dominant competitive moves as procurement officers consolidate vendor relationships.
Within the European infrastructure tier, SWARCO leverages its continental footprint to dominate procurement channels across Germany, Sweden, and the Netherlands. Carmanah Technologies occupies a position as the North American solar-powered specialist anchoring municipal contracts in Texas, Florida, and Australian school zone deployments. LACROIX City exemplifies the R&D-intensive connectivity archetype competing on connected vehicle-ready sign systems with edge computing and low-power wide-area network integration.
| Leading Market Players |
|---|
| Carmanah Technologies |
| SWARCO |
| LACROIX City |
| Wanco |
| TAPCO |
| Ver-Mac |
| Traffic Logix |
| Radarsign |
| TraffiCalm |
| Others |
Value Network & Pricing Analysis
Capacity utilization at East Asian lithium-ion cell foundries directly shapes battery subsystem pricing floors for solar-powered sign manufacturers, compressing margins for European and North American assemblers unable to match procurement scale. This concentration cascades through display driver IC allocation constraints, forcing tiered procurement strategies that segment vendors by their ability to secure long-term component offtake.
Pricing Analysis
Unit economics diverge sharply between German EN 12966-certified systems and Australian off-grid deployments, with certification timelines and solar autonomy requirements driving spread differentiation. Three-tier pricing structure across premium, standard, and economy levels separates connected vehicle-ready units with DSRC stacks from basic LED feedback displays and legacy analog drum systems. Cost compression in standard-tier hardware is intensifying because municipal procurement officers now bundle analytics platforms with hardware orders. School zone contractors in Queensland exhibit highest price sensitivity due to volume tender structures, while Dutch Rijkswaterstaat programs show lowest sensitivity given CSRD-mandated lifecycle accounting premiums.
Supply Chain Analysis
Strategic stockpiling of K-band radar modules and LED driver ICs has displaced just-in-time preferences as automotive sector demand volatility disrupts traffic equipment allocation queues. Component sourcing concentrates in China for lithium-ion cells, Taiwan for power management semiconductors, and Germany for precision radar transceivers. Raw material dependencies span crystalline silicon wafers, aluminum extrusions for enclosures, and rare-earth elements in magnet assemblies for trailer mounting systems. Single-source vulnerability in cellular modem firmware licensing creates bottleneck exposure for connectivity-enabled units. Distribution runs through municipal procurement frameworks in the United States and Germany, direct concession-holder channels in Texas and Florida, and centralized national tenders in Sweden and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected vehicle infrastructure mandates and software-defined radar miniaturization are compressing product refresh cycles from seven years to three, creating high-growth disruption for vendors with edge computing capabilities.
For Market Incumbents: Secure exclusive supplier status with Rijkswaterstaat and Texas DOT through integrated analytics platforms that document speed reduction outcomes to audit standards. Deepen backward integration into ARM-based edge processor supply to offset RF engineer scarcity and compress bill-of-materials exposure from semiconductor allocation constraints.
For New Entrants and Emerging Players: Anchor in Australian school zone deployments under revised Austroads guidelines, where portable solar-powered unit demand concentrates in Queensland and Western Australia without entrenched vendor relationships. Target private toll operators in Texas and Florida through direct procurement channels outside municipal bidding processes, leveraging performance-based contracting models that pay per documented outcome.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors R&D-intensive connectivity players with DSRC/C-V2X protocol stacks and cloud-based traffic analytics platforms over hardware-centric assemblers. Long-term viability hinges on intelligent transportation system integration depth rather than manufacturing scale. Acquisition targets should demonstrate embedded cellular connectivity and edge computing architectures. The signal to watch is FHWA MUTCD guideline revisions mandating connected infrastructure compatibility for federal-aid highway eligibility.
| Strategic Initiative | Industry Significance |
|---|---|
| DSRC Protocol Integration | Positions speed signs as edge nodes for autonomous vehicle fleets in German and Dutch pilot corridors. |
| Solar Photovoltaic Cost Curve Exploitation | Eliminates trenching costs in Australian school zones and rural North American deployments. |
| Performance-Based Contracting Pivot | Restructures vendor cash flow toward multi-year service obligations in Texas and Florida. |
| Software-Defined Radar Development | Enables over-the-air calibration updates and truck-versus-passenger classification for Stuttgart operators. |
| CSRD Supply Chain Verification | Captures premium positioning in French and Danish tenders through embodied emissions documentation. |
Research Methodology
A standing panel of municipal traffic department procurement officers, radar sensor calibration engineers, solar power integration specialists, and intelligent transportation system architects provided ongoing calibration against operational deployment realities. Primary fieldwork combined structured interviews with traffic safety contractors in Texas, Florida, Germany, and Australia alongside secondary validation through FHWA MUTCD guideline documents, EN 12966 certification records, Austroads technical specifications, and municipal tender databases. Bottom-up unit economics modeling triangulated against top-down procurement budget allocations across the analysis window.
Consistency checks validated volume and value outputs against FHWA highway safety expenditure reports, European Committee for Standardization certification timelines, and Queensland Department of Transport school zone procurement disclosures. Segmentation modeling captured product type differentiation, technology substitution patterns, end-user budget authority structures, and installation permanence requirements. CAGRs were derived from documented procurement trajectories and regulatory mandate implementation schedules, with specific inputs including Vision Zero fatality-reduction target binding dates and Austroads guideline revision effective periods.
Material uncertainties — lithium-ion supply concentration disruptions, EN 12966 certification timeline extensions, and LED driver IC allocation constraints — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory mandate adherence schedules and municipal budget continuity. Practitioners should keep alternative scenarios live as connected vehicle infrastructure standards and performance-based contracting adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Latin America Automotive HVAC Market
Others
Bamboo Straws Market
Others
Communication Base Station Body Market
Others
Europe Military 4D Printing Market
Others
Cloud Digital Video Recorder Market
Others
Italy Smart Home Market
Others
Latin America Travel Retail Market
Others
Reinforcement Geosynthetics Market
Others
Synthetic Leather Market
Others
Moveable Water Tap Market
Others
8K Technology Market
Others
Global Extruded Plastics Market
Others
Hotel Wardrobe Market
Others
Asia-Pacific Telecom Transformers Market
Others
Smart-Connected Power Plug Socket Market
Others
Global Pumpkin Candles Market