
 Global Transparent Plastics Market | 2026-2036
Global Transparent Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Transparent Plastics Market Foresight
Subscription-based resin grade certification and software-defined optical property testing is consolidating how transparent plastics get specified and purchased. Dow, Inc. leverages captive polyethylene terephthalate capacity across the US Gulf Coast to anchor supply for medical device and food packaging tiers. SABIC competes through differentiated polycarbonate formulations targeting automotive headlamp and electronic display applications. Covestro AG specializes in high-purity optical grades that sustain premium positioning within lens and sensor cover segments.
Transparent plastics are thermoplastic and thermoset materials formulated for light transmission typically exceeding 80% in the visible spectrum, achieved through controlled molecular architecture, minimal crystallinity, and additive packages that suppress haze and UV degradation. Their primary industrial purpose spans protective barriers, optical media, lightweight glazing, and sterile packaging where visual inspection or light propagation is functionally essential. Polycarbonate dominates structural load-bearing applications such as automotive glazing and safety equipment where impact resistance outweighs scratch sensitivity. PET captures the fastest growth trajectory within food and pharmaceutical packaging driven by recyclability mandates and deposit-return scheme expansion across European and North American jurisdictions. Acrylic-Polymer Blend grades occupy margin-rich niches in signage and decorative lighting where surface hardness and weatherability command price premiums over commodity alternatives.
FDA food-contact notifications and EPA toxic substance evaluations shape which monomers and additives gain commercial traction within US-bound transparent plastic formulations. REACH registration requirements and the EU F-Gas Regulation constrain certain blowing agents and processing aids used in extrusion and thermoforming operations. China's GB standards and SAMR quality supervision protocols enforce optical consistency and migration limits for domestic and export-oriented production. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer-specific recycling targets that will determine which resin families retain access to premium end-use channels.
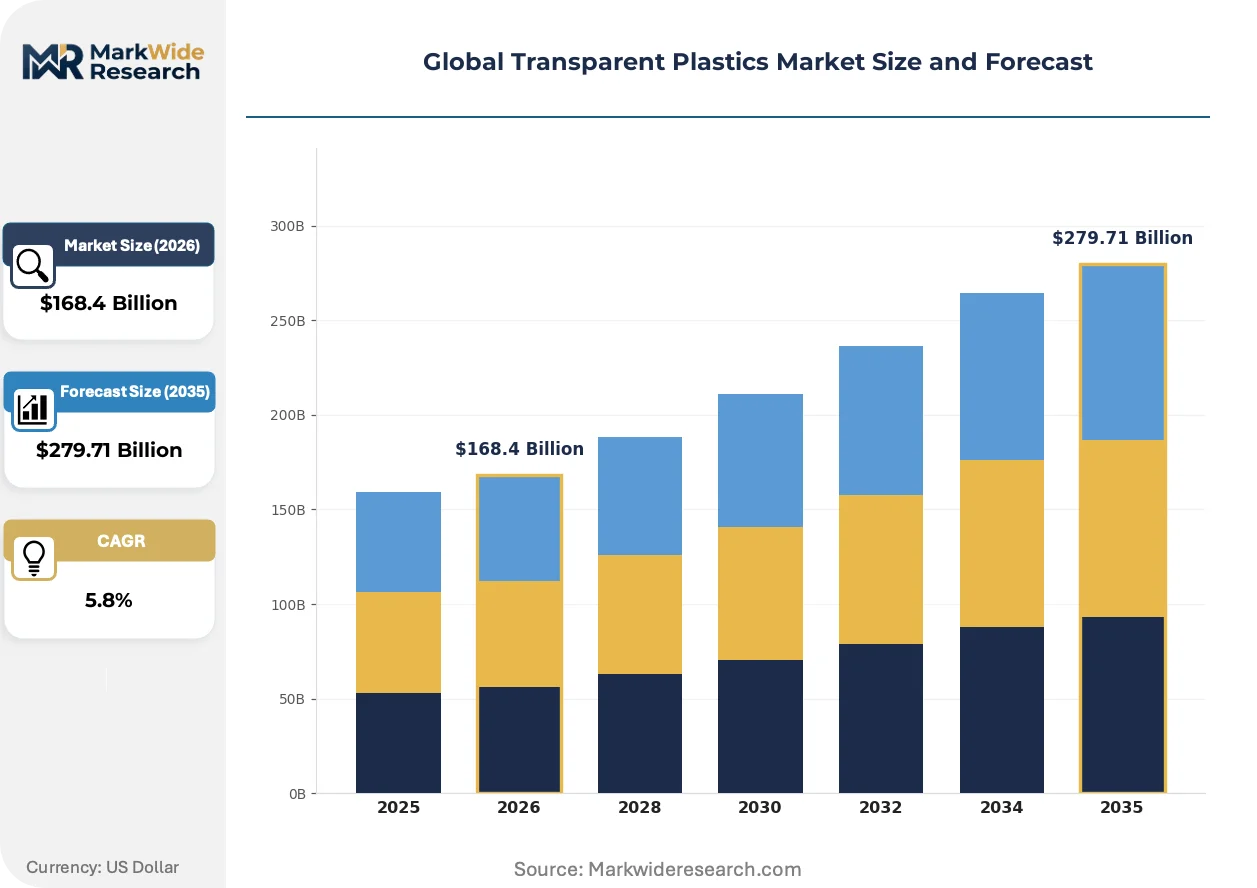
Market Dynamics
The EU's REACH restrictions on bisphenol-A migration are accelerating substitution toward bio-based acrylics and advanced polymer blends across food-contact and pharmaceutical applications.
Growth Catalysts
- Deposit-return scheme expansion:European and North American jurisdictions mandate container recyclability, pulling PET into blister packaging and beverage bottles at accelerated rates.
- Automotive lighting tier demand:China's eastern coastal manufacturing belt concentrates integrated resin-to-sheet production for headlamp and display panel supply chains.
- Medical device packaging standards:FDA food-contact notifications and sterile barrier requirements specify polycarbonate and PET grades for pharmaceutical blisters and surgical kits.
Market Restraints
- Crude-linked feedstock volatility:Paraxylene and bisphenol-A prices swing with naphtha cracking economics, compressing margin visibility for PET and polycarbonate converters.
- Monomer supply concentration:Caprolactam and methyl methacrylate production clusters in Northeast Asia create geographic vulnerability for acrylic-polymer blend availability.
- Optical purity technical ceilings:Haze suppression below 1% in thick-gauge sheet requires capital-intensive melt filtration that excludes smaller extrusion operations.
Strategic Opportunities
- Bio-based acrylic penetration:Germany's chemical parks and Netherlands biorefinery corridors offer fermentation-derived methyl methacrylate feedstock for premium lens applications.
- Sensor cover convergence:Lidar and camera module integration in vehicles is fusing optical-grade polycarbonate with anti-reflective coating technologies.
- Extended producer responsibility frameworks:France's Citeo and Italy's CONAI systems create certified recycled-content premiums for pharmaceutical packaging tenders.
Industry Challenges
- Multi-jurisdiction compliance cadence:Synchronizing FDA food-contact notifications with REACH registration updates and China's GB standard revisions extends product launch timelines.
- Optical metrology skill scarcity:Spectrophotometry and haze-meter operation for light transmission validation exceeds training capacity at mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Transparent Plastics Market |
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $279.71 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Acrylic, PET, PVC, Polystyrene, Acrylic-Polymer Blend End Use Industry: Packaging, Electronics, Construction, Optical Instruments, Consumer Goods, Signage Technology: Injection Molding, Extrusion, Thermoforming, Blow Molding, Casting, Compression Molding Application: Automotive Components, Medical Devices, Display Panels, Lighting Fixtures, Protective Equipment, Decorative Items |
| Companies Covered | Dow, Inc., SABIC, BASF SE, Covestro AG, PPG Industries, Inc., LyondellBasell Industries N.V., DuPont de Nemours, Inc., INEOS Group Limited, LANXESS AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Transparent Plastics Market Shifts & Advancements
Software-defined optical property testing is consolidating specification workflows while resin grade certification migrates toward subscription-based digital platforms.
Machine-vision inline inspection is automating haze and color consistency verification during extrusion. Automotive glazing suppliers in Stuttgart and Detroit deploy these systems to compress lot-release cycles from days to hours. The technology is automating quality documentation for OEM optical specifications.
REACH registration requirements and the EU F-Gas Regulation constrain blowing agents and processing aids in thermoforming operations. Extruders reformulate with inert gas systems to maintain cell structure in foamed polycarbonate. Medical packaging converters in Ireland and the Netherlands face the steepest compliance cost escalation.
Subscription-based resin certification platforms are displacing traditional certificate-of-analysis procurement. Brand owners in food and pharmaceutical sectors now specify blockchain-traceable optical grades. Germany and Switzerland host the densest adoption of these verification networks.
Global Transparent Plastics Market Segmentation
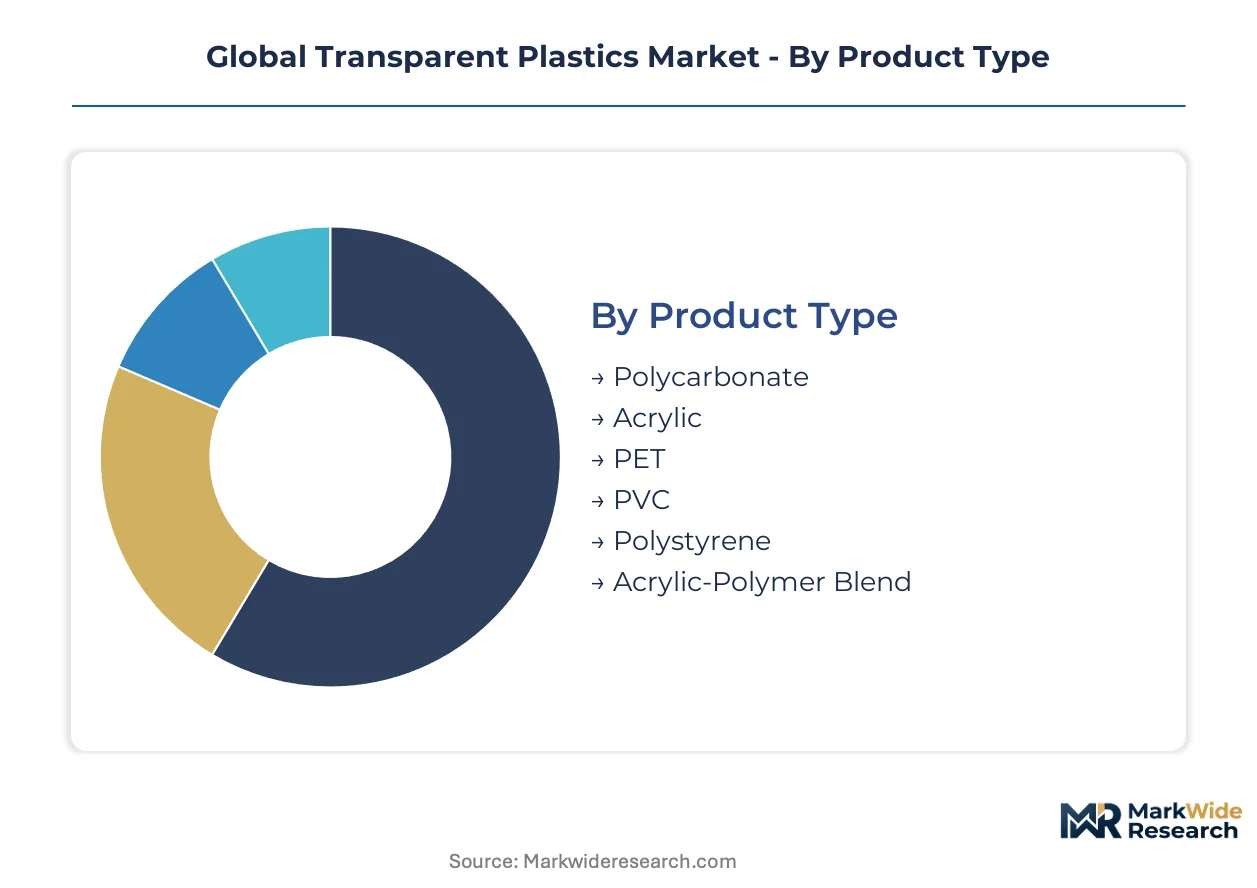
Transparent plastics specifications diverge sharply across end-use channels, with optical purity thresholds and regulatory compliance requirements determining resin selection. Upgrade cycles in automotive lighting and display panel manufacturing are accelerating formulation shifts toward higher-performance grades.
Product Type:
Replacement timelines in automotive glazing and medical packaging are compressing as OEMs specify next-generation optical grades with enhanced durability and regulatory clearance.
- Polycarbonate:Amorphous thermoplastic with impact resistance exceeding 250 times that of glass, formulated for headlamp lenses and safety visors. Demand clusters in Stuttgart and Detroit automotive tiers where ECE R43 compliance mandates shatter-resistant glazing. REACH bisphenol-A migration limits are forcing reformulation investments.
- PET:Semi-crystalline polyester with clarity exceeding 90% in thin-gauge sheet, dominating food-contact and pharmaceutical blister applications. Germany and California deposit-return schemes are pulling virgin and recycled grades into beverage packaging at accelerated rates. FDA food-contact notifications govern monomer specifications for US-bound shipments.
- Acrylic:Poly(methyl methacrylate) homopolymer with surface hardness superior to polycarbonate, capturing signage and decorative lighting niches. Weatherability in UV-exposed applications drives specification in Dubai and Australian exterior installations.
- PVC:Chlorinated polymer with cost-positioned clarity in construction glazing and medical tubing, constrained by ECHA candidate list scrutiny on plasticizer migration.
- Polystyrene:Crystal-grade styrenic with lowest cost-per-kilogram in disposable packaging, losing share to PET in circular-economy jurisdictions with extended producer responsibility frameworks.
- Acrylic-Polymer Blend:Alloy formulations combining PMMA with impact modifiers for premium lens applications where scratch resistance and dimensional stability command price premiums over commodity alternatives.
Volume placements concentrate in PET; the faster expansion belongs to Acrylic-Polymer Blend.
End Use Industry:
Cost-tier stratification separates specification-grade optical applications from commodity packaging, with certification requirements widening the gap between premium and standard segments.
- Packaging:Pharmaceutical blisters, food-contact trays, and beverage bottles requiring migration-tested clarity and seal integrity. EU F-Gas Regulation constraints on thermoforming blowing agents are elevating processing costs for Irish and Dutch converters.
- Electronics:Display panel substrates, sensor covers, and device housings where light transmission and dimensional stability are critical. Lidar module integration in vehicles is fusing optical-grade polycarbonate with anti-reflective coatings.
- Construction:Skylights, noise barriers, and architectural glazing where polycarbonate sheet replaces glass for weight reduction. China's eastern coastal manufacturing belt supplies integrated resin-to-sheet production for regional infrastructure projects.
- Optical Instruments:Camera lenses, microscopy components, and laser optics demanding haze suppression below 0.5% and refractive index precision. Germany and Switzerland host the densest concentration of high-purity optical grade processors.
- Consumer Goods:Kitchenware, cosmetic containers, and appliance panels where surface aesthetics and dishwasher durability determine material selection.
- Signage:Exterior advertising displays and illuminated wayfinding systems requiring UV-stable color retention and impact resistance.
Packaging commands the largest volume footprint; Electronics is climbing the fastest on sensor cover convergence.
Technology:
Application-specific precision requirements are fragmenting process selection, with thin-wall optical components demanding fundamentally different equipment than thick-gauge structural sheet.
- Injection Molding:High-pressure process for complex optical components with tight dimensional tolerances, dominating medical device housing and automotive lens production. Machine-vision inline inspection is automating haze verification during production.
- Extrusion:Continuous sheet and profile production for glazing and display substrates, where melt filtration investments determine optical purity ceilings. Caprolactam supply concentration in Northeast Asia creates geographic vulnerability for nylon-modified acrylic availability.
- Thermoforming:Vacuum and pressure forming of pre-extruded sheet into packaging trays and equipment housings, constrained by EU F-Gas Regulation on blowing agent selection.
- Blow Molding:Stretch-blow and extrusion-blow processes for hollow containers, capturing beverage bottle and pharmaceutical jar applications with biaxial orientation for clarity enhancement.
- Casting:Cell-cast and continuous-cast methods for premium acrylic sheet with superior optical properties, serving lens and museum glazing applications where surface perfection justifies slower production rates.
- Compression Molding:Matched-die forming for thick-section optical components and thermoset acrylic formulations, occupying niche applications in aerospace and military optics.
Extrusion handles the heaviest volume throughput; Injection Molding is gaining share fastest on medical and automotive precision demands.
Application:
Margin structures diverge dramatically between safety-critical regulated applications and decorative commodity uses, with certification burden determining profitability thresholds.
- Automotive Components:Headlamp lenses, glazing, and interior trim requiring ECE R43 and FMVSS 205 compliance for impact and optical performance. Stuttgart and Detroit suppliers deploy automated spectrophotometry to compress lot-release cycles.
- Medical Devices:Surgical kits, diagnostic housings, and drug delivery components governed by FDA 21 CFR and EU MDR sterile barrier requirements. Blockchain-traceable resin certification is displacing traditional certificate-of-analysis procurement.
- Display Panels:LCD, OLED, and emerging micro-LED substrates where thermal expansion matching and light transmission uniformity are critical. China's integrated resin-to-sheet producers supply Korean and Japanese panel manufacturers.
- Lighting Fixtures:LED lenses, diffusers, and decorative elements where thermal management and color stability under continuous operation determine material selection.
- Protective Equipment:Face shields, safety goggles, and machine guarding where polycarbonate impact resistance outweighs scratch sensitivity in regulatory compliance frameworks.
- Decorative Items:Awards, furniture accents, and architectural features where surface polish and color saturation command aesthetic premiums over functional performance.
Automotive Components absorbs the greatest resin tonnage; Medical Devices shows the steepest expansion trajectory on packaging standard tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of transparent plastics feedstock while the United States and Germany absorb premium optical grades for automotive and medical applications. This production-consumption asymmetry shapes trade flows and regional specialization patterns.
United States
Medical device packaging and automotive headlamp demand pull high-purity polycarbonate and PET grades into Ohio and Michigan manufacturing corridors. FDA food-contact notifications and EPA toxic substance evaluations govern monomer specifications for domestic and export-bound formulations. Gulf Coast petrochemical complexes near Houston anchor captive polyethylene terephthalate capacity serving North American medical and food packaging tiers.
Germany
Automotive lighting and optical instrument manufacturers in Stuttgart specify ECE R43 compliant polycarbonate for headlamp lenses and safety glazing applications. REACH registration requirements and the EU F-Gas Regulation constrain blowing agents and processing aids in thermoforming operations. Chemical parks in Ludwigshafen and Leverkusen host fermentation-derived methyl methacrylate production for bio-based acrylic penetration into premium lens segments.
China
Integrated resin-to-sheet producers in the Yangtze River Delta supply display panel substrates and automotive lighting components to Korean and Japanese electronics manufacturers. GB standards and SAMR quality supervision protocols enforce optical consistency and migration limits for domestic consumption and export-oriented production. Ningbo and Shanghai extrusion clusters concentrate melt filtration capacity for thick-gauge sheet with haze suppression below 1%.
Japan
Camera module and lidar sensor cover integration in vehicles drives specification of optical-grade polycarbonate with anti-reflective coating technologies. METI industrial standards and JIS specifications govern refractive index precision for microscopy and laser optics applications. Chubu region manufacturers around Nagoya supply precision-molded components to domestic automotive and electronics OEMs.
Netherlands
Biorefinery corridors near Rotterdam offer fermentation-derived methyl methacrylate feedstock for premium acrylic applications in signage and decorative lighting. EU extended producer responsibility frameworks including Citeo certification create recycled-content premiums for pharmaceutical packaging tenders. Medical packaging converters in the southern provinces face steep compliance cost escalation from F-Gas Regulation constraints on thermoforming operations.
Global Transparent Plastics Market Competitive Landscape
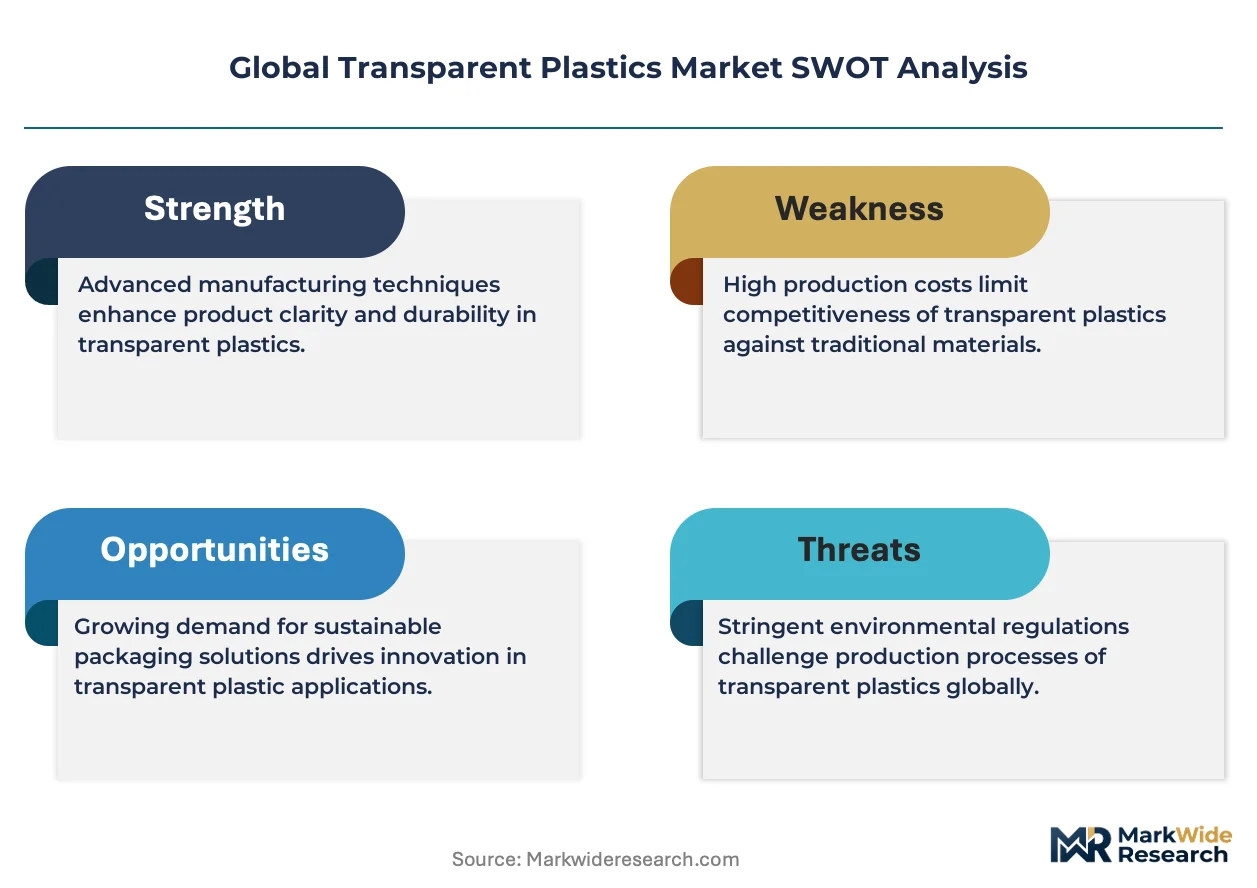
Capital-heavy producers compete with asset-light designers across the transparent plastics value chain. The market structures around three tiers: integrated petrochemical majors with captive resin capacity, specialized optical grade compounders, and regional extrusion converters serving commodity packaging segments. Strategic moves concentrate on backward integration into paraxylene and bisphenol-A feedstock, plus subscription-based digital certification platforms that displace traditional procurement workflows.
Among integrated petrochemical majors, Dow Inc., SABIC, and Covestro AG exemplify divergent specialization patterns. Dow leverages Gulf Coast polyethylene terephthalate capacity to anchor supply for medical device and food packaging applications. SABIC occupies a position emphasizing differentiated polycarbonate formulations for automotive and electronic display segments. Covestro sits within the high-purity optical grade tier, serving lens and sensor cover markets where refractive index precision commands premium positioning.
| Leading Market Players |
|---|
| Dow, Inc. |
| SABIC |
| BASF SE |
| Covestro AG |
| PPG Industries, Inc. |
| LyondellBasell Industries N.V. |
| DuPont de Nemours, Inc. |
| INEOS Group Limited |
| LANXESS AG |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between pharmaceutical optical grades and commodity packaging resins manifests in both pricing power and supply chain configuration, with FDA-cleared and REACH-registered materials commanding contract-based offtake premiums while spot-market PET fluctuates with paraxylene volatility. This bifurcation concentrates margin capture among integrated producers with captive bisphenol-A and purified terephthalic acid capacity, while smaller extrusion converters absorb feedstock cost swings without pricing leverage.
Pricing Analysis
Margin tightening in commodity PET sheet traces to naphtha-cracking economics and deposit-return scheme volatility, while optical-grade polycarbonate maintains pricing stability through long-term medical device contracts. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-traceable pharmaceutical grades from FDA-notified food-contact tiers and uncertified construction sheet. Pricing pressure stems from crude-linked paraxylene swings that compress converter margins without equivalent pass-through. Brand owners in sterile packaging show least price sensitivity; construction glazing buyers exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs and pharmaceutical packagers mandate qualified secondary suppliers for optical-grade polycarbonate and migration-tested PET, preventing single-source concentration despite production clustering. Feedstock production concentrates in China, the United States, and Germany; acrylic monomer supply draws from Northeast Asian caprolactam and methyl methacrylate corridors. Raw material dependencies rest on paraxylene, bisphenol-A, and purified terephthalic acid availability. Tariff exposure on Chinese extruded sheet creates structural risk for European and North American converters. Distribution runs through integrated resin-to-sheet producers directly to Tier 1 automotive and medical device manufacturers, bypassing commodity distributors for certified grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transparent plastics procurement is transitioning from certificate-of-analysis documentation to subscription-based digital certification platforms, with blockchain-traceable resin grades displacing legacy paper-based verification workflows in pharmaceutical and food-contact segments.
For Market Incumbents: Lock in optical-grade certification moats by deepening backward integration into high-purity methyl methacrylate and bisphenol-A feedstock, while deploying machine-vision inline inspection to compress lot-release cycles against emerging software-defined testing entrants. Prioritize REACH registration maintenance and FDA notification currency as regulatory compliance becomes the primary switching cost for pharmaceutical packagers.
For New Entrants and Emerging Players: Capture white-space in bio-based acrylic fermentation from German and Dutch biorefinery corridors, where premium lens applications tolerate higher feedstock costs for sustainability positioning. Target sensor cover convergence in automotive lidar modules as the most penetrable segment, leveraging anti-reflective coating partnerships with Tier 1 lighting suppliers as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized optical-grade compounders possessing haze-suppression below 0.5% capability, given sensor cover demand acceleration and medical packaging standard tightening. Long-term viability favors assets with demonstrated FDA master file access and automotive ECE R43 certification history. Watch for inflection in extended producer responsibility framework adoption across European jurisdictions as the signal for recycled-content premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol-A Feedstock | Captive supply from Gulf Coast complexes anchors margin stability for polycarbonate producers serving medical tiers. |
| Machine-Vision Inline Inspection Deployment | Automated haze verification compresses lot-release cycles from days to hours for Stuttgart automotive suppliers. |
| Fermentation-Derived Methyl Methacrylate Scale-Up | Leverkusen and Rotterdam biorefinery corridors enable bio-based acrylic penetration into premium lens segments. |
| Blockchain-Traceable Resin Certification Platform | Digital verification networks displace certificate-of-analysis procurement for pharmaceutical packaging brand owners. |
| Anti-Reflective Coating Technology Partnership | Sensor cover convergence in lidar modules fuses optical-grade polycarbonate with surface treatment expertise. |
Research Methodology
Multi-period observation of resin grade pricing spreads, regulatory notification timelines, and optical purity certification adoption anchored the trend analysis, supplemented by interviews with extrusion plant managers, pharmaceutical packaging procurement leads, automotive Tier 1 supplier quality directors, and optical grade R&D specialists. Secondary validation drew from FDA food-contact notification databases, ECHA REACH registration filings, SEC 10-K disclosures from integrated petrochemical majors, and customs trade data for paraxylene and bisphenol-A flows. Bottom-up volume modeling across product grades triangulated with top-down demand aggregation from end-use industries.
Segment-weighting applied resin grade tier, end-use industry, processing technology, and regional production hub dimensions across the analysis window. CAGRs derived from fitted growth curves incorporating feedstock cost trajectories, regulatory compliance cost escalation, and substitution elasticity between polycarbonate, PET, and acrylic-polymer blends. Industry-specific forecast inputs included deposit-return scheme expansion rates and automotive lighting content-per-vehicle trends.
The model holds under stable regulatory compliance cost assumptions; deviation in REACH restriction scope or FDA notification processing timelines would shift premium-grade pricing power and segment growth trajectories. A model refresh is warranted upon material change in extended producer responsibility framework adoption or bio-based acrylic production cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Cat Dry Food Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Moveable Water Tap Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Land Surveying Equipment Market
Others
Global Animal Feed Protein Ingredients Market
Others
Africa Lime Market
Others
Latin America Contract Packaging Market
Others
Europe Travel Retail Market
Others
Reef Aquarium Market
Others
Digital Supply Chain Market
Others
Shisha Tobacco Market
Others
5G Edge Computing Market
Others
Latin America Video Conferencing Hardware Market
Others
GCC Shisha Tobacco Market
Others
Global Contactless Biometrics Technology Market