
 Global Enterprise Media Gateway Market | 2026-2036
Global Enterprise Media Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Media Gateway Market Intelligence
The customer base for enterprise media gateways is broadening beyond traditional large telecom providers to include a diverse set of mid-market enterprises. This shift away from concentrated procurement requires vendors to adapt their channel strategies. Cisco Systems leverages its dominant networking footprint to bundle gateway solutions. Ribbon Communications specializes in carrier-grade products for service providers, while AudioCodes Ltd. differentiates through its focus on voice-over-IP technologies.
An enterprise media gateway is a network device that converts media streams between disparate telecommunications networks, such as TDM and IP-based infrastructures. Its core function involves protocol translation, for instance between Session Initiation Protocol (SIP) and traditional circuit-switched voice channels. Cloud-based and virtualized deployments are gaining share over on-premise hardware, offering greater scalability for enterprise clients. Within technology segments, demand for gateways that support integrated Unified Communications and video conferencing protocols is outpacing standalone Voice over IP applications.
Regulatory frameworks from bodies like the US Federal Communications Commission (FCC) and China's Ministry of Industry and Information Technology (MIIT) govern network interoperability and access. In Europe, CE marking ensures hardware safety standards, while GDPR compliance is critical for gateways processing personal data. The evolution toward software-defined and fully virtualized network functions is reshaping competitive positioning. Stakeholder success depends on navigating the transition from hardware-centric models to flexible, software-based service delivery.
Market Dynamics
The central force shaping the enterprise media gateway market is the technological and economic imperative to transition from legacy TDM infrastructure to all-IP networks. This shift compels enterprises to adopt gateways as essential translation devices during multi-year migration projects.
Growth Catalysts
- IP Network Migration:The enterprise-wide replacement of traditional TDM-based private branch exchange (PBX) systems with IP-based platforms necessitates media gateways to bridge communication protocols during the transition.
- Unified Communications Adoption:The integration of voice, video, and data services into a single Unified Communications (UC) platform requires gateways to ensure seamless interoperability with the public switched telephone network (PSTN).
- Infrastructure Modernization:National-level telecommunication infrastructure upgrades, particularly in the United States and China, create large-scale demand for carrier-grade gateways to manage network interconnections.
Market Restraints
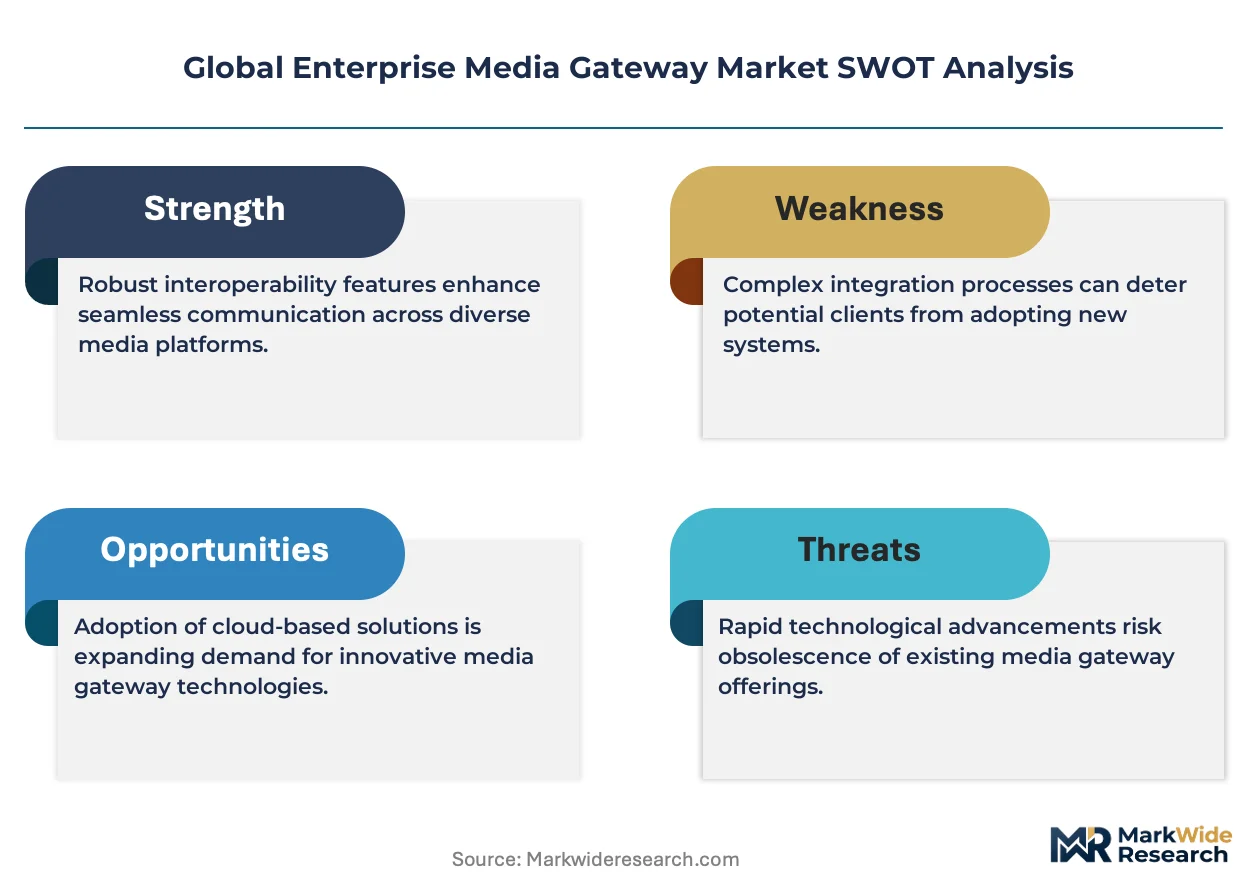
- Substitution by Virtualization:The emergence of fully virtualized, software-based session border controllers and cloud-native functions offers an alternative to dedicated hardware gateways, threatening hardware-centric business models.
- Protocol Complexity:Persistent interoperability issues between different vendor implementations of Session Initiation Protocol (SIP) and legacy protocols increase the complexity and cost of gateway deployment and management.
- Semiconductor Dependence:The reliance on a concentrated group of suppliers for specialized digital signal processors (DSPs) creates potential supply chain vulnerabilities and pricing pressures for hardware gateway manufacturers.
Strategic Opportunities
- Integrated Security Gateways:Developing gateways with embedded security features, such as deep packet inspection and denial-of-service protection, creates a value-added solution for enterprises concerned with VoIP security.
- Mid-Market Expansion:Tailoring smaller-scale, cost-effective gateway appliances for mid-market enterprises that are beginning their journey away from legacy PBX systems represents a significant area for growth.
- Edge Consolidation:Combining media gateway functionality with Session Border Controller (SBC) capabilities into a single device offers enterprises a simplified, consolidated solution for the network edge.
Industry Challenges
- Legacy System Integration:Vendors and integrators face significant difficulty in ensuring new IP gateways can seamlessly connect with decades-old, often poorly documented TDM equipment without causing service disruptions.
- Dual-Skillset Scarcity:A shortage of network engineers possessing deep expertise in both legacy circuit-switched signaling and modern VoIP protocols complicates network migration projects for enterprise clients.
- Regulatory Compliance:Navigating disparate international standards, including FCC interoperability rules in the US and Europe's CE marking for hardware safety, adds overhead to product development and deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Media Gateway Market |
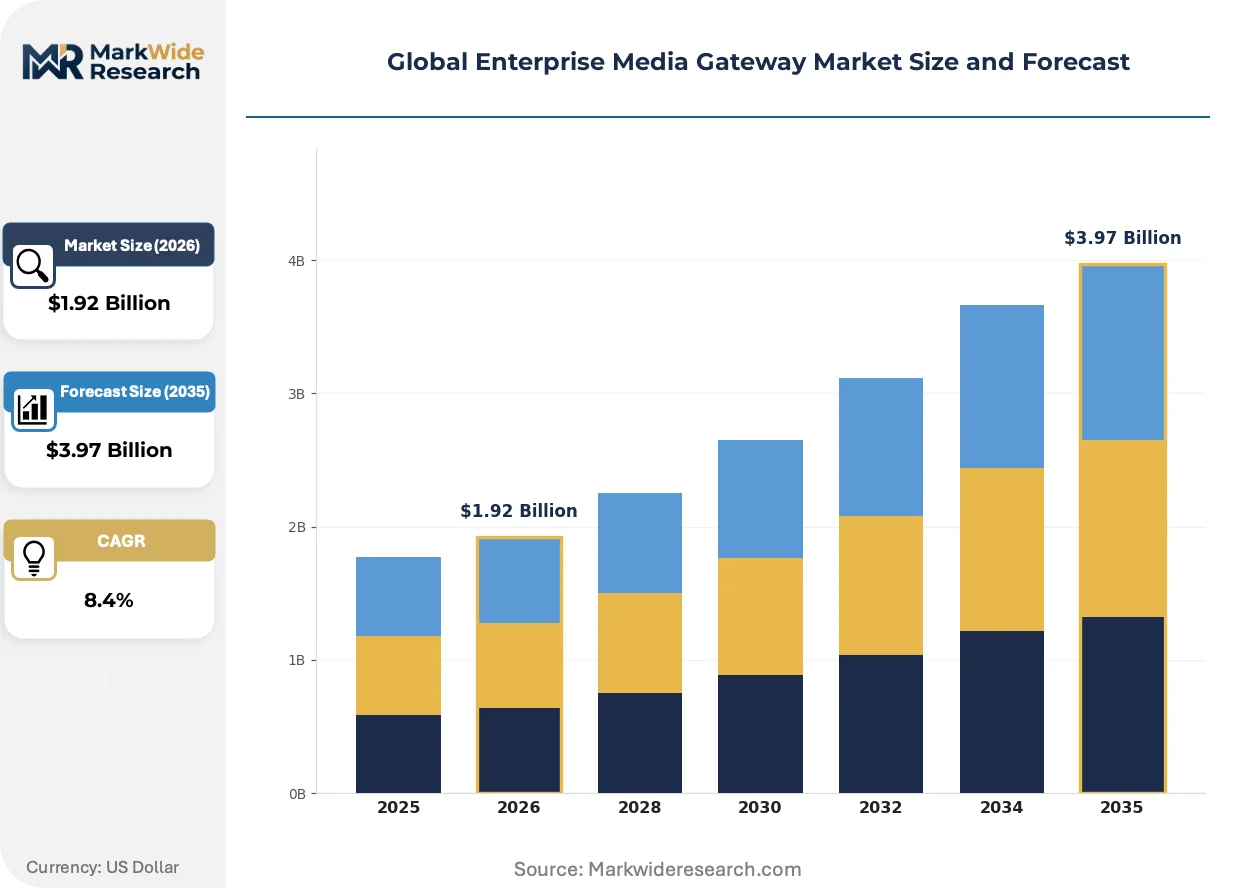
| Market Size in 2026 | $1.92 Billion |
| Market Size in 2035 | $3.97 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Voice over IP, Unified Communications, Video Conferencing, Media Streaming End User: Telecom Providers, IT Departments, Enterprises, Content Providers Deployment: On-Premise, Cloud-Based, Hybrid, Virtualized Service Type: Managed Services, Professional Services, Support Services, Maintenance Services |
| Companies Covered | Ribbon Communications, ZTE Corporation, Huawei Technologies Co. Ltd., Matrix Comsec, Grandstream Networks, Cisco Systems, AudioCodes Ltd., Dialogic Corporation, Avaya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Media Gateway Market Strategic Shifts & Innovations
The evolution from hardware-centric models to flexible, software-based service delivery is the definitive trend. This transition alters vendor business models, enterprise procurement strategies, and the very definition of a network gateway, moving it from a physical box to a virtual function.
Network Function Virtualization (NFV) allows media gateway logic to operate as software on commercial off-the-shelf servers. Service providers and large enterprises are adopting NFV to reduce their reliance on proprietary hardware and increase service agility. Consequently, NFV is absorbing the core functions of dedicated physical appliances into more scalable and cost-effective virtualized or cloud-based data center environments.
Regulatory mandates are accelerating the technology lifecycle. The FCC's framework guiding the retirement of legacy TDM networks in the US provides a clear signal for carriers to accelerate their IP transition plans. This forces carriers to either deploy media gateways as a bridge for their remaining TDM customers or compel those customers to upgrade. The carrier services segment is most impacted, driving investment in gateway capacity.
A clear shift from perpetual hardware purchasing to subscription-based consumption for gateway functionality is underway. This change disrupts the traditional value-added reseller channel, which has historically focused on equipment sales, in favor of cloud marketplaces and direct software-as-a-service models. This consumption pattern is most pronounced in North America, where enterprise preference for operational expenditure models is well-established.
Global Enterprise Media Gateway Market Segmentation
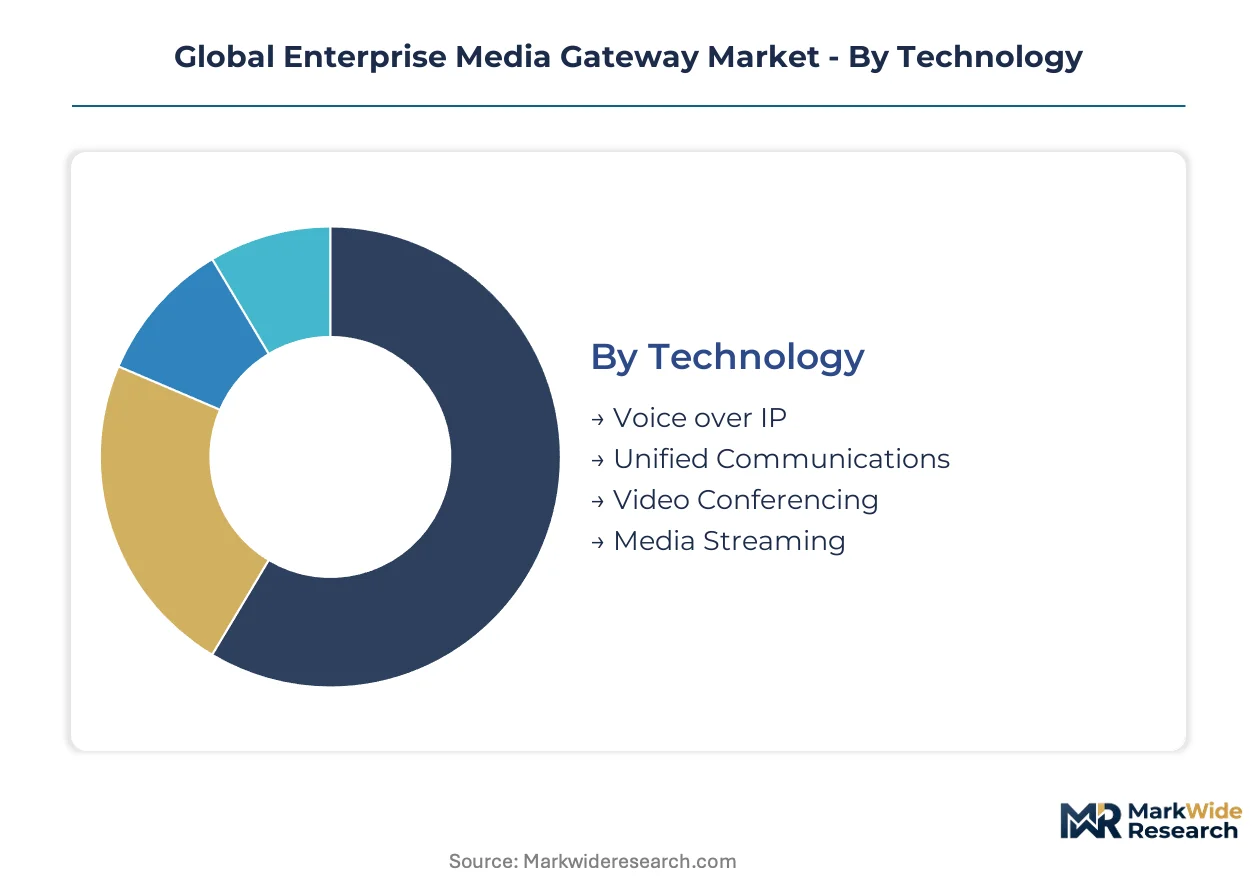
The enterprise media gateway market exhibits distinct segments driven by evolving technological requirements and diverse end-user needs. Understanding these classifications provides clarity on where investment flows and innovation concentrates across the value chain. This detailed segmentation highlights the specific product and service offerings that address varied operational scales and strategic objectives within telecommunications infrastructure.
Technology:
The technology segment differentiates between solutions optimized for high-volume voice traffic and those offering premium integrated communication experiences.
- Voice over IP:This technology converts analog voice signals into digital packets for transmission over IP networks, facilitating cost-effective communication. Demand for these basic translation capabilities remains strong in enterprises transitioning from legacy TDM systems, particularly in regions like the United States where infrastructure upgrades are ongoing.
- Unified Communications:These platforms integrate voice, video, messaging, and presence services into a single user experience, requiring advanced gateway functionality. Adoption is accelerating among large enterprises seeking to consolidate communication tools, driving demand for gateways supporting integrated protocols across global operations.
- Video Conferencing:Gateways supporting video conferencing protocols enable interoperability between disparate video platforms and traditional telecommunication networks. These solutions are critical for organizations with geographically dispersed teams.
- Media Streaming:Solutions in this area handle the conversion and transmission of various media types, ensuring compatibility across different streaming formats and network types. Content providers utilize these gateways for efficient distribution.
Mature deployment sits with Voice over IP. Newer deployment is concentrated in Unified Communications.
End User:
Customer type dictates the scale and complexity of media gateway solutions required, ranging from specialized carrier-grade systems to adaptable enterprise platforms.
- Telecom Providers:These entities deploy carrier-grade media gateways to manage large-scale network interconnections and bridge TDM and IP networks for their subscriber base. National-level telecommunication infrastructure upgrades, particularly in China, create substantial demand for these high-capacity solutions.
- Enterprises:Businesses utilize media gateways to connect their internal IP-based communication systems with external PSTN lines and other IP networks. Mid-market enterprises are increasingly adopting these solutions as they modernize their communication infrastructure, moving away from traditional PBX systems.
- IT Departments:Internal IT departments within organizations procure gateways to manage their specific network infrastructure and ensure seamless communication across various internal systems. These departments prioritize integration capabilities.
- Content Providers:Companies that deliver digital content, such as video or audio streaming services, use media gateways to optimize content delivery across diverse network environments. They focus on bandwidth efficiency and format conversion.
Telecom Providers command significant market share. Enterprises represent the fastest-growing end-user segment.
Deployment:
The deployment model reflects the shift from traditional hardware-centric installations to flexible, software-defined network functions.
- Cloud-Based:This model delivers gateway functionality as a service from a cloud infrastructure, offering scalability and reduced on-premise hardware requirements. Enterprises in North America, driven by preference for operational expenditure models, are increasingly favoring these flexible deployments.
- On-Premise:Hardware-based media gateways are installed directly within the enterprise's data center or communication closet, providing direct control over the infrastructure. Many large organizations with existing legacy systems continue to rely on on-premise solutions during multi-year migration projects.
- Hybrid:Hybrid deployments combine elements of both on-premise and cloud-based solutions, allowing enterprises to leverage existing infrastructure while integrating new cloud services. This model offers a balanced approach for complex IT environments.
- Virtualized:Virtualized gateways operate as software instances on standard server hardware, decoupling the gateway function from proprietary physical appliances. Service providers are adopting virtualization to enhance network agility and reduce hardware footprint.
On-Premise deployments still maintain a significant installed base. Cloud-Based solutions are gaining share fastest.
Service Type:
Service type segmentation highlights the value-added offerings that complement hardware and software solutions, improving operational efficiency and technical support.
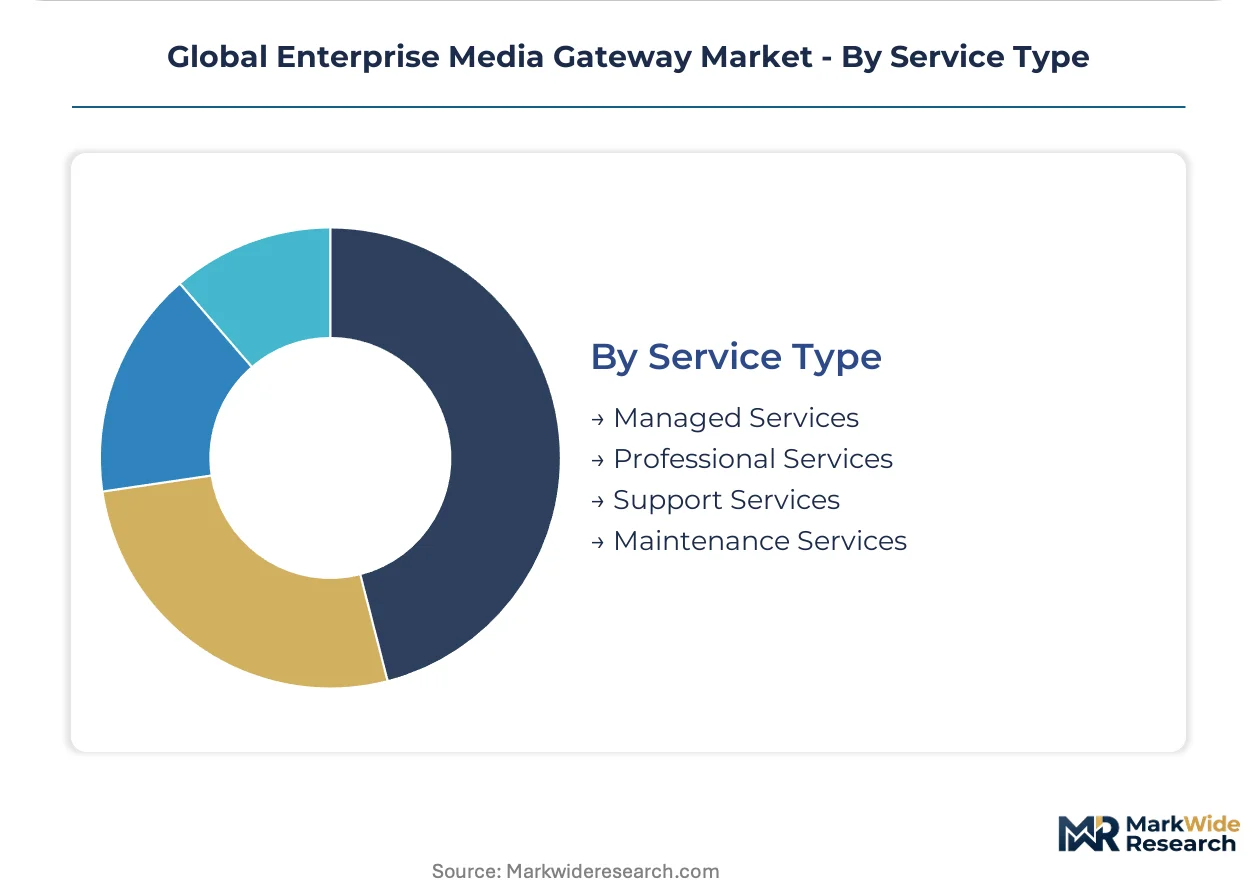
- Managed Services:Third-party providers handle the deployment, monitoring, and maintenance of media gateway infrastructure for enterprises, ensuring optimal performance and uptime. This approach is particularly attractive to mid-market enterprises lacking specialized in-house IT expertise for complex network management.
- Professional Services:These services encompass consulting, system integration, and custom configuration to tailor media gateway solutions to specific enterprise requirements. Organizations undertaking large-scale UC platform rollouts often engage professional services to navigate protocol complexities and ensure seamless integration.
- Support Services:This segment includes technical assistance, troubleshooting, and help desk support for media gateway products. Reliable support is crucial for maintaining continuous communication services.
- Maintenance Services:Maintenance services cover routine inspections, software updates, and hardware repairs to ensure the longevity and optimal functioning of media gateway systems. These services extend the lifespan of deployed infrastructure.
Managed Services offer comprehensive operational support. Professional Services provide specialized integration expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for enterprise media gateways is concentrating in key global economies, driven by significant infrastructure modernization efforts. The United States and China are central to this growth, undertaking large-scale upgrades to their telecommunications networks. This necessitates gateways to bridge legacy and modern IP infrastructures.
United States
United States enterprises are actively migrating from legacy TDM systems to IP-based platforms, necessitating media gateways for protocol translation. The FCC's framework for TDM network retirement accelerates this transition for carriers. Technology hubs like Silicon Valley in California demonstrate strong demand for integrated UC gateway solutions.
China
China's extensive national telecommunication infrastructure upgrades create substantial demand for carrier-grade media gateways. The Ministry of Industry and Information Technology (MIIT) guides policies for network interoperability. Large telecom providers in Beijing are key adopters, managing critical network interconnections.
Germany
German mid-market enterprises are increasingly adopting Unified Communications platforms, driving demand for scalable media gateway solutions. GDPR compliance is a significant regulatory factor for gateways handling personal data within Europe. Industrial regions like Bavaria are seeing infrastructure modernization, favoring hybrid gateway deployments.
United Kingdom
United Kingdom organizations, especially in the public sector, are transitioning towards cloud-based communication services. CE marking regulations ensure hardware safety standards for media gateways deployed across the region. London's financial services industry drives demand for secure, high-performance gateway solutions.
India
India is undergoing rapid digital transformation, leading to significant enterprise adoption of IP networks and UC platforms. The Telecom Regulatory Authority of India (TRAI) guides policies for telecommunication infrastructure development. Technology hubs such as Bengaluru are seeing increased deployment of virtualized gateway solutions for scalable communication.
Global Enterprise Media Gateway Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue cloud-native and virtualized gateway functions. The market structure exhibits a blend of specialized hardware providers and integrated networking giants. Strategic archetypes include carrier-grade solution providers, enterprise Unified Communications specialists, and software-defined networking innovators. Companies are increasingly engaging in strategic partnerships to integrate diverse communication protocols and expanding their service delivery models through subscription-based offerings.
Within the enterprise UC specialists tier, Cisco Systems exemplifies a bundled approach, leveraging its dominant networking footprint to offer integrated gateway solutions to its broad customer base. Ribbon Communications, a US-based corporation, anchors the carrier-grade product segment, focusing on high-capacity solutions tailored for large service providers. AudioCodes Ltd., an Israeli-based company, occupies a position as a voice-over-IP technology specialist, differentiating through its dedicated focus on advanced voice communication protocols and cloud integration capabilities. These players represent the diverse strategic orientations defining the market's competitive dynamics.
| Leading Market Players |
|---|
| Ribbon Communications |
| ZTE Corporation |
| Huawei Technologies Co. Ltd. |
| Matrix Comsec |
| Grandstream Networks |
| Cisco Systems |
| AudioCodes Ltd. |
| Dialogic Corporation |
| Avaya |
Cost & Logistics Intelligence
The transition from hardware-centric models to software-defined network functions simultaneously reshapes cost economics and concentrates supply around specialized software developers and virtualized infrastructure providers. This shift impacts both hardware and service pricing.
Pricing Analysis
Volume-driven sales of traditional hardware gateways now contend with margin pressure from software-based alternatives. Subscription-based consumption models are gaining traction, especially for cloud-based deployments, offering operational expenditure benefits. Price differentiation often stems from customization levels and bundled professional services, with mid-market enterprises exhibiting higher price sensitivity. Cost compression in hardware units intensifies due to virtualization and increased competition.
Supply Chain Analysis
Logistics and freight costs for physical gateway hardware contribute to regional pricing disparities, particularly for specialized components. The supply chain for enterprise media gateways draws from a concentrated group of semiconductor manufacturers in Taiwan and the United States for digital signal processors. A structural risk involves single-source vulnerabilities for these specialized components, impacting hardware availability. Distribution typically runs through value-added resellers and direct sales channels, increasingly complemented by cloud marketplaces for software solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enterprise media gateway market is navigating a critical technology-transition phase, as software-defined networking increasingly replaces legacy hardware-centric deployments. This shift demands strategic reorientation across the value chain.
For Market Incumbents:Anticipate continued erosion of hardware-centric revenue streams by accelerating investment in software-defined network functions and cloud-native solutions. Diversify into managed services for virtualized gateways to counter margin pressure from emerging software-only providers. Leverage existing customer relationships and channel control to cross-sell integrated UC platforms. Prioritize R&D in AI-driven network management to differentiate offerings.
For New Entrants and Emerging Players:Cloud service providers represent a key channel for penetrating the enterprise media gateway market with virtualized offerings. Target underpenetrated mid-market enterprises seeking cost-effective, scalable solutions for their IP migration projects. Emphasize ease of deployment and integration with popular Unified Communications platforms as a go-to-market angle. Focus on specific regional regulatory compliance features to gain traction.
For Investors and Strategic Acquirers:Re-rating potential sits with software-defined networking specialists given the accelerating enterprise shift to virtualized communication infrastructures. Long-term viability hinges on companies that can pivot from hardware sales to recurring software subscriptions and managed services. Identify acquisition targets with strong intellectual property in voice-over-IP protocols or robust cloud integration capabilities. A critical signal to watch is the pace of legacy TDM network retirement in key geographies like the United States.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Gateway Development | Accelerates the transition from physical appliances to flexible, virtualized network functions for enterprises. |
| Subscription Model Rollout | Shifts revenue from one-time hardware sales to predictable, recurring operational expenditures for clients. |
| Integrated SBC Functionality | Simplifies network edge deployments by combining security and media translation for enterprise clients. |
| Mid-Market Focused Appliance | Addresses the specific cost and scalability needs of smaller enterprises migrating from PBX systems. |
| Strategic Cloud Partnerships | Expands distribution and deployment options for virtualized gateways through hyperscaler platforms. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, complemented by primary interviews with industry stakeholders. We engaged Chief Technology Officers, IT procurement specialists, network engineers, and telecom service providers. This approach facilitated a robust bottom-up and top-down triangulation of market size and trends, integrating insights from FCC filings and MIIT reports.
Data-stream reconciliation across multiple sources informed the analytical framework for market projections over the forecast period. Segmentation dimensions included technology, end-user, deployment model, service type, and regional IP migration patterns. Compound annual growth rates were derived from historical data analysis and projected adoption curves. Key inputs included enterprise IT spending trends and Unified Communications platform rollout schedules.
Caveats apply where unforeseen regulatory changes or significant technological disruptions could materially shift the outlook. Forecasts reflect assumptions regarding IP network transition rates and virtualization adoption. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Green Communication Market
Communication Services
Pcaas Market
Communication Services
North America Postal Services Market
Communication Services
Video Managed Services Market
Communication Services
Industrial Communication Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Video Conferencing Market
Communication Services
Walkie Talkie Market
Communication Services
Consumer Communication Services Market
Communication Services
Cloud Communication Platform Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Global Communications Interface Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Postal Services Market