
 Video Conferencing Market | 2026-2036
Video Conferencing Market Size, Share, and Industry Trends Forecast 2026-2036
Video Conferencing Market Intelligence
Healthcare provider usage is expanding as hospitals integrate video conferencing into routine patient workflows. Microsoft leverages its cloud ecosystem to anchor enterprise deployments across regulated industries. Zoom competes through brand recognition and consumer-to-business channel conversion. Owl Labs specializes in intelligent camera hardware that differentiates meeting room experiences.
Video conferencing encompasses real-time audiovisual communication systems transmitting encoded media streams across IP networks with latency thresholds below 150 milliseconds for synchronous interaction. These systems serve commercial and institutional purposes by collapsing geographic distance in decision-making workflows. Software solutions dominate revenue contribution due to recurring subscription economics and rapid feature iteration cycles. Cloud-based deployment captures the fastest expansion trajectory as IT departments abandon on-premises maintenance burdens. Hardware devices retain margin concentration in executive boardroom and large auditorium configurations where acoustic engineering justifies premium positioning.
FCC guidelines in the United States govern broadband quality benchmarks that directly affect service reliability commitments. GDPR in Europe and HIPAA compliance requirements constrain data routing architectures and vendor qualification processes. Stakeholders must monitor regulatory divergence across jurisdictions as sovereignty mandates fragment cloud infrastructure strategies.
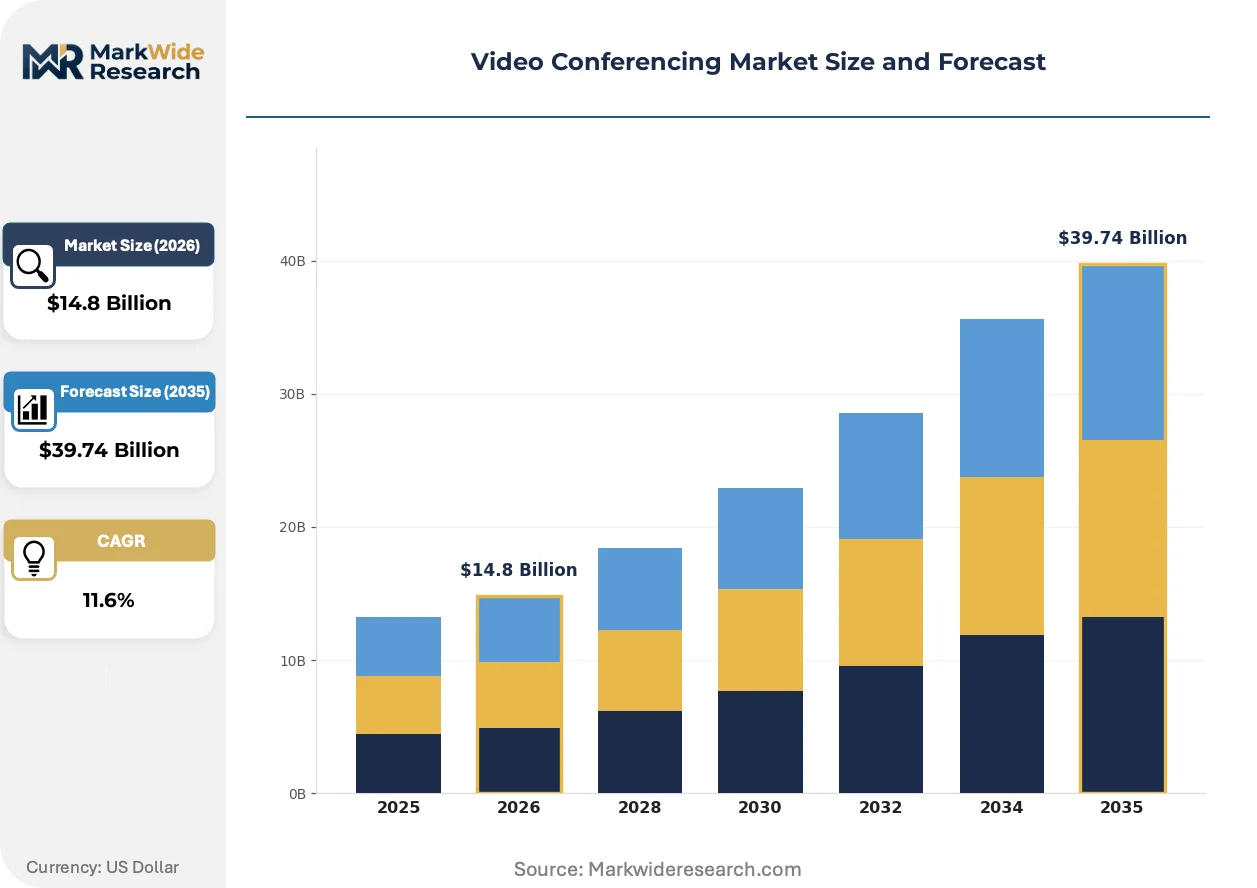
Market Dynamics
Enterprise migration from on-premises PBX systems to cloud-native collaboration platforms is compressing replacement cycles and forcing incumbent vendors to rearchitect pricing models around per-seat subscriptions rather than capital equipment sales.
Growth Catalysts
- HIPAA encryption mandates:United States healthcare providers must deploy end-to-end encrypted platforms for telehealth reimbursement eligibility, accelerating procurement of compliant solutions.
- Hybrid work permanence:Knowledge-intensive sectors in Germany and the United Kingdom have institutionalized distributed team structures, sustaining demand for room systems and personal endpoints.
- AI-powered noise suppression:Machine learning inference at the edge is absorbing ambient acoustic processing, reducing hardware BOM costs for intelligent speakerbars.
Market Restraints
- Semiconductor supply concentration:Taiwan-based foundries dominate image signal processor fabrication, creating vulnerability for camera OEMs during capacity constraints.
- GDPR data residency friction:European enterprises face architectural complexity routing media streams through sovereign cloud regions, inflating deployment costs versus unified global backbones.
- WebRTC performance ceilings:Browser-based real-time communication stacks degrade under packet loss above 2%, limiting adoption in bandwidth-constrained emerging markets.
Strategic Opportunities
- India's digital health infrastructure:The country's national telemedicine guidelines create procurement pathways for cloud-based consultation platforms in tier-2 and tier-3 cities.
- Spatial audio convergence:Integration of head-related transfer function processing with beamforming microphones is absorbing immersive meeting experiences previously requiring dedicated AV integrators.
- CSRD disclosure requirements:European corporate sustainability reporting mandates are forcing enterprises to quantify travel reduction from virtual collaboration, converting carbon accounting into vendor selection criteria.
Industry Challenges
- Interoperability certification backlog:SIP trunking and H.323 gateway testing delays from standards bodies extend enterprise deployment timelines by 4-8 weeks.
- Legacy PBX integration complexity:Financial services firms in the United States maintain hybrid environments requiring session border controllers that increase operational overhead.
- Specialized acoustic engineering talent scarcity:Vendors struggle to hire DSP firmware developers capable of optimizing microphone array algorithms for reverberant spaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Conferencing Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Hardware Devices, Integrated Systems, Cloud Solutions End User: Enterprises, Educational Institutions, Healthcare Providers, Government Agencies Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Feature: Screen Sharing, Recording, Virtual Backgrounds, Real-Time Collaboration |
| Companies Covered | LifeSize, Fuze, Zoom, Kudo, Hopin, Microsoft, Owl Labs, Apizee, Lark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Conferencing Market Strategic Shifts & Innovations
Artificial intelligence inference is migrating from cloud data centers to endpoint devices, compressing latency for real-time features while reducing bandwidth consumption and subscription dependency for core functionality.
Neural processing units embedded in conference room cameras are absorbing computer vision workloads including speaker tracking, occupancy sensing, and automated framing. Large enterprises with distributed real estate portfolios are deploying these systems to reduce IT support tickets for manual camera adjustments. The shift is absorbing functionality previously delivered through separate room control processors.
GDPR's data portability and erasure requirements are reshaping vendor data architectures across European deployments. Service providers must maintain granular audit trails of media stream processing locations. Healthcare and financial services verticals in Germany and France are prioritizing vendors with EU-sovereign infrastructure certifications.
Buyers are unbundling hardware procurement from software subscriptions, treating endpoints as depreciable assets while negotiating shorter-term SaaS commitments. This pattern is most pronounced in United States higher education and state government sectors where capital and operating budgets remain siloed. Channel partners are responding with financing vehicles that bridge the accounting treatment gap.
Video Conferencing Market Segmentation
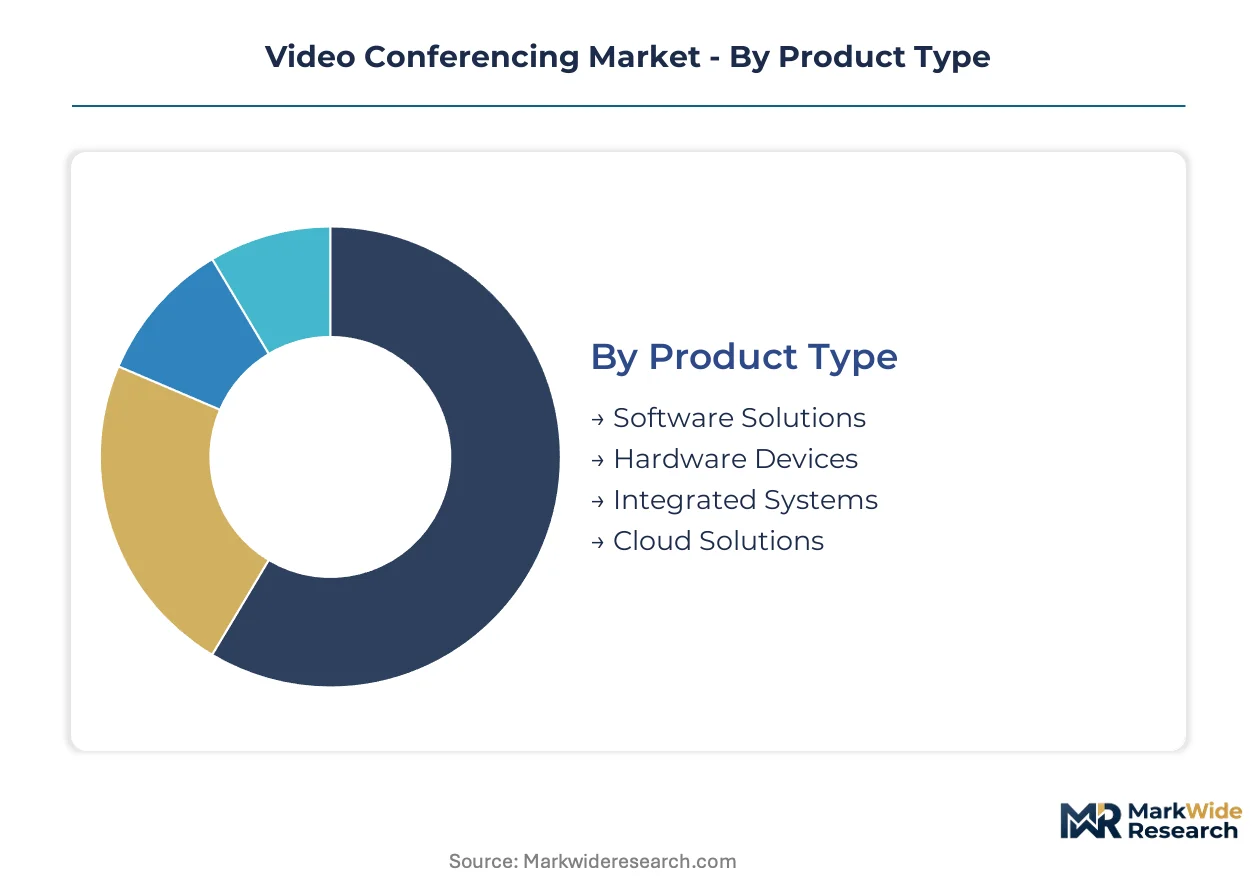
Video conferencing procurement patterns diverge sharply between standalone software subscriptions and deeply embedded enterprise collaboration stacks. Understanding these integration depths reveals why IT departments consolidate vendors in some segments while maintaining specialist suppliers in others.
Product Type:
Integration depth separates components that function as isolated tools from those woven into unified communication suites.
- Software Solutions:Cloud-native applications deliver codec-agnostic connectivity through browser interfaces and dedicated clients. Healthcare providers in the United States select these platforms for HIPAA-compliant telehealth workflows where end-to-end encryption satisfies reimbursement requirements. Procurement concentrates in enterprise licensing agreements with per-seat subscription economics.
- Hardware Devices:Purpose-built endpoints integrate dedicated image signal processors, microphone arrays, and acoustic echo cancellation circuits. German automotive manufacturers deploy these systems in engineering review rooms where reverberant concrete architecture demands specialized beamforming. Premium positioning persists in executive boardrooms where acoustic engineering justifies capital expenditure over software-only alternatives.
- Integrated Systems:Bundled software-hardware combinations reduce deployment complexity for mid-market buyers. Educational institutions in the United Kingdom favor these configurations for rapid classroom rollout without dedicated AV staff.
- Cloud Solutions:Multi-tenant architectures eliminate on-premises infrastructure maintenance. India's tier-2 city hospitals access these deployments through national telemedicine procurement frameworks.
Volume placements concentrate in Software Solutions; the faster expansion belongs to Cloud Solutions.
End User:
Regulatory exposure and procurement authority create distinct buying behaviors across institutional categories.
- Enterprises:Knowledge-intensive sectors maintain distributed team structures requiring room systems and personal endpoints. Hybrid work permanence in Germany and the United Kingdom sustains refresh cycles for both huddle spaces and home office configurations.
- Educational Institutions:Universities and K-12 districts balance capital equipment depreciation against operating budget SaaS commitments. United States state governments separate these funding streams, driving channel partners to develop financing vehicles that bridge accounting treatments.
- Healthcare Providers:HIPAA encryption mandates accelerate compliant platform procurement for telehealth reimbursement eligibility. United States hospitals integrate video conferencing into routine patient workflows for remote consultation and specialist access.
- Government Agencies:Sovereign cloud requirements and data residency constraints dominate vendor qualification. European public sector buyers prioritize EU-sovereign infrastructure certifications under GDPR portability and erasure obligations.
Procurement volume clusters in Enterprises; Healthcare Providers are expanding most quickly.
Deployment:
Architecture choices reflect IT department risk tolerance and legacy infrastructure commitments.
- On-Premises:Self-managed infrastructure persists in financial services firms requiring session border controllers for hybrid PBX environments. United States banks maintain these configurations for regulatory audit trail control.
- Cloud-Based:Multi-tenant services capture IT departments abandoning maintenance burdens. GDPR data residency friction in Europe inflates deployment costs versus unified global backbones, fragmenting vendor strategies.
- Hybrid:Mixed architectures bridge legacy investments and cloud-native capabilities. Manufacturing facilities in China deploy edge nodes for low-latency factory floor communication while routing executive sessions through centralized cloud infrastructure.
- Mobile:Smartphone and tablet clients extend participation beyond fixed endpoints. Field service technicians in India's tier-3 cities rely on these deployments for remote expert consultation under national digital health guidelines.
Cloud-Based deployments dominate new installations; Hybrid architectures are gaining share fastest.
Feature:
Capability differentiation separates commodity connectivity from workflow-embedded collaboration tools.
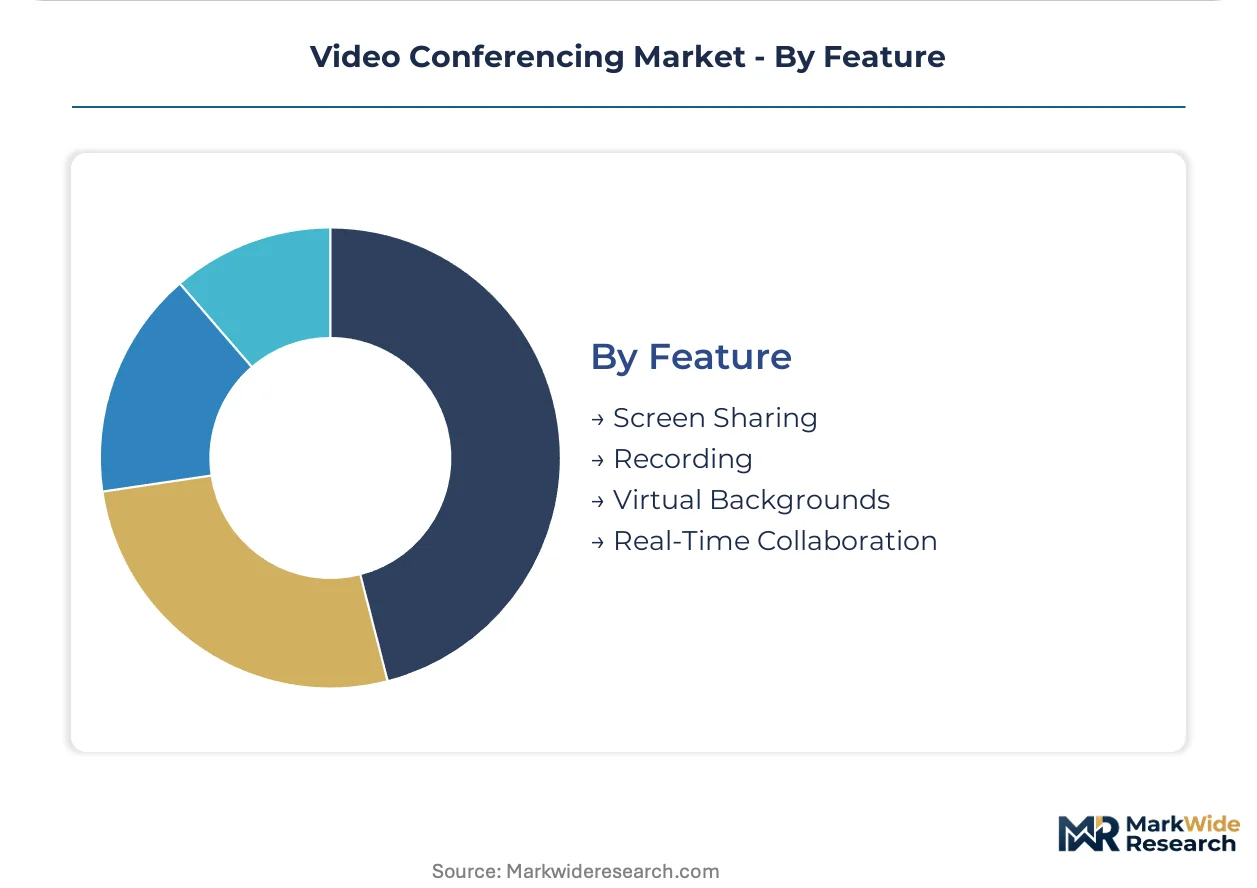
- Screen Sharing:Real-time content transmission enables document co-editing and presentation delivery. Enterprise training departments treat this as baseline functionality rather than competitive differentiator.
- Recording:Persistent media capture supports compliance documentation and asynchronous review. Financial services firms in the United States deploy these capabilities for regulatory examination preparation.
- Virtual Backgrounds:Computer vision segmentation replaces physical environments with digital alternatives. Neural processing units in modern endpoints absorb this workload locally, reducing cloud inference costs.
- Real-Time Collaboration:Integrated whiteboarding, annotation, and document co-creation transform meetings into working sessions. Design teams in Germany's industrial sector select platforms embedding these tools directly into CAD workflow integrations.
Screen Sharing commands the largest installed base; Real-Time Collaboration shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Software Technology Parks of India scheme and China's Hainan Free Trade Port are concentrating cloud infrastructure investment, pulling procurement authority toward Asia-Pacific data center clusters while HIPAA and GDPR compliance requirements fragment vendor qualification pathways across North America and Europe.
United States
Enterprise healthcare systems drive platform procurement for telehealth reimbursement eligibility under HIPAA encryption mandates. FCC broadband quality benchmarks govern service reliability commitments for cross-state deployments. Hospital networks in the Boston-Cambridge corridor integrate video conferencing into specialist consultation workflows.
Germany
Automotive engineering clusters sustain demand for reverberant-space acoustic solutions in concrete-walled design review facilities. GDPR data residency requirements force architectural complexity routing media through sovereign cloud regions. Manufacturing headquarters in Stuttgart and Wolfsburg deploy intelligent camera systems for distributed supplier coordination.
China
State-owned enterprise digitization programs accelerate replacement of legacy telephony infrastructure in tier-1 manufacturing hubs. MIIT cloud service licensing frameworks constrain foreign vendor participation in government procurement. Shenzhen and Hangzhou technology parks host domestic platform development for regional deployment.
India
National telemedicine guidelines create procurement pathways for tier-2 and tier-3 city hospital networks. TRAI broadband penetration targets enable mobile-first consultation platforms in bandwidth-constrained districts. Hyderabad and Bengaluru health-tech clusters incubate localized deployment models.
United Kingdom
Higher education institutions balance capital equipment depreciation against operating budget SaaS commitments in distributed campus configurations. CSRD disclosure requirements convert carbon accounting from virtual collaboration into vendor selection criteria. London and Manchester university systems lead unbundled hardware-software procurement patterns.
Video Conferencing Market Key Industry Players
Top-tier vendors anchor enterprise cloud ecosystems, while mid-market specialists compete through hardware differentiation and vertical-specific compliance certifications. The vendor base stratifies across three archetypes: platform-integrated suites, intelligent endpoint fabricators, and telehealth-compliance specialists. Consolidation pressure is forcing portfolio diversification through strategic partnerships and geographic licensing arrangements rather than pure acquisition activity.
Within the platform-integrated tier, Microsoft leverages cloud ecosystem anchoring across regulated industries, while Zoom competes through brand recognition and consumer-to-business channel conversion. Owl Labs occupies a position exemplifying intelligent camera hardware specialization that differentiates meeting room experiences through acoustic engineering capabilities.
| Leading Market Players |
|---|
| LifeSize |
| Fuze |
| Zoom |
| Kudo |
| Hopin |
| Microsoft |
| Owl Labs |
| Apizee |
| Lark |
| Others |
Cost & Logistics Intelligence
Edge AI inference migration from cloud data centers to endpoint devices is compressing hardware bill-of-material costs while simultaneously concentrating procurement leverage among semiconductor foundries capable of fabricating neural processing units. This technological shift reshapes vendor economics by reducing subscription dependency for core functionality while amplifying supply-side concentration for specialized image signal processors.
Pricing Analysis
Short lead-time premiums for intelligent camera hardware run 15-25% above standard procurement cycles, reflecting Taiwan foundry capacity constraints and just-in-time enterprise deployment schedules. Subscription SaaS tiers dominate software pricing, with HIPAA certification levels and EU-sovereign data residency creating sharp price differentiation between compliant and standard offerings. Cost compression in mid-market hardware is intensifying because AI-powered noise suppression is absorbing acoustic processing previously requiring dedicated DSP chips. Educational institutions in the United States exhibit highest price sensitivity due to siloed capital and operating budgets, while German automotive manufacturers demonstrate lowest sensitivity for reverberant-space acoustic engineering.
Supply Chain Analysis
GDPR portability certifications and HIPAA encryption qualifications gate vendor participation in European healthcare and United States hospital procurement, creating qualification backlogs that extend deployment timelines. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, with image signal processors and neural processing units drawing from concentrated foundry capacity. Microphone array MEMS sensors and acoustic echo cancellation chipsets rest on specialized analog semiconductor supply. Single-source vulnerability in Taiwan-based image signal processor fabrication threatens camera OEM output during capacity constraints. Distribution runs through systems integrators and AV specialists for enterprise room deployments, direct-to-consumer channels for personal endpoints, and national procurement frameworks for India's tier-2 hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-integrated suites as GDPR data residency requirements and HIPAA compliance certification costs force specialist vendors toward strategic partnerships or exit. Smaller hardware fabricators face particular pressure from AI inference migration reducing their differentiation moats.
For Market Incumbents: Acquire specialized acoustic engineering talent pools and DSP firmware development capabilities to defend against AI-powered noise suppression commoditizing intelligent speakerbar hardware. Microsoft and Zoom should prioritize backward integration into sovereign cloud infrastructure for EU data residency compliance, while Owl Labs must secure captive supply of image signal processors through long-term foundry commitments to mitigate Taiwan concentration risk. For New Entrants and Emerging Players: Channel partners specializing in higher education financing vehicles offer the most penetrable entry path, given unbundled hardware-software procurement patterns and siloed budget structures in United States state government sectors. India's tier-2 and tier-3 city hospital networks under national telemedicine guidelines represent underserved white space with lower compliance barriers than tier-1 enterprise deployments. Target vertical-specific compliance certifications as the primary go-to-market angle rather than competing on feature parity. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by platform-integrated suites seeking hardware differentiation or geographic licensing reach, with financial sponsor roll-ups of mid-market AV specialists as secondary liquidity routes. Long-term viability favors vendors with EU-sovereign infrastructure certifications and HIPAA-compliant telehealth workflows, as regulatory divergence fragments cloud strategies. Watch for MIIT cloud service licensing framework enforcement in China as an inflection indicator for foreign vendor participation constraints.| Strategic Initiative | Industry Significance |
|---|---|
| HIPAA Compliance Certification | United States healthcare reimbursement eligibility gates telehealth platform procurement for hospital networks. |
| EU-Sovereign Infrastructure Deployment | GDPR data residency requirements force architectural complexity that inflates deployment costs versus global backbones. |
| Neural Processing Unit Integration | Edge AI inference migration absorbs computer vision workloads previously requiring separate room control processors. |
| Channel Partner Financing Vehicles | Higher education and state government sectors require capital-operating budget bridges for unbundled procurement. |
| Spatial Audio Convergence Development | Head-related transfer function processing with beamforming microphones absorbs immersive experiences from dedicated AV integrators. |
Research Approach
Document review covered hyperscaler capex disclosures, FCC broadband quality benchmarks, SEC filings from platform vendors, and EU regulatory guidance on GDPR data portability, complemented by interviews with CTOs at enterprise healthcare systems, IT procurement officers in German automotive manufacturers, channel partners specializing in education financing, and biomedical engineers integrating telehealth workflows. Secondary validation drew from TRAI broadband penetration reports, CDSCO telemedicine guidelines, and hospital procurement databases. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure deployment tracking.
Historical subscription growth trajectories cross-referenced against panel input from platform vendors and systems integrators anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user vertical, integration depth, and regional regulatory cluster. CAGRs were derived from elasticity modeling against broadband penetration curves and enterprise PBX replacement cycle compression. Industry-specific forecast inputs incorporated HIPAA reimbursement policy evolution and MIIT cloud licensing enforcement patterns.
Caveats apply where semiconductor foundry capacity constraints, GDPR regulatory interpretation shifts, or telehealth reimbursement policy changes could materially shift the outlook. Forecasts reflect assumptions regarding hybrid work permanence and AI inference cost compression trajectories. A model refresh is warranted upon material change in FCC broadband quality benchmark enforcement or EU sovereign cloud certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Push-To-Talk Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Dispatch Console Market
Communication Services
Postal Services Market
Communication Services
Consumer Communication Services Market
Communication Services
Global Communications Interface Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
Audio Conferencing Services Market
Communication Services
Meeting Solutions Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Cloud Communication Platform Market
Communication Services
Pcaas Market
Communication Services
Broadcasting Solutions Market
Communication Services
Global Call Center Platform Market