
 Cloud Video Conferencing Market | 2026-2036
Cloud Video Conferencing Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Video Conferencing Market Analysis
India is tilting toward cloud infrastructure expansion as domestic data center capacity surges to support real-time video workloads. Zoom Video Communications leverages its consumer-brand recognition to anchor enterprise upsell pipelines across Asia-Pacific. Microsoft sustains integration density by embedding video functionality within broader productivity suites. Cisco Systems specializes in hardened security architectures that dominate regulated verticals including healthcare and financial services.
Cloud video conferencing denotes real-time audiovisual communication delivered via internet-hosted infrastructure, typically supporting resolutions from 720p to 4K with latency targets below 150 milliseconds for synchronous interaction. The technology relies on distributed media servers, software-defined networking, and adaptive bitrate algorithms to maintain session quality across variable bandwidth conditions. Public cloud deployment captures the largest revenue pool due to minimal capital requirements and elastic scaling, while hybrid cloud configurations are expanding fastest among enterprises with data residency obligations. Managed services within the service type dimension concentrate margin pools, as ongoing optimization and security monitoring command recurring premiums over one-time professional services engagements.
FCC guidelines on broadband quality benchmarks shape baseline connectivity assumptions for platform design in the United States, while GDPR and the EU AI Act in Europe impose strict processing transparency and automated decision-making constraints on features like real-time transcription and sentiment analysis. ISO 27001 and SOC 2 Type II certifications function as table stakes for vendor qualification in enterprise procurement. Stakeholders must monitor how emerging encryption standards and cross-border data flow restrictions will redefine architectural requirements for multi-tenant platforms.
Market Dynamics
Enterprise IT departments are accelerating migration from legacy on-premises systems to cloud-native platforms, driven by federal hybrid-work mandates and data residency obligations that reshape vendor procurement criteria.
Growth Catalysts
- Federal hybrid-work mandates:United States public-sector procurement continues expanding cloud video conferencing deployments across civilian agencies and defense contractors.
- GDPR and EU AI Act compliance:European enterprises prioritize certified vendors offering automated decision-making transparency for real-time transcription features.
- Adaptive bitrate algorithms:These technologies maintain session quality across variable bandwidth conditions, enabling reliable 4K streaming in emerging markets with infrastructure constraints.
Market Restraints
- Data center energy costs:Real-time video workloads consume substantial compute resources, exposing operators to electricity price volatility in markets dependent on imported natural gas.
- Cross-border data flow restrictions:Fragmented sovereignty requirements force redundant infrastructure investments, compressing margins for multi-tenant platform operators.
- Legacy hardware amortization cycles:Enterprises with sunk capital in on-premises PBX systems delay full cloud migration, extending replacement timelines.
Strategic Opportunities
- India domestic data center expansion:Surging local capacity creates white space for real-time video workloads without latency penalties from offshore routing.
- Healthcare vertical penetration:Telehealth reimbursement permanence under United States Medicare creates durable demand for HIPAA-compliant conferencing architectures.
- Edge computing convergence:Distributed media servers combined with 5G network slicing enable sub-50 millisecond latency for surgical consultation applications.
Industry Challenges
- SOC 2 Type II certification timelines:Vendor qualification processes extend 6-12 months, delaying revenue recognition for new market entrants.
- Legacy system integration complexity:Enterprises struggle to bridge SIP trunking protocols between existing telephony infrastructure and cloud-native APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Video Conferencing Market |
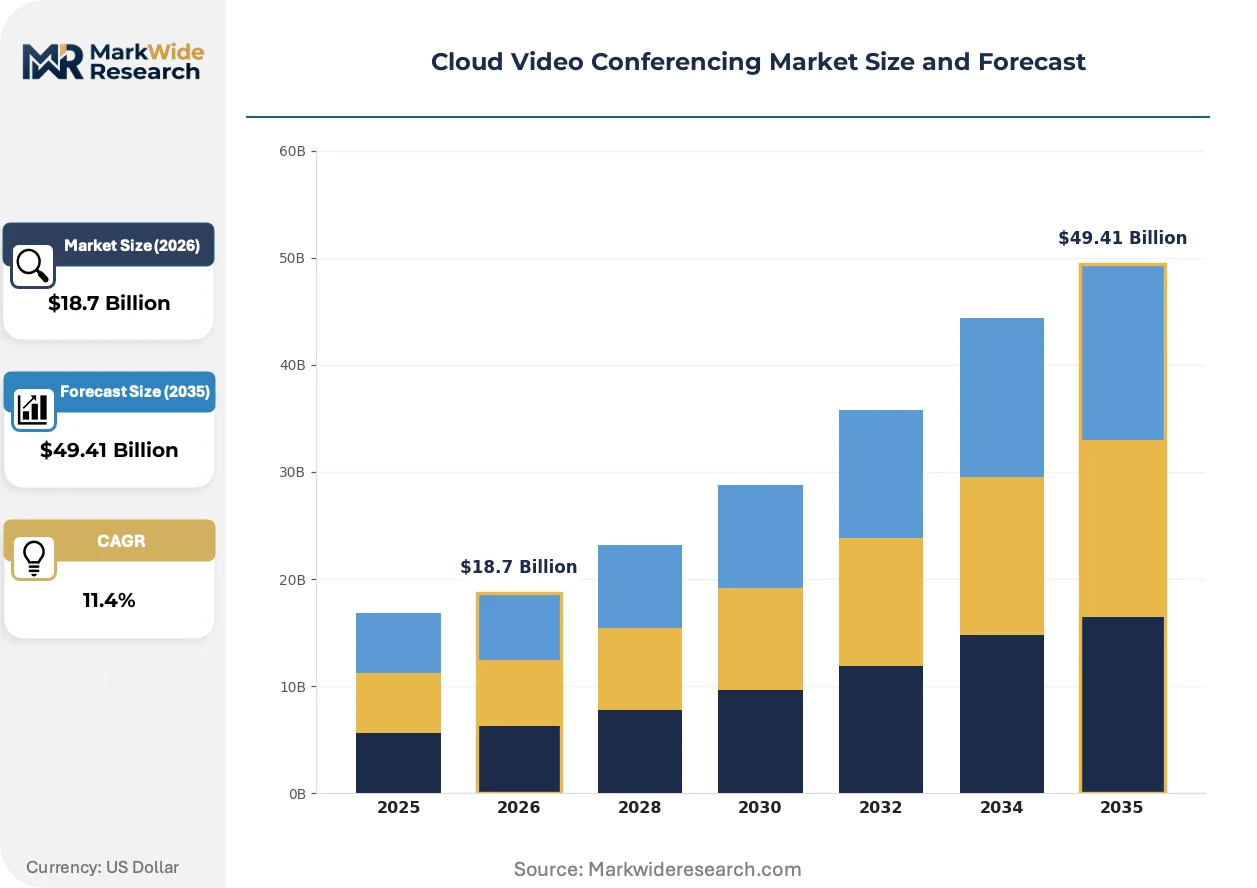
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises End User: Enterprise, Small Business, Educational Institution, Government Service Type: Managed Services, Professional Services, Support Services, API Integration Feature: Screen Sharing, Recording, Virtual Backgrounds, Chat Functionality |
| Companies Covered | Zoom Video Communications, Microsoft, Cisco Systems, Google, BlueJeans Network, Lifesize, Avaya, RingCentral, Pexip, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Video Conferencing Market Emerging Trajectories
Software-defined networking architectures are actively reshaping how media traffic routes across internet exchange points, compressing the distinction between carrier-grade and over-the-top delivery quality.
AI-powered noise suppression and background replacement is collapsing the perceived quality gap between consumer and enterprise-grade endpoints. Financial services contact centers in Singapore and London are deploying these features at scale, eliminating dedicated acoustic treatment investments. The technology is collapsing hardware differentiation as a competitive moat, forcing vendors to compete on security architecture instead.
The EU AI Act imposes strict processing transparency requirements on real-time sentiment analysis and biometric identification features. Vendors must now document algorithmic decision pathways for European deployments, adding compliance engineering overhead. Healthcare and legal verticals within the European Union are responding by demanding on-premise AI inference to maintain data sovereignty.
Subscription fatigue among mid-market buyers is fragmenting procurement authority away from centralized IT departments toward departmental credit-card purchasing. Line-of-business leaders in United States professional services firms now evaluate video tools based on calendar integration speed rather than security certifications. This pattern concentrates most visibly in creative agencies and boutique consultancies where project-based collaboration demands rapid tool deployment.
Cloud Video Conferencing Market Segmentation
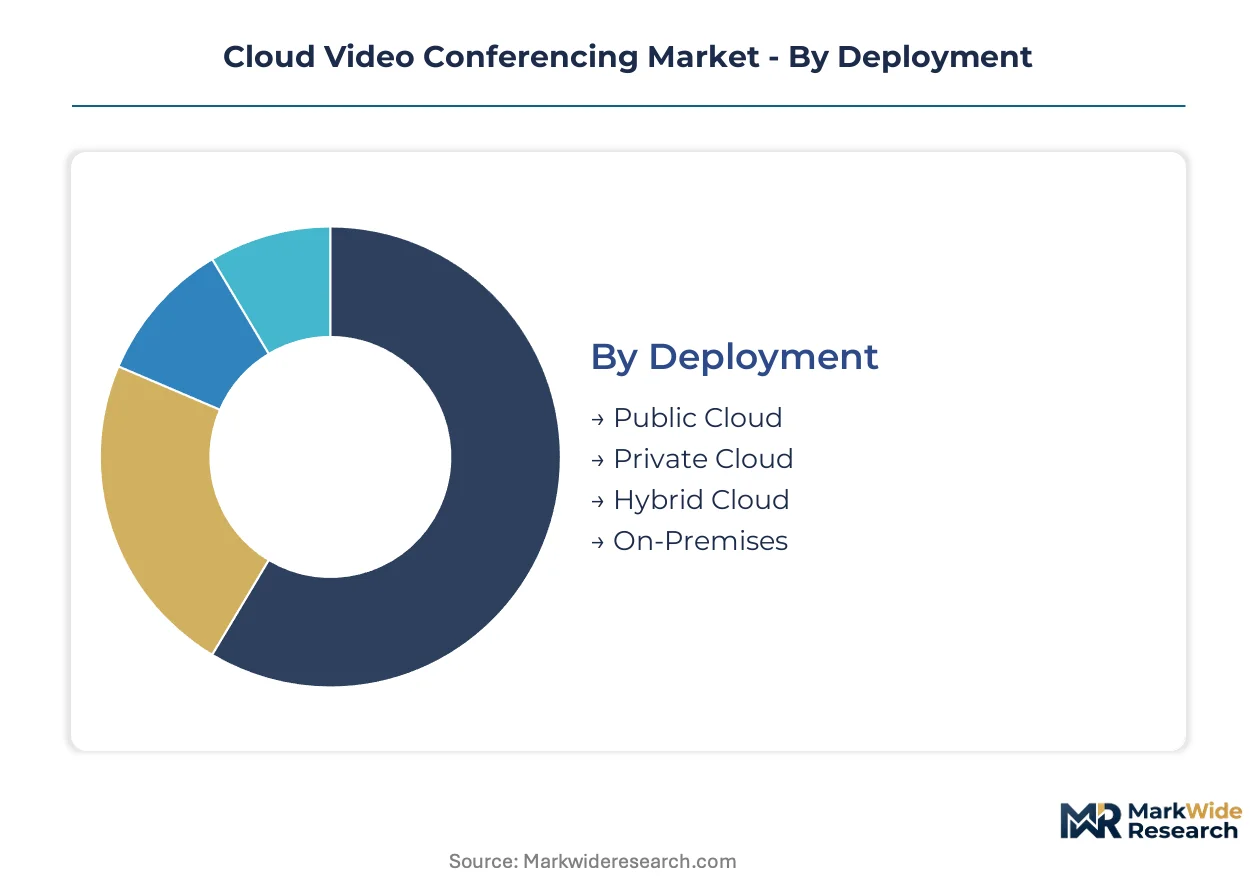
Cloud video conferencing segmentation reveals how procurement authority fragments across infrastructure models, organizational scales, and functional requirements. Vendors must calibrate packaging and pricing to distinct buyer profiles with divergent compliance obligations and latency tolerances.
Deployment:
Mature public cloud offerings dominate procurement volumes, while emerging hybrid configurations capture enterprises navigating data sovereignty mandates.
- Public Cloud:Multi-tenant infrastructure delivers elastic scaling with zero capital expenditure. United States federal agencies drive procurement under hybrid-work mandates, prioritizing FedRAMP authorization over customization depth.
- Hybrid Cloud:Split architectures route sensitive workloads through on-premise nodes while leveraging public cloud for general sessions. European healthcare providers demand this model to satisfy GDPR processing transparency requirements for AI-powered transcription.
- Private Cloud:Single-tenant deployments serve defense contractors and financial institutions with air-gapped security requirements.
- On-Premises:Legacy installations persist where sunk hardware investments delay migration timelines.
Public Cloud retains volume leadership; Hybrid Cloud holds the steepest expansion curve.
End User:
Cost tier stratification separates enterprise buyers with dedicated procurement teams from departmental purchasers operating on discretionary budgets.
- Enterprise:Centralized IT departments negotiate volume contracts with SOC 2 Type II and ISO 27001 certification requirements. United States professional services firms consolidate vendor relationships to reduce subscription sprawl.
- Small Business:Credit-card purchasing dominates, with buyers prioritizing calendar integration speed over security architecture depth. Creative agencies and boutique consultancies drive this segment.
- Educational Institution:K-12 and university procurement favors unlimited participant licensing for lecture capture and remote instruction.
- Government:Civilian and defense contractors mandate FedRAMP or equivalent authorization, extending sales cycles 6-12 months.
Enterprise commands procurement value concentration; Small Business gains share fastest through departmental bypass of centralized IT.
Service Type:
Margin pools concentrate in ongoing operational engagements rather than one-time implementation work.
- Managed Services:Continuous monitoring, optimization, and security patching command recurring premiums. Healthcare verticals in the United States require HIPAA-compliant managed architectures with 99.999% uptime SLAs.
- Professional Services:Custom integration and migration consulting generates project revenue with limited repeatability.
- Support Services:Tiered helpdesk offerings differentiate premium contracts from self-service tiers.
- API Integration:Embedded video functionality for SaaS platforms and custom workflows.
Managed Services captures margin leadership; API Integration follows the steepest adoption trajectory as platform embedding accelerates.
Feature:
Application-specific functionality separates commodity conferencing from differentiated collaboration platforms.
- Screen Sharing:Real-time desktop and application broadcasting with annotation tools. Financial services contact centers in Singapore deploy this for document review sessions with remote clients.
- Recording:Cloud storage with searchable transcripts and compliance retention policies. Legal verticals require immutable audit trails for depositions and client consultations.
- Virtual Backgrounds:AI-powered segmentation eliminates dedicated acoustic treatment investments in contact centers.
- Chat Functionality:Persistent messaging threads with file attachment and emoji reaction support.
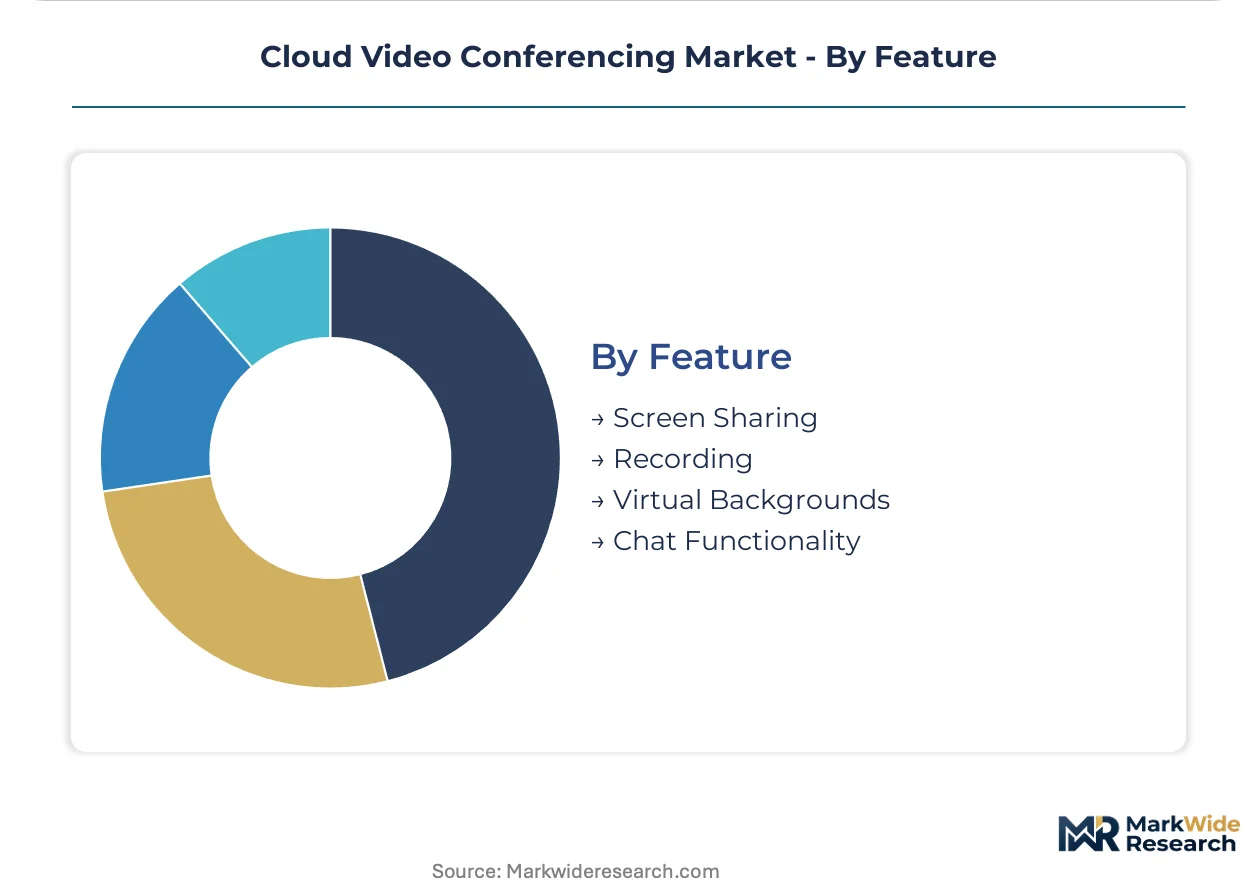
Screen Sharing retains usage frequency leadership; Recording holds the steepest compliance-driven expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform engineering talent clusters in the United States, Germany, India, and Singapore, with each jurisdiction imposing distinct compliance architectures on deployment decisions. Enterprise procurement patterns diverge sharply across these markets based on data sovereignty mandates and federal workforce policies.
United States
Federal hybrid-work directives sustain public-sector procurement velocity across civilian agencies and defense contractors. FCC broadband quality benchmarks shape platform latency assumptions for synchronous 4K sessions. Seattle and San Francisco Bay Area engineering clusters drive adaptive bitrate algorithm development for variable bandwidth conditions.
Germany
Industrial Mittelstand firms demand ISO 27001-certified architectures for cross-border engineering collaboration with automotive suppliers. GDPR processing transparency requirements restrict AI-powered transcription features in manufacturing verticals. Munich and Stuttgart host concentrated deployment of hybrid cloud configurations satisfying data residency obligations.
India
Domestic data center capacity expansion enables real-time video workloads without offshore routing penalties. TRAI infrastructure guidelines accelerate fiber penetration in tier-2 cities for reliable session quality. Bangalore and Hyderabad engineering hubs specialize in distributed media server optimization for emerging market bandwidth constraints.
Singapore
Financial services contact centers deploy AI-powered noise suppression at scale across trading floors and client advisory suites. Monetary Authority of Singapore cybersecurity notices mandate encryption standards for cross-border voice data. The city-state's internet exchange density supports sub-50 millisecond latency targets for regional headquarters operations.
United Kingdom
Professional services firms consolidate vendor relationships to reduce subscription sprawl across London and Manchester offices. Information Commissioner's Office guidance on automated decision-making constrains sentiment analysis deployment in legal verticals. The country's post-EU regulatory divergence creates procurement uncertainty for multinational platform selection.
Cloud Video Conferencing Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying encryption modules, media processing engines, and adaptive streaming protocols. The vendor landscape exhibits tiered concentration with three to five full-stack providers capturing enterprise procurement volume while niche players occupy compliance-specific segments. Two dominant strategic archetypes emerge: productivity-suite bundlers leveraging existing enterprise relationships, and security-first architects targeting regulated verticals. Competitive moves center on FedRAMP authorization acceleration and API ecosystem expansion for embedded video functionality.
Within the productivity-suite tier, Microsoft and Google represent platform bundlers embedding video functionality within broader collaboration stacks. Zoom Video Communications occupies a position exemplifying consumer-brand recognition translated into enterprise upsell pipelines. Cisco Systems anchors the security-specialist archetype, with its naming convention indicating systems-level heritage in hardened network architectures.
| Leading Market Players |
|---|
| Zoom Video Communications |
| Microsoft |
| Cisco Systems |
| BlueJeans Network |
| Lifesize |
| Avaya |
| RingCentral |
| Pexip |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Taiwan Semiconductor Manufacturing for media processing silicon compresses margin buffers across hardware-dependent tiers while simultaneously widening spreads between SOC 2-certified premium offerings and uncertified economy alternatives. FCC broadband quality benchmarks and GDPR processing transparency mandates cascade through procurement specifications, forcing tiered compliance investments that reshape vendor cost structures and buyer qualification timelines.
Pricing Analysis
FedRAMP authorization dictates the pricing tier structure for United States public-sector deployments, separating premium federal-grade subscriptions from standard commercial licenses and economy self-serve tiers lacking compliance documentation. Price differentiation centers on certification depth and managed service bundling, with HIPAA-compliant healthcare architectures commanding substantial premiums over basic conferencing licenses. Pricing pressure intensifies as departmental credit-card purchasing in mid-market professional services firms collapses willingness-to-pay for security-heavy packages. Small business buyers exhibit highest price sensitivity, prioritizing calendar integration speed over architectural hardening, while defense contractors demonstrate lowest sensitivity given mandate-driven procurement authority.
Supply Chain Analysis
Upstream silicon feedstock for media encoding engines concentrates in Taiwan, South Korea, and the United States, with advanced node fabrication for real-time video processing chips resting on TSMC's foundry dominance. Software-defined networking components draw from Chinese optical module suppliers and German precision manufacturing for edge server chassis. Tariff exposure on Chinese-manufactured networking hardware threatens margin stability for price-competitive tiers. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with API-first vendors embedding through SaaS platform partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud video conferencing represents a platform-economics inflection where API ecosystem density and calendar-native deployment velocity displace standalone security certifications as primary procurement filters. Interoperability with Microsoft 365 and Google Workspace productivity graphs now determines vendor survival more than feature parity.
For Market Incumbents: Build switching-cost moats through deep API integration into line-of-business workflows rather than standalone conferencing features. Incumbents must accelerate FedRAMP authorization velocity to defend federal procurement share against emerging security-first specialists. Vertical integration into edge computing infrastructure offers margin protection against hyperscaler commoditization of core video transport. For New Entrants and Emerging Players: Build out HIPAA-compliant managed service architectures targeting United States telehealth reimbursement permanence as the most penetrable white-space segment. India domestic data center expansion creates geographic arbitrage opportunity for latency-optimized regional offerings. New entrants should pursue platform embedding partnerships with project management SaaS vendors rather than direct enterprise sales competition. For Investors and Strategic Acquirers: Security-architecture specialists with existing FedRAMP authorization and healthcare vertical penetration represent the highest-conviction acquisition target archetype for platform bundlers seeking regulated-market credibility. Long-term viability hinges on sustaining API ecosystem density against productivity-suite consolidation. Investors should monitor departmental credit-card purchasing penetration rates as the critical inflection signal for pricing power erosion in mid-market segments.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Unlocks United States federal procurement pipelines worth billions under hybrid-work mandates. |
| API Ecosystem Expansion | Embeds video functionality into SaaS platforms, capturing recurring revenue through platform partnerships. |
| Edge Computing Infrastructure Deployment | Enables sub-50 millisecond latency for surgical consultation and financial trading applications. |
| Healthcare Vertical Specialization | Captures telehealth reimbursement permanence under Medicare with HIPAA-compliant architectures. |
| Hybrid Cloud Configuration Development | Satisfies GDPR data residency obligations for European healthcare and legal verticals. |
Methodological Framework
Cross-validation between primary interviews with enterprise IT procurement officers, platform engineering leads, and healthcare technology directors anchors the qualitative findings against secondary validation from SEC filings of public conferencing vendors, hyperscaler capex disclosures, and FCC broadband deployment reports. Bottom-up triangulation aggregates deployment volumes across organization size tiers while top-down calibration benchmarks against federal procurement databases and European enterprise software spending surveys.
Calibration against historical adoption curves for SaaS productivity tools refines the analytical framework across deployment models, end-user scales, service types, and feature requirements throughout the forecast period. CAGRs derive from segment-level growth rate convergence modeling with elasticity adjustments for compliance cost pass-through. Industry-specific inputs include TRAI fiber penetration data for India infrastructure buildout and Medicare telehealth reimbursement policy durability assumptions.
Sensitivities concentrate around cross-border data flow restriction expansion, electricity price volatility in European data center markets, and departmental purchasing authority fragmentation in mid-market professional services. Forecasts reflect documented assumptions on federal hybrid-work mandate continuity and AI Act implementation timelines. Cross-checking against hyperscaler earnings call commentary on video infrastructure investment is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
Express Digitizer Market
Digital Solutions
India PLM Market
Digital Solutions
Virtual Closet Market
Digital Solutions
Governed Enterprise Architecture Scenario Sandbox Market
Digital Solutions
North America API Management Market
Digital Solutions
UK and Germany Diet and Nutrition Apps Market
Digital Solutions
Track and Trace Solutions Market
Digital Solutions
Video Management System Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Model Based Enterprise Market
Digital Solutions
Route Optimization Software Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
European Digital Transaction Management Software Market