
 Industrial Communication Market | 2026-2036
Industrial Communication Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Communication Market Intelligence
Deterministic-grade network reliability is unwinding legacy fieldbus dependencies across heavy process industries. Siemens AG leverages deep vertical integration in programmable automation controllers to sustain installed-base loyalty. Belden Inc. anchors North American manufacturing with specialized industrial cabling and switch portfolios. Huawei Technologies Co., Ltd. competes aggressively on 5G private network solutions for smart factory deployments.
Industrial communication encompasses hardware, protocols, and software systems that enable deterministic data exchange between sensors, controllers, and enterprise systems in mission-critical environments, typically operating with latency below one millisecond and redundancy tolerances of 99.999% uptime. Its primary purpose is synchronizing physical production processes with digital control layers to eliminate unplanned downtime. Industrial Ethernet now leads product type revenue as TSN compatibility displaces legacy PROFIBUS and DeviceNet installations. Wireless communication represents the fastest-expanding segment, though margin pools remain thinner due to interoperability certification burdens. Factory automation applications command the largest share of protocol licensing fees, while energy management applications show the steepest growth trajectory in utility-scale deployments.
IEC 62443 cybersecurity frameworks and IEEE 802.1 TSN standards shape product roadmaps by mandating encrypted device authentication and time-synchronized packet delivery. The EU Cyber Resilience Act and China's GB/T standards for industrial control systems are tightening market access requirements for non-compliant vendors. Stakeholders must weigh backward integration into semiconductor supply chains against protocol-agnostic software strategies as qualification timelines lengthen.
Market Dynamics
The convergence of deterministic Ethernet with wireless backhaul is restructuring procurement priorities across heavy process industries, forcing vendors to recalibrate protocol compatibility roadmaps against tightening cybersecurity mandates.
Growth Catalysts
- IEC 62443 Mandates:The IEC 62443 cybersecurity framework is hardening device authentication requirements across power generation and oil & gas installations, compelling infrastructure upgrades that favor encrypted industrial Ethernet switches over legacy fieldbus architectures.
- Automotive Assembly Modernization:German and Chinese automotive OEMs are deploying TSN-enabled backbone networks to synchronize robotic welding cells with sub-millisecond precision, creating sustained protocol licensing demand.
- 5G Private Network Spectrum Allocation:China's MIIT and Germany's BNetzA have released localized spectrum bands for industrial 5G, enabling brownfield factories to bypass cabling constraints in sprawling process plants.
Market Restraints
- Silicon Supply Concentration:Advanced industrial Ethernet PHYs and TSN-capable switch ASICs depend on Taiwanese and South Korean foundry capacity, exposing lead times to geopolitical friction.
- Interoperability Certification Burden:Wireless sensor networks face prolonged conformance testing against IEC 62591 and ISA100.11a standards, delaying commercial deployment and compressing vendor margins.
- PROFIBUS Installed Base Lock-In:Decades of DeviceNet and PROFIBUS deployment in petrochemical complexes create switching costs that resist Ethernet migration despite superior bandwidth economics.
Strategic Opportunities
- India's Smart Factory Incentives:India's PLI scheme for electronics manufacturing is attracting industrial communication vendors to establish local production for textile and pharmaceutical automation clusters.
- Edge-AI Convergence:The fusion of TSN time synchronization with GPU-accelerated edge inference is opening new protocol licensing streams for predictive maintenance applications in steel and cement plants.
- Energy Management Vertical:Utility-scale solar and wind farms are mandating IEC 61850-9-2 process bus implementations, creating demand for sampled value publishing over Ethernet in substation automation.
Industry Challenges
- TSN Configuration Expertise Gap:Network engineering talent capable of tuning IEEE 802.1Qbv time-aware shapers and 802.1AS clock synchronization remains scarce across system integrator channels.
- Legacy Brownfield Integration:Retrofitting EtherNet/IP or PROFINET into plants with 20-year-old Modbus RTU architectures demands costly protocol gateways that complicate fault diagnostics.
- Cybersecurity Compliance Timelines:Achieving IEC 62443-3-3 SL-3 certification for safety instrumented systems extends product development cycles by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Communication Market |
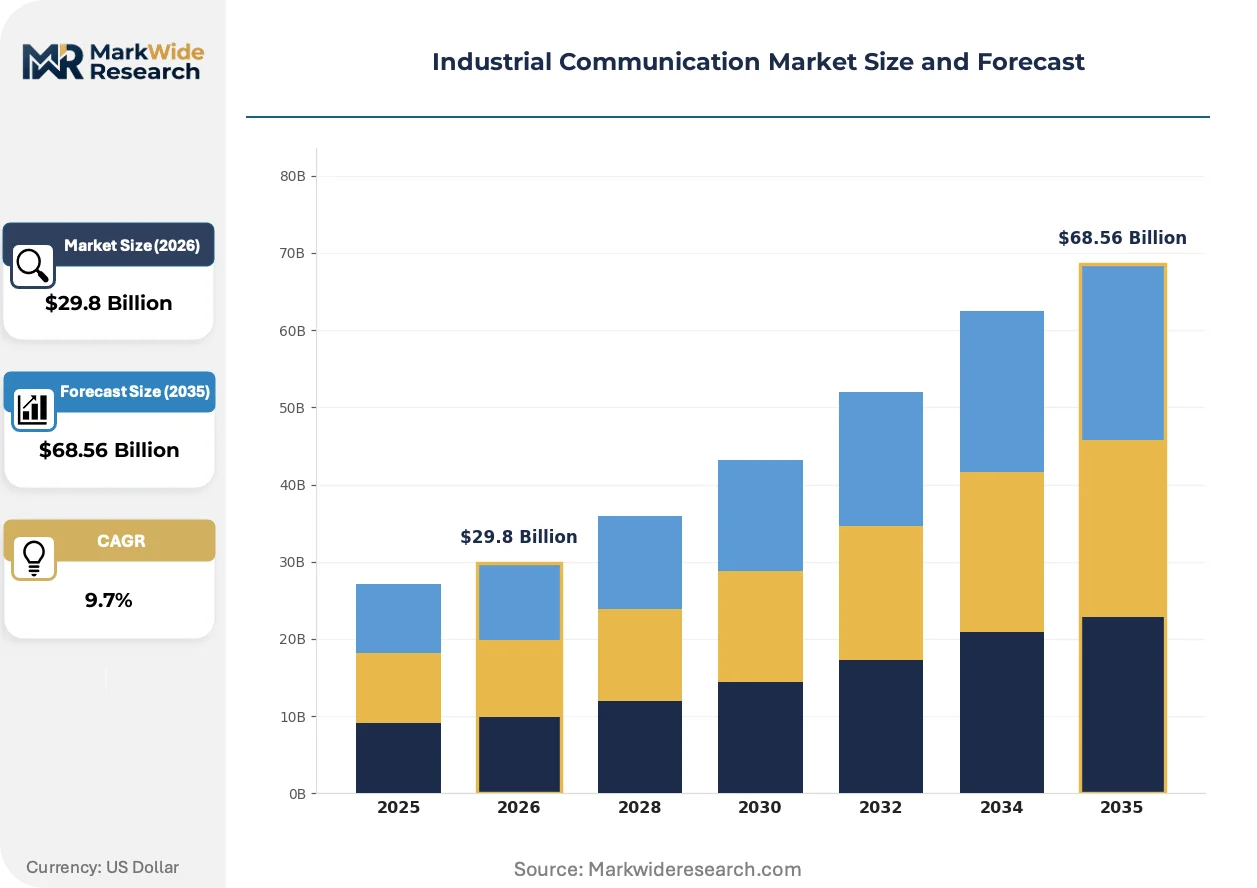
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $68.56 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fieldbus, Industrial Ethernet, Wireless Communication, Industrial IoT Gateways Communication Protocol: PROFINET, Modbus, EtherCAT, FOUNDATION Fieldbus, CANopen Application: Process Automation, Factory Automation, Energy Management, Building Automation, Transportation Systems End User: Manufacturing Plants, Energy Providers, Facility Management, Transportation Operators |
| Companies Covered | Cisco Systems, Inc., Siemens AG, Rockwell Automation, Inc., Schneider Electric SE, ABB Ltd., OMRON Corporation, Huawei Technologies Co., Ltd., Belden Inc., Moxa Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Communication Market Strategic Shifts & Innovations
Deterministic networking technologies are bifurcating into hardened real-time Ethernet cores and flexible wireless peripheries, with standardization bodies racing to harmonize security and synchronization requirements across both domains.
Time-Sensitive Networking is fragmenting the industrial switching landscape by enabling converged traffic classes—control loops, video analytics, and enterprise IT—on shared copper and fiber infrastructure. Automotive powertrain manufacturers in Stuttgart and Wolfsburg are deploying TSN-enabled backbone networks to replace parallel fieldbus and safety bus architectures. This convergence is compressing switch port counts per production line while elevating software-defined network management to a primary procurement criterion.
The EU Cyber Resilience Act is mandating vulnerability disclosure and automatic update mechanisms for industrial communication devices sold in member states. Hardware vendors must now embed secure boot chains and signed firmware pipelines that extend development timelines but create compliance differentiation against non-European competitors. Process industries in Rotterdam and Antwerp are prioritizing CRAct-certified switches for new refinery and chemical complex builds.
Buyer preference is pivoting toward protocol-agnostic software platforms that abstract physical layer dependencies through unified configuration environments. System integrators in Detroit and Shanghai are unbundling hardware procurement from engineering services, favoring vendors offering cloud-hosted device management portals. This disintermediation is most pronounced in automotive and consumer electronics assembly, where line reconfiguration frequency exceeds traditional vendor support contract cycles.
Industrial Communication Market Segmentation
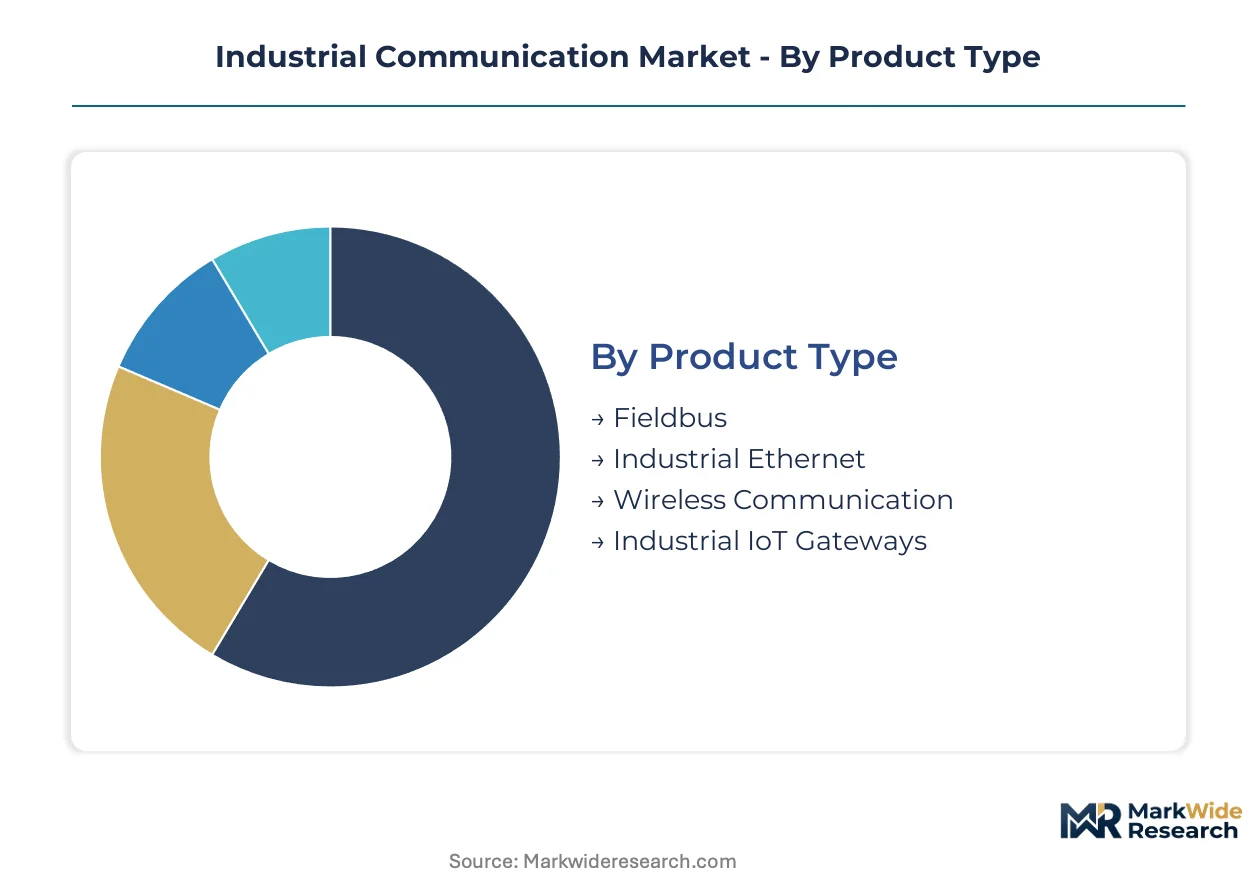
Industrial communication segmentation reveals how deterministic performance requirements and cybersecurity mandates reshape procurement across hardware, protocol, and application layers. Buyers increasingly weight protocol compatibility against long-term migration costs.
Product Type:
Substitution pressure intensifies as TSN-capable Ethernet displaces legacy fieldbus architectures in brownfield process plants.
- Fieldbus:Legacy serial protocols including PROFIBUS and DeviceNet dominate petrochemical and water treatment installations with decades of embedded instrumentation. European refineries in Rotterdam and Antwerp resist migration despite bandwidth limitations, fearing operational disruption during protocol transitions.
- Industrial Ethernet:Switched Ethernet with deterministic extensions now anchors new automotive and semiconductor fab deployments. German automotive OEMs in Stuttgart and Wolfsburg specify TSN-enabled backbone networks to synchronize robotic cells with sub-millisecond precision.
- Wireless Communication:5G private networks and Wi-Fi 6 industrial variants enable mobile robotics and condition monitoring without cabling constraints.
- Industrial IoT Gateways:Edge aggregation devices bridge operational technology networks to enterprise cloud platforms.
Industrial Ethernet retains volume leadership; Wireless Communication holds the steepest expansion curve.
Communication Protocol:
Cost tier stratification separates premium deterministic protocols from economy-positioned fieldbus alternatives in procurement specifications.
- PROFINET:Siemens-backed industrial Ethernet protocol with integrated safety and motion control extensions. Chinese automotive battery plants in Ningbo and Changzhou specify PROFINET IRT for gigabit-speed synchronized drives.
- Modbus:Ubiquitous serial and TCP-based protocol maintaining presence through simplicity and minimal licensing fees.
- EtherCAT:Beckhoff-developed Ethernet protocol with distributed clock synchronization for high-speed motion control.
- FOUNDATION Fieldbus:Process-industry protocol with intrinsic safety and device diagnostics for hazardous environments.
- CANopen:Controller Area Network protocol optimized for embedded motion control in packaging machinery and medical devices.
PROFINET commands the largest installed base; EtherCAT gains share fastest in precision motion applications.
Application:
Application maturity varies sharply between established factory automation and emerging energy management verticals with divergent certification requirements.
- Process Automation:Continuous manufacturing control in oil, gas, chemicals, and pharmaceuticals with 99.999% uptime mandates. US Gulf Coast refineries under EPA and OSHA jurisdiction prioritize IEC 62443-certified networks for safety instrumented systems.
- Factory Automation:Discrete manufacturing with high-velocity reconfiguration demands. Japanese electronics assemblers in Osaka and Nagoya deploy protocol-agnostic software platforms to compress line changeover intervals.
- Energy Management:Grid-scale solar, wind, and substation automation requiring IEC 61850-9-2 process bus implementations.
- Building Automation:HVAC, lighting, and access control integration with BACnet and LonWorks protocols.
- Transportation Systems:Railway signaling and port logistics with EN 50159 safety communications requirements.
Factory Automation sustains the broadest protocol licensing revenue; Energy Management climbs the fastest on utility-scale renewable deployments.
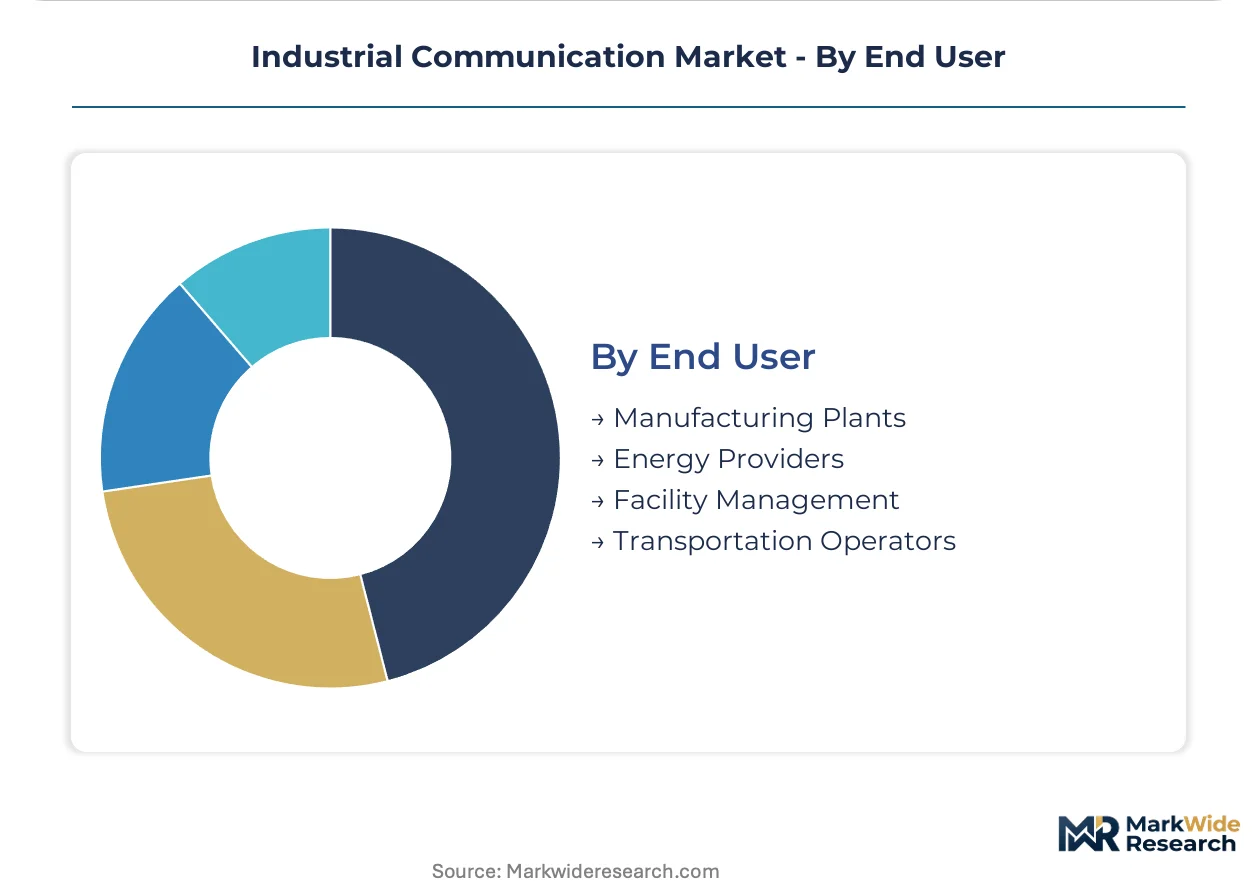
End User:
Customer type determines procurement centralization, with energy providers imposing stringent vendor qualification against manufacturing plant decentralized purchasing.
- Manufacturing Plants:Automotive, electronics, and food processing facilities with line-specific network engineering autonomy. Indian textile clusters in Surat and Tiruppur leverage PLI scheme incentives to deploy first-generation industrial Ethernet.
- Energy Providers:Electric utilities and oil majors with enterprise-wide cybersecurity governance. German transmission operators under BNetzA regulation mandate IEC 62443-3-3 SL-3 certification for substation communication.
- Facility Management:Commercial and industrial building operators prioritizing interoperability over deterministic performance.
- Transportation Operators:Railway authorities and port authorities with safety-critical communication mandates.
Manufacturing Plants generate the highest transaction volume; Energy Providers impose the most rigorous compliance barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial communication equipment flows from German and Chinese manufacturing hubs toward import-dependent automation markets in India and Southeast Asia. Export strength concentrates where TSN semiconductor supply chains and automotive OEM demand overlap.
Germany
Automotive powertrain manufacturers in Stuttgart and Wolfsburg drive TSN backbone deployments for robotic welding synchronization. BNetzA spectrum allocation for industrial 5G enables brownfield factories to bypass cabling constraints. The Ruhr Valley chemical corridor resists Ethernet migration despite IEC 62443 mandates, preserving PROFIBUS dependencies in legacy petrochemical installations.
China
Battery plant construction in Ningbo and Changzhou generates sustained demand for gigabit-speed synchronized drive networks. MIIT localized spectrum releases for private 5G networks accelerate wireless adoption in sprawling steel and cement complexes. Yangtze River Delta electronics assemblers deploy protocol-agnostic software platforms to compress line reconfiguration cycles.
United States
Gulf Coast refineries under EPA and OSHA jurisdiction prioritize IEC 62443-certified networks for safety instrumented systems. Detroit automotive system integrators unbundle hardware procurement from engineering services, favoring cloud-hosted device management portals. Silicon Valley semiconductor fabs anchor North American demand for deterministic Ethernet switch ports.
India
PLI scheme incentives attract industrial communication vendors to establish local production for Surat and Tiruppur textile automation clusters. CEA grid modernization mandates drive IEC 61850-9-2 process bus implementations in utility-scale solar farms. Maharashtra pharmaceutical manufacturers deploy first-generation industrial Ethernet under electronics manufacturing incentive programs.
Japan
Osaka and Nagoya electronics assemblers leverage protocol-agnostic platforms to accelerate line changeover intervals. METI standardization support for TSN interoperability reduces conformance testing burdens for domestic switch vendors. Kyushu semiconductor material plants integrate edge-AI convergence with time-synchronized packet delivery for predictive maintenance.
Industrial Communication Market Key Industry Players
Listed leaders compete with private specialists across protocol licensing and embedded software stacks, creating a tiered structure where scale-driven Ethernet switch vendors face focused fieldbus gateway providers. Siemens AG and Cisco Systems anchor the premium tier through deep automation controller integration and enterprise IT convergence. Three archetypes dominate: diversified industrial conglomerates with captive semiconductor supply, specialized communication hardware vendors with regional manufacturing footprints, and emerging private network specialists leveraging 5G spectrum access. Competitive moves center on backward integration into TSN-capable ASIC design and strategic partnerships with automotive OEMs for backbone specification lock-in.
Within the diversified industrial tier, Siemens AG exemplifies vertical integration through programmable automation controller ecosystems that sustain installed-base loyalty. Belden Inc. and Moxa Inc. occupy positions as specialized communication hardware vendors with concentrated North American and Asia-Pacific manufacturing presence respectively. Huawei Technologies Co., Ltd. anchors the private network specialist archetype, competing aggressively on 5G solutions for smart factory deployments where spectrum access creates regional differentiation.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Siemens AG |
| Rockwell Automation, Inc. |
| Schneider Electric SE |
| ABB Ltd. |
| OMRON Corporation |
| Huawei Technologies Co., Ltd. |
| Belden Inc. |
| Moxa Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Taiwanese and South Korean foundries directly shapes price floors for TSN-capable switch ASICs, concentrating supply-side leverage among semiconductor fabricators while compressing margins for downstream industrial Ethernet vendors.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates IEC 62443-3-3 SL-3 certified safety instrumented systems from uncertified commercial variants, with volume scale and after-sales service bundling as secondary tiering factors. Cost compression in economy-tier fieldbus gateways is intensifying because Indian and Southeast Asian manufacturing plants prioritize minimal licensing fees over deterministic performance. Automotive OEMs in Germany and China exhibit the lowest price sensitivity, while Indian textile clusters under PLI scheme constraints drive hardest bargain for entry-level industrial Ethernet switches.
Supply Chain Analysis
Inventory lead times for advanced industrial Ethernet PHYs and TSN-capable switch ASICs have extended substantially, exposing procurement pipelines to single-source vulnerability. Supply concentrates in Taiwan, South Korea, and Germany for semiconductor fabrication, with specialized industrial cabling production anchored in the United States and China. Raw material dependencies include high-purity copper for shielded twisted-pair cables, gallium arsenide for optical transceivers, and rare earth elements for magnetic components in power supplies. Distribution runs through authorized industrial automation distributors with field engineering support, bypassing commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial communication market represents a high-growth disruption driven by IEC 62443 cybersecurity mandates and TSN protocol maturation forcing infrastructure replacement cycles across heavy process industries.
For Market Incumbents: Fortify installed-base loyalty through captive semiconductor supply of TSN-capable ASICs and accelerated IEC 62443-3-3 SL-3 certification pipelines. Siemens AG and Rockwell Automation must deepen backward integration into programmable logic controller ecosystems to defend against protocol-agnostic software platforms threatening hardware-attach margins. Priority investment in German and Chinese automotive OEM specification lock-in secures backbone network procurement decisions. For New Entrants and Emerging Players: Cloud-hosted device management portals represent a service-layer gap where incumbents under-serve mid-sized manufacturing plants with line reconfiguration cycles shorter than traditional vendor support contracts. Target Indian pharmaceutical and textile automation clusters under PLI scheme incentives, where first-generation industrial Ethernet deployments lack legacy fieldbus switching costs. Go-to-market leverage rests on unbundled engineering services sold separately from hardware procurement. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors private network specialists with localized 5G spectrum access and protocol-agnostic software stacks over hardware-centric switch vendors. Long-term viability hinges on TSN semiconductor design capabilities and automotive OEM relationship density. The signal to watch is BNetzA and MIIT spectrum allocation velocity for industrial 5G, indicating brownfield wireless adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| TSN Semiconductor Backward Integration | Captive ASIC design secures supply continuity against Taiwanese foundry concentration risk. |
| IEC 62443-3-3 SL-3 Certification Investment | SL-3 certification opens safety instrumented system procurement at US Gulf Coast refineries under EPA jurisdiction. |
| 5G Private Network Spectrum Partnership | BNetzA and MIIT spectrum access enables brownfield wireless deployment without cabling infrastructure. |
| Protocol-Agnostic Software Platform Launch | Cloud-hosted management portals unbundle hardware from engineering services for automotive OEMs. |
| Indian PLI Scheme Local Production | Surat and Tiruppur textile clusters generate first-generation industrial Ethernet demand under electronics manufacturing incentives. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across plant engineering, OEM procurement, system integration, and industrial cybersecurity roles. Primary interviews with maintenance directors at German automotive plants, automation engineers at Chinese battery facilities, and network architects at US Gulf Coast refineries were cross-validated against secondary sources including IEC standardization committee minutes, BNetzA spectrum allocation filings, MIIT equipment certification databases, and SEC 10-K disclosures from listed industrial automation vendors. Bottom-up protocol licensing volume estimates and top-down infrastructure investment forecasts were triangulated to constrain projection variance.
Across the analysis window, the forecasting framework modeled product type substitution dynamics, communication protocol licensing trajectories, application vertical penetration rates, and end-user procurement centralization patterns. CAGRs were derived from segment-level volume build-ups calibrated to automotive OEM backbone deployment schedules and utility-scale renewable substation automation timelines. Industry-specific inputs included TSN switch port shipment data and IEC 62443 certification pipeline visibility.
Forecasts assume regulatory continuity in EU Cyber Resilience Act implementation, China's GB/T industrial control system standards, and India's CEA grid modernization mandates; material policy shifts would require re-modeling. Semiconductor supply concentration in Taiwan and South Korea, plus interoperability certification duration uncertainty, represent primary forecast revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Green Communication Market
Communication Services
Global Critical Communication Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Video Managed Services Market
Communication Services
Contact Center As a Service (Ccaas) Market
Communication Services
Pcaas Market
Communication Services
Broadcasting Solutions Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
Dispatch Console Market
Communication Services
Push-To-Talk Market
Communication Services
Audio Conferencing Services Market
Communication Services
Global Communications Interface Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Mobile Messaging Market
Communication Services
Global Passenger Information System Market