
 Virtual Closet Market | 2026-2036
Virtual Closet Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Closet Market Insights
Subscription-based leasing models for enterprise software is reconfiguring competitive entry barriers in the virtual closet space. Stylebook leverages cloud-based infrastructure to sustain its position among individual consumers seeking wardrobe digitization. Suofeiya anchors its offering through manufacturing scale in custom closet hardware paired with companion software. Acloset differentiates via AI-driven outfit recommendations that compete with manual curation services.
A virtual closet is a digital inventory system that catalogs garments through image recognition, 3D rendering, or manual upload, enabling users to visualize, organize, and plan outfits without physical access to items. The system relies on metadata tagging for color, fabric, occasion, and seasonality to generate functional outfit combinations for personal or commercial styling purposes. Mobile Apps currently dominate user acquisition channels due to smartphone penetration and camera integration, while Interactive Mirrors represent the fastest-growing hardware segment as retailers embed them in fitting rooms. AI-Driven Solutions capture expanding margin pools through recurring subscription revenue and data monetization, whereas Web Platforms face maturity pressure from app-first consumer behavior.
The Federal Trade Commission scrutinizes data collection practices in fashion-tech applications, shaping how virtual closet providers structure privacy disclosures and user consent flows. The EU AI Act imposes risk-classification requirements on automated styling recommendations, affecting market access for platforms serving European consumers. ISO standards for augmented reality interoperability increasingly influence technical partnerships between software developers and hardware manufacturers. Stakeholders must weigh compliance investment against feature velocity as regulatory fragmentation intensifies across jurisdictions.
Market Dynamics
AI-driven outfit recommendation engines are compressing the styling value chain by automating curation that previously required human intermediaries. This force redistributes margin pools from personal stylists and department stores toward algorithmic platforms that capture recurring subscription revenue.
Growth Catalysts
- FTC Data Governance Framework:The Federal Trade Commission's scrutiny of fashion-tech data practices is accelerating privacy-by-design investments that build consumer trust and reduce churn in virtual closet applications.
- Smartphone Camera Integration:Mobile device penetration with advanced image recognition capabilities is expanding user acquisition channels for wardrobe digitization services.
- Direct-to-Consumer Brand Investment:US-based apparel retailers are deploying virtual try-on tools to reduce return rates and improve conversion in online channels.
Market Restraints
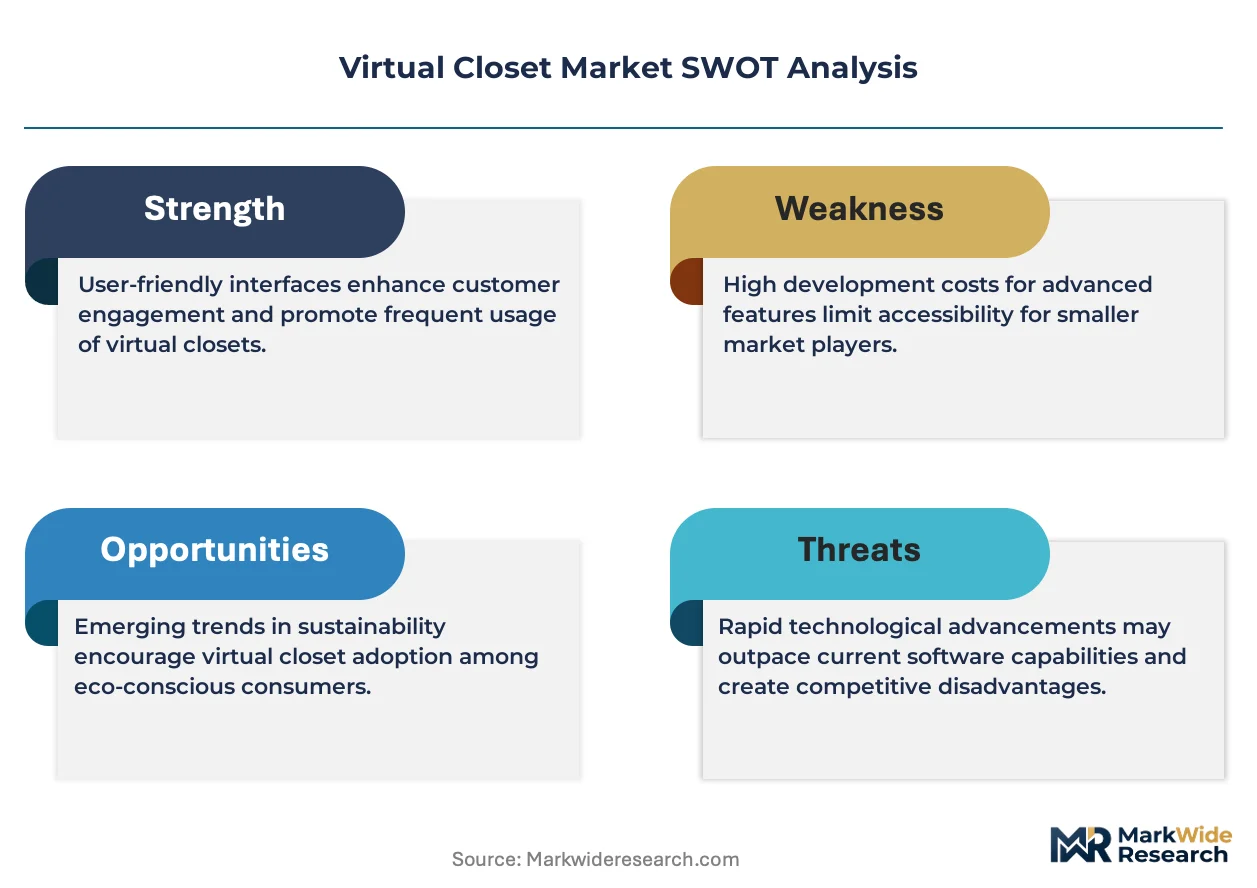
- Cloud Infrastructure Costs:Recurring compute and storage expenses for 3D garment rendering create margin pressure on subscription pricing models.
- EU AI Act Classification:Risk-tier requirements for automated recommendation systems impose compliance friction on platforms serving European consumers.
- Manual Upload Dependency:Persistent image tagging labor requirements limit scalability for users without automated wardrobe digitization hardware.
Strategic Opportunities
- Interactive Mirror Deployment:Fitting room hardware embedding represents an underpenetrated retail channel for virtual closet software integration.
- ISO AR Interoperability Standards:Emerging technical specifications for augmented reality are creating partnership opportunities between software developers and mirror manufacturers.
- Enterprise Leasing Models:Subscription-based software licensing for fashion retailers offers recurring revenue expansion beyond individual consumer segments.
Industry Challenges
- Metadata Standardization:Inconsistent tagging taxonomies for color, fabric, and occasion across platforms impede outfit algorithm accuracy and user experience consistency.
- Legacy System Integration:Retail inventory management software requires custom API development to synchronize with virtual closet applications, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Closet Market |
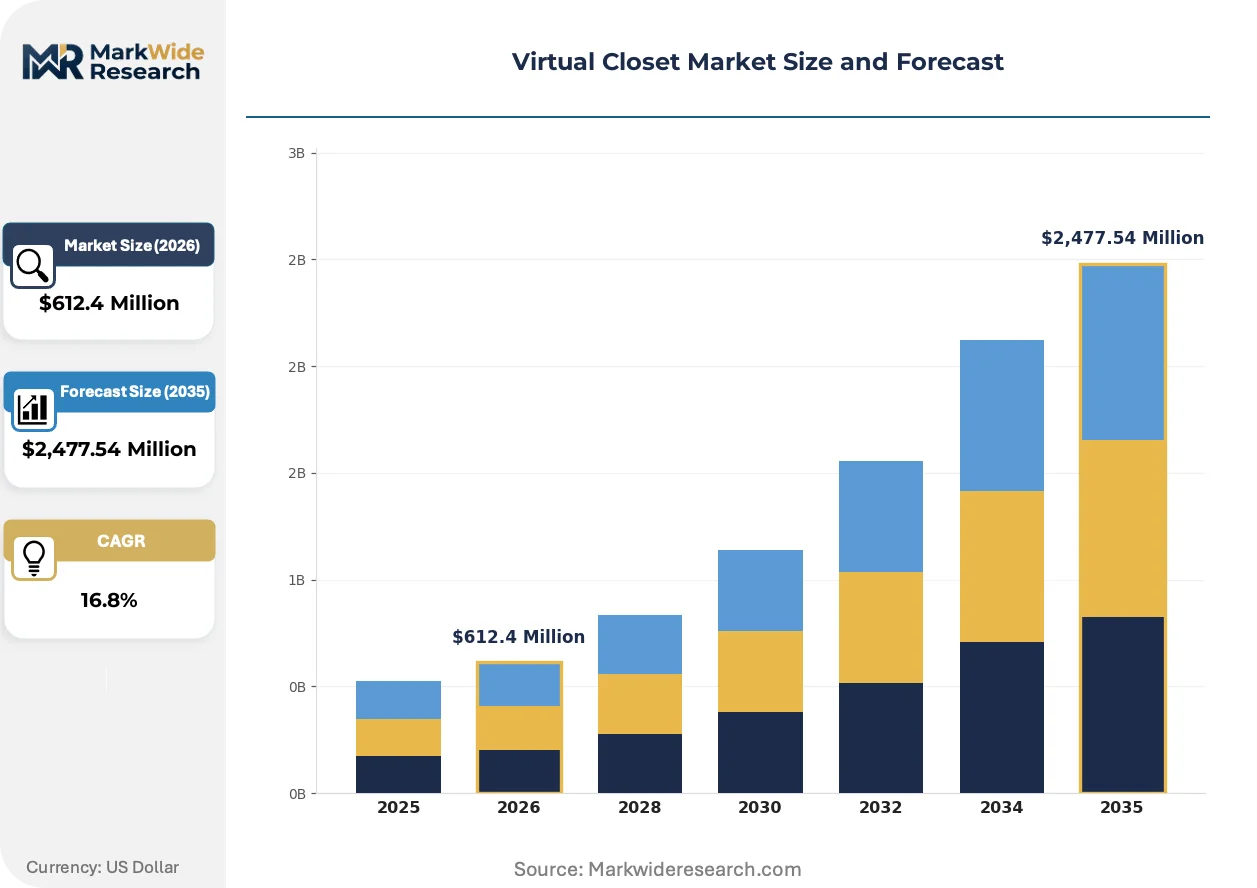
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $2,477.54 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Apps, Web Platforms, Virtual Assistants, Interactive Mirrors User Demographic: Women, Men, Teens, Professionals Technology: Augmented Reality, AI-Driven Solutions, 3D Rendering, Cloud-Based Services Sales Channel: Online Retail, Mobile Application Stores, Subscription Services, Direct Sales |
| Companies Covered | Holike, Smart Closet, IKEA, Stylebook, Pureple, Stanley, Topstrong, Acloset, Suofeiya, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Closet Market Trends and Innovations
Generative AI is compressing content production cycles for fashion visualization while regulatory fragmentation across jurisdictions forces architectural decisions that prioritize compliance velocity over feature expansion.
Computer vision algorithms trained on garment photography are virtualizing the physical try-on experience by generating realistic fit simulations on diverse body models. Fast-fashion retailers are deploying these tools at scale to reduce return processing costs. The technology is virtualizing inventory presentation, collapsing the distinction between digital browsing and physical fitting.
The EU AI Act's risk-classification framework for automated styling recommendations is reshaping platform architecture decisions for European market access. Providers must implement human oversight mechanisms and algorithmic transparency features that increase development overhead. Fashion-tech applications serving EU consumers face the strictest compliance requirements among developed markets.
Subscription fatigue among digital service users is fragmenting demand across free-tier and premium offerings in wardrobe management applications. Younger demographics favor ad-supported models with limited features over recurring payments. This pattern is most visible in the United States where direct-to-consumer brand saturation has normalized cancellation behavior.
Virtual Closet Market Segmentation
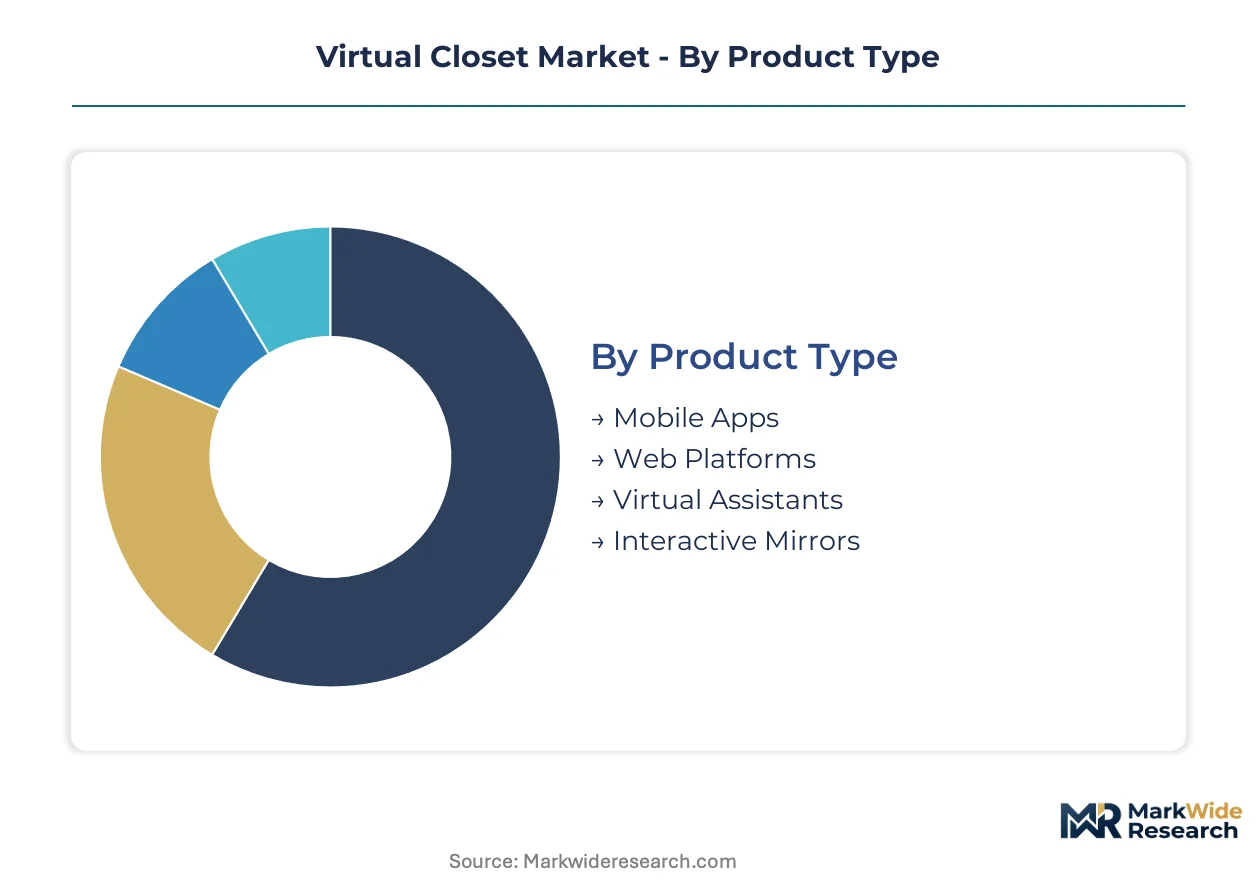
Virtual closet providers configure service architectures around distinct user workflows and hardware ecosystems. Segmentation reveals where development resources concentrate and which interfaces command premium positioning.
Product Type:
After-sales service intensity varies sharply across interface modalities, with hardware-embedded solutions requiring field maintenance while software-native products rely on cloud support desks.
- Mobile Apps:Camera-native applications leverage smartphone penetration for wardrobe digitization through automated background removal and metadata tagging. United States direct-to-consumer brands prioritize this channel for virtual try-on deployments to reduce return rates. Mobile Apps hold the largest share; momentum sits with Interactive Mirrors.
- Interactive Mirrors:Fitting room hardware embeds RFID readers and depth sensors to synchronize physical inventory with digital visualization. Retailers in the United States deploy these units to compress the styling value chain and capture in-store behavioral data. These units expand most quickly as ISO AR interoperability standards mature.
- Web Platforms:Browser-based interfaces face maturity pressure from app-first consumer behavior but retain enterprise utility for inventory management dashboards.
- Virtual Assistants:Voice-activated wardrobe queries integrate with smart home ecosystems for hands-free outfit planning during morning routines.
Mobile Apps dominate individual user acquisition; Interactive Mirrors capture expanding enterprise deployment budgets.
User Demographic:
Application intensity tracks lifestyle complexity, with time-constrained segments prioritizing automated curation over manual wardrobe management.
- Professionals:Workwear-focused users demand occasion-based outfit algorithms that align garments with dress codes and calendar events. United States corporate adoption concentrates in consulting and finance verticals where appearance consistency carries career consequences. Professionals command the highest subscription willingness-to-pay; Teens drive freemium volume expansion.
- Women:Historically concentrated demand reflects broader fashion e-commerce participation and social sharing behaviors around outfit curation.
- Men:Emerging segment characterized by preference for minimalist interfaces and capsule wardrobe optimization rather than expansive digitization.
- Teens:Social-native users prioritize TikTok-integrated sharing features and peer-to-peer outfit voting over traditional cataloging functions.
Women constitute the established revenue base; Professionals represent the steepest expansion trajectory for premium tiers.
Technology:
Cost tier stratification separates proprietary algorithm development from commodity infrastructure leasing.
- AI-Driven Solutions:Recommendation engines trained on garment metadata and user preference vectors automate outfit generation without human stylist intervention. United States platforms invest heavily here to capture recurring subscription revenue and reduce customer acquisition costs through personalization stickiness. AI-Driven Solutions command margin premiums; Cloud-Based Services enable market entry at scale.
- Augmented Reality:Real-time garment overlay on camera feeds requires precise body tracking and fabric physics simulation for convincing fit visualization.
- 3D Rendering:Photogrammetry-based asset creation supports virtual try-on with accurate drape and texture representation for luxury applications.
- Cloud-Based Services:Infrastructure-as-a-service models lower capital barriers for new entrants but compress differentiation to frontend experience alone.
AI-Driven Solutions concentrate development talent; Augmented Reality climbs fastest on retail hardware integration.
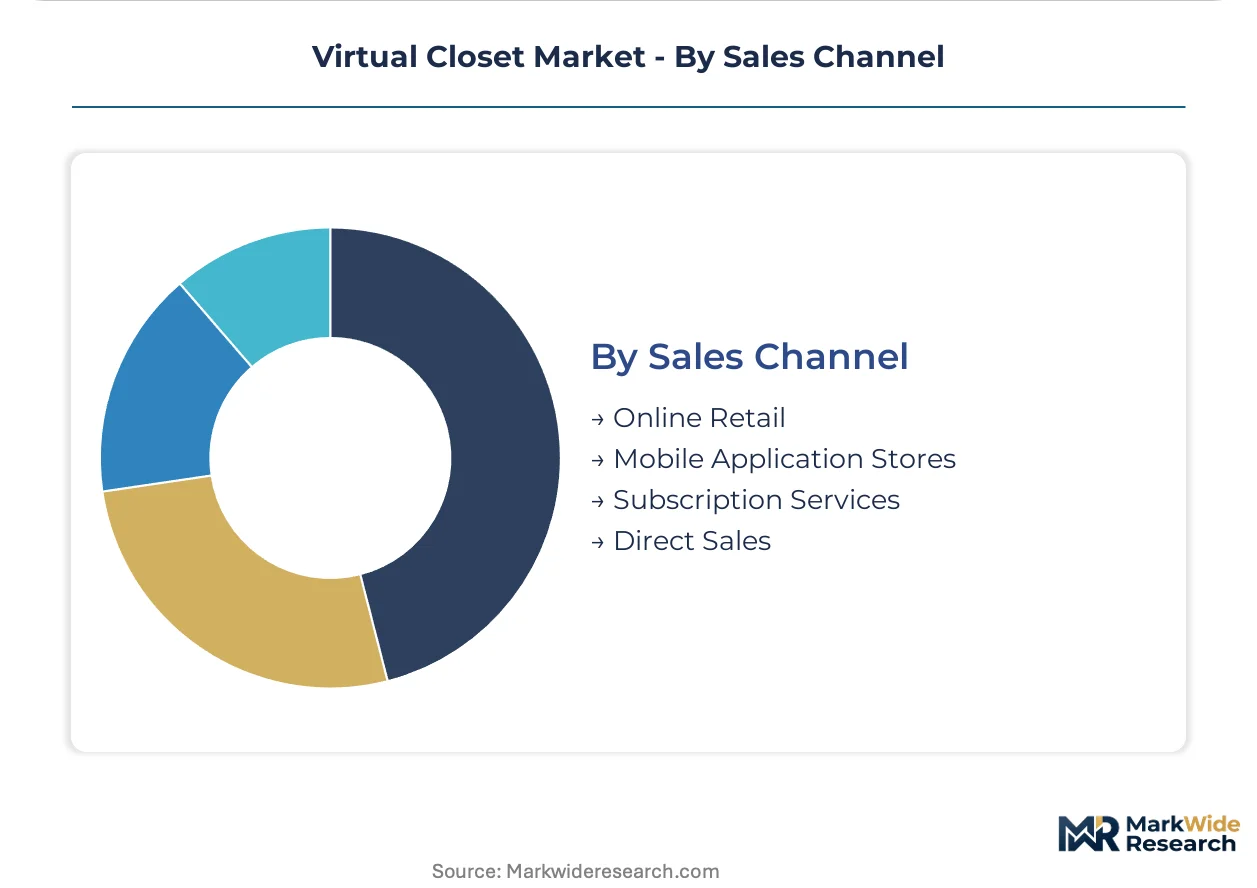
Sales Channel:
Customer acquisition economics favor recurring revenue models over transactional distribution.
- Subscription Services:Monthly or annual billing for premium features including unlimited outfit generation and priority AI processing locks in predictable lifetime value. United States users show highest tolerance for recurring payments among developed markets. Subscription Services anchor provider economics; Mobile Application Stores dominate user discovery.
- Online Retail:Bundled hardware-software packages through e-commerce marketplaces reach consumers seeking integrated wardrobe digitization systems.
- Mobile Application Stores:Apple App Store and Google Play commission structures shape pricing architecture and feature gating for freemium conversion funnels.
- Direct Sales:Enterprise contracts with fashion retailers bypass platform fees but require dedicated sales engineering for legacy system integration.
Subscription Services generate the most predictable revenue; Direct Sales unlock the largest per-contract values.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virtual closet software flows primarily from US and European developers toward Asian manufacturing hubs, with cross-border data processing creating regulatory friction points. Service exports concentrate in subscription revenue from North American consumers, while hardware-integrated deployments absorb capital in East Asian retail infrastructure.
United States
Direct-to-consumer apparel brands drive enterprise adoption of virtual try-on tools to compress return processing costs. FTC scrutiny of fashion-tech data collection forces privacy-by-design investments that extend development timelines. San Francisco and New York anchor algorithm development clusters where AI-driven personalization engines attract venture funding.
Germany
Luxury automotive and fashion conglomerates pilot interactive mirror installations in flagship retail locations. EU AI Act risk-classification requirements impose human oversight mandates on automated styling recommendations. Munich and Berlin concentrate compliance engineering talent for algorithmic transparency documentation.
China
Smart manufacturing ecosystems integrate virtual closet software with custom furniture production lines for wardrobe system bundling. MIIT data localization rules require domestic cloud infrastructure for consumer garment image storage. Shenzhen and Hangzhou dominate hardware-software integration engineering for mirror-based retail deployments.
Japan
Department store chains deploy compact virtual closet kiosks in dense urban retail formats to maximize selling space efficiency. METI guidelines on AI service transparency shape disclosure requirements for automated outfit recommendations. Tokyo's Shibuya and Ginza districts host concentrated pilot programs for generative AI styling tools.
United Kingdom
Fast-fashion retailers license virtual try-on modules to reduce environmental costs from return shipping volumes. GDPR enforcement actions against fashion apps with excessive data retention periods elevate compliance spending. London's Shoreditch and Manchester's Northern Quarter sustain independent developer studios serving mid-market brands.
Virtual Closet Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in computer vision and rendering engines. Market structure fragments across consumer app developers, enterprise software vendors, and hardware-embedded solution providers. Three archetypes dominate: cloud-native wardrobe digitization apps, custom closet manufacturers with companion software, and retail technology integrators. Consolidation pressure concentrates on AI talent acquisition and ISO AR interoperability certification partnerships.
Within the consumer app tier, Stylebook and Acloset exemplify divergent positioning strategies. Suofeiya anchors the manufacturing-software hybrid model through its Chinese production base. IKEA represents the furniture retailer's entry path via smart home ecosystem integration.
| Leading Market Players |
|---|
| Holike |
| Smart Closet |
| IKEA |
| Stylebook |
| Pureple |
| Stanley |
| Topstrong |
| Acloset |
| Suofeiya |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in cloud infrastructure provisioning across the United States is compressing margins for virtual closet SaaS providers while simultaneously enabling aggressive tiered pricing experiments that reshape customer acquisition economics.
Pricing Analysis
Enterprise fashion retailers anchor pricing negotiations through volume-based SaaS licensing that stratifies across premium AI-curation tiers, standard cataloging modules, and economy self-service entry points. Price differentiation rests on algorithmic sophistication depth and ISO AR interoperability certification status. Pricing pressure stems from subscription fatigue among individual consumers migrating toward ad-supported freemium alternatives. Younger demographics exhibit highest price sensitivity; corporate procurement teams at direct-to-consumer brands demonstrate lowest elasticity due to return-rate reduction mandates.
Supply Chain Analysis
Tariff exposure between China and the United States dominates hardware-embedded solution economics as interactive mirror manufacturers face component cost volatility. Manufacturing concentrates in Shenzhen and Hangzhou for mirror assembly, with South Korean display panel suppliers and Taiwanese sensor module providers anchoring critical component flows. Raw material dependencies span rare-earth magnets for RFID systems, optical-grade glass for depth sensors, and specialized semiconductors for edge AI processing. Single-source vulnerability concentrates in advanced image sensor fabrication. Distribution runs through direct enterprise sales for retail deployments and mobile application stores for consumer software delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across user workflow preferences—professional calendar integration versus teen social sharing—creates defendable niche positions for specialists who resist horizontal feature expansion.
For Market Incumbents: Harden platform stickiness through backward integration into proprietary computer vision training pipelines that reduce dependency on third-party garment recognition APIs. Deepen ISO AR interoperability certification partnerships with mirror manufacturers to lock out competing software layers. Cloud infrastructure cost escalation threatens margin sustainability; captive GPU cluster deployment in domestic data centers offers defensive control over rendering economics. For New Entrants and Emerging Players: Pursue white-space concentration in men's capsule wardrobe optimization where interface minimalism preferences remain underserved by feature-heavy incumbent applications. Target Germany and Japan for regulatory-compliant AI styling tools that incumbent platforms struggle to retrofit for EU AI Act and METI transparency mandates. Launch through furniture retail partnerships bundling software with custom closet hardware installations. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native wardrobe digitization as infrastructure commoditization enables leaner operational models. Long-term viability favors platforms with data network effects from multi-year user garment libraries rather than transactional try-on tools. Acquisition screening should prioritize teams with computer vision PhD density and existing FTC privacy audit compliance. Watch for inflection signals in direct-to-consumer brand consolidation activity that concentrates enterprise buyer power.| Strategic Initiative | Industry Significance |
|---|---|
| ISO AR Interoperability Certification | Unlocks hardware-embedded deployment partnerships with mirror manufacturers seeking standardized software layers. |
| Backward Integration into Computer Vision Training | Captures proprietary garment recognition capability that third-party API dependencies cannot replicate. |
| Enterprise Leasing Model Expansion | Captures recurring revenue from direct-to-consumer brands prioritizing return-rate reduction investments. |
| Regulatory-First Architecture Development | Accelerates EU AI Act and FTC compliance velocity that feature-first competitors must retrofit. |
| Generative AI Styling Content Pipeline | Compresses visualization production cycles for fast-fashion retailers demanding rapid inventory turnover. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with virtual closet application product managers, fashion retail technology procurement officers, computer vision engineering leads, interactive mirror hardware manufacturers, and regulatory compliance specialists at platforms serving European markets. Secondary validation drew from SEC filings of publicly traded fashion retailers, FTC enforcement action databases, EU AI Act implementation guidance documents, and mobile application store analytics. Bottom-up user adoption modeling and top-down enterprise spending estimates were triangulated to constrain projection variance.
Calibration against historical subscription revenue trajectories and hardware deployment cycles shaped the analytical framework across the analysis window. Segmentation dimensions modeled include interface modality, user demographic cohort, technology stack architecture, and sales channel structure. CAGRs were derived from fitted growth curves incorporating smartphone camera capability advancement rates, cloud infrastructure cost deflation assumptions, and regulatory compliance investment lag effects. Forecast inputs included direct-to-consumer brand virtual try-on adoption schedules and ISO AR standard ratification timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or venture capital availability for fashion-tech startups would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and hardware cost curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global IC Card/Smart Card Market
Digital Solutions
Online Recruitment Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Kazakhstan ICT Market
Digital Solutions
Global Digital Experience Management Market
Digital Solutions
Returnless Refund Fraud Detection Market
Digital Solutions
Hybrid Events Software Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
ICT Investment in Government Market
Digital Solutions
Community Engagement Platform Market
Digital Solutions
Digital Workplace Technologies Market
Digital Solutions
Online Laundry Services Market
Digital Solutions
Web Real-Time Communication (Webrtc) Market
Digital Solutions
Consent Management Market
Digital Solutions
Global Freelance Platforms Market