
 Global Personal Cooling Device Market | 2026-2036
Global Personal Cooling Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Personal Cooling Device Market Intelligence
The market for personal cooling devices is decoupling as premium, feature-rich neck fans diverge from low-cost, high-volume handheld coolers. Dyson Ltd. differentiates with advanced air multiplier technology and ergonomic designs targeting affluent consumers. In contrast, Midea Group leverages its massive manufacturing scale to compete on price and volume in the mass market, particularly through e-commerce channels.
A personal cooling device is a portable apparatus designed to create a localized microclimate for an individual. These units often utilize thermoelectric modules based on the Peltier effect or evaporative cooling technology to reduce ambient air temperature. While neck fans represent the fastest-growing product type, portable air conditioners maintain a hold on users needing higher cooling capacity. Thermoelectric technology leads in high-performance segments, whereas evaporative systems dominate entry-level products.
Product safety and electronics compliance are governed by a matrix of national standards. In the United States, the FCC sets rules for electronic emissions, while CE marking is mandatory for market access in the European Union. Battery safety is also critical, with many manufacturers adhering to IEC 62133 standards to mitigate risks. Future product development will hinge on balancing cooling effectiveness with battery longevity and device weight.
Market Dynamics
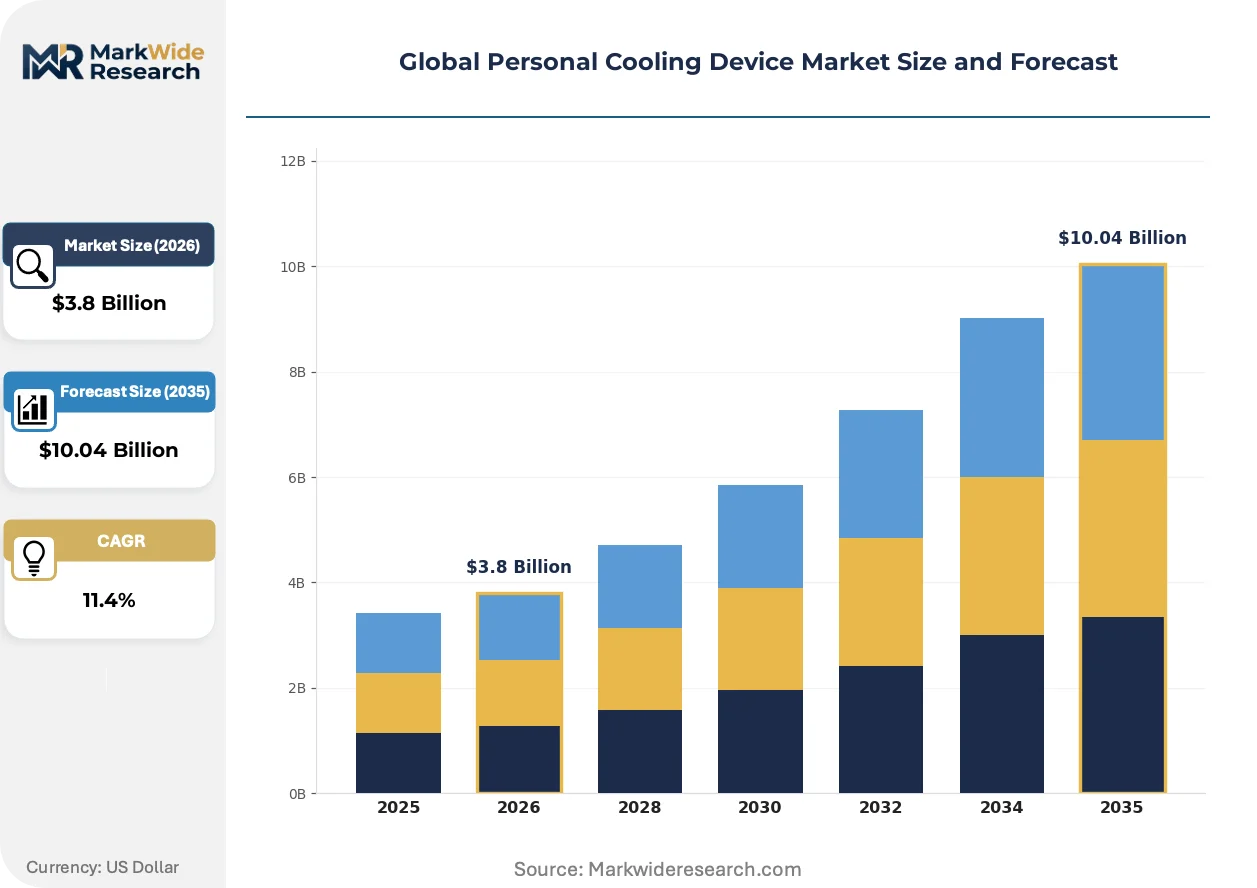
The central structural force shaping the personal cooling device market is the convergence of advanced battery energy density with rising occupational safety mandates for heat exposure. This dynamic allows for the creation of higher-performance, longer-lasting devices that meet the specific demands of industrial and outdoor workers in increasingly warm climates.
Growth Catalysts
- Battery Technology Advancement:Innovations in lithium-ion energy density and charging speeds are enabling manufacturers to produce more powerful and longer-lasting devices, a critical factor for users without access to constant power sources.
- Occupational Health Regulations:Growing emphasis on mitigating heat stress for workers in sectors like construction and logistics, exemplified by guidelines from bodies like the US OSHA, is driving employer-led procurement of personal cooling solutions.
- Urban Heat Island Effect:Intensifying heat in major metropolitan areas, particularly in countries like India and Brazil, is expanding the consumer base beyond industrial applications to include daily commuters and residents seeking personal climate relief.
Market Restraints
- Component Cost Volatility:The price of high-performance thermoelectric modules and high-density lithium-ion battery cells remains a significant barrier, particularly for manufacturers targeting mass-market price points.
- Weight and Ergonomics Trade-off:A fundamental technical limitation persists between cooling capacity and device weight. Increasing cooling power often requires larger batteries and heat sinks, which can compromise user comfort and portability.
- Battery Safety and Transport Rules:Strict regulations governing the air transport of lithium-ion batteries, set by organizations like IATA, add logistical complexity and cost to the global supply chain, impacting both component sourcing and finished goods distribution.
Strategic Opportunities
- Medical and Therapeutic Niches:There is an opportunity to develop specialized devices for medical applications, such as helping patients with multiple sclerosis or other conditions that cause heat sensitivity manage their symptoms.
- Smart Device Integration:Incorporating IoT connectivity allows for features like remote control via smartphone apps, performance monitoring, and automated adjustments based on biometric data or ambient temperature, opening avenues for premium subscription services. *Underpenetrated Climate Zones: Markets in the Middle East and Southeast Asia with high average temperatures and significant outdoor workforces represent substantial growth areas for durable, high-performance personal cooling products.
Industry Challenges
- Fragmented Compliance Requirements:Manufacturers face significant hurdles in navigating the disparate electronic and safety standards across key markets, including FCC regulations in the US, CE marking in the EU, and BIS certification in India.
- Battery Lifecycle Management:The lack of standardized, accessible recycling programs for lithium-ion batteries in many regions poses a sustainability challenge and a potential future regulatory risk for the industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Personal Cooling Device Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neck Fans, Handheld Coolers, Wearable Cooling Vests, Cooling Scarves, Portable Air Conditioners Technology: Thermoelectric, Evaporative, Phase Change Material, Battery-Powered, Solar-Powered End User: Outdoor Enthusiasts, Construction Workers, Fitness Trainers, Event Staff, Commuters Distribution Channel: E-commerce Platforms, Specialty Retail Stores, Sporting Goods Retailers, Direct Manufacturer Sales, Pop-up Shops |
| Companies Covered | Honeywell International Inc., Dyson Ltd., LG Electronics Inc., Panasonic Holdings Corp., O2Cool LLC, Samsung Electronics, Emerson Electric, Midea Group, Evapolar Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Personal Cooling Device Market Strategic Shifts & Innovations
The market is rapidly evolving from simple air circulation to active thermal management. Miniaturization of cooling components and advancements in material science are enabling a new class of devices that offer personalized microclimates with greater efficiency and portability. This shift is redefining user expectations and product capabilities.
Solid-state thermoelectric modules, which use the Peltier effect to create a temperature differential, form the core of high-end active cooling. Premium device manufacturers are adopting these modules to offer tangible cooling rather than just air movement. This technology is electrifying the personal comfort category, moving it beyond fans into true micro-climate control systems for discerning consumers and professional users.
Global standards like IEC 62133 are becoming table stakes for battery safety, profoundly influencing design and supply chain choices. This regulation compels rigorous testing against risks like internal short circuits and thermal runaway, adding significant time and cost to product development. Consequently, smaller brands face higher barriers to entry in regulated markets like the European Union, where compliance is mandatory.
Direct-to-consumer (DTC) sales models are disrupting traditional retail channels for personal cooling devices. Brands are leveraging social media and e-commerce platforms to build communities around specific use cases, from outdoor sports to construction work, bypassing intermediaries. This trend is most pronounced in the fashion-conscious neck fan segment in markets like South Korea and Japan, where online influencers directly shape consumer preferences.
Global Personal Cooling Device Market Segmentation
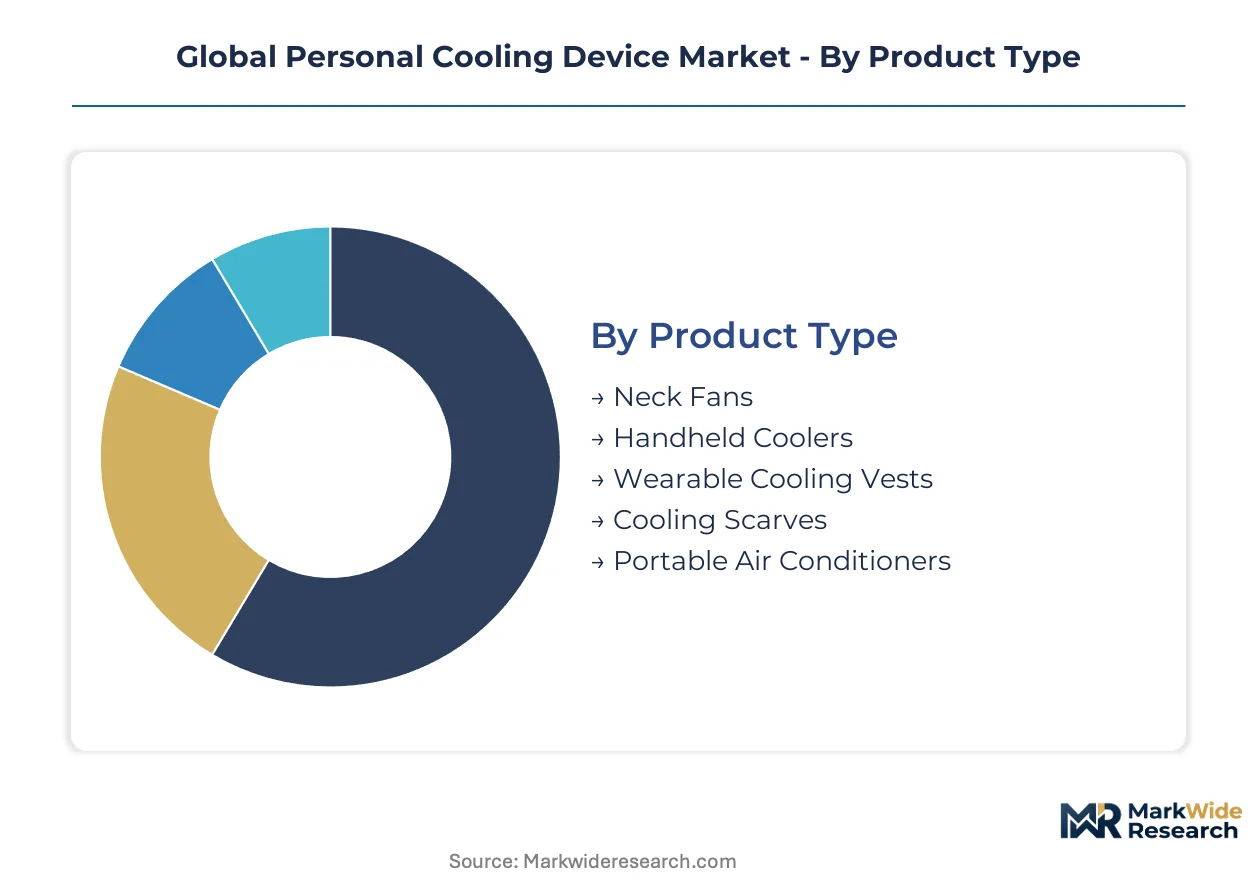
Understanding the personal cooling device market requires a detailed segmentation analysis to discern the various product types, underlying technologies, target end-users, and effective distribution channels. This granular view highlights where innovation is concentrated and how different consumer needs are being met across diverse applications.
Product Type:
The market for personal cooling devices is bifurcating between high-volume, cost-effective solutions and premium, feature-rich offerings. This split influences design, manufacturing scale, and target demographics across all product categories.
- Neck Fans:These devices offer hands-free operation and localized cooling, making them ideal for commuters in dense urban environments like Tokyo and Mumbai. Innovations in battery life and airflow design are driving their rapid expansion.
- Portable Air Conditioners:These units provide significant cooling capacity for personal spaces, often utilized by outdoor event staff or individuals in temporary workstations. Their larger size typically requires more power and limits extreme portability.
- Handheld Coolers:Compact and highly portable, handheld coolers serve the mass market with simple air movement, often powered by basic battery cells. Consumers seeking immediate, low-cost relief from heat frequently purchase these devices.
- Wearable Cooling Vests:Designed for sustained thermal regulation, these vests often incorporate advanced cooling elements for workers in demanding industrial settings or athletes. Their specialized nature commands a higher price point.
- Cooling Scarves:Utilizing evaporative or phase change material technology, cooling scarves offer lightweight and discreet temperature management for casual users. They provide a passive cooling effect without electronic components.
Today's leader: Neck Fans. Tomorrow's challenger: Wearable Cooling Vests.
Technology:
Cost structures for personal cooling devices are heavily influenced by the core cooling technology employed, ranging from simple air movement to complex solid-state thermal transfer. Manufacturers select technologies based on desired performance, power consumption, and production cost targets.
- Thermoelectric:These modules leverage the Peltier effect to create a temperature differential, offering active, tangible cooling in high-performance devices. Premium brands like Dyson Ltd. integrate this technology for discerning consumers.
- Battery-Powered:The integration of advanced lithium-ion cells enables portable and cordless operation, critical for devices used by construction workers in remote locations. Energy density advancements directly impact device run-time and power output.
- Evaporative:This technology relies on the evaporation of water to draw heat away from the body, providing a cost-effective and energy-efficient cooling solution. Entry-level handheld coolers frequently utilize evaporative pads.
- Phase Change Material:PCMs absorb and release thermal energy during phase transitions, offering passive, sustained cooling without requiring electrical power. These materials are often found in specialized cooling apparel.
- Solar-Powered:Devices incorporating small photovoltaic cells offer extended operational times in direct sunlight, appealing to outdoor enthusiasts and users in off-grid environments. Their effectiveness is contingent on solar availability.
Supply chain concentration for critical components heavily influences the adoption of advanced cooling technologies.
End User:
The application landscape for personal cooling devices is broad, with distinct user groups driving demand for tailored product features and performance attributes. Different end-user segments prioritize varying aspects like durability, portability, or sustained cooling capacity.
- Construction Workers:This segment demands robust, durable devices capable of withstanding harsh conditions and providing significant cooling during prolonged outdoor shifts. Occupational safety regulations in the US (OSHA) and India drive procurement.
- Commuters:Individuals navigating urban heat islands in cities like São Paulo and New Delhi seek lightweight, discreet, and long-lasting cooling solutions for daily travel. Neck fans are particularly popular within this group.
- Outdoor Enthusiasts:Hikers, campers, and sports participants require portable, often rugged devices that can operate without constant power access. Battery life and weather resistance are key considerations for these users.
- Fitness Trainers:Professionals and athletes engaged in intense physical activity need effective cooling to manage body temperature and enhance performance. Wearable cooling vests offer continuous thermal regulation during exercise.
- Event Staff:Individuals working at outdoor festivals, concerts, or sporting events require comfortable, hands-free cooling solutions for extended periods. Ease of use and long battery life are important for this segment.
Demand for personal cooling solutions is increasingly driven by specific occupational and lifestyle requirements.
Distribution Channel:
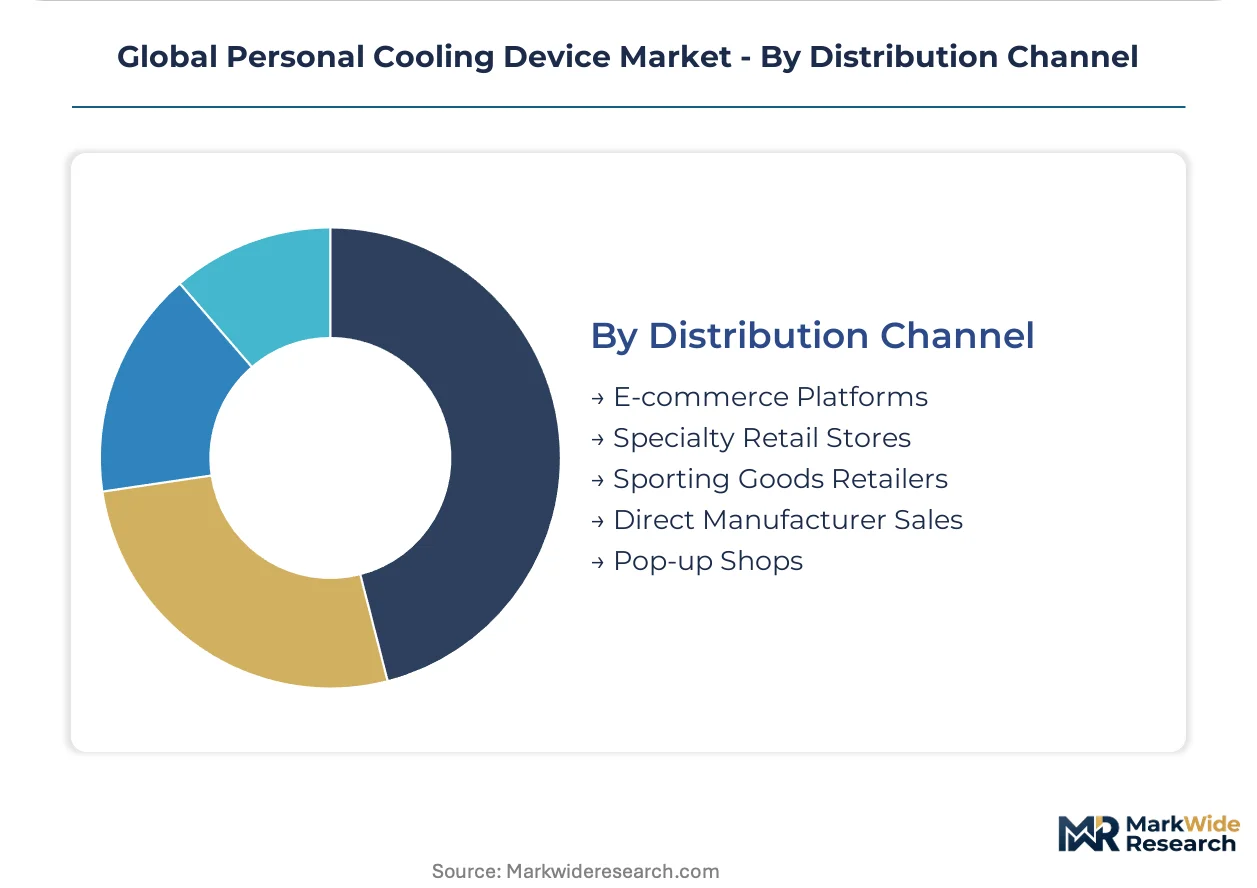
Customer procurement patterns for personal cooling devices vary significantly, reflecting product complexity, price point, and target audience. The rise of e-commerce has reshaped how consumers discover and purchase these products.
- E-commerce Platforms:Online marketplaces facilitate broad market reach for both established brands and new entrants, offering competitive pricing and direct-to-consumer models. This channel is particularly strong in South Korea and Japan for fashion-conscious neck fans.
- Specialty Retail Stores:These outlets cater to premium segments, offering expert advice and the opportunity for customers to experience high-end devices firsthand. Stores focusing on outdoor gear or electronics often stock advanced cooling solutions.
- Sporting Goods Retailers:Stores specializing in athletic equipment and outdoor recreation gear provide a focused channel for products designed for active users. They often carry wearable cooling vests and rugged portable fans.
- Direct Manufacturer Sales:Brands establish their own online stores to control the customer experience, build brand loyalty, and collect direct feedback. This model supports subscription services for smart cooling devices.
- Pop-up Shops:Temporary retail spaces capitalize on seasonal demand or specific events to showcase new products and engage directly with consumers. This channel generates buzz and allows for immediate sales conversion.
E-commerce platforms are gaining share fastest, driven by convenience and product accessibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While demand in the United States focuses on occupational safety for construction workers, India's market expands due to urban heat and daily commuters. These distinct drivers shape product development and distribution strategies across diverse global geographies. Manufacturers adapt to localized climate challenges and regulatory environments.
United States
Demand for personal cooling solutions in the United States rises from stringent occupational safety mandates for outdoor workers. OSHA guidelines for heat stress mitigation compel employers in construction and logistics to procure advanced cooling devices. Silicon Valley and other tech hubs drive innovation in smart device integration and battery technology for consumer applications.
India
Rapid urbanization and intensifying urban heat island effects in India create significant demand for personal cooling devices among commuters and outdoor laborers. The Bureau of Indian Standards (BIS) certification ensures product safety and quality for electronic devices. Major metropolitan areas like Mumbai and Delhi witness high sales volumes for neck fans and handheld coolers, particularly through e-commerce.
Brazil
Construction workers and outdoor event staff in Brazil require durable, high-performance personal cooling solutions due to the country's warm climate. ANVISA regulations for medical devices could influence future specialized cooling products for therapeutic niches. São Paulo and Rio de Janeiro present strong consumer markets for portable cooling devices, driven by lifestyle and climate factors.
Japan
Japan's market for personal cooling devices is influenced by sophisticated consumer preferences for ergonomic design and miniaturization, especially among commuters. METI guidelines for electronic product safety and energy efficiency shape product development. Tokyo and other major cities show strong adoption of premium neck fans through direct-to-consumer channels and fashion-conscious e-commerce.
Germany
Demand in Germany for personal cooling devices stems from industrial applications and an increasing focus on worker comfort in manufacturing. CE marking is mandatory for market access in the European Union, ensuring compliance with health, safety, and environmental protection standards. Industrial centers in Bavaria and North Rhine-Westphalia are early adopters of wearable cooling vests for specialized work environments.
Global Personal Cooling Device Market Key Industry Players
Top-tier vendors anchor the premium segment, while a broad array of manufacturers competes in the mass-market and entry-level categories. This market structure supports both innovation-driven differentiation and volume-based pricing strategies. Key strategic archetypes include technology innovators, scale manufacturers, and niche specialists. Dominant competitive moves involve portfolio diversification into adjacent comfort solutions and geographic expansion into underpenetrated climate zones.
On the premium innovation vector, Dyson Ltd. exemplifies a focus on advanced air multiplier technology and ergonomic designs for affluent consumers. Conversely, at the mass-market scale, Midea Group leverages its extensive manufacturing capabilities to compete on price and volume. These companies represent distinct approaches to market penetration, with Dyson targeting high-end differentiation and Midea focusing on broad accessibility.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Dyson Ltd. |
| LG Electronics Inc. |
| Panasonic Holdings Corp. |
| O2Cool LLC |
| Samsung Electronics |
| Emerson Electric |
| Midea Group |
| Evapolar Ltd. |
| Others |
Cost & Logistics Intelligence
Construction workers' procurement of personal cooling devices drives a transactional, unit-based pricing structure, particularly for durable, high-performance models. This demand prioritizes ruggedness over aesthetic differentiation.
Pricing Analysis
Bundled offerings often include extended warranties or subscription services for smart cooling devices, commanding premium pricing. Unbundled, transactional sales of handheld coolers dominate the mass market. Price differentiation stems from advanced thermoelectric technology and specific safety certifications like CE marking. Pricing softness reflects component cost volatility, especially for lithium-ion batteries. Commuters are highly price-sensitive for entry-level neck fans, while industrial buyers prioritize performance and durability.
Supply Chain Analysis
Regional distribution centers in key consumer markets like India and Japan manage localized inventory for personal cooling devices. Global supply concentrates in China for manufacturing and assembly, with critical components sourced from South Korea and Japan. Raw material dependencies include high-performance thermoelectric modules and lithium-ion battery cells. Logistical complexity from strict IATA regulations for lithium-ion battery transport presents a structural risk. Distribution runs through e-commerce platforms and specialty retailers, particularly for fashion-conscious neck fans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
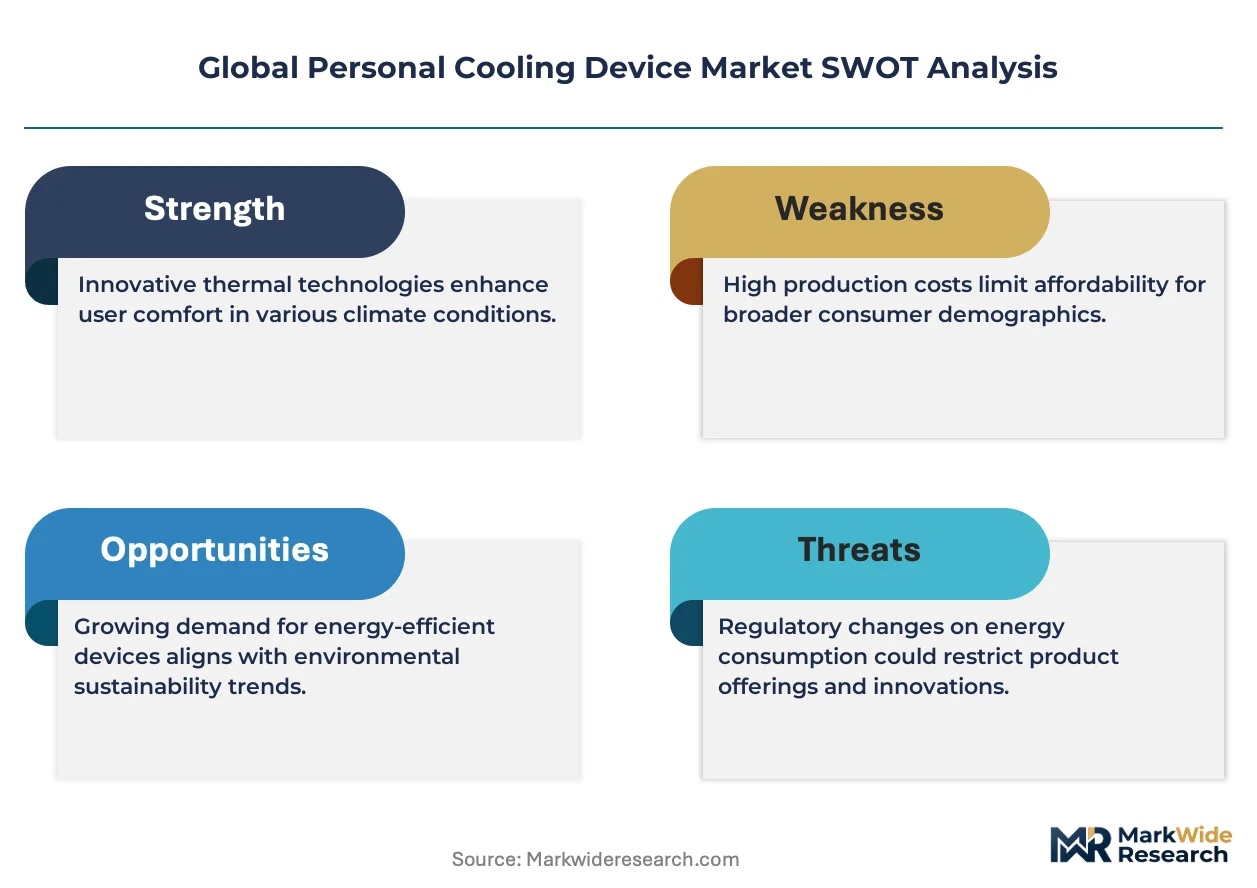
The personal cooling device market acts as a regulatory compounder, with OSHA guidelines for heat stress mitigation significantly driving employer-led procurement. This regulatory push creates sustained demand for advanced solutions.
For Market Incumbents: Anticipate continued pressure from low-cost mass-market entrants by investing in next-generation thermoelectric technology. Diversify product portfolios to include specialized medical and therapeutic devices, leveraging existing R&D capabilities. Strengthen channel partnerships with industrial safety distributors to secure employer-led procurement contracts. Focus on battery longevity and device weight improvements to maintain premium differentiation against substitute technologies.
For New Entrants and Emerging Players: Begin with targeting underpenetrated climate zones like the Middle East and Southeast Asia for durable, high-performance products. Focus on the event staff segment with hands-free, long-lasting cooling solutions. A direct-to-consumer online sales model allows rapid market entry and brand building around specific use cases. Leverage social media influencers in fashion-conscious markets to drive adoption of innovative neck fan designs.
For Investors and Strategic Acquirers: Industrial conglomerates are the most active acquirers in this space, seeking to integrate personal cooling into broader occupational safety portfolios. The market offers long-term viability over a five-to-ten-year window, driven by climate change and worker safety mandates. Acquisition targets should be specialized manufacturers with strong intellectual property in thermoelectric or advanced battery technology. The signal to watch is the increasing number of employer-mandated procurement programs for heat stress mitigation.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Portfolio Diversification | Expands market reach into medical and therapeutic niches for heat-sensitive patients. |
| Advanced Battery R&D Investment | Extends operational times and reduces device weight, enhancing user comfort and utility. |
| E-commerce Channel Expansion | Captures direct-to-consumer sales, particularly for fashion-conscious neck fans in urban markets. |
| Occupational Safety Certification | Opens access to employer-led procurement in regulated sectors like construction and logistics. |
| Thermoelectric Module Miniaturization | Enables higher cooling efficiency in smaller, more ergonomic personal cooling devices. |
Research Approach
Direct dialogue with product development executives, industrial safety managers, and e-commerce platform leads informed this analysis. Primary insights were validated through extensive secondary research, combining bottom-up and top-down triangulation. Secondary sources included national standards organizations, industry association reports, and regulatory body publications. Procurement managers at construction firms and consumer electronics retailers also contributed to the data approach.
The quantitative model produced detailed volume and value projections across the analysis window. Segmentation dimensions modeled included product type, core technology, end-user application, and distribution channel. Compound annual growth rates were derived from historical data trends and projected technological advancements. Key forecast inputs included lithium-ion battery energy density improvements and regional heat index projections.
Caveats apply where unforeseen regulatory changes or significant component supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding technological evolution and market adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Management Systems
Europe Home Energy Management System Market
Energy Management Systems
Building Energy Management Solution Market
Energy Management Systems
Shared Power Bank Market
Energy Management Systems
Noise Mitigation System Market
Energy Management Systems
Asia-Pacific Home Energy Management System Market
Energy Management Systems
Building Energy Management Systems (BEMS) Market
Energy Management Systems
Global Variable Air Volume (VAV) System Market
Energy Management Systems
Smart Thermostat Market
Energy Management Systems
United Arab Emirates Portable Air Conditioning Market
Energy Management Systems
District Cooling Market
Energy Management Systems
Intelligent PDU Market
Energy Management Systems
Smart Water Cooler Market
Energy Management Systems
IoT Smart Gas Meter Market
Energy Management Systems
Mobile Metering System Market
Energy Management Systems
Smart HVAC Controls Market
Energy Management Systems
AI-Driven Lighting Controls Market