
 Pipe Inspection Robot Market | 2026-2036
Pipe Inspection Robot Market Size, Share, and Industry Trends Forecast 2026-2036
Pipe Inspection Robot Market Analytics
German sensor manufacturers and Japanese precision engineering houses is hardening supply-side capacity for high-durability crawler systems. IBAK Helmut Hunger GmbH & Co. KG anchors European demand through specialized optical inspection platforms for municipal sewer networks. Deep Trekker Inc. competes in North American freshwater and industrial segments with portable remotely operated vehicle designs. Envirosight LLC sustains channel dominance in U.S. municipal procurement through extensive distributor coverage and training infrastructure.
Pipe inspection robots are electromechanical crawler or swimming platforms equipped with CCTV cameras, ultrasonic thickness sensors, and laser profiling tools, designed to traverse and assess the interior condition of buried or inaccessible pipelines without excavation or flow interruption. Their primary purpose is to detect structural defects, corrosion, blockages, and infiltration in water, sewer, and energy distribution networks before catastrophic failure occurs. Optical technology occupies the largest installed base due to mature CCTV standards and lower per-unit cost, while ultrasonic platforms capture expanding share in oil and gas corrosion monitoring where wall-thickness quantification determines replacement timing. Application demand concentrates in water supply and sewage systems where EPA consent decrees and EU Urban Waste Water Treatment Directive enforcement compel systematic condition assessment.
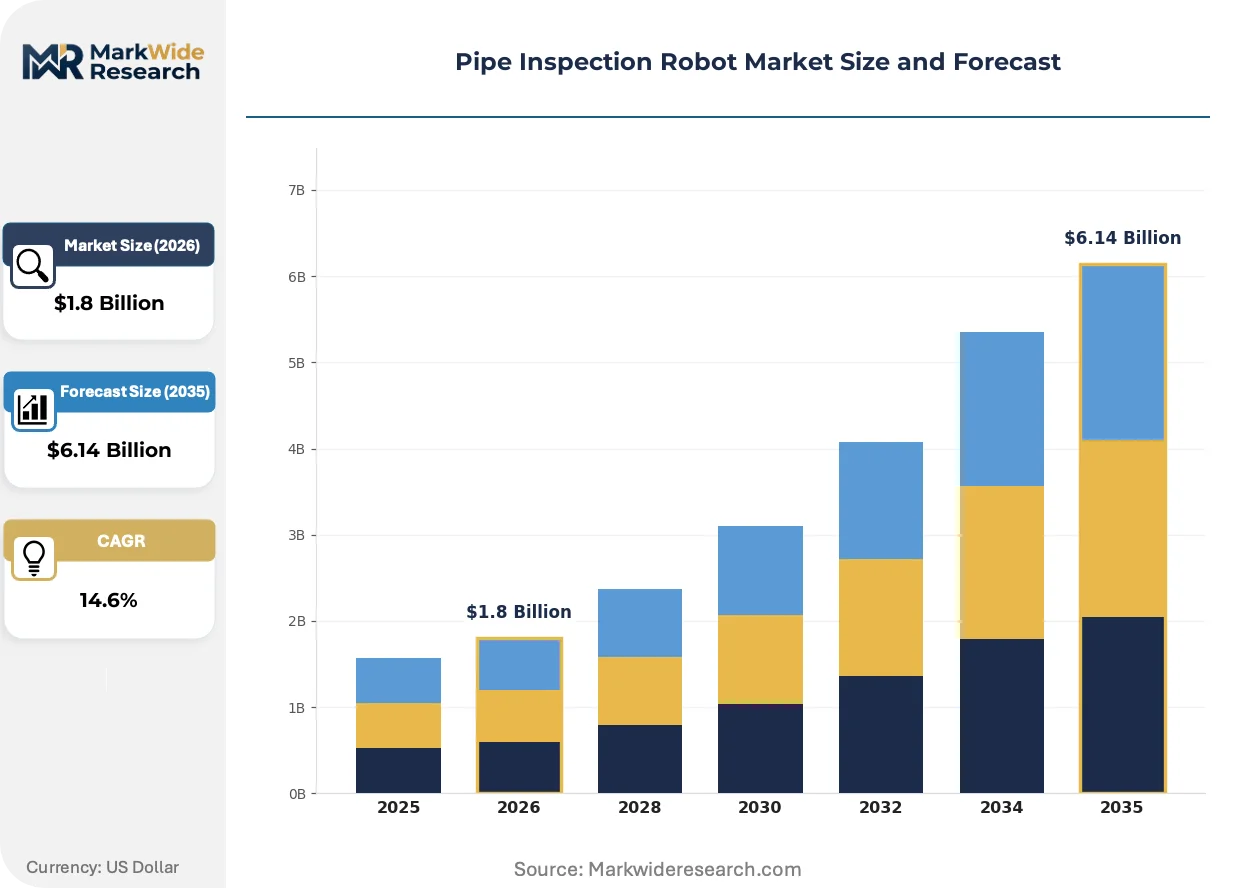
EPA sanitary sewer overflow regulations and the EU Urban Waste Water Treatment Directive mandate periodic structural assessment of collection systems, directly expanding the addressable base of inspection robot deployments. OSHA confined space entry standards further accelerate robotic substitution for human entry in hazardous pipeline environments. Stakeholders must monitor evolving interoperability standards between robot data formats and utility asset management platforms to secure long-term contract viability.
Market Dynamics
Municipal consent decrees in the United States are forcing water utilities to accelerate pipeline condition assessment schedules, compressing replacement cycles for aging crawler fleets and expanding the installed base of autonomous inspection platforms.
Growth Catalysts
- EPA Sanitary Sewer Overflow Regulations:Enforcement actions against non-compliant utilities in the United States mandate systematic structural assessment, creating immediate procurement pull for crawler-based CCTV systems.
- Ultrasonic thickness sensing:Wall-loss quantification capabilities in oil and gas transmission networks enable predictive replacement scheduling, displacing reactive maintenance models.
- Japan:METI-directed infrastructure resilience programs fund autonomous pipe assessment for earthquake-prone utility corridors, concentrating demand for precision-engineered platforms.
Market Restraints
- Lithium-ion battery supply concentration:Dependence on East Asian cell manufacturers creates procurement vulnerability for portable crawler systems with extended runtime requirements.
- OSHA confined space entry standards:Regulatory complexity around robotic substitution documentation slows deployment approval timelines in municipal procurement channels.
- Manual CCTV inspection:Low-cost operator-driven alternatives retain share in budget-constrained small-diameter sewer networks, capping price realization for entry-level autonomous units.
Strategic Opportunities
- India:Smart Cities Mission funding for underground utility mapping creates first-mover advantage for inspection-as-a-service providers establishing localized maintenance infrastructure.
- AI-powered defect classification:Machine vision convergence with laser profiling enables real-time structural grading, compressing analysis cycles from days to hours.
- EU Green Deal:Circular economy directives for water infrastructure lifespan extension mandate condition-based asset management, expanding inspection frequency requirements.
Industry Challenges
- NASSCO PACP certification timelines:Operator training and equipment validation requirements create deployment bottlenecks for utilities under consent decree deadlines.
- Legacy SCADA integration:Proprietary data formats from crawler OEMs obstruct seamless flow into centralized utility asset management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pipe Inspection Robot Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Magnetic, Optical, Robotic Application: Water Supply, Oil & Gas, Industrial, Sewage End User: Municipalities, Oil Refineries, Manufacturing Plants, Utility Companies Service Type: Inspection, Maintenance, Data Analysis, Repair |
| Companies Covered | GE Inspection Robotics, RedZone Robotics, Envirosight LLC, Inuktun Services Ltd, IBAK Helmut Hunger GmbH & Co. KG, CUES Inc., Honeybee Robotics, iPEK International GmbH, Deep Trekker Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pipe Inspection Robot Market Evolving Landscape
Autonomous navigation algorithms and edge-computing sensor fusion are compressing the gap between raw inspection data and actionable maintenance decisions, reshaping how utilities prioritize capital deployment.
SLAM-based autonomous navigation is automating trajectory planning in GPS-denied pipeline environments. Water utilities in Germany are deploying self-directed crawlers that eliminate tethered operator control, reducing crew-hour requirements by half. This capability is automating the transition from periodic inspection campaigns to continuous structural monitoring.
The EU Urban Waste Water Treatment Directive's 2027 compliance checkpoint is accelerating crawler fleet refresh cycles across municipal procurement in France and the Netherlands. Asset managers must demonstrate systematic condition assessment documentation, elevating data-integrity specifications in tender requirements. German utilities are responding by specifying EN 13508-2-compliant reporting formats in all new equipment acquisitions.
Subscription-based inspection-as-a-service models are displacing capital purchase patterns among mid-sized North American water districts. Third-party providers bearing equipment ownership risk are capturing share from municipal direct procurement. This shift is most visible in Texas and Florida, where private utility operators prioritize operational expenditure flexibility over balance-sheet asset ownership.
Pipe Inspection Robot Market Segmentation
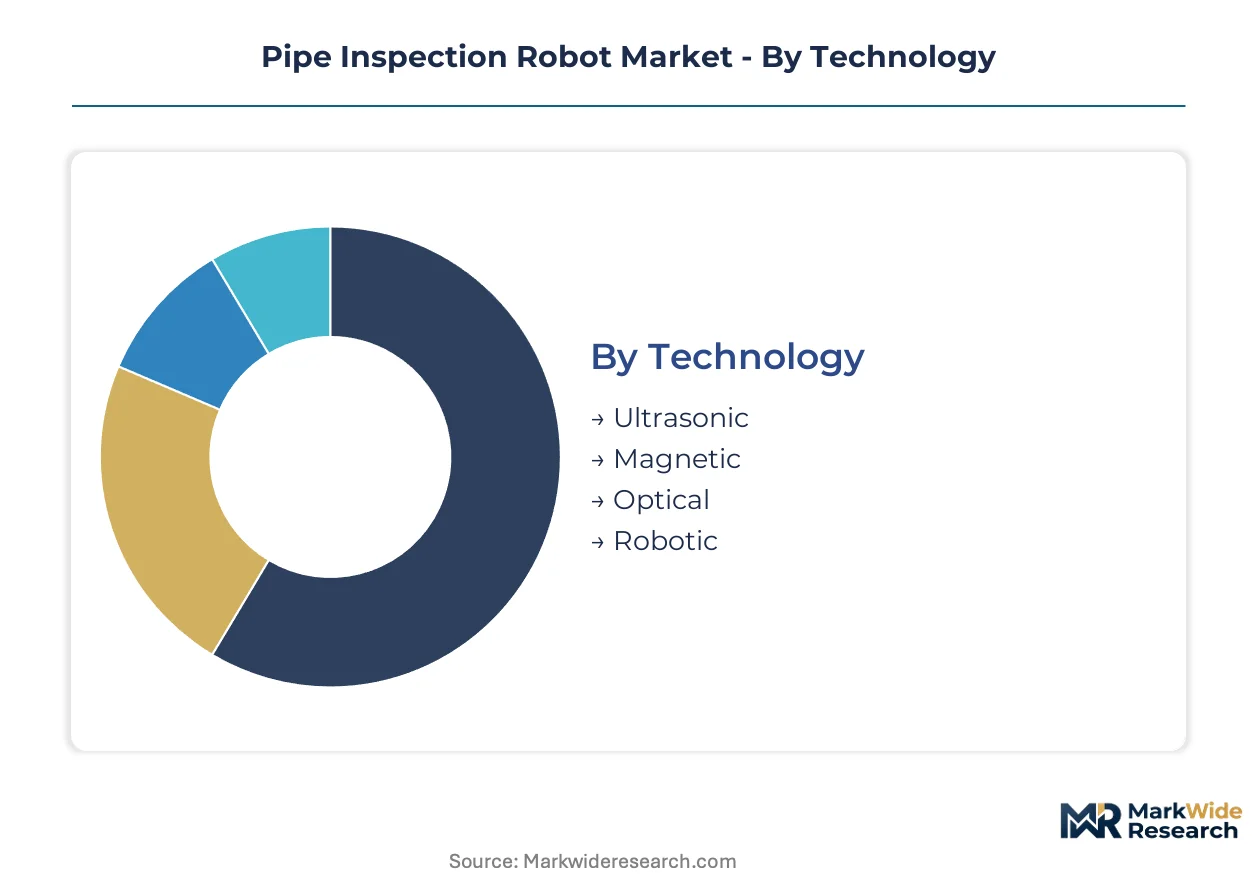
Technology integration depth determines procurement patterns across the pipe inspection robot market, with standalone crawler systems dominating municipal budgets while embedded sensor arrays penetrate industrial predictive maintenance contracts. Application requirements further fragment purchasing criteria, as oil and gas operators prioritize wall-thickness quantification against EPA spill prevention mandates while water utilities emphasize CCTV documentation for consent decree compliance.
Technology:
Standalone inspection platforms operate independently with onboard power and processing, whereas embedded systems integrate permanently into pipeline infrastructure for continuous monitoring. Integration depth varies sharply by end-use risk tolerance.
- Optical:CCTV camera arrays mounted on crawler chassis capture visual defect documentation under NASSCO PACP standards. Municipal procurement in the United States concentrates here due to lower per-unit cost and mature operator certification pathways. EPA sanitary sewer overflow enforcement drives replacement cycles for aging optical fleets.
- Ultrasonic:Thickness-sensing transducers quantify wall loss in metallic transmission pipelines without surface preparation. Oil and gas operators in Germany deploy these for predictive replacement scheduling under pressure equipment directives. METI-funded resilience programs in Japan accelerate adoption for earthquake-prone utility corridors.
- Magnetic:Flux leakage and eddy current systems detect corrosion anomalies in ferrous water mains. Brief treatment: Utility companies in the Netherlands specify magnetic platforms for cast iron network assessment ahead of EU Urban Waste Water Treatment Directive deadlines.
- Robotic:Autonomous navigation platforms with SLAM-based trajectory planning eliminate tethered operator control. Brief treatment: German manufacturers lead deployment of self-directed crawlers that halve crew-hour requirements for large-diameter sewer inspection.
Optical technology leads volumes today; ultrasonic platforms are gaining share fastest in corrosion-critical applications.
Application:
Cost tier segmentation separates budget-constrained municipal systems from capital-intensive industrial installations with continuous monitoring requirements.
- Sewage:Crawler-based CCTV systems traverse gravity sewer lines to document structural defects, infiltration, and flow obstructions. Consent decree deadlines in the United States compress assessment schedules and expand fleet procurement. NASSCO certification requirements create deployment bottlenecks for utilities under regulatory pressure.
- Water Supply:Potable water main inspection demands sanitizable platforms with pressure-rated enclosures. German utilities specify EN 13508-2-compliant reporting formats in tender requirements. The EU Green Deal's circular economy directives mandate condition-based lifespan extension for buried infrastructure.
- Oil & Gas:Pipeline integrity management programs require wall-thickness mapping for corrosion growth rate modeling. Brief treatment: FERC-regulated transmission operators in the United States prioritize ultrasonic platforms for high-consequence area assessments.
- Industrial:Process piping networks in chemical and power generation facilities deploy specialized crawlers for confined space entry substitution. Brief treatment: OSHA standards accelerate robotic substitution for human entry in hazardous pipeline environments.
Sewage applications dominate current installations; water supply segments are expanding most quickly under directive-driven assessment mandates.
End User:
Customer type determines procurement modality, with municipalities favoring capital purchase and private operators shifting toward operational expenditure models.
- Municipalities:Public water and sewer authorities procure crawler fleets through competitive bidding with extensive distributor coverage requirements. Texas and Florida districts increasingly adopt inspection-as-a-service to preserve balance-sheet flexibility.
- Utility Companies:Private water and wastewater operators prioritize equipment interoperability with centralized asset management platforms. Brief treatment: Legacy SCADA integration challenges obstruct seamless data flow from proprietary crawler formats.
- Oil Refineries:Downstream processing facilities deploy specialized platforms for furnace tube and flare line assessment. Brief treatment: Predictive maintenance programs displace reactive turnaround inspection schedules.
- Manufacturing Plants:Industrial process operators require portable systems for periodic integrity verification. Brief treatment: Lithium-ion battery supply concentration creates procurement vulnerability for extended runtime requirements.
Municipalities anchor current demand; utility companies are shifting procurement patterns fastest toward service-based models.
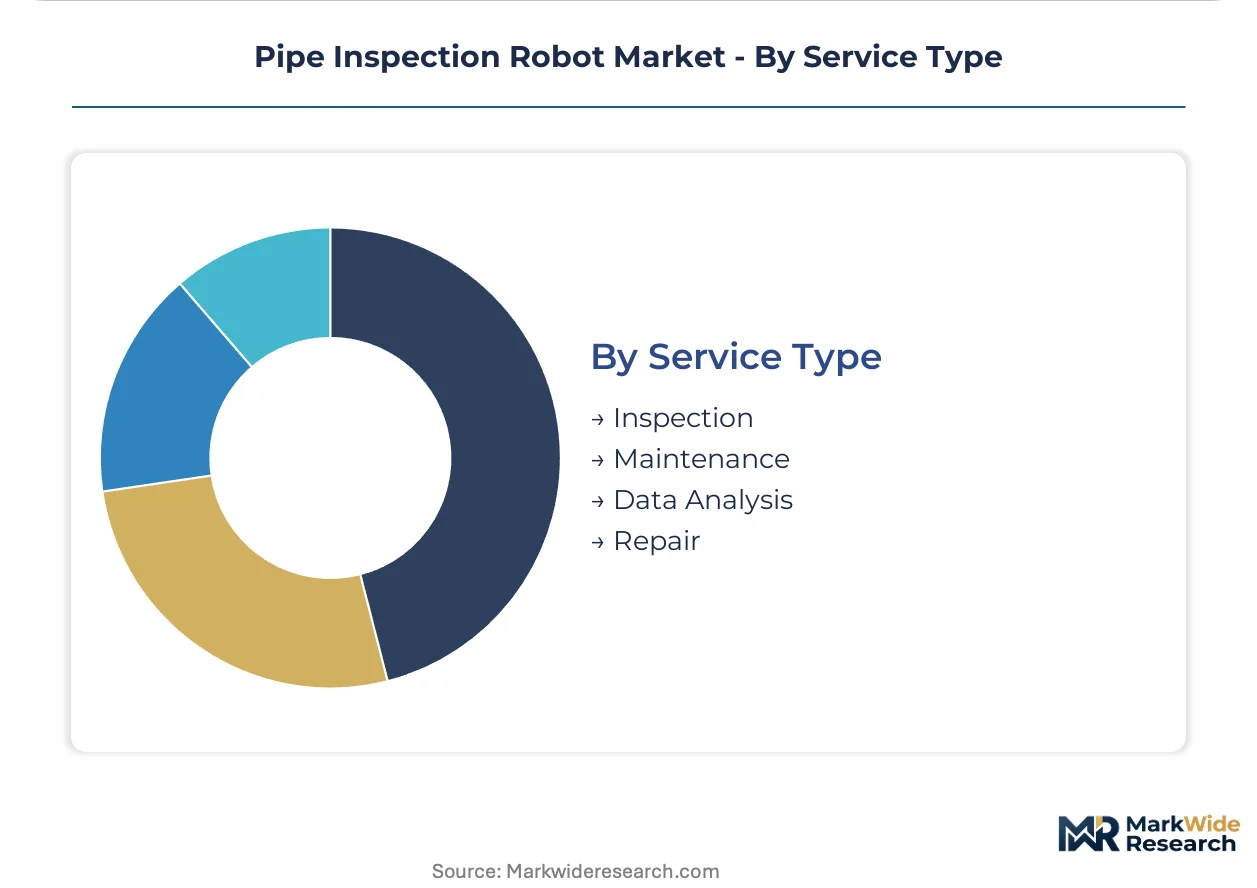
Service Type:
Margin structure varies across the service spectrum, with data analysis commanding premium pricing against commoditized inspection labor.
- Inspection:Field deployment of crawler systems to capture raw condition data remains the volume foundation. Brief treatment: Manual CCTV alternatives retain share in budget-constrained small-diameter networks.
- Data Analysis:AI-powered defect classification compresses structural grading cycles from days to hours. Machine vision convergence with laser profiling enables real-time prioritization of capital deployment.
- Maintenance:Preventive scheduling based on condition assessment outputs extends asset lifespan. Brief treatment: EU Green Deal mandates elevate inspection frequency requirements for circular economy compliance.
- Repair:Trenchless rehabilitation coordination requires precise defect localization from robotic survey data. Brief treatment: Cured-in-place pipe installers depend on accurate crawler measurements for liner dimensioning.
Inspection services generate the highest volumes today; data analysis is climbing the fastest as utilities automate defect interpretation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese precision engineering houses capture premium-tier margins as EPA consent decrees and METI resilience programs widen the cost-of-compliance gap against budget-constrained municipal procurement channels elsewhere.
United States
EPA sanitary sewer overflow enforcement compels systematic structural assessment across aging municipal networks. Consent decree deadlines compress replacement cycles for crawler fleets in Texas and Florida districts. Houston and Miami-Dade utilities increasingly adopt inspection-as-a-service models to preserve capital flexibility.
Germany
EN 13508-2-compliant reporting mandates elevate data-integrity specifications in tender requirements for municipal sewer assessment. The EU Urban Waste Water Treatment Directive accelerates crawler fleet refresh cycles across Rhineland and Bavarian utility corridors. Munich-based engineering clusters specialize in self-directed SLAM navigation platforms.
Japan
METI-directed infrastructure resilience programs concentrate demand for earthquake-prone utility corridor assessment. Precision-engineered autonomous platforms penetrate Tokyo-Osaka industrial corridors under national disaster mitigation funding. Nagoya manufacturing bases supply high-durability crawler systems for seismic zone deployment.
Netherlands
EU Green Deal circular economy directives mandate condition-based lifespan extension for buried water infrastructure. Dutch utilities specify magnetic flux leakage platforms for cast iron network assessment ahead of 2027 compliance checkpoints. Rotterdam-Eindhoven industrial clusters integrate inspection data with centralized asset management platforms.
India
Smart Cities Mission funding for underground utility mapping creates first-mover opportunity for inspection-as-a-service providers. Municipal corporations in Maharashtra and Gujarat pilot crawler-based CCTV systems for non-revenue water reduction. Bangalore and Hyderabad technology clusters develop localized maintenance infrastructure for autonomous pipe assessment platforms.
Pipe Inspection Robot Market Competitive Landscape
German producers anchor the precision-engineering tier; North American specialists hold the portable-systems segment. The vendor base splits between consolidated municipal procurement channels and fragmented industrial niche suppliers. Three archetypes dominate: optical-CCTV incumbents with distributor infrastructure, ultrasonic specialists serving corrosion-critical oil and gas networks, and autonomous-navigation challengers eliminating tethered operator control. Capacity expansion and AI-powered defect classification partnerships represent the dominant competitive vectors.
Among German fabricators, IBAK Helmut Hunger GmbH & Co. KG and iPEK International GmbH exemplify the precision-engineering archetype with specialized optical platforms for municipal sewer networks. Deep Trekker Inc. represents the portable-ROV positioning for North American freshwater and industrial segments. These three anchors illustrate how geographic specialization and application focus segment competitive positioning across procurement channels.
| Leading Market Players |
|---|
| GE Inspection Robotics |
| RedZone Robotics |
| Envirosight LLC |
| Inuktun Services Ltd |
| IBAK Helmut Hunger GmbH & Co. KG |
| CUES Inc. |
| Honeybee Robotics |
| iPEK International GmbH |
| Deep Trekker Inc. |
| Others |
Value Network & Pricing Analysis
Captive integration into precision sensor manufacturing anchors German and Japanese producers in premium-tier positioning, while outsourced assembly in lower-cost jurisdictions enables price competition in portable crawler segments. This bifurcation concentrates margin capture with optical-CCTV incumbents who control distributor networks, while modular component sourcing exposes entry-level autonomous platforms to lithium-ion cell price volatility.
Pricing Analysis
Distributor margin layering in municipal procurement channels absorbs 15-25 points before equipment reaches utility buyers, compressing manufacturer realized pricing against direct industrial sales. Three-tier pricing structure across EN 13508-2 certified, NASSCO PACP compliant, and uncertified economy levels segments buyer willingness-to-pay by regulatory exposure. Cost compression in portable crawler tiers intensifies as Texas and Florida districts shift toward inspection-as-a-service, transferring equipment ownership risk to third-party providers. Small-diameter sewer operators exhibit highest price sensitivity, retaining manual CCTV alternatives where consent decree pressure remains absent.
Supply Chain Analysis
Refurbishment flows for high-durability crawler chassis extend asset lifecycles and create secondary parts markets that compete with OEM spare pricing. Component sourcing draws from Japan for precision drive systems, Germany for optical sensor arrays, and South Korea for lithium-ion power modules. Single-source vulnerability concentrates in East Asian battery cell supply, exposing portable system manufacturers to procurement disruption. Distribution runs through specialized environmental equipment distributors with NASSCO-certified training infrastructure, locking municipal channel access behind technical validation requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
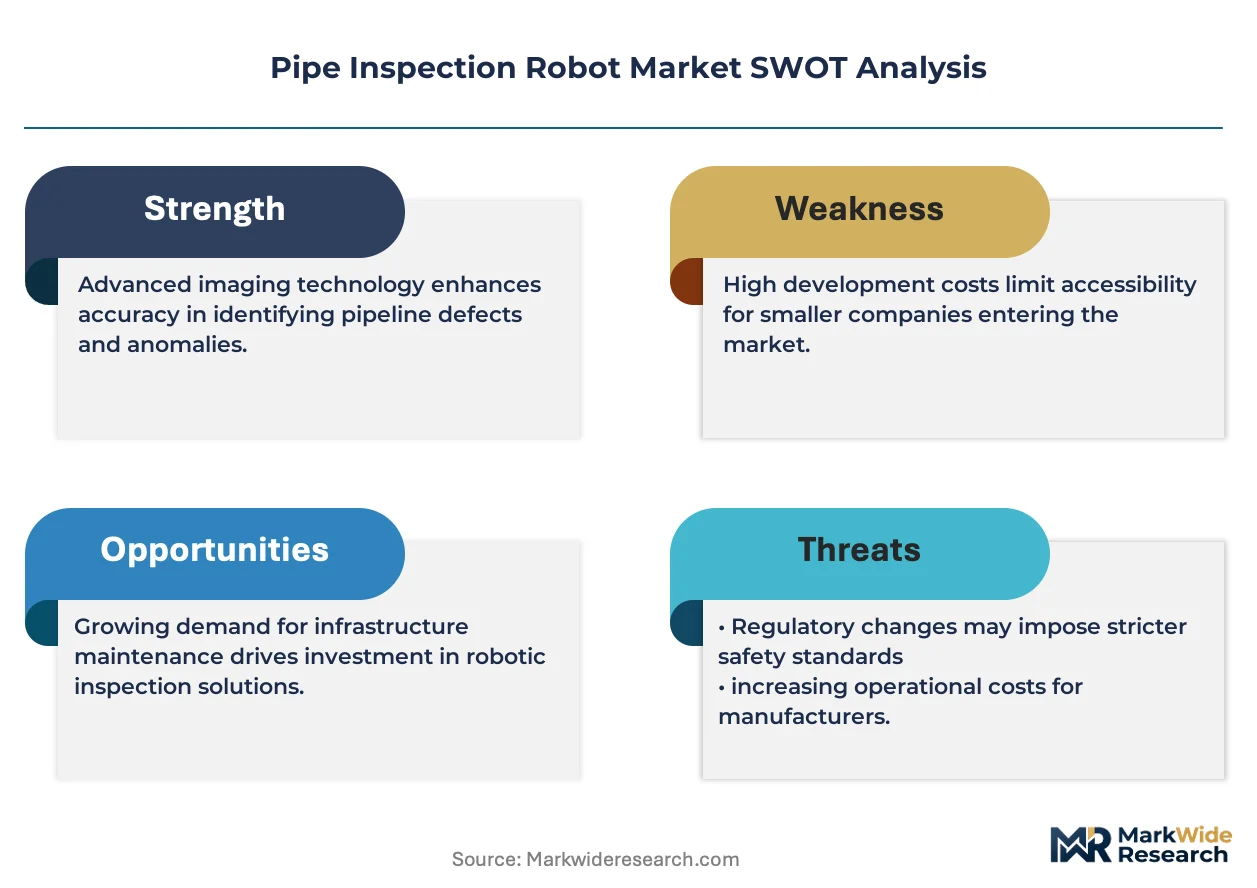
Pipe inspection robot demand compounds through regulatory enforcement layering, with EPA consent decree deadlines and EU Urban Waste Water Treatment Directive checkpoints creating predictable procurement waves that favor prepared suppliers.
For Market Incumbents: Deepen backward integration into optical sensor manufacturing to defend margin position against ultrasonic platform encroachment in oil and gas corrosion monitoring. Expand captive training infrastructure to accelerate NASSCO PACP certification throughput for utilities under consent decree pressure, converting deployment bottlenecks into channel lock-in. For New Entrants and Emerging Players: Enter via inspection-as-a-service models in Texas and Florida municipal districts, where operational expenditure flexibility outweighs capital ownership preferences. Target mid-sized water authorities with bundled data-analysis offerings that automate defect classification, capturing share from equipment-only vendors lacking AI-powered interpretation layers. For Investors and Strategic Acquirers: Roll-up economics work for regional inspection-service providers because fragmented municipal procurement channels reward localized maintenance infrastructure and relationships. Five-to-ten year viability hinges on data-format interoperability with utility asset management platforms. Monitor EPA enforcement action intensity against non-compliant utilities as early signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Defect Classification Development | Machine vision convergence with laser profiling compresses structural grading cycles for consent decree compliance. |
| SLAM Navigation Platform Launch | Self-directed crawlers halve crew-hour requirements in German large-diameter sewer inspection deployments. |
| Inspection-as-a-Service Expansion | Subscription models capture Texas and Florida districts shifting from capital purchase to operational expenditure. |
| EN 13508-2 Certification Investment | Compliant reporting formats unlock EU municipal tender participation ahead of Urban Waste Water Treatment Directive deadlines. |
| Lithium-Ion Supply Diversification | Alternative cell sourcing mitigates procurement vulnerability for portable crawler extended runtime requirements. |
Research Methodology
Multiple input streams — primary interviews with municipal procurement officers, crawler OEM technical directors, and NASSCO certification trainers; secondary validation through EPA enforcement databases, EU tender documentation, and utility capital expenditure disclosures; plus customs trade data for component flows — were reconciled through bottom-up and top-down triangulation. Field intelligence from equipment distributors in Texas, Florida, and Rhineland utility corridors informed procurement pattern assessment. Secondary sources included FERC pipeline integrity filings, METI infrastructure resilience program announcements, and Smart Cities Mission project databases.
Historical shipment data was cross-referenced against panel input from utility asset managers to anchor growth assumptions across the analysis window. Segmentation modeling incorporated technology tier, application risk profile, end-user procurement modality, and regional regulatory enforcement intensity. CAGRs were derived from installed base replacement cycles and first-time adoption curves in emerging markets. Forecast inputs included lithium-ion battery cost trajectories, AI vision processing cost declines, and municipal budget elasticity under consent decree pressure.
The model holds under continued EPA and EU directive enforcement; deviation in regulatory forbearance or lithium supply disruption would shift replacement timing and geographic penetration rates. Practitioners should monitor EPA consent decree settlement announcements and EU Green Deal implementation guidance for early signals of procurement cycle acceleration or delay.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Europe Agricultural Robots and Mechatronics Market
Robotics and Automation
Palletizing Robots Market
Robotics and Automation
Gimbal Stabilizers Market
Robotics and Automation
Robotic Tool Changer Market
Robotics and Automation
Global Articulated Robot Market
Robotics and Automation
Delta Robotics Market
Robotics and Automation
Mobile Robotics Software Market
Robotics and Automation
Healthcare Robots Market
Robotics and Automation
Indonesia Robotics Market
Robotics and Automation
Search and Rescue Robots Market
Robotics and Automation
Hospital Robots Market
Robotics and Automation
Global Delivery Robots Market
Robotics and Automation
Simultaneous Localization and Mapping (SLAM) Market
Robotics and Automation
Modular Robotics Market
Robotics and Automation
Global Security Robots Market
Robotics and Automation
Household Cleaning Robotics Market