
 Walkie Talkie Market | 2026-2036
Walkie Talkie Market Size, Share, and Industry Trends Forecast 2026-2036
Walkie Talkie Market Outlook
Enterprise security teams are unwinding dependence on cellular backup as primary push-to-talk channels. Motorola Solutions Inc. dominates North American public safety procurement through its integrated command-center ecosystem. Hytera Communications Corporation Limited competes aggressively on price in emerging markets with DMR Tier III trunking solutions. Kenwood Corporation specializes in compact, mil-spec handheld units for wildland firefighting agencies.
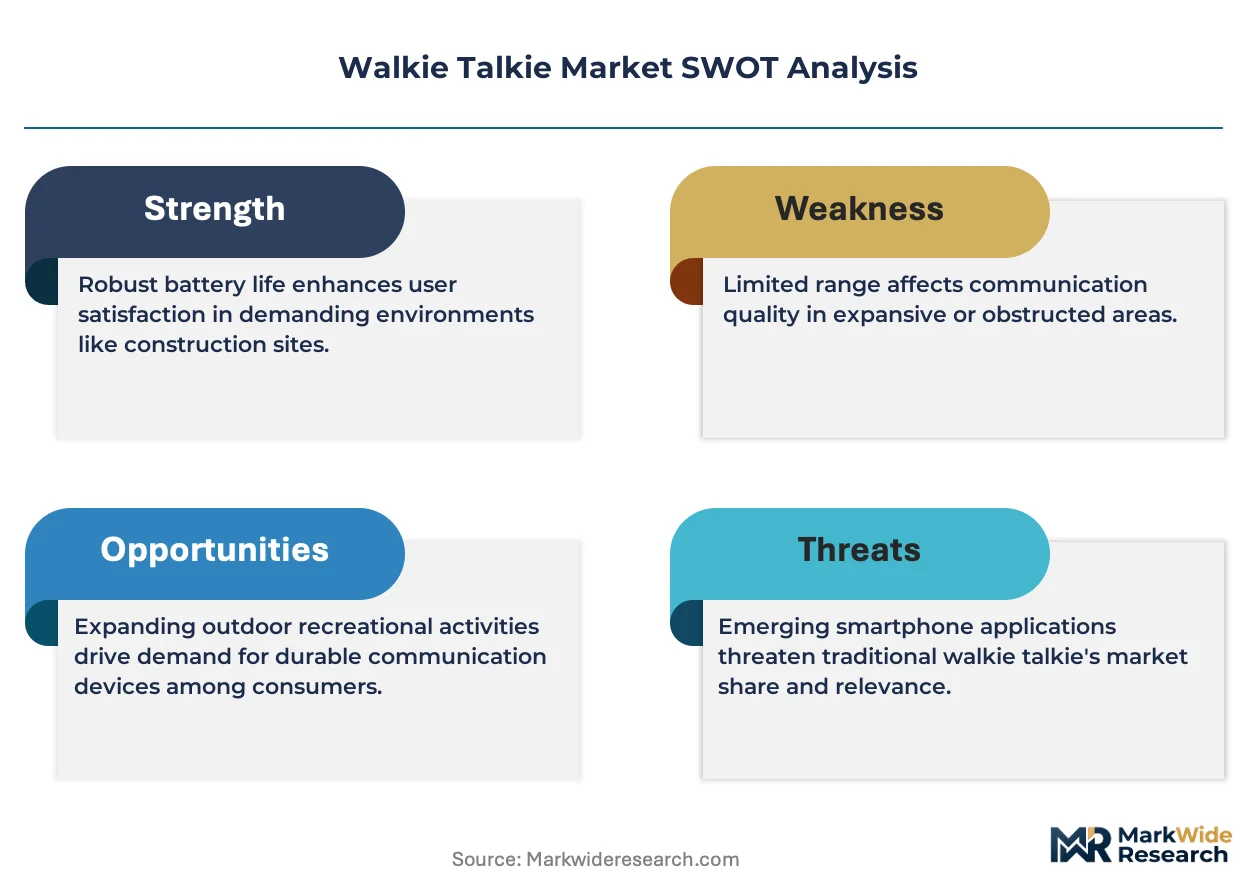
A walkie talkie is a portable, two-way radio transceiver operating on licensed VHF, UHF, or 700/800 MHz public safety bands, typically delivering 0.5–5 watts output power with push-to-talk half-duplex voice communication. The device enables instant group coordination without cellular infrastructure, serving construction foremen, hotel operations staff, and disaster response commanders. Digital walkie talkies now command the fastest expansion as AES-256 encryption, GPS telemetry, and over-the-air programming replace legacy analog voice-only units. The emergency services end-user segment anchors premium pricing, where agencies mandate P25 Phase 2 compliance and multi-band interoperability. Short-range devices in hospitality face margin compression from smartphone-based PoC apps, though analog walkie talkies persist in cost-sensitive developing markets.
FCC Part 90 rules govern U.S. land mobile radio licensing, while the EU Radio Equipment Directive 2014/53/EU mandates CE marking and spectrum harmonization across member states. Manufacturers must navigate divergent frequency allocations, as Brazil's ANATEL and India's WPC impose local type-approval requirements that delay product launches. Stakeholders should monitor software-defined radio architectures that promise multi-protocol flexibility without hardware swaps.
Market Dynamics
Spectrum scarcity and FCC narrowbanding mandates are forcing public safety agencies into accelerated hardware refresh cycles, compressing replacement timelines from decade-long analog deployments to encrypted digital systems.
Growth Catalysts
- FCC narrowbanding mandates:Federal spectrum reallocation rules in the United States compel legacy analog fleet replacement, creating sustained procurement volume for P25 Phase 2 compliant hardware.
- Encrypted digital migration:AES-256 encryption and GPS telemetry integration are displacing voice-only analog units across emergency services, expanding average unit value.
- Wildland firefighting specialization:Compact mil-spec handheld demand from federal land management agencies is concentrating premium procurement in ruggedized form factors.
Market Restraints
- Semiconductor supply volatility:RF component lead times and foundry capacity constraints in East Asian manufacturing clusters delay OEM delivery schedules.
- Smartphone PoC substitution:Cellular-based push-to-talk applications are eroding hospitality and retail price points, compressing margins in sub-premium tiers.
- Local type-approval fragmentation:Divergent frequency allocations and certification requirements from Brazil's ANATEL and India's WPC extend product launch timelines by 12-18 months.
Strategic Opportunities
- Software-defined radio architectures:Multi-protocol flexibility without hardware swaps enables single-device coverage of P25, DMR, and analog legacy systems.
- Hotel operations digitization:Property management system integration and indoor positioning telemetry create upsell potential in hospitality verticals previously lost to smartphone apps.
- EU Radio Equipment Directive harmonization:CE marking standardization across member states reduces certification duplication costs for pan-European deployments.
Industry Challenges
- RF engineering talent scarcity:Specialized microwave and trunking protocol expertise required for P25 Phase 2 development concentrates in defense contractors, limiting vendor hiring pools.
- Legacy system integration complexity:Municipal agencies demand backward compatibility with decades-old analog infrastructure, forcing dual-mode hardware designs that increase BOM costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Walkie Talkie Market |
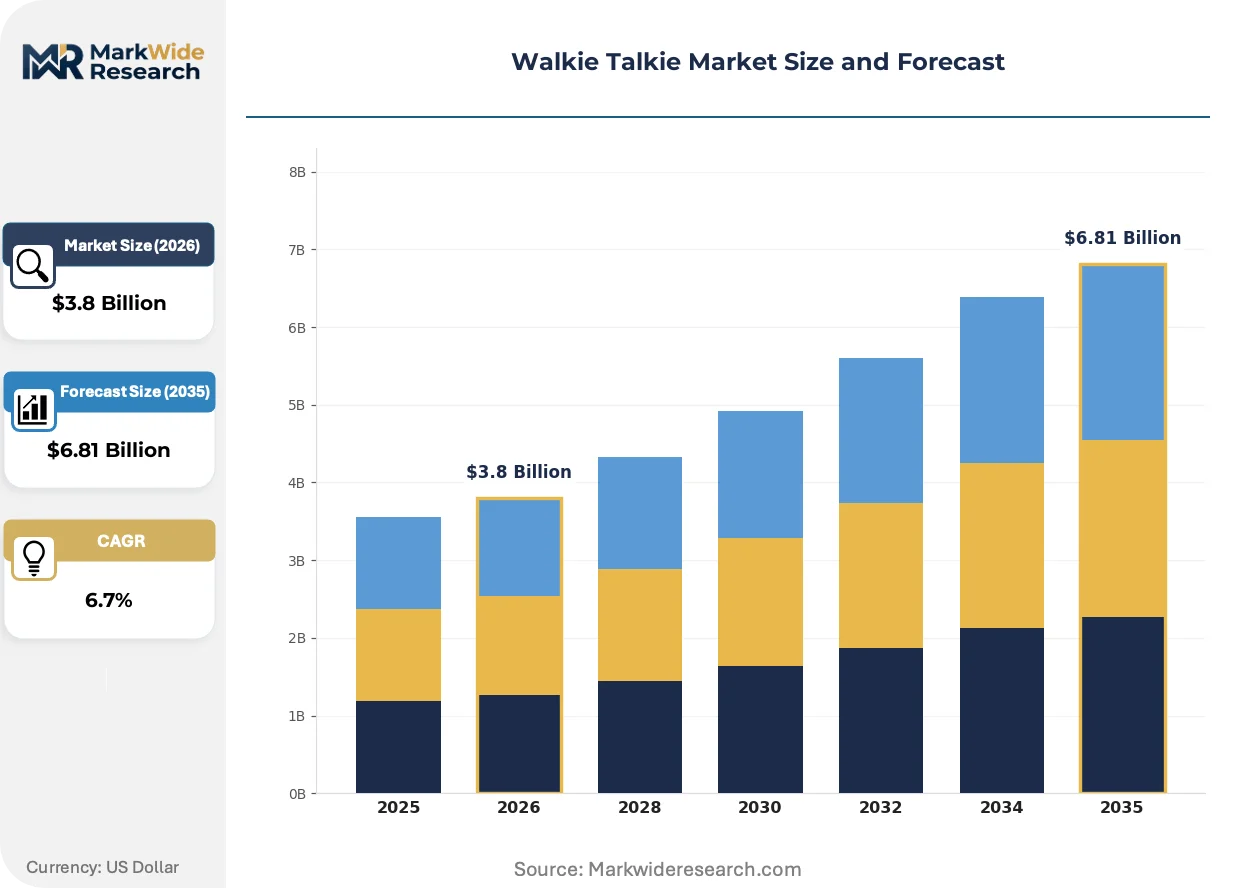
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Walkie Talkies, Digital Walkie Talkies, Multichannel Walkie Talkies, Waterproof Walkie Talkies End User: Construction, Security, Hospitality, Emergency Services Communication Range: Short Range, Medium Range, Long Range, Very Long Range Channel Count: Single Channel, Dual Channel, Multi-Channel, Advanced Channel |
| Companies Covered | Hytera Communications Corporation Limited, Uniden Corporation, Motorola Solutions Inc., Zebra Technologies, Cobra Electronics Corporation, Kenwood Corporation, Tait Communications, Vertex Standard, Icom Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Walkie Talkie Market Strategic Shifts
Digital voice protocols and over-the-air reprogramming capabilities are dissolving the hardware-software boundary in professional radio equipment, enabling post-sale feature monetization and remote fleet management.
Software-defined radio platforms are decomposing the traditional fixed-architecture transceiver market. Public safety agencies in the United States are piloting field-programmable units that switch between P25, DMR, and LTE waveforms without hardware swaps. This flexibility is compressing vendor lock-in and enabling multi-agency interoperability without fleet standardization.
EU Radio Equipment Directive 2014/53/EU harmonization is eliminating member-state certification fragmentation. Manufacturers now submit to single CE marking processes valid across Germany, France, and Italy. The directive accelerates product launches but mandates stricter electromagnetic compatibility testing that elevates R&D overhead for smaller OEMs.
Enterprise security teams are unwinding cellular backup dependence for mission-critical push-to-talk. Construction foremen and hotel operations managers are reverting to licensed VHF and UHF hardware as primary channels, treating cellular as failover only. This behavioral pivot is visible most acutely in hurricane-prone Gulf Coast states where cellular infrastructure proved unreliable during emergency response.
Walkie Talkie Market Segmentation
Walkie talkie procurement patterns diverge sharply across user environments, with FCC mandates and spectrum licensing rules creating distinct compliance tiers that reshape product specifications. Understanding these segment boundaries reveals where hardware refresh cycles concentrate and where margin compression threatens incumbent suppliers.
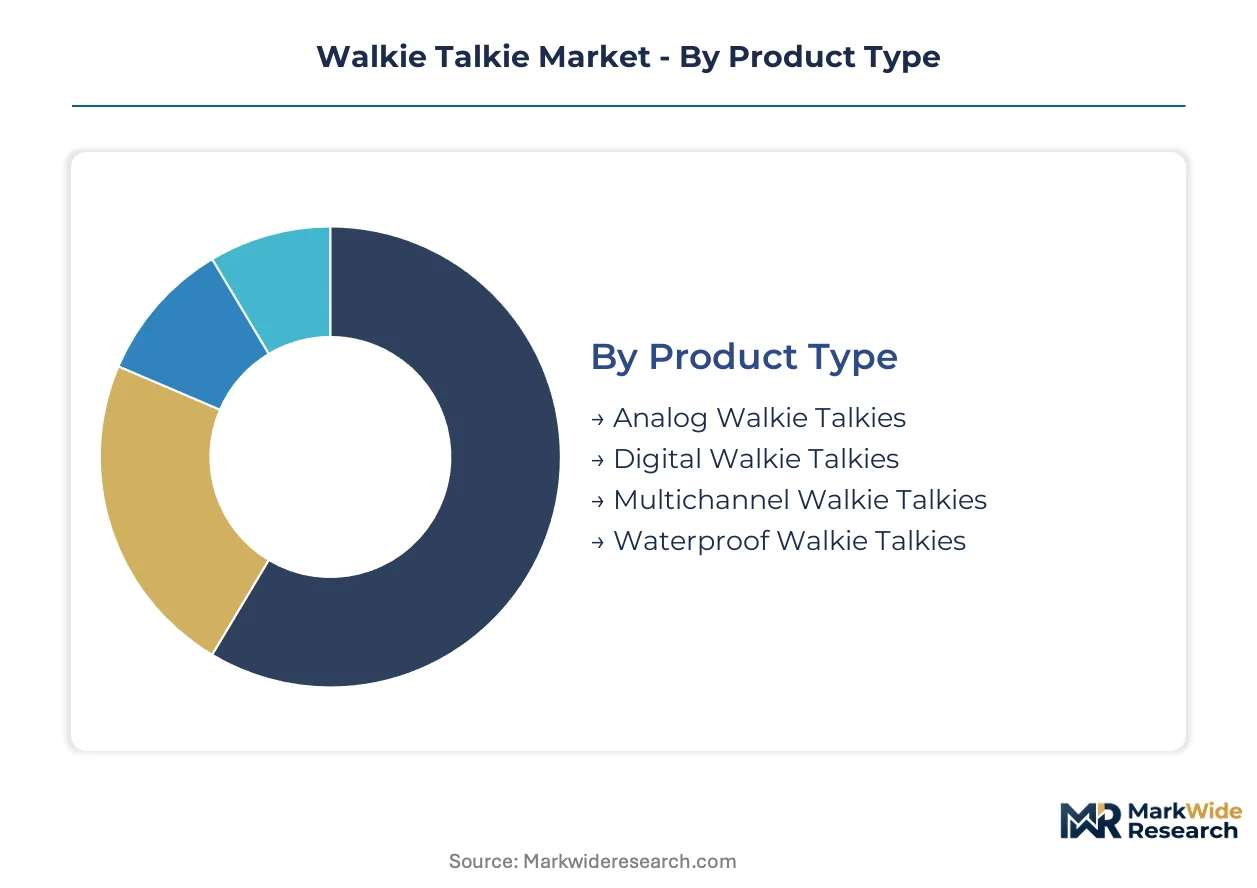
Product Type:
FCC narrowbanding mandates and encryption requirements create regulatory fault lines that separate compliant digital systems from legacy analog hardware.
- Digital Walkie Talkies:AES-256 encryption, GPS telemetry, and over-the-air reprogramming capabilities satisfy P25 Phase 2 compliance for emergency services. Federal interoperability grants in the United States fund multi-agency network upgrades, concentrating premium procurement in encrypted trunking systems.
- Analog Walkie Talkies:Voice-only transmission on licensed VHF and UHF bands persists in cost-sensitive developing markets where regulatory deadlines remain distant. Hospitality and retail operations in India and Brazil continue analog fleet expansion despite narrowbanding pressure in North America.
- Multichannel Walkie Talkies:Programmable group channels enable construction site coordination across overlapping contractor teams.
- Waterproof Walkie Talkies:IP67-rated enclosures serve marine patrol and wildland firefighting agencies in hurricane-prone Gulf Coast states.
Established volume favors analog walkie talkies; emerging adoption favors digital walkie talkies.
End User:
Application environment dictates durability specifications, with mil-grade requirements in federal land management contrasting sharply with lightweight hospitality deployments.
- Emergency Services:P25 Phase 2 compliance, multi-band interoperability, and ruggedized form factors anchor premium pricing. Wildland firefighting agencies demand compact mil-spec handhelds with extended battery life for remote deployment.
- Construction:Licensed VHF and UHF hardware serves as primary push-to-talk channels, with cellular treated as failover only. Gulf Coast contractors unwound cellular dependence after infrastructure failures during emergency response.
- Security:Enterprise teams prioritize licensed spectrum independence from cellular congestion at large venues and critical infrastructure sites.
- Hospitality:Smartphone-based PoC apps erode price points, though property management system integration creates upsell potential for digital units with indoor positioning telemetry.
Emergency services concentrate procurement value; hospitality faces the steepest substitution pressure.
Communication Range:
Output power and antenna architecture segment the market into distinct licensing and infrastructure investment tiers.
- Long Range:5-watt output power with repeater infrastructure supports regional public safety networks across dispersed municipalities. FCC spectrum reallocation accelerates hardware refresh cycles for these deployments.
- Very Long Range:Trunking systems and tower networks enable statewide interoperability for emergency command structures, requiring sustained capital expenditure.
- Medium Range:2-4 watt units balance portability with building penetration for urban security patrols.
- Short Range:0.5-2 watt FRS/GMRS devices serve hotel operations and retail floor management where cellular backup suffices.
Very long range systems command infrastructure budgets; short range devices confront PoC displacement.
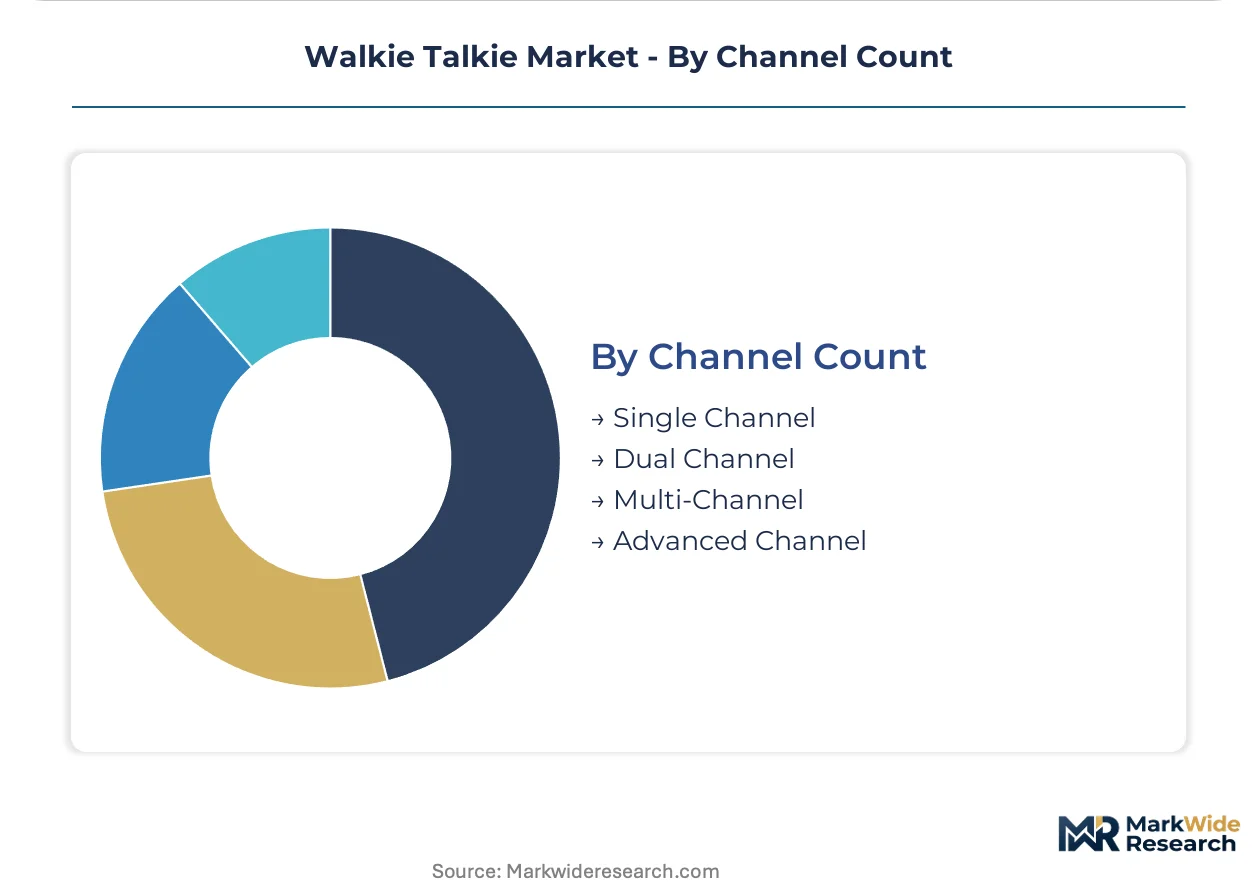
Channel Count:
Fleet complexity and interoperability requirements scale directly with channel architecture sophistication.
- Multi-Channel:16-32 programmable channels enable construction foremen to segregate trade-specific communications while maintaining emergency override access.
- Advanced Channel:Trunked systems with dynamic channel assignment support hundreds of simultaneous talk groups for metropolitan emergency services.
- Dual Channel:Monitor capability allows security supervisors to track perimeter and lobby frequencies simultaneously.
- Single Channel:Dedicated frequency simplicity persists in small-scale hospitality and retail operations with minimal coordination complexity.
Multi-channel configurations dominate commercial procurement; advanced channel systems gain share fastest in public safety digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast's 7,500-mile pipeline and refinery network sustains emergency response procurement for petrochemical corridor security teams. Dense port infrastructure from Rotterdam to Singapore creates parallel demand clusters for licensed spectrum coordination.
United States
Federal interoperability grants drive multi-agency P25 Phase 2 upgrades across municipal police and fire departments. FCC narrowbanding mandates compress replacement timelines from decade-long analog cycles to encrypted digital refreshes. Gulf Coast hurricane response corridors concentrate procurement in Houston and New Orleans, where cellular infrastructure failures accelerated licensed VHF dependence.
Germany
Industrial security teams at Ruhr Valley chemical complexes prioritize licensed UHF hardware for blast-resistant facility coordination. EU Radio Equipment Directive 2014/53/EU harmonization eliminates member-state certification duplication, though stricter electromagnetic compatibility testing elevates R&D overhead. Bavaria's automotive manufacturing belt generates demand for multichannel units across supplier park logistics.
China
MIIT spectrum allocations for professional mobile radio expand licensed capacity at Shanghai Port and Ningbo-Zhoushan container terminals. Domestic manufacturers compete aggressively on DMR Tier III trunking price points for Belt and Road infrastructure projects. Shenzhen's electronics manufacturing cluster supplies RF components with compressed lead times relative to East Asian competitors.
India
WPC type-approval requirements extend product launch timelines by 12-18 months for imported professional radio equipment. Analog walkie talkies persist in cost-sensitive hospitality and retail operations across Mumbai and Delhi-NCR despite narrowbanding pressure elsewhere. Domestic assembly incentives under the PLI scheme attract component localization for sub-2 watt FRS devices.
Brazil
ANATEL certification fragmentation complicates entry for trunking system vendors serving São Paulo's private security sector. Oil platform coordination off Rio de Janeiro's coast drives demand for IP67-rated marine units. Analog fleets expand in retail and construction segments where regulatory deadlines remain distant.
Walkie Talkie Market Competitive Environment
Listed leaders compete with private specialists across spectrum licensing and encryption certification dimensions. The vendor base stratifies into three tiers: integrated command-center ecosystem providers, price-competitive trunking specialists, and compact mil-spec handheld fabricators. Consolidation pressure concentrates in North American public safety procurement, where federal grant funding favors established certification holders. Dominant competitive moves include strategic partnerships for multi-protocol software-defined radio development and geographic expansion through local type-approval partnerships.
Within the integrated ecosystem tier, Motorola Solutions Inc. anchors premium positioning through command-center software bundling. Hytera Communications Corporation Limited and Kenwood Corporation exemplify divergent specialization strategies—Hytera occupies the price-competitive DMR trunking segment while Kenwood concentrates ruggedized form factors for federal land management agencies. These three entities represent the dominant competitive archetypes shaping procurement patterns across emergency services, industrial security, and hospitality verticals.
| Leading Market Players |
|---|
| Hytera Communications Corporation Limited |
| Uniden Corporation |
| Motorola Solutions Inc. |
| Zebra Technologies |
| Cobra Electronics Corporation |
| Kenwood Corporation |
| Tait Communications |
| Vertex Standard |
| Icom Inc. |
| Others |
Value Chain & Pricing Dynamics
FCC Part 90 narrowbanding compliance gates both supplier qualification and price differentiation simultaneously, forcing OEMs to absorb certification overhead while agencies pay premiums for encrypted P25 Phase 2 hardware. This regulatory threshold concentrates procurement value among certification holders and segments the market into compliance tiers that reshape margin structures.
Pricing Analysis
Volume-discount tiering separates federal interoperability grant recipients from municipal agencies purchasing in smaller lots. Three-tier pricing structure across premium, standard, and economy levels reflects encryption certification grade, ruggedization spec, and after-sales service bundling. Cost compression in hospitality and retail analog tiers is intensifying because smartphone PoC apps erode licensed hardware demand. Construction foremen and emergency services agencies exhibit lowest price sensitivity; budget hotel operators in developing markets show highest.
Supply Chain Analysis
Strategic stockpiling of RF components dominates procurement behavior as foundry capacity constraints in Taiwan, South Korea, and Japan create persistent lead time volatility. Shenzhen's electronics cluster feeds from GaAs power amplifiers, ceramic filters, and lithium-polymer cells. Single-source vulnerability in East Asian semiconductor fabrication threatens OEM delivery schedules. Distribution runs through authorized dealer networks serving public safety procurement officers and industrial security teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense imperative against cellular-based push-to-talk applications that erode licensed hardware demand in hospitality and retail verticals. Smartphone PoC platforms threaten margin compression across sub-premium tiers.
For Market Incumbents: Compound software-defined radio capabilities to enable multi-protocol flexibility without hardware swaps, neutralizing smartphone PoC displacement in enterprise security. Deepen backward integration into RF component supply to buffer foundry capacity volatility in East Asian manufacturing clusters. Prioritize P25 Phase 2 certification maintenance to retain federal interoperability grant access.
For New Entrants and Emerging Players: Fleet management software integration represents a service-layer gap where incumbents under-serve construction and logistics operators. Target property management system integration for hospitality verticals previously lost to smartphone apps. Pursue local type-approval partnerships in Brazil and India to bypass 12-18 month launch delays.
For Investors and Strategic Acquirers: FCC narrowbanding deadlines reshape the acquisition landscape toward certification-rich targets with established public safety dealer networks. Five-to-ten year viability hinges on software-defined radio transition execution rather than legacy analog manufacturing scale. Monitor ANATEL and WPC regulatory harmonization progress as inflection indicator for emerging market entry feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Enables P25, DMR, and LTE waveform switching without hardware swaps for multi-agency interoperability. |
| Local Type-Approval Partnership | Accelerates ANATEL and WPC certification timelines by 12-18 months for Brazil and India entry. |
| Property Management System Integration | Captures hospitality upsell potential with indoor positioning telemetry previously lost to smartphone PoC apps. |
| RF Component Supply Security | Reduces foundry capacity vulnerability through strategic stockpiling or captive supply of GaAs amplifiers. |
| Federal Interoperability Grant Alignment | Secures sustained procurement volume from multi-agency network upgrade funding in United States public safety. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with public safety procurement officers, RF engineering directors, hotel operations managers, and construction site foremen; and secondary validation through FCC equipment authorization databases, EU CE marking registries, ANATEL and WPC type-approval filings, and customs trade records. Bottom-up triangulation across OEM shipment estimates and top-down reconciliation against federal grant disbursement data anchored volume forecasts.
Across the analysis window, the forecasting framework modeled product type, end-user vertical, communication range tier, and channel architecture sophistication. CAGRs derived from segment-level growth rate reconciliation against macroeconomic indicators and regulatory deadline schedules. Forecast inputs incorporated FCC narrowbanding compliance timelines, EU Radio Equipment Directive harmonization progress, and MIIT spectrum allocation expansions.
Forecasts assume regulatory continuity in FCC Part 90, EU Radio Equipment Directive 2014/53/EU, and MIIT professional mobile radio regimes; material policy shifts would require re-modeling. Revision becomes warranted when smartphone PoC substitution rates or semiconductor supply volatility cross thresholds that alter hardware refresh cycle assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Enterprise Communication Infrastructure Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Pcaas Market
Communication Services
Meeting Solutions Market
Communication Services
North America Postal Services Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Cloud Communication Platform Market
Communication Services
Global Passenger Information System Market
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Rich Communications Suite Services and Subscribers Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Global Critical Communication Market
Communication Services
Global Communications Interface Market
Communication Services
Global Audio Communication Monitoring Market