
 Cloud Communication Platform Market | 2026-2036
Cloud Communication Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Communication Platform Market Analysis
Buyer concentration among large enterprises is hardening as Fortune 500 firms consolidate vendor relationships onto single-platform stacks. Twilio anchors the developer-centric API segment with programmable messaging infrastructure that extends into embedded communications. Microsoft Teams dominates enterprise collaboration through deep Office 365 integration, while Cisco Webex competes in regulated industries with hardened security certifications.
A cloud communication platform delivers real-time voice, video, messaging, and contact center functions over internet protocol infrastructure with guaranteed service-level agreements exceeding 99.99% uptime. The architecture replaces on-premises PBX systems with elastic, API-driven resources that scale on demand. Unified communications and contact center solutions command the deepest margin pools as enterprises bundle subscription tiers. Messaging services and communication APIs represent the fastest-expanding segments, driven by embedded conversational interfaces in banking and retail applications.
The FCC enforces net neutrality and emergency service accessibility standards that shape VoIP provider obligations in the United States. GDPR and the EU AI Act impose data localization and algorithmic transparency mandates that filter platform architecture choices across European deployments. Enterprises must monitor evolving cross-border data transfer agreements and sovereign cloud certification programs to sustain compliant infrastructure strategies.
Market Dynamics
API-first architectures are collapsing the traditional boundary between communication infrastructure and application software, forcing vendors to embed programmable voice and messaging directly into enterprise workflows rather than selling standalone connectivity.
Growth Catalysts
- GDPR and EU AI Act compliance:European enterprises are migrating to sovereign cloud deployments to satisfy data localization mandates, creating demand for region-hardened platforms with algorithmic transparency documentation.
- Healthcare digitization:Hospital systems are replacing legacy pagers and on-call systems with cloud-based patient communication platforms that integrate electronic health records with real-time alerting.
- Embedded finance:Banking applications are weaving conversational interfaces into mobile apps, requiring low-latency messaging APIs that authenticate transactions through biometric-linked communication threads.
Market Restraints
- Submarine cable concentration:Transatlantic and transpacific fiber routes pass through chokepoints vulnerable to geopolitical disruption or physical damage, exposing latency-sensitive voice services to availability risk.
- Carrier API dependency:Tier-1 mobile network operators in Germany, Japan, and the United States control termination pricing for SMS and voice, limiting margin compression for platform providers.
- E911 regulatory fragmentation:FCC requirements for precise location reporting in emergency calls conflict with privacy frameworks in other jurisdictions, complicating multi-tenant platform architecture.
Strategic Opportunities
- Edge computing convergence:5G network slicing and edge node deployment are enabling sub-50-millisecond video processing for remote surgery and industrial AR, opening premium service tiers.
- India's Digital Public Infrastructure:The country's unified payments interface and health stack are creating standardized APIs that communication platforms can leverage for verified citizen messaging.
- Carbon accounting integration:CSRD disclosure requirements are pushing enterprises to select communication vendors with Scope 3 emissions tracking embedded in service dashboards.
Industry Challenges
- Real-time engineering talent scarcity:WebRTC and media server optimization require specialized skills that command premium compensation, constraining platform development velocity.
- Legacy PBX integration complexity:Enterprises with hybrid estates must maintain Session Border Controllers and SIP trunking during multi-year migration windows, inflating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Communication Platform Market |
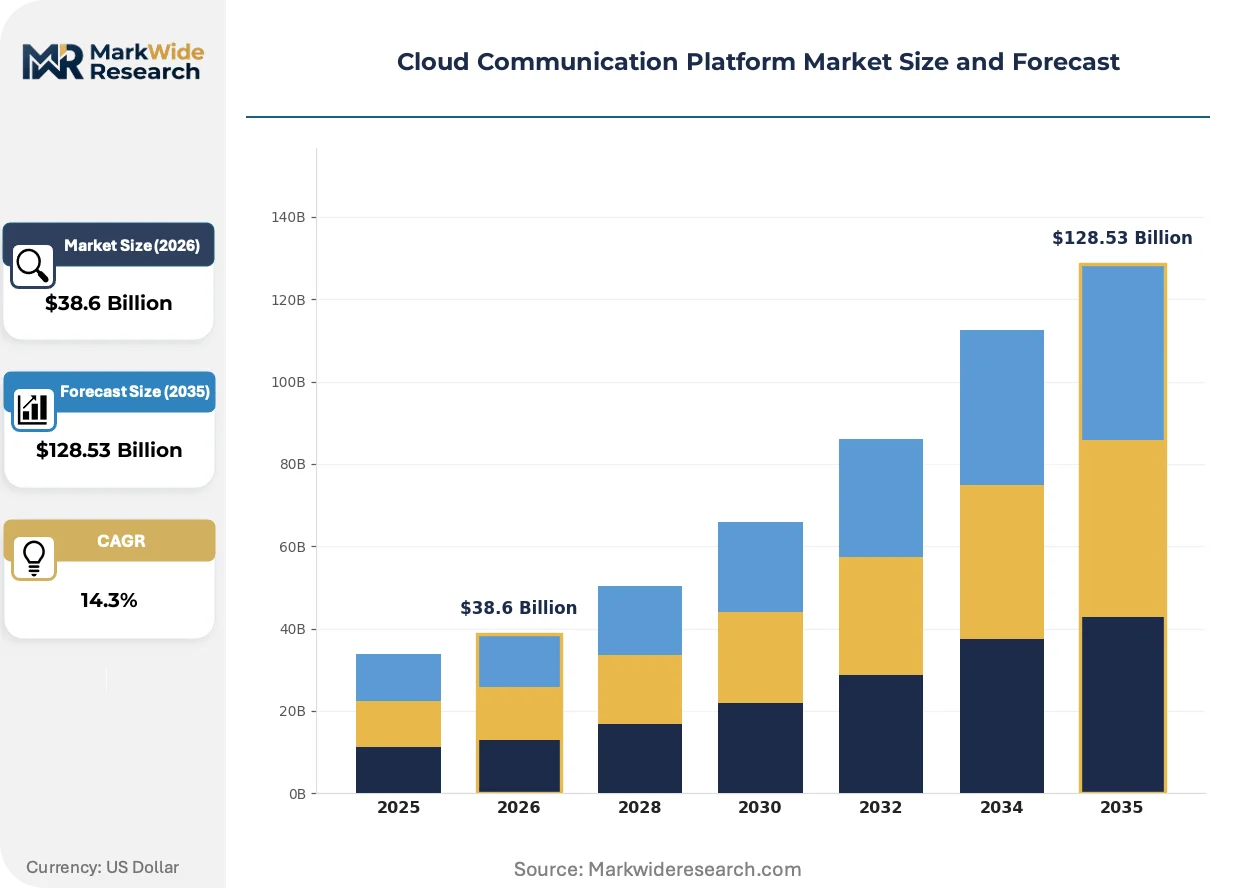
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $128.53 Billion |
| CAGR (2026 – 2036) | 14.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: Unified Communications, VoIP Services, Video Conferencing, Messaging Services End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Solution Type: Contact Center Solutions, Collaboration Tools, Communication APIs, Analytics Solutions |
| Companies Covered | RingCentral, 8x8, Twilio, Intermedia, CloudTalk, Zoom, Cisco Webex, Zendesk Talk, Microsoft Teams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Communication Platform Market Emerging Trajectories
Conversational AI and programmable infrastructure are dissolving the distinction between communication platforms and business process software, enabling context-aware interactions that trigger automated workflows.
CPaaS architectures are unifying voice, video, and messaging into single SDKs that developers embed directly into customer-facing applications. Retail banks in Singapore and the United Kingdom are deploying these stacks to authenticate high-value transactions through biometric voiceprints. The consolidation is compressing vendor consolidation timelines as enterprises abandon point solutions for unified stacks.
The EU AI Act's risk classification system is forcing platform providers to document training data provenance and algorithmic decision logic for customer-facing chatbots. Vendors serving European financial services must now maintain model cards and human oversight mechanisms. German automotive manufacturers are delaying conversational assistant rollouts to complete conformity assessments.
Enterprise buyers are consolidating vendor relationships onto single-platform stacks with guaranteed interoperability. Fortune 500 procurement teams are negotiating enterprise-wide licenses that bundle contact center, collaboration, and embedded messaging. This concentration is most visible in the United States, where healthcare systems are replacing fragmented departmental tools with unified communication estates.
Cloud Communication Platform Market Segmentation
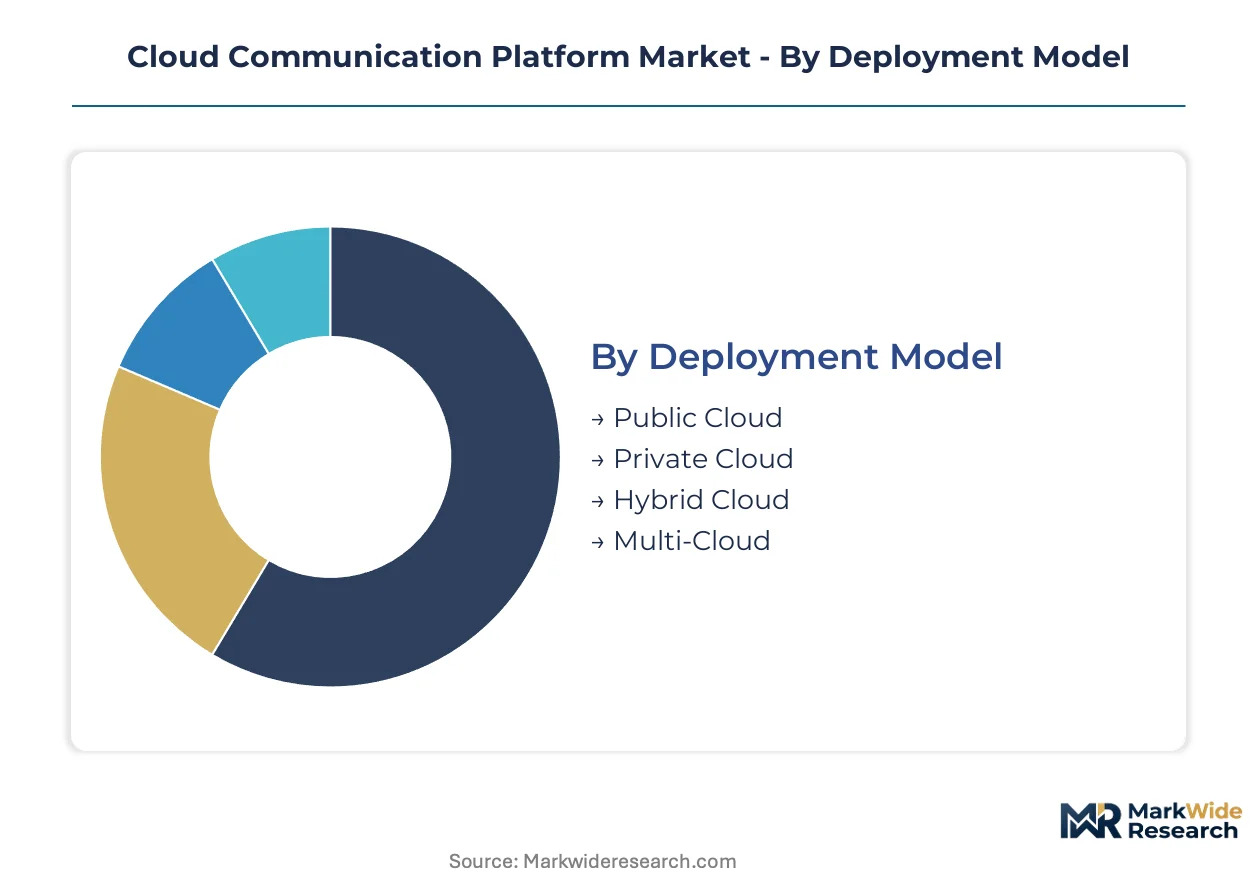
Cloud communication platforms fragment across four critical dimensions that determine procurement priorities. Deployment models dictate compliance posture and capital structure. Service and solution types align with specific workflow integration requirements. End-user scale determines pricing elasticity and feature depth expectations.
Deployment Model:
Enterprises select deployment architecture based on data sovereignty obligations and legacy system interdependencies.
- Public Cloud:Shared infrastructure delivers elastic capacity with consumption-based pricing. Retail banks in Singapore and fintech startups favor this model for rapid application deployment without hardware procurement cycles.
- Private Cloud:Dedicated single-tenant environments satisfy HIPAA and GDPR requirements for patient data isolation. German automotive manufacturers and Swiss pharmaceutical firms mandate private deployments for R&D collaboration platforms.
- Hybrid Cloud:Split workloads between on-premises Session Border Controllers and cloud media servers. Healthcare systems in the United States deploy hybrid models to preserve legacy paging integration while modernizing patient portals.
- Multi-Cloud:Active-active redundancy across AWS, Azure, and Google Cloud regions eliminates single-provider dependency. Financial services firms in London and New York architect multi-cloud voice infrastructure for regulatory resilience.
Public cloud leads on scale; multi-cloud leads on momentum.
Service Type:
Service selection tracks the shift from standalone connectivity to embedded workflow integration.
- Unified Communications:Integrated voice, video, and messaging with presence awareness and calendar synchronization. Large enterprises in the United States consolidate Microsoft Teams and Cisco Webex licenses to reduce vendor fragmentation.
- VoIP Services:Session Initiation Protocol trunking replaces PSTN termination with packet-switched voice. Call centers in India and the Philippines deploy VoIP infrastructure to compress international termination costs.
- Video Conferencing:WebRTC-based HD video with screen sharing and recording for compliance documentation. Remote surgery networks in South Korea and telehealth providers in Australia demand sub-50-millisecond latency guarantees.
- Messaging Services:Programmable SMS, WhatsApp Business API, and RCS for transactional notifications. Embedded finance applications in Brazil and Nigeria authenticate payments through biometric-linked messaging threads.
Messaging services are gaining share fastest; unified communications retains the deepest installed base.
End User:
Buyer scale determines contract structure, with procurement sophistication increasing at the enterprise tier.
- SMEs:Sub-500-employee organizations purchasing standardized subscription tiers through self-service portals. Professional services firms in Canada and Australia adopt Zoom Phone and RingCentral without dedicated IT staff.
- Large Enterprises:Fortune 500 procurement teams negotiating enterprise-wide licenses with custom SLAs and dedicated support pods. Manufacturing conglomerates in Japan bundle contact center, collaboration, and IoT alerting into single-vendor estates.
- Government Agencies:FedRAMP and IL5 certification requirements filter vendor eligibility. Federal civilian agencies in the United States and ministries in the United Kingdom mandate sovereign cloud deployments with domestic data residency.
- Educational Institutions:K-12 districts and universities prioritizing accessibility compliance and parental communication portals. University systems in California and Texas replace legacy PBX with cloud platforms supporting hybrid classroom models.
Large enterprises lead on scale; government agencies are climbing the fastest.
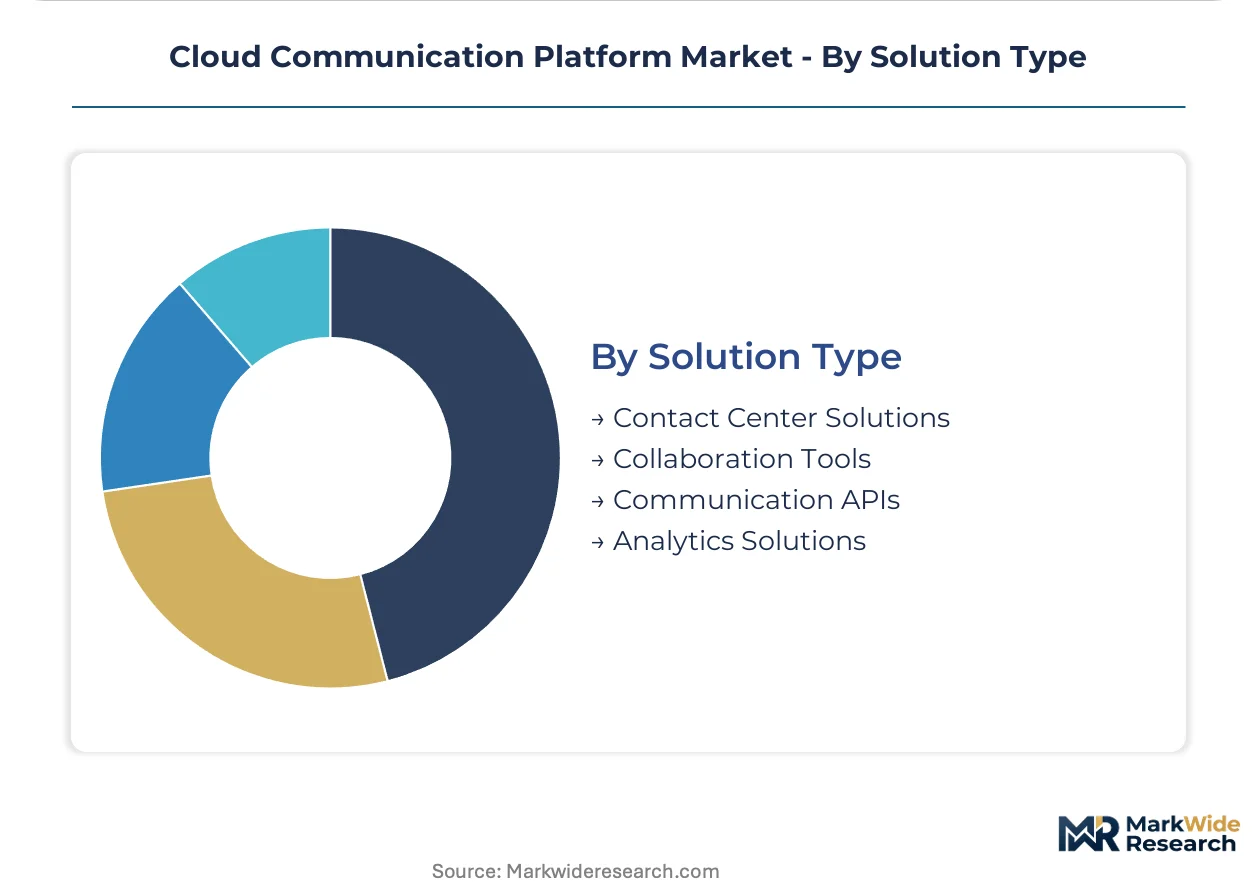
Solution Type:
Solution architecture determines margin structure, with API layers commanding premium pricing over packaged applications.
- Contact Center Solutions:Omnichannel routing, workforce management, and quality monitoring for customer service operations. Insurance carriers in Germany and airlines in the United Arab Emirates deploy AI-powered sentiment analysis for real-time agent coaching.
- Collaboration Tools:Persistent chat, document co-editing, and project management integration. Technology firms in Seattle and Stockholm standardize on Slack and Microsoft Teams for distributed engineering teams.
- Communication APIs:Programmable voice, video, and messaging SDKs embedded directly into customer-facing applications. Retail banks in the United Kingdom and Singapore authenticate high-value transactions through biometric voiceprints.
- Analytics Solutions:Conversation intelligence, sentiment extraction, and predictive routing optimization. Healthcare providers in the Netherlands analyze patient interaction patterns to reduce no-show rates and improve outcomes.
Contact center solutions lead on scale; communication APIs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's sovereign cloud migration outpaces France's regulatory compliance spending, while India's Digital Public Infrastructure creates API standardization opportunities unmatched elsewhere in Asia-Pacific.
United States
Fortune 500 consolidation drives demand for unified communication estates with FedRAMP certification. FCC net neutrality enforcement shapes VoIP provider obligations for emergency service accessibility. Healthcare systems in California and Texas replace fragmented departmental tools with cloud platforms supporting hybrid clinical workflows.
Germany
Automotive manufacturers and pharmaceutical firms mandate private cloud deployments for R&D collaboration platforms. GDPR and EU AI Act compliance requirements push enterprises toward algorithmic transparency documentation. Industrial clusters in Bavaria and Baden-Württemberg prioritize data residency with localized infrastructure investments.
United Kingdom
Retail banks deploy biometric voiceprint authentication for high-value transaction verification. Financial regulators mandate operational resilience standards for critical communication infrastructure. London-based fintechs leverage CPaaS architectures to embed conversational interfaces into mobile banking applications.
India
Unified Payments Interface integration creates standardized APIs for verified citizen messaging at scale. TRAI regulations govern termination pricing for SMS and voice services. Bengaluru and Hyderabad technology corridors attract embedded finance deployments requiring low-latency messaging infrastructure.
Singapore
Wealth management firms deploy sub-50-millisecond video infrastructure for remote client advisory services. Monetary Authority of Singapore guidelines shape cloud outsourcing risk management for financial institutions. Marina Bay financial district concentrates demand for multi-cloud redundancy across AWS, Azure, and Google Cloud regions.
Cloud Communication Platform Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: developer-centric API platforms, enterprise collaboration suites with deep productivity integration, and security-hardened solutions for regulated industries. Competitive moves concentrate on portfolio diversification through embedded AI capabilities and geographic expansion via sovereign cloud certifications.
Within the developer-centric tier, Twilio exemplifies programmable infrastructure specialization, while Microsoft Teams occupies a position as the productivity-integrated collaboration anchor. Cisco Webex represents the security-certification archetype for regulated verticals. These three entities collectively illustrate the strategic segmentation driving vendor consolidation timelines as enterprises abandon point solutions for unified stacks.
| Leading Market Players |
|---|
| RingCentral |
| 8x8 |
| Twilio |
| Intermedia |
| CloudTalk |
| Zoom |
| Cisco Webex |
| Zendesk Talk |
| Microsoft Teams |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists dominate the mid-tier contact center segment, compressing pricing discipline through portfolio synergies while redirecting supply chain investment toward API infrastructure consolidation rather than hardware procurement.
Pricing Analysis
Capacity additions in India and Southeast Asia are reshaping price floors for VoIP termination and messaging APIs. The market operates on subscription-tiered SaaS models with consumption-based overages. Price differentiation hinges on SLA guarantees and FedRAMP certification tiers. Pricing pressure stems from carrier API dependency in Germany, Japan, and the United States. SMEs exhibit highest price sensitivity; Fortune 500 buyers prioritize interoperability over unit cost.
Supply Chain Analysis
Refurbishment flows for on-premises PBX equipment extend hardware depreciation cycles as enterprises migrate to cloud-native stacks. Supply concentrates in the United States, Ireland, and Singapore for hyperscale data center infrastructure. Component dependencies include submarine fiber cables, Session Border Controllers, and WebRTC media servers. Single-source vulnerability runs through transatlantic cable chokepoints. Distribution runs through direct enterprise sales with channel partners serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud communication platforms function as stable compounders, with embedded finance and healthcare digitization delivering recurring revenue expansion regardless of macroeconomic volatility.
For Market Incumbents: Cement platform stickiness through deep EHR and ERP integration that raises switching costs. Prioritize sovereign cloud certifications for EU AI Act compliance. Defend against API-first challengers by acquiring conversational AI specialists. Expand edge computing partnerships for sub-50-millisecond latency guarantees.
For New Entrants and Emerging Players: Begin with India's Digital Public Infrastructure stack, where UPI integration creates standardized on-ramps for verified messaging. Target mid-market healthcare systems in the United States replacing fragmented departmental tools. Pursue white-label embedded finance deployments for neobanks in Brazil and Nigeria.
For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid cloud migration specialists with legacy PBX integration expertise. Five-to-ten-year viability favors vendors with multi-cloud redundancy architecture and CSRD-aligned carbon accounting dashboards. Monitor TRAI termination pricing rulings and FCC net neutrality enforcement as margin inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act compliance unlocks German automotive and pharmaceutical procurement pipelines. |
| API Platform Integration | Unified SDKs for voice, video, and messaging accelerate retail banking deployment timelines. |
| Edge Node Deployment | 5G network slicing enables remote surgery and industrial AR premium service tiers. |
| Conversational AI Acquisition | Algorithmic transparency documentation satisfies GDPR risk classification requirements. |
| Carbon Accounting Integration | Scope 3 emissions tracking aligns with CSRD disclosure mandates for European enterprises. |
Methodological Framework
Direct dialogue with cloud platform architects, enterprise IT procurement officers, contact center operations directors, and regulatory compliance leads grounded the qualitative foundation. Secondary validation drew from FCC enforcement actions, EDPB guidance documents, TRAI tariff orders, and hyperscaler infrastructure expansion disclosures. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Market size outputs trace deployment model adoption curves, service type migration patterns, and end-user scale elasticity across the projection horizon. Segmentation dimensions modeled include public-private-hybrid-multi-cloud architecture, unified communications versus API-centric solutions, and SME-large enterprise-government-educational institution buyer tiers. CAGRs derived from historical elasticity analysis applied to healthcare digitization and embedded finance penetration trajectories.
Several conditions sit outside the modeled scope, including submarine cable geopolitical disruption, carrier termination pricing renegotiations, and E911 regulatory harmonization failures. Forecasts reflect assumptions about 5G network slicing commercialization and sovereign cloud certification timeline adherence. Practitioners should monitor EU AI Act enforcement patterns and India's Digital Public Infrastructure API standardization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
Video Managed Services Market
Communication Services
Consumer Communication Services Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Web Conferencing Market
Communication Services
Voip Services Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Pcaas Market
Communication Services
Global Critical Communication Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
India Communication Platform As a Service (Cpaas) Market
Communication Services
Meeting Solutions Market
Communication Services
Video Conferencing Market
Communication Services
Walkie Talkie Market
Communication Services
Postal Services Market
Communication Services
In Flight Entertainment and Communication Market