
 In Flight Entertainment and Communication Market | 2026-2036
In Flight Entertainment and Communication Market Size, Share, and Industry Trends Forecast 2026-2036
In Flight Entertainment and Communication Market Foresight
Lightweight composite enclosures and fiber-optic backbone cabling are rebalancing hardware weight-to-performance economics in cabin systems. Panasonic Avionics Corporation leverages its vertical integration across content licensing and satellite antenna manufacturing to sustain margin control on wide-body programs. Thales Group anchors European supply chains through manufacturing scale in France and technology leadership in cybersecurity-hardened avionics interfaces. Collins Aerospace competes through backward integration into seat-back display production and in-house semiconductor sourcing for connectivity modules.
In Flight Entertainment and Communication encompasses integrated hardware-software systems that deliver audio-visual content, internet connectivity, and passenger services aboard aircraft through Ku-band, Ka-band, or L-band satellite links, air-to-ground cellular towers, and onboard local area networks with latency thresholds under 300 milliseconds for acceptable streaming quality. The primary commercial purpose centers on passenger satisfaction metrics tied to airline brand loyalty and ancillary revenue from premium Wi-Fi tiers. IFE Systems and In-Flight Wi-Fi together command the largest installed base, though 5G Infrastructure represents the fastest-growing technology dimension as terrestrial network operators partner with aviation hardware vendors. Streaming Services concentrate margin pools through content licensing exclusivity, while Connectivity Hardware remains capital-intensive with long replacement cycles tied to airframe retrofit schedules.
The FAA mandates cybersecurity certification under evolving Special Conditions for connected cabin systems, while the EU Aviation Safety Agency enforces CE marking and MDR-aligned electromagnetic compatibility standards for European-registered aircraft. The International Telecommunication Union coordinates spectrum allocation for satellite communication links, directly shaping which frequency bands manufacturers prioritize in next-generation antenna design. Stakeholders must monitor spectrum reallocation proceedings and emerging national data sovereignty rules that could fragment content delivery architectures across jurisdictions.
Market Dynamics
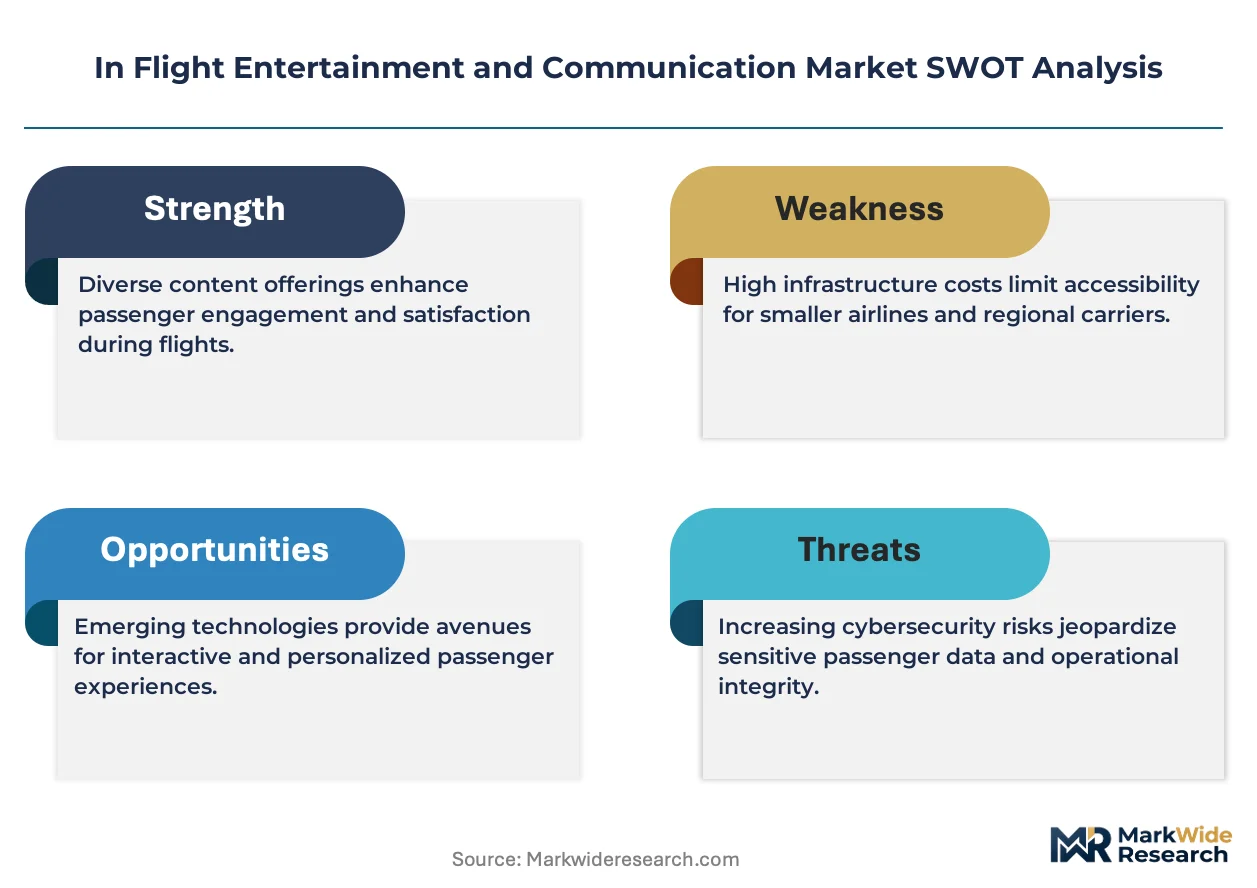
Satellite bandwidth economics and FAA cybersecurity mandates are compressing hardware replacement cycles while forcing airlines to consolidate vendor relationships around vertically integrated suppliers capable of end-to-end certification.
Growth Catalysts
- Ka-band satellite capacity expansion:High-throughput satellite constellations are slashing per-megabit delivery costs for oceanic routes. Airlines now provision streaming-grade bandwidth on transatlantic narrow-body services previously limited to basic connectivity.
- FAA Special Conditions for connected cabin systems:Mandatory cybersecurity certification timelines are accelerating fleet-wide hardware refreshes. Carriers cannot defer upgrades without risking operational approval for new airframe deliveries.
- Premium cabin differentiation:Gulf carriers and Asian full-service airlines are installing immersive seat-back systems with 4K displays and Bluetooth audio pairing. This hardware arms race pulls component demand from economy-only retrofit programs.
Market Restraints
- Gallium nitride semiconductor supply concentration:RF power amplifier substrates for phased-array antennas depend on a limited foundry base in Taiwan and the United States. Geopolitical friction threatens antenna production schedules.
- Airframe retrofit downtime costs:Narrow-body connectivity upgrades require 3-5 day groundings per aircraft. Low-cost carriers with high fleet utilization cannot absorb revenue loss without seasonal scheduling windows.
- Copper and rare earth magnet price volatility:Motorized seat mechanisms and antenna positioning systems face input cost swings. Suppliers struggle to pass through material escalations under long-term airline procurement contracts.
Strategic Opportunities
- India domestic fleet expansion:IndiGo and Air India are adding 500+ narrow-bodies through 2030 with factory-installed connectivity. Indigenous content requirements under PLI schemes favor local assembly partnerships.
- 5G air-to-ground convergence:Terrestrial network operators are integrating aviation bands with ground infrastructure. Hybrid satellite-cellular architectures reduce satellite bandwidth consumption on continental routes.
- EU CSRD-aligned sustainability reporting:Airlines must disclose passenger-facing digital service carbon intensity. Lightweight fiber-optic cabling and low-power displays earn procurement preference in European tenders.
Industry Challenges
- Embedded software certification bottlenecks:DO-178C compliance for passenger-facing operating systems requires specialized aviation software engineers. Talent scarcity extends development timelines by 6-12 months.
- Multi-vendor integration complexity:Airlines source antennas, modems, servers, and displays from separate suppliers. System-level electromagnetic interference testing consumes scarce lab capacity and delays entry-into-service.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In Flight Entertainment and Communication Market |
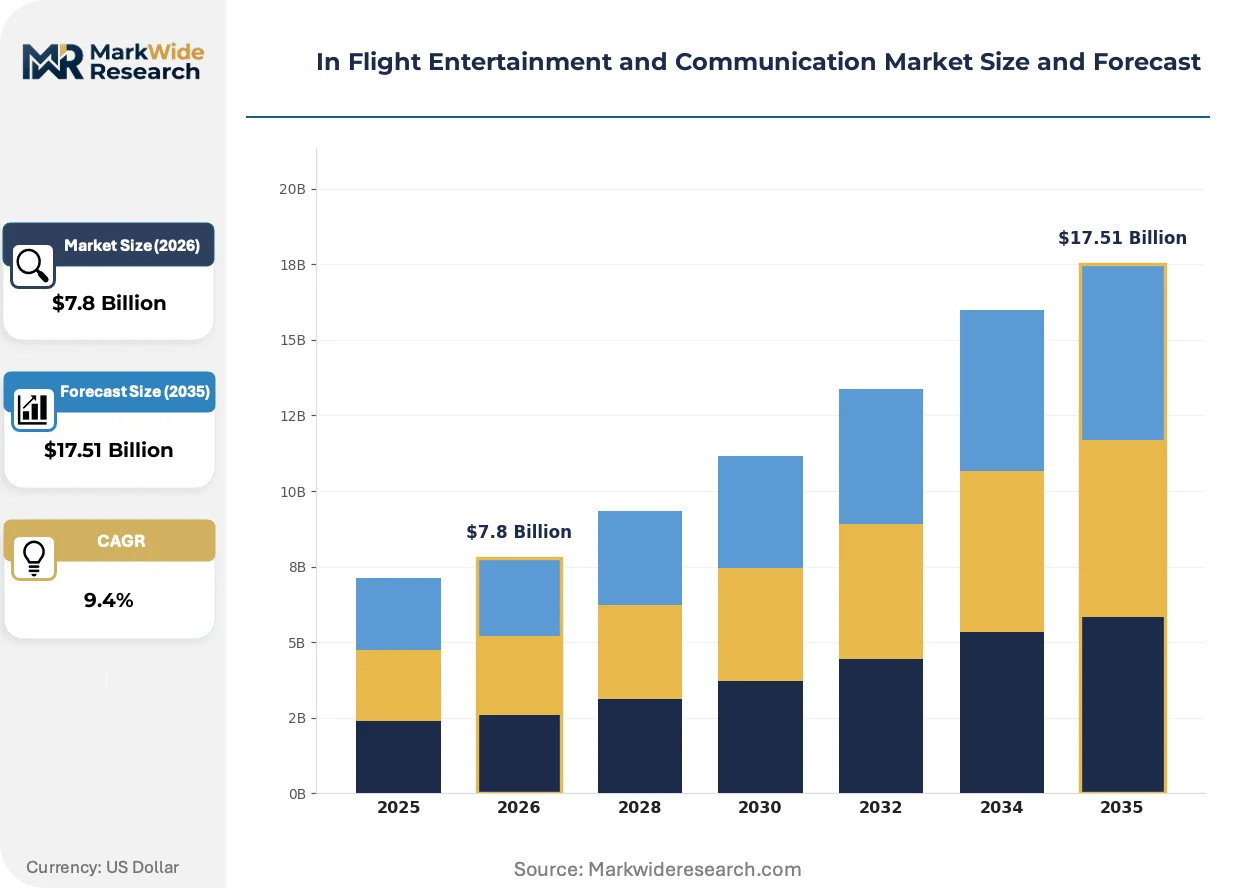
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $17.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IFE Systems, In-Flight Wi-Fi, Streaming Services, Connectivity Hardware Technology: Satellite Communication, Air-to-Ground Technology, 5G Infrastructure, Hybrid Systems End User: Commercial Airlines, Private Jets, Charter Services, Government Flights Service Type: Installation Services, Maintenance Services, Content Management, Support Services |
| Companies Covered | Panasonic Avionics Corporation, Thales Group, Collins Aerospace, Anuvu, Astronics Corporation, Viasat Inc., Gogo Inc., Burrana Pty Ltd, Safran, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In Flight Entertainment and Communication Market Shifts & Advancements
Artificial intelligence inference at the network edge is compressing content personalization latency while enabling real-time bandwidth optimization algorithms that adapt to satellite handoff zones.
Edge computing nodes deployed within cabin server racks are automating content caching decisions based on passenger demographic profiles and flight route libraries. Lufthansa and Singapore Airlines are piloting these systems on long-haul fleets. The technology is automating manual content provisioning workflows that previously required ground-based upload scheduling.
The FAA's evolving Special Conditions for connected aircraft systems now mandate hardware security modules in all passenger-facing network equipment. Manufacturers must redesign antenna control units and wireless access points with tamper-resistant silicon. Wide-body programs with 2027 delivery slots are absorbing the bulk of engineering validation costs.
Airline procurement departments are consolidating connectivity contracts under single-source agreements spanning hardware, installation, and content licensing. This bundling displaces the previous multi-vendor model where carriers negotiated satellite links, antenna hardware, and entertainment content separately. European and Middle Eastern network operators are most aggressive in pursuing these consolidated awards.
In Flight Entertainment and Communication Market Segmentation
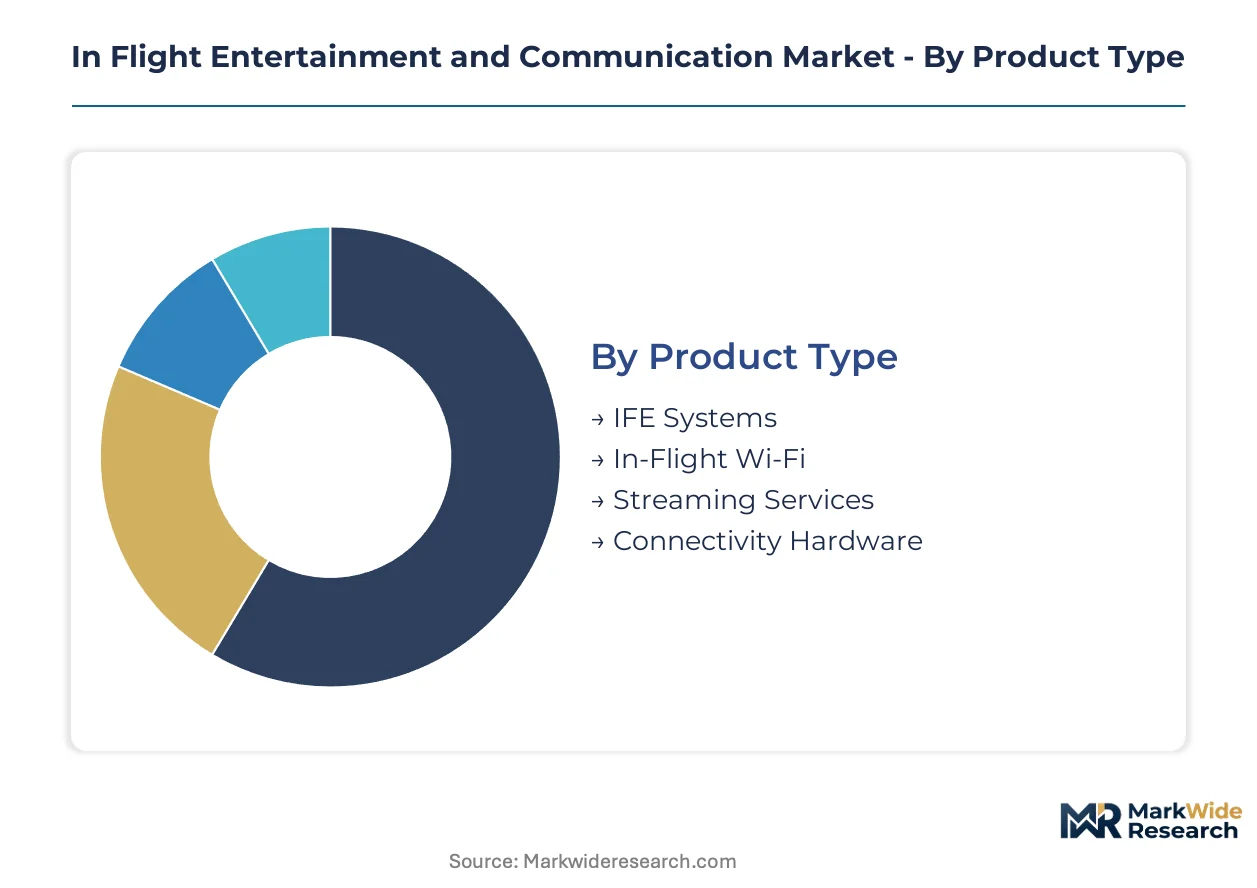
Segmentation in this market maps directly to procurement decision hierarchies at airlines, where technology choices cascade through hardware specifications, service bundling, and regulatory compliance requirements. Each category isolates distinct buyer priorities that reshape competitive positioning across the supply chain.
Product Type:
Airlines differentiate procurement budgets by whether systems generate ancillary revenue directly or function as cost-center infrastructure.
- IFE Systems:Integrated seat-back and overhead entertainment hardware with embedded displays, audio distribution, and passenger control units. Demand concentrates in Gulf carrier and Asian full-service airline premium cabin retrofits, driven by 4K display upgrade cycles and Bluetooth audio mandates.
- In-Flight Wi-Fi:Passenger internet connectivity delivered through satellite or air-to-ground links with tiered bandwidth provisioning. United States narrow-body fleet retrofits dominate volumes, propelled by passenger satisfaction metrics tied to loyalty program enrollment.
- Streaming Services:Licensed content libraries and platform software for passenger-facing entertainment portals.
- Connectivity Hardware:Antennas, modems, servers, and network infrastructure forming the physical connectivity layer.
IFE Systems leads volumes today; Streaming Services is gaining share fastest.
Technology:
Frequency band selection and network architecture determine coverage economics across route networks.
- Satellite Communication:Ku-band, Ka-band, and L-band links delivering oceanic and remote airspace coverage. Ka-band high-throughput constellations are slashing per-megabit costs for transatlantic narrow-body services previously limited to basic connectivity.
- Air-to-Ground Technology:Cellular tower-based connectivity over continental landmasses with lower latency than satellite alternatives. Continental United States and European core routes absorb the bulk of deployment, constrained by spectrum licensing fragmentation across national borders.
- 5G Infrastructure:Next-generation terrestrial networks integrating aviation-specific spectrum bands.
- Hybrid Systems:Architectures combining satellite and air-to-ground links for seamless handoff.
Satellite Communication anchors installed base; 5G Infrastructure climbs the fastest.
End User:
Operational tempo and regulatory exposure segment buyers by upgrade cycle urgency and certification stringency.
- Commercial Airlines:Scheduled passenger carriers operating fixed-route networks with high fleet utilization. Major United States carriers are retrofitting narrow-body fleets with satellite-based streaming platforms, compelled by FAA cybersecurity directives for connected cabin systems.
- Private Jets:Corporate and individually owned aircraft with customized cabin configurations. North American and European owner-operators prioritize lightweight hardware and discrete antenna profiles over content library depth.
- Charter Services:On-demand operators with variable route structures and rapid turnaround requirements.
- Government Flights:State-operated aircraft with hardened security and sovereign data requirements.
Commercial Airlines dominates procurement volumes; Private Jets expands most quickly.
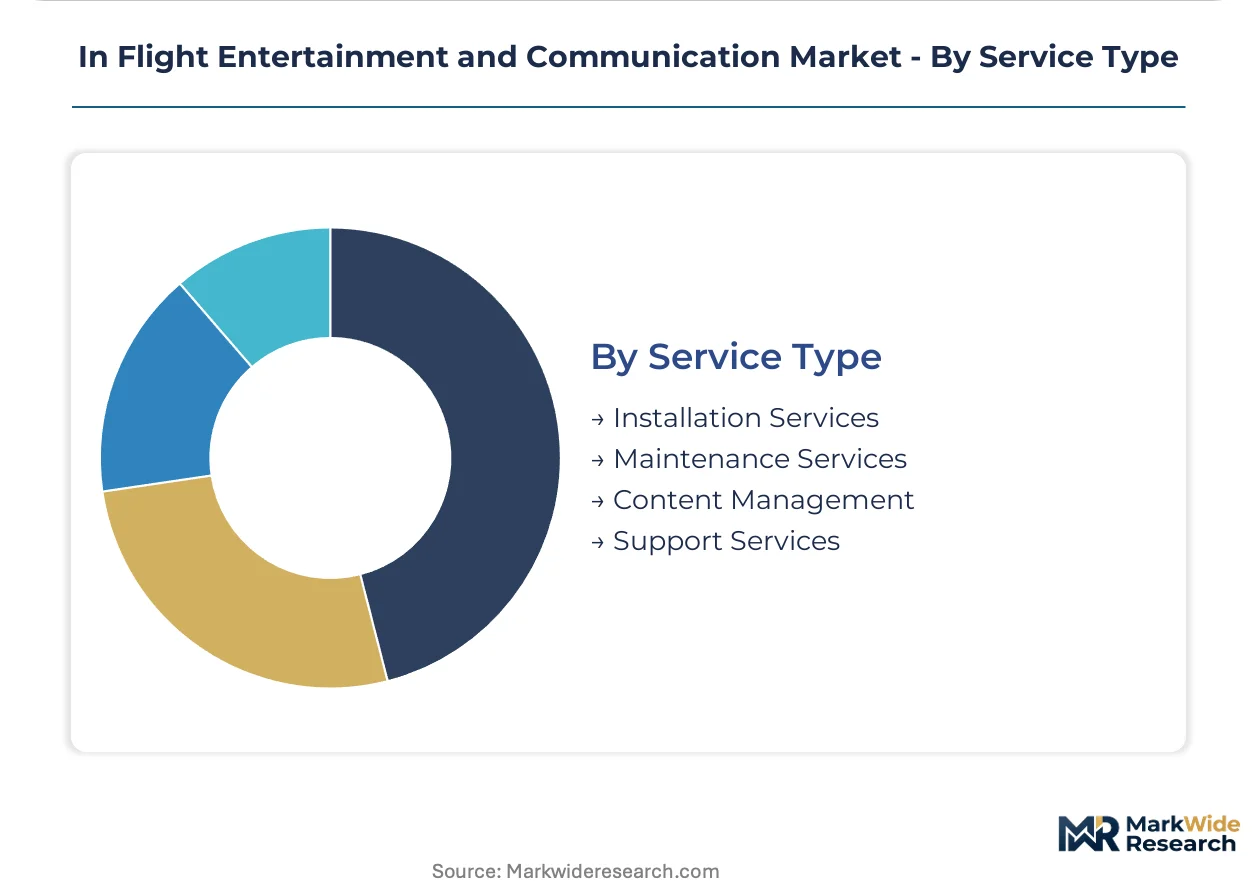
Service Type:
Contract bundling preferences separate airlines seeking operational simplicity from those optimizing lifetime cost of ownership.
- Installation Services:Airframe modification, hardware mounting, and system integration during scheduled maintenance windows. Narrow-body retrofit programs in the United States face 3-5 day groundings per aircraft, compressing installation demand into seasonal scheduling windows.
- Maintenance Services:Preventive and corrective support for hardware availability and performance guarantees.
- Content Management:Licensing negotiation, library curation, and passenger-facing software updates.
- Support Services:Technical helpdesk, spare parts logistics, and field engineering dispatch.
Installation Services commands peak project revenue; Content Management shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seattle-Tacoma aerospace corridor anchors global demand for narrow-body connectivity retrofits, with major carriers accelerating fleet-wide hardware refreshes. FAA cybersecurity mandates are compressing replacement cycles across North American installations. Satellite bandwidth economics now enable streaming-grade service on transatlantic single-aisle routes previously limited to basic connectivity.
United States
United Airlines and Delta Air Lines are retrofitting 1,500+ narrow-bodies with Ka-band satellite platforms by 2027. FAA Special Conditions for connected cabin systems mandate hardware security modules in all passenger-facing network equipment. Seattle and Dallas-Fort Worth host the dominant antenna integration facilities serving domestic carrier retrofit programs.
China
China Eastern and Air China are expanding connectivity across 800+ aircraft as MIIT accelerates aviation spectrum allocation for L-band and Ku-band services. Civil Aviation Administration of China certification timelines for imported satellite terminals are extending supplier qualification periods by 4-6 months. Shanghai Pudong and Beijing Daxing concentrate MRO capacity for wide-body entertainment system upgrades.
Germany
Lufthansa Group is piloting edge-computing content caching on long-haul A350 and 787 fleets to reduce ground-based upload dependencies. EU CSRD-aligned sustainability reporting requirements are elevating procurement weighting for low-power displays and fiber-optic cabling. Hamburg anchors European cabin systems engineering clusters serving Middle East carrier premium programs.
India
IndiGo and Air India factory-install mandates are driving 500+ narrow-body connectivity deliveries through 2030. PLI scheme indigenous content requirements favor local assembly partnerships for antenna positioning systems and server racks. Bangalore and Hyderabad host emerging electronics manufacturing clusters qualifying for aviation hardware production.
United Arab Emirates
Emirates and Etihad are deploying immersive 4K seat-back systems across A380 and 777 premium cabins with Bluetooth audio pairing as standard. GCAA harmonization with FAA cybersecurity directives is accelerating hardware refresh timelines for Dubai-registered wide-bodies. Dubai International Airport's MRO zone concentrates specialized installation capacity for superjumbo entertainment retrofits.
In Flight Entertainment and Communication Market Competitive Landscape
Global majors compete with regional champions across certification bandwidth and vertical integration depth. The supplier base organizes into three tiers: full-stack integrators controlling content licensing through antenna manufacturing; hardware specialists focused on modular connectivity components; and regional service providers capturing installation and maintenance contracts. Consolidation pressures favor end-to-end suppliers capable of unified cybersecurity certification. Competitive positioning hinges on backward integration into semiconductor sourcing and captive content libraries.
Among vertically integrated systems houses, Panasonic Avionics Corporation and Thales Group exemplify the full-stack archetype spanning satellite antenna production through passenger-facing software. Collins Aerospace occupies a position emphasizing seat-back display manufacturing and in-house connectivity module sourcing. These three anchors demonstrate how certification scale and manufacturing breadth determine eligibility for consolidated airline procurement contracts bundling hardware, installation, and content licensing.
| Leading Market Players |
|---|
| Panasonic Avionics Corporation |
| Thales Group |
| Collins Aerospace |
| Anuvu |
| Astronics Corporation |
| Viasat Inc. |
| Gogo Inc. |
| Burrana Pty Ltd |
| Safran |
| Others |
Supply & Pricing Matrix
EU CSRD-aligned sustainability reporting gates qualified supply and premium-tier pricing access by mandating carbon intensity disclosures for passenger-facing digital services. Airlines seeking procurement preference must source lightweight fiber-optic cabling and low-power displays from certified suppliers, compressing vendor pools and elevating compliant hardware pricing.
Pricing Analysis
Input-cost pass-through dynamics shape contract negotiations as gallium nitride semiconductor substrates and rare earth magnet prices fluctuate. Three-tier pricing structure across premium, standard, and economy levels separates immersive 4K seat-back systems from basic connectivity modules and bare-hardware antenna installations. Pricing pressure stems from airline procurement departments consolidating contracts under single-source agreements that bundle hardware, installation, and content licensing. Low-cost carriers exhibit highest price sensitivity due to narrow-body retrofit downtime costs, while Gulf carriers prioritize performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and United States foundries for RF power amplifier substrates essential to phased-array antenna production. Component sourcing draws from Japan for precision motors, Germany for fiber-optic backbone systems, and China for display panel assemblies. Tariff exposure threatens antenna production schedules amid geopolitical friction over semiconductor supply concentration. Distribution runs through Seattle-Tacoma and Dallas-Fort Worth integration facilities serving North American carrier retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The In Flight Entertainment and Communication Market functions as a stable compounder where FAA cybersecurity mandates for connected cabin systems drive steady hardware refresh demand regardless of passenger traffic cyclicality.
For Market Incumbents: Anchor market position through backward integration into seat-back display manufacturing and captive semiconductor sourcing for connectivity modules. Consolidate vendor relationships around end-to-end certification capabilities to capture single-source procurement contracts displacing multi-vendor models. Invest in DO-178C software engineering talent pools to compress development timelines threatened by embedded software certification bottlenecks. For New Entrants and Emerging Players: Launch via local assembly partnerships targeting India's PLI scheme indigenous content requirements for 500+ narrow-body factory-install mandates through 2030. Penetrate the private jet segment where North American owner-operators prioritize lightweight hardware over content depth and procurement cycles run shorter than commercial airline tenders. Pursue 5G air-to-ground convergence opportunities as terrestrial network operators seek aviation hardware integration partners. For Investors and Strategic Acquirers: Roll-up economics work for regional installation and maintenance service providers because airline procurement consolidation favors end-to-end suppliers capable of unified cybersecurity certification. Five-to-ten year viability hinges on manufacturers with captive content libraries and antenna production scale. Watch FAA Special Conditions evolution as the inflection indicator for accelerated replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | FAA Special Conditions compliance enables eligibility for consolidated airline procurement contracts. |
| Local Assembly Partnership | India PLI scheme qualification opens access to IndiGo and Air India factory-install mandates. |
| Edge Computing Deployment | Onboard content caching reduces ground-based upload dependencies for Lufthansa and Singapore Airlines pilots. |
| Ka-band Antenna Scale-Up | High-throughput satellite capacity slashes per-megabit delivery costs for transatlantic narrow-body services. |
| 5G Air-to-Ground Integration | Hybrid satellite-cellular architectures reduce bandwidth consumption on continental United States and European routes. |
Research Methodology
Bottom-up commercial airline fleet modeling reconciled against top-down connectivity hardware shipment tracking forms the analytical core of this study. Primary interviews with airline procurement directors, avionics systems engineers, satellite bandwidth procurement managers, and MRO facility operators combined with secondary validation from FAA Special Conditions filings, EASA certification databases, and ITU spectrum allocation proceedings. Customs data for gallium nitride substrates, fiber-optic cabling imports, and seat-back display assemblies anchored supply-side triangulation against airline retrofit announcement tracking.
Historical trendline analysis across satellite bandwidth cost curves, airframe delivery schedules, and regulatory certification timelines informed projection construction. Segmentation dimensions modeled include product type, frequency band technology, end-user operational tempo, and service bundling preferences alongside airline fleet utilization rates and route network coverage requirements. CAGRs derived from fitted trend extrapolation adjusted for regulatory mandate acceleration effects and hardware replacement cycle compression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FAA cybersecurity directive timeline shifts or geopolitical disruption to Taiwan semiconductor foundry operations. Forecasts reflect documented assumptions regarding satellite constellation deployment schedules, airline capital expenditure prioritization, and spectrum reallocation proceedings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
High Performance Message Infrastructure Market
Communication Services
Push-To-Talk Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
Managed Communication Services Market
Communication Services
Asia-Pacific Postal Services Market
Communication Services
Fixed Business Voice Platforms and Services Market
Communication Services
Telecommunications Relay Service (TRS) Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Industrial Communication Market
Communication Services
Voice Commerce Market
Communication Services
Audio Conferencing Services Market
Communication Services
Postal Services Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Mobile Messaging Market
Communication Services
Voip Services Market
Communication Services
Rich Communications Suite Services and Subscribers Market