
 IP Multimedia Subsystem (IMS) Services Market | 2026-2036
IP Multimedia Subsystem (IMS) Services Market Size, Share, and Industry Trends Forecast 2026-2036
IP Multimedia Subsystem (IMS) Services Market Foresight
Core network function licensing is rewriting margin distribution between proprietary hardware vendors and software-native challengers. Ericsson AB leverages its installed base of packet core equipment to sustain recurring support contracts across European tier-one operators. Huawei Technologies Co. Ltd. anchors significant deployment volume through integrated radio-access-to-core bundles in Middle Eastern and African markets. Mavenir Systems Inc. competes aggressively on cloud-native pricing to displace incumbent suppliers in North American greenfield 5G standalone builds.
IP Multimedia Subsystem services constitute a standardized architectural framework for delivering internet protocol-based multimedia communications using Session Initiation Protocol signaling, diameter/HTTP interfaces, and service capability interaction managers to enable real-time voice, video, and messaging across heterogeneous access networks. The architecture primarily enables telecommunications providers to consolidate circuit-switched and packet-switched services onto a unified IP backbone while maintaining regulatory-grade reliability and intercarrier interoperability. Voice over IP services within the service type dimension retain the largest revenue share as carriers sunset legacy PSTN infrastructure, though 5G technology deployments within the technology dimension are generating the fastest incremental capacity requirements as standalone core rollouts accelerate. Cloud-based deployment models are capturing disproportionate growth momentum relative to on-premises alternatives as operators seek opex flexibility and horizontal scaling for traffic spikes.
The Federal Communications Commission in the United States mandates interconnection and accessibility standards that preserve IMS-based voice as a universal service obligation during copper network retirement, while 3GPP specifications enforced by national regulators across Germany, Japan, and South Korea shape product certification requirements for core network equipment. The European Telecommunications Standards Institute framework influences procurement specifications for cross-border interoperability, particularly where roaming agreements depend on common IMS service profiles. Stakeholders must monitor divergence between regional 5G standalone deployment timelines and associated IMS core refresh cycles to align capacity investments with actual traffic migration patterns.
Market Dynamics
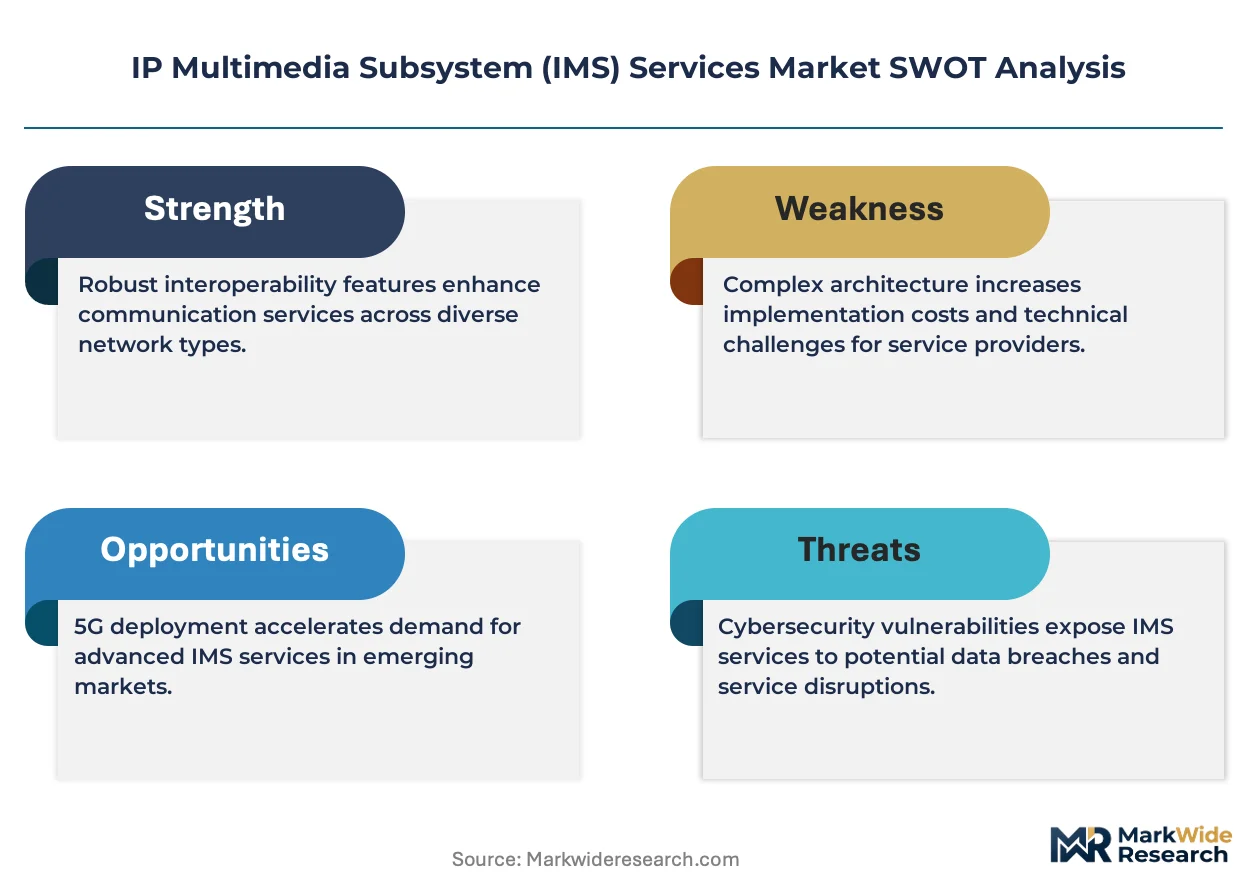
The migration from hardware-centric IMS deployments toward containerized, cloud-native architectures is compressing vendor margins while forcing incumbent suppliers to restructure licensing models around software subscriptions rather than perpetual equipment sales.
Growth Catalysts
- 3GPP Release 17 mandates:Interworking requirements between 5G core and legacy IMS infrastructure in Germany and South Korea are compelling operators to refresh core networks ahead of voice-over-5G service launches.
- FCC universal service obligations:Copper network retirement rules in the United States preserve IMS-based voice as a mandatory interconnection standard, locking in replacement demand.
- Container orchestration maturity:Kubernetes-based deployment patterns enable horizontal scaling for traffic spikes, attracting capital from North American carriers seeking operational flexibility.
Market Restraints
- Specialized engineering talent scarcity:SIP protocol expertise and Diameter interface engineering skills command premium compensation, inflating implementation costs for tier-two operators.
- Radio-access bundling concentration:Integrated RAN-to-core procurement in Middle Eastern and African markets limits standalone IMS vendor access to these geographies.
- Legacy PSTN interworking complexity:SS7 signaling gateway maintenance requirements extend depreciation schedules and delay full IP transition timelines.
Strategic Opportunities
- Greenfield 5G standalone builds:North American carriers without incumbent packet core investments present openings for cloud-native challengers to establish footholds through competitive pricing.
- Cross-border roaming harmonization:ETSI framework alignment across European Union member states creates procurement specifications favoring vendors with multi-country certification.
- Network function virtualization convergence:IMS core consolidation with subscriber data management and policy control functions enables single-vendor accountability models.
Industry Challenges
- Multi-vendor interoperability certification:Testing labs in Japan and South Korea maintain divergent acceptance criteria for diameter/HTTP interfaces, fragmenting product development roadmaps.
- Session border controller integration:Enterprise SIP trunking deployments require customized security policy configurations that extend professional services engagement durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IP Multimedia Subsystem (IMS) Services Market |
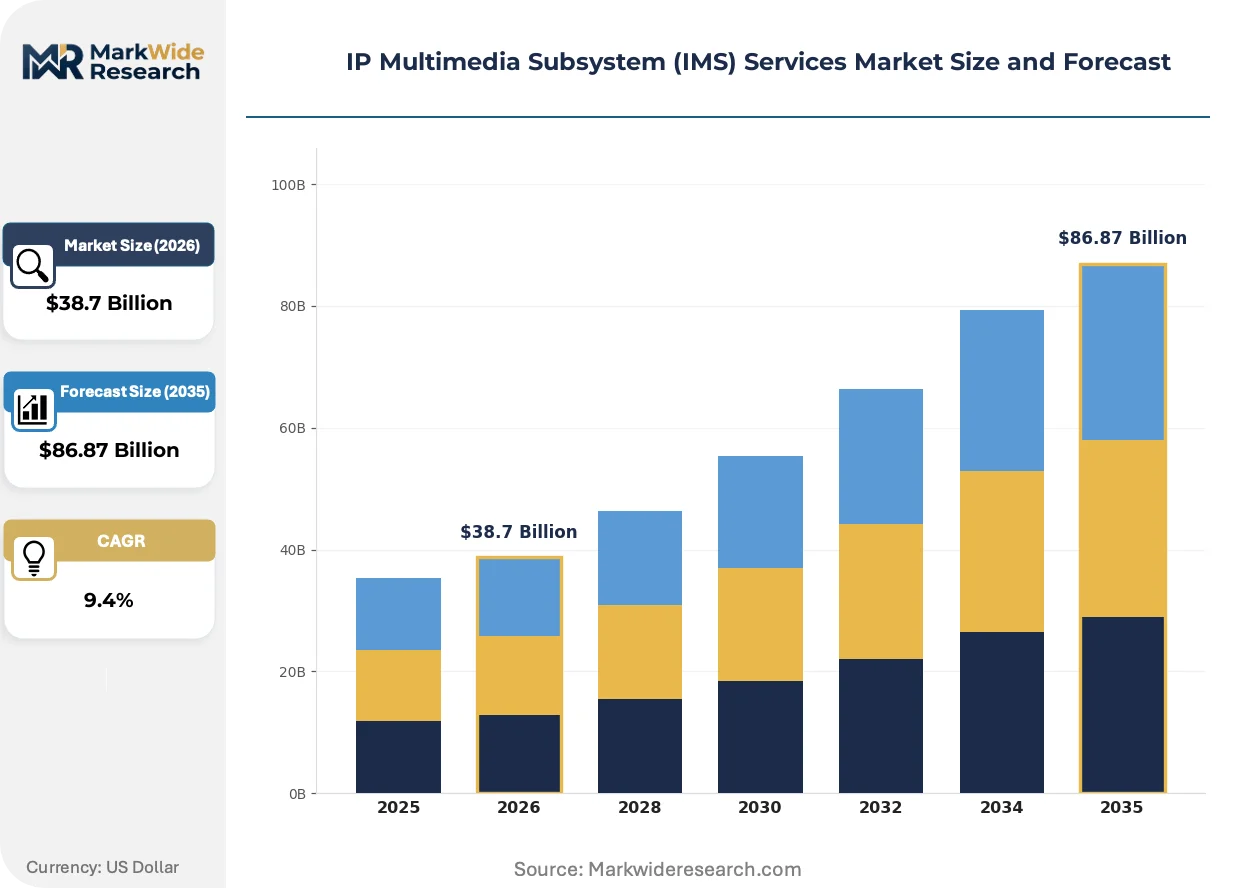
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice over IP, Video Conferencing, Messaging Services, Multimedia Streaming Deployment Model: Cloud-Based, On-Premises, Hybrid Solutions, Managed Services End User: Telecommunications Providers, Enterprises, Government Agencies, Educational Institutions Technology: Session Initiation Protocol, WebRTC, LTE, 5G Technology |
| Companies Covered | Huawei Technologies Co. Ltd., Ericsson AB, Nokia Corporation, Cisco Systems Inc., Samsung Electronics Co. Ltd., ZTE Corporation, Oracle Corporation, IBM Corporation, Mavenir Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IP Multimedia Subsystem (IMS) Services Market Shifts & Advancements
Containerization and microservices decomposition are redrawing competitive boundaries between integrated hardware vendors and modular software suppliers, with deployment velocity and operational expenditure models replacing capital efficiency as the primary procurement evaluation criteria.
Cloud-native IMS core implementations are collapsing the traditional separation between control plane and user plane functions. Tier-one operators in South Korea and Germany are deploying these architectures for voice-over-5G services. The structural consequence is collapsing hardware refresh cycles from five-year equipment replacement schedules toward continuous software delivery pipelines.
REACH chemical substance restrictions and RoHS substance limitations in the European Union are constraining printed circuit board compositions and solder materials used in remaining on-premises IMS equipment. Manufacturers serving European tier-one operators must maintain dual supply chains for compliant and non-compliant component variants. German carriers are responding by accelerating cloud migration timelines to reduce hardware certification exposure.
Enterprise buyers are consolidating vendor relationships around systems integrators capable of delivering managed IMS services rather than purchasing core licenses directly. Channel intermediaries with multi-vendor orchestration expertise are displacing direct OEM relationships in mid-market telecommunications procurement. This consolidation is most visible in North American healthcare and financial verticals where HIPAA and SEC voice recording compliance requirements demand specialized service-level guarantees.
IP Multimedia Subsystem (IMS) Services Market Segmentation
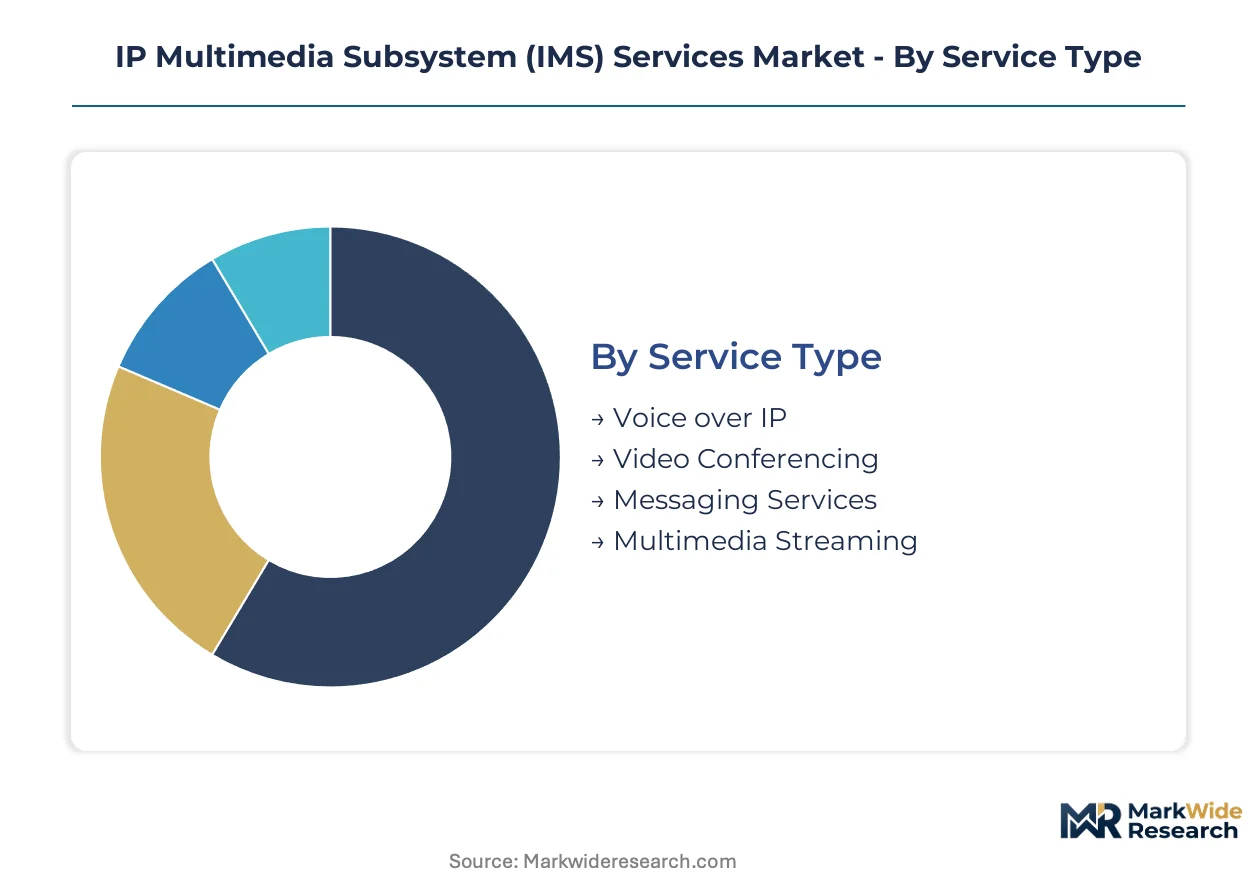
Segmentation in the IP Multimedia Subsystem services market reveals how architectural choices, service delivery modes, and underlying technologies partition investment flows across carrier infrastructure budgets. Each dimension carries distinct procurement patterns, vendor qualification requirements, and operational risk profiles that shape competitive positioning.
Service Type:
The use-case spectrum spans real-time interactive communications through passive content consumption, with each service imposing different latency, synchronization, and quality-of-service requirements on core network functions.
- Voice over IP:Session Initiation Protocol-based call control with diameter/HTTP interfaces for subscriber authentication. Demand concentrates among German and South Korean carriers sunsetting PSTN infrastructure under 3GPP Release 17 mandates for voice-over-5G interworking.
- Video Conferencing:Real-time media negotiation with adaptive bitrate management for heterogeneous endpoint capabilities. Enterprise procurement in North American healthcare and financial verticals drives investment as HIPAA and SEC compliance requirements demand specialized service-level guarantees.
- Messaging Services:Rich communication services with multimedia file transfer and location sharing capabilities.
- Multimedia Streaming:Buffer-managed content delivery with CDN edge caching for broadcast and on-demand video.
The dominant share belongs to Voice over IP, while Video Conferencing is closing the gap fastest.
Deployment Model:
Cost tier differentiation separates capital-intensive perpetual licensing from operational expenditure models with consumption-based scaling.
- Cloud-Based:Containerized network functions orchestrated through Kubernetes with horizontal autoscaling for traffic spikes. North American carriers prioritize this model to avoid hardware refresh cycles and reduce REACH/RoHS compliance exposure in European operations.
- On-Premises:Dedicated hardware appliances with five-year depreciation schedules and full operational control over physical security boundaries.
- Hybrid Solutions:Split control plane and user plane deployment with sensitive functions retained on-premises while traffic handling shifts to cloud infrastructure.
- Managed Services:Third-party operation of core network functions with outcome-based service-level agreements and professional services integration.
Cloud-Based deployment attracts the largest capital allocation, though Hybrid Solutions are expanding most quickly among tier-two operators seeking staged migration paths.
End User:
Customer type determines procurement complexity, with regulated industries demanding specialized compliance certifications and multi-vendor interoperability testing.
- Telecommunications Providers:Tier-one and tier-two carriers with national numbering plan obligations and universal service requirements. German operators refresh IMS cores to satisfy FCC-equivalent interconnection mandates during copper network retirement.
- Enterprises:Mid-market and large corporations consolidating unified communications onto SIP trunking architectures with session border controller integration.
- Government Agencies:Public sector entities with classified communication requirements and domestic-only routing constraints.
- Educational Institutions:Universities and research networks with high-volume video collaboration needs and limited capital budgets.
Telecommunications Providers command the majority of vendor attention, yet Enterprises are gaining share fastest as channel intermediaries displace direct OEM relationships.
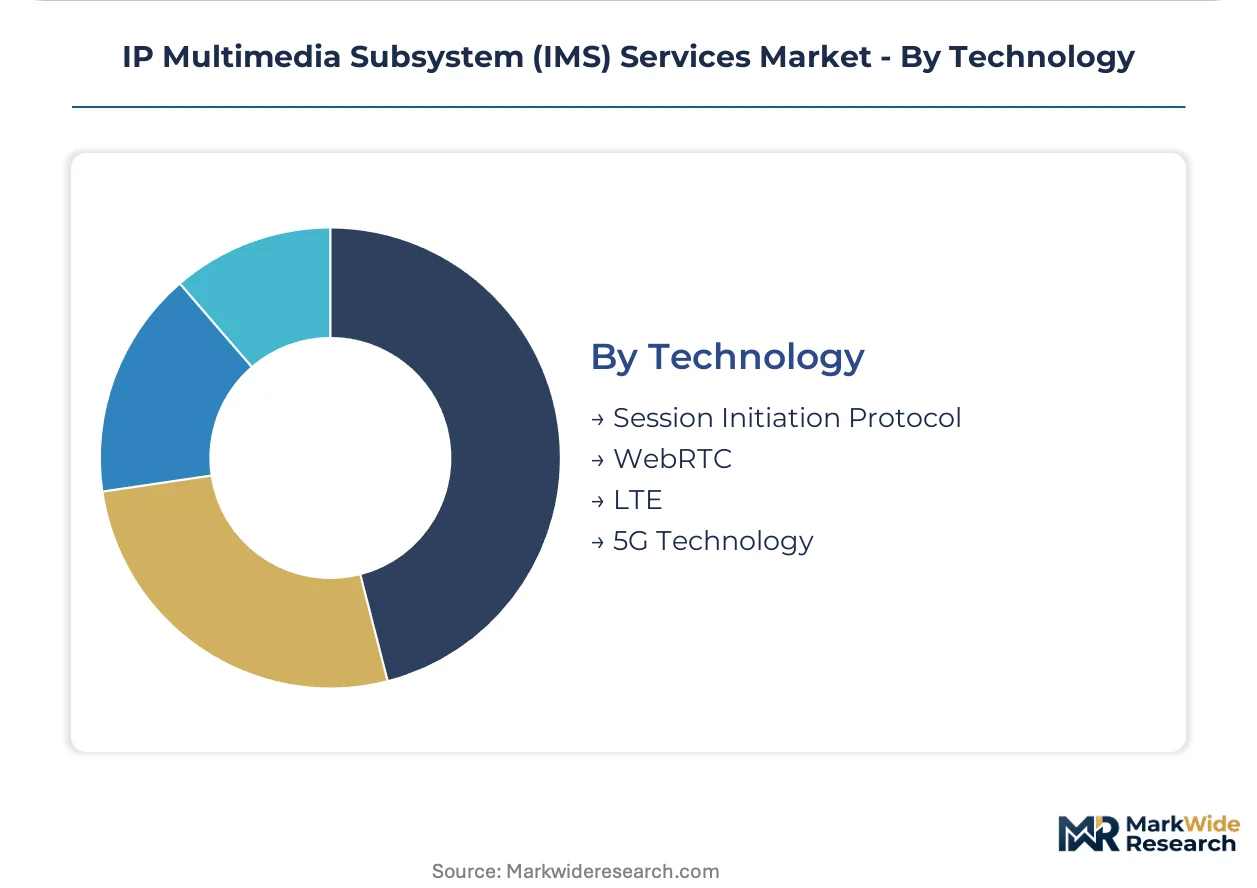
Technology:
Maturity curves separate established protocols with deep engineering talent pools from emerging standards with compressed certification timelines.
- 5G Technology:Standalone core architectures with service-based interfaces and network exposure functions for third-party service integration. South Korean carriers deploy these for voice-over-5G launches, collapsing traditional control-user plane separation.
- Session Initiation Protocol:Mature call signaling protocol with extensive interoperability testing and established diameter interface specifications.
- WebRTC:Browser-native real-time communication without plugin dependencies, enabling embedded video in web applications.
- LTE:Evolved packet core interworking for voice-over-LTE services during transitional 4G-5G coexistence periods.
Session Initiation Protocol retains the largest installed base, while 5G Technology shows the steepest expansion trajectory as standalone core rollouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German carriers consume IMS services through cloud-native procurement lenses while South Korean operators prioritize integrated radio-access bundles, revealing a transcontinental split in deployment philosophy that shapes vendor qualification requirements.
United States
North American carriers without legacy packet core investments drive greenfield 5G standalone builds. FCC universal service obligations preserve IMS-based voice as mandatory interconnection standards during copper network retirement. Channel intermediaries in Greater Boston and the Pacific Northwest displace direct OEM relationships among healthcare and financial enterprises seeking HIPAA and SEC-compliant voice recording.
Germany
REACH chemical substance restrictions and RoHS limitations constrain printed circuit board compositions for on-premises equipment. The country's national telecommunications regulator enforces interconnection standards equivalent to FCC mandates during PSTN sunsetting. Operators in North Rhine-Westphalia accelerate cloud migration timelines to reduce hardware certification exposure.
South Korea
3GPP Release 17 mandates compel operators to refresh IMS cores ahead of voice-over-5G service launches. The national telecommunications authority shapes product certification requirements for core network equipment through specification enforcement. Seoul Capital Area carriers deploy cloud-native architectures collapsing traditional control-user plane separation.
Japan
Multi-vendor interoperability certification requirements for diameter/HTTP interfaces fragment product development roadmaps. METI influences procurement specifications through standardization frameworks. Testing labs in Tokyo maintain divergent acceptance criteria that extend professional services engagement durations for enterprise SIP trunking deployments.
United Arab Emirates
Middle Eastern markets exhibit concentrated radio-access bundling that limits standalone IMS vendor access. The national telecommunications regulator oversees cross-border roaming harmonization requirements. Dubai-based operators anchor significant deployment volume through integrated infrastructure procurement models.
IP Multimedia Subsystem (IMS) Services Market Competitive Landscape
Capability concentration sits with integrated hardware vendors possessing deep packet core installed bases; scale advantage sits with cloud-native challengers competing on subscription pricing models. The vendor landscape organizes around three strategic archetypes: legacy equipment suppliers defending recurring support contracts, software-native specialists penetrating greenfield builds, and systems integrators capturing managed services relationships. Dominant competitive moves include restructuring licensing models around software subscriptions and consolidating subscriber data management functions into single-vendor accountability frameworks.
Within the integrated infrastructure tier, Huawei Technologies Co. Ltd. and Ericsson AB occupy positions shaped by geographic market access patterns. Mavenir Systems Inc. exemplifies the cloud-native challenger archetype competing on operational expenditure flexibility. ZTE Corporation and Nokia Corporation sit within the scale-driven segment where multi-country certification capabilities determine procurement eligibility. Samsung Electronics Co. Ltd. represents the convergence play anchoring significant deployment volume through bundled radio-access-to-core offerings.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd. |
| Ericsson AB |
| Nokia Corporation |
| Cisco Systems Inc. |
| Samsung Electronics Co. Ltd. |
| ZTE Corporation |
| Oracle Corporation |
| IBM Corporation |
| Mavenir Systems Inc. |
| Others |
Supply & Pricing Matrix
Overcapacity in European on-premises hardware manufacturing is compressing vendor margins while accelerating cloud-native procurement preferences among German carriers seeking to avoid REACH and RoHS compliance costs. This utilization imbalance feeds directly into pricing power shifts from integrated equipment suppliers toward software-native challengers competing on subscription economics.
Pricing Analysis
Long-term support contracts dominate incumbent vendor revenue, though project-based cloud-native deployments are gaining share among North American greenfield carriers. Price differentiation rests on certification tier—ETSI multi-country qualification commands premium positioning against single-market alternatives—and volume scale, with tier-one operators extracting favorable per-subscriber rates. Pricing pressure intensifies from Mavenir's aggressive SaaS-tiered undercutting of perpetual licensing models. Tier-two operators exhibit highest price sensitivity due to limited engineering budgets, while government agencies prioritize security certification over cost.
Supply Chain Analysis
Upstream feedstock for specialized IMS hardware concentrates in Taiwan for advanced semiconductor components, Germany for precision engineering of signaling equipment, and South Korea for memory-intensive network function virtualization platforms. Component dependencies include high-reliability server-grade processors, carrier-grade Ethernet switching silicon, and specialized Diameter interface chipsets. Single-source vulnerability persists in session border controller ASIC supply. Distribution runs through systems integrators with multi-vendor orchestration expertise rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as 3GPP Release 17 mandates force voice-over-5G core refreshes across Germany and South Korea before legacy PSTN sunset deadlines.
For Market Incumbents: Build installed-base lock-in through subscriber data management consolidation with policy control functions. Ericsson should deepen recurring support contract penetration across European tier-one operators facing copper retirement timelines. Defensive priority centers on cloud-native licensing restructuring to match Mavenir's subscription economics before greenfield 5G standalone decisions finalize. For New Entrants and Emerging Players: North American healthcare and financial verticals represent the most penetrable entry point for HIPAA and SEC-compliant managed IMS services. Channel intermediaries with compliance expertise displace direct OEM relationships in these segments. Go-to-market leverage rests on Kubernetes-native horizontal scaling demonstrations during traffic spike scenarios. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native challengers with greenfield 5G standalone footholds. Long-term viability favors vendors capturing multi-country ETSI certification for cross-border roaming harmonization. Acquisition target archetype: software-native specialists with container orchestration IP and existing North American carrier relationships. Signal to watch: divergence between regional 5G standalone deployment timelines and actual voice traffic migration patterns.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Licensing Restructuring | Subscription models displace perpetual sales, matching Mavenir's pricing posture in North American greenfield builds. |
| Multi-Country ETSI Certification | Cross-border roaming harmonization requirements in European Union procurement specifications favor certified vendors. |
| Subscriber Data Management Consolidation | Single-vendor accountability models reduce interoperability testing burden for tier-one German operators. |
| Managed Services Channel Development | Systems integrators with HIPAA and SEC expertise capture healthcare and financial vertical procurement in the United States. |
| Kubernetes-Native Horizontal Scaling | Traffic spike orchestration capabilities attract North American carrier capital seeking operational flexibility. |
Research Methodology
A standing panel of network architecture executives, IMS procurement leads at tier-one carriers, cloud-native platform engineers, and regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from 3GPP specification documents, FCC universal service obligation filings, ETSI framework publications, and national telecommunications regulator enforcement notices in Germany, South Korea, and Japan. Bottom-up deployment volume estimates triangulated against top-down carrier capex disclosures.
Scenario-bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, deployment model, end user category, and technology maturity. CAGRs derived from capacity investment alignment with voice traffic migration patterns, incorporating 5G standalone rollout velocity and legacy PSTN sunset regulatory deadlines as industry-specific forecast inputs.
Practitioners should monitor 3GPP Release 18 timeline shifts and divergent national copper retirement schedules for early signals requiring forecast revision. Cross-checking against disclosed carrier IMS core refresh announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Europe Contact Center As a Service (Ccaas) Market
Communication Services
Direct-To-Home (DTH) Satellite TV Services Market
Communication Services
In Flight Entertainment and Communication Market
Communication Services
Global Audio Communication Monitoring Market
Communication Services
Pcaas Market
Communication Services
Walkie Talkie Market
Communication Services
Mobile Messaging Market
Communication Services
Meeting Solutions Market
Communication Services
North America Postal Services Market
Communication Services
Video Managed Services Market
Communication Services
High Performance Message Infrastructure Market
Communication Services
Global Communications Interface Market
Communication Services
Voip Services Market
Communication Services
Dispatch Console Market
Communication Services
Video Conferencing Market
Communication Services
Postal Services Market