
 Global Communications Interface Market | 2026-2036
Global Communications Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Global Communications Interface Market Foresight
Industrial-grade interface certification is bifurcating the competitive landscape into mission-critical and consumer-grade supply tiers. Siemens leverages its embedded automation expertise to dominate ruggedized Ethernet and serial interface modules for factory floors. Cisco Systems anchors enterprise networking through deep control over proprietary protocol stacks and chassis-level integration.
A communications interface comprises the physical and logical boundary enabling signal exchange between electronic subsystems, typically specified by impedance tolerance, data rate bandwidth, and protocol state-machine compatibility. These components govern interoperability across telecom infrastructure, server backplanes, and avionics buses where bit-error-rate thresholds determine operational reliability. Wired Ethernet and PCIe interface types command the largest installed base, though wireless Bluetooth and Zigbee protocol segments are expanding fastest in edge IoT deployments where power budgets constrain physical layer selection. Optical deployment modes carry premium positioning in data center interconnects, while hybrid wired-wireless architectures capture margin pools in smart manufacturing environments requiring deterministic latency.
FCC equipment authorization rules shape US market access for radio-frequency interfaces, while EU REACH and RoHS directives constrain substance composition in connector plating and cable sheathing. China's MIIT enforces domestic GB standards for wireless protocol certification, creating parallel compliance tracks for vendors serving mainland network equipment vendors. Stakeholders must monitor divergence between regional electromagnetic compatibility regimes when architecting unified product platforms.
Market Dynamics
Hyperscale data center buildouts are compressing interface procurement cycles, forcing suppliers to align roadmaps with AI workload timelines rather than traditional enterprise refresh schedules.
Growth Catalysts
- EU AI Act compliance mandates:Cross-border data interface certification requirements under the EU AI Act are accelerating replacement cycles for non-compliant legacy installations across German and French telecom infrastructure.
- Hyperscale facility expansion:Data center operators in the United States, China, and Germany are deploying high-bandwidth optical interconnects to support GPU cluster scaling for generative AI training workloads.
- Edge IoT power constraints:Bluetooth Low Energy and Zigbee protocol adoption is expanding in battery-constrained industrial sensors, displacing wired alternatives in predictive maintenance deployments.
Market Restraints
- Copper and rare earth price volatility:Connector plating materials subject to supply concentration in Chinese processing facilities are squeezing margins for mid-tier module vendors.
- REACH substance restrictions:EU RoHS and REACH directives on cable sheathing compounds are forcing reformulation cycles that extend product qualification timelines by 8-14 months.
- Wireless spectrum congestion:Unlicensed 2.4 GHz band saturation in dense urban deployments is degrading effective throughput for Zigbee-based building automation networks.
Strategic Opportunities
- India manufacturing incentives:PLI scheme subsidies for electronics manufacturing are attracting interface module assembly capacity to serve domestic telecom and industrial automation demand.
- Deterministic wireless convergence:Time-Sensitive Networking over 5G private networks is opening hybrid wired-wireless architectures for smart manufacturing latency-critical applications.
- Optical co-packaging:Silicon photonics integration with switch ASICs is creating white space for co-packaged optical interface suppliers targeting next-generation data center spine fabrics.
Industry Challenges
- High-speed signal integrity engineering scarcity:Specialized talent for 112 Gbps PAM4 SerDes validation is concentrated among semiconductor vendors, constraining module house design velocity.
- Multi-jurisdiction certification stacking:Simultaneous FCC, CE, and MIIT GB standard compliance for unified product platforms is extending time-to-revenue for wireless interface launches.
- Legacy fieldbus integration complexity:Brownfield industrial sites running PROFIBUS and Modbus RTU are resisting Ethernet-APL migration due to rewiring capex and downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Communications Interface Market |
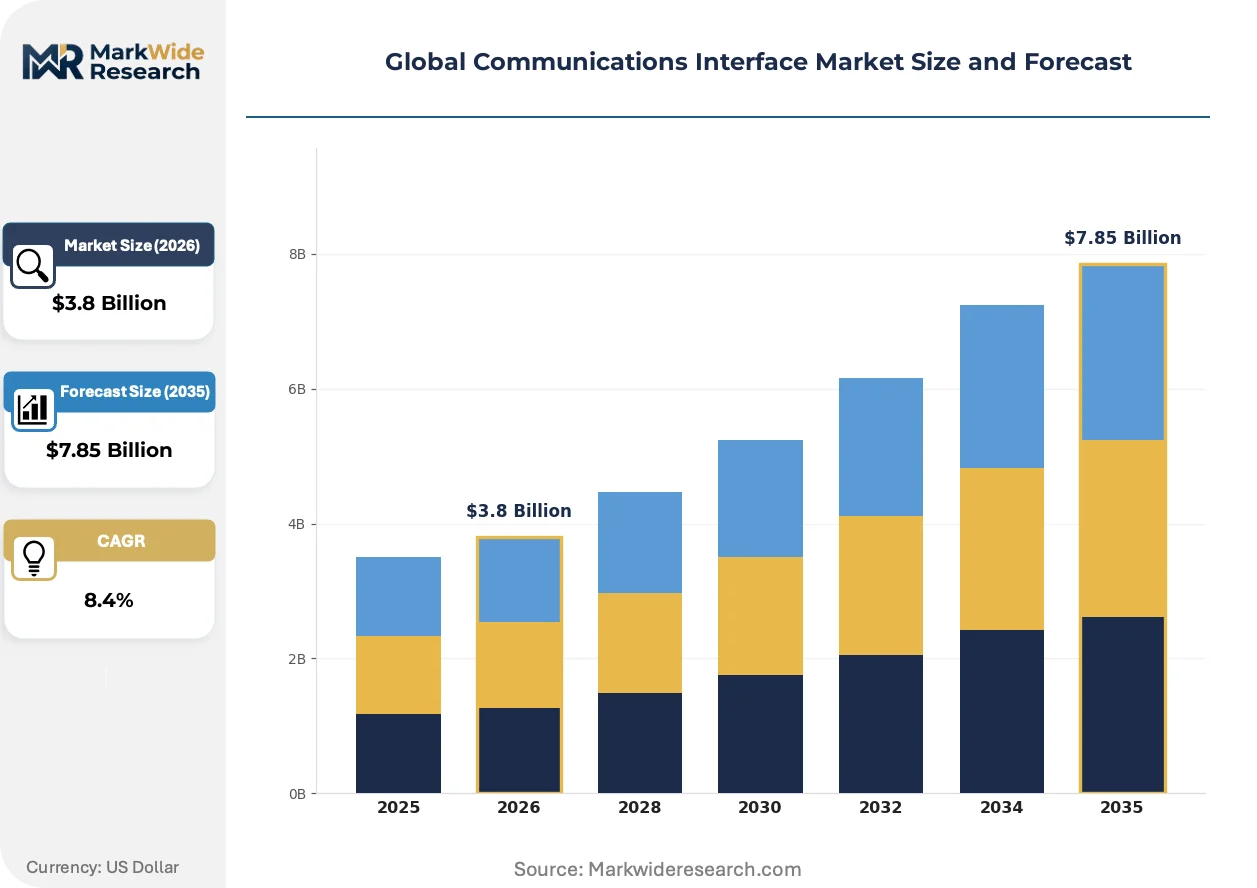
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Interface Type: USB, HDMI, Ethernet, Serial, PCIe, Thunderbolt Protocol: I2C, SPI, CAN, Bluetooth, Zigbee, NFC End User Industry: Telecom Operators, Data Centers, Network Equipment Vendors, Consumer Electronics Makers, Aerospace Systems Integrators Deployment Mode: Wired, Wireless, Hybrid, Optical, Satellite, Infrared |
| Companies Covered | Siemens, Qualcomm, Cisco Systems, IBM, Intel, ZTE, Juniper Networks, Oracle, Samsung, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Communications Interface Market Shifts & Advancements
Interface technology roadmaps are diverging between performance-maximized data center optics and power-minimized edge wireless, with certification regimes hardening the boundary between these domains.
Silicon photonics transceivers operating at 800 Gbps are bifurcating the data center interconnect market. Cloud operators deploying GPU clusters are standardizing on co-packaged optics to reduce switch power consumption. This technology compression is marginalizing traditional pluggable transceiver vendors in high-density spine applications.
China's MIIT GB standards for wireless protocol certification are tightening electromagnetic compatibility requirements for mainland network equipment. Domestic vendors must now complete separate test sequences from international FCC or CE tracks. Foreign module suppliers are responding by establishing localized testing partnerships in Shenzhen and Beijing.
Buyer consolidation among hyperscale operators is compressing interface procurement into direct strategic supplier relationships. Distributor and value-added reseller channels are losing share in high-volume Ethernet and optical segments. This channel restructuring is most visible in the United States, where Amazon Web Services, Microsoft Azure, and Google Cloud collectively account for dominant share of 400 Gbps+ port demand.
Global Communications Interface Market Segmentation
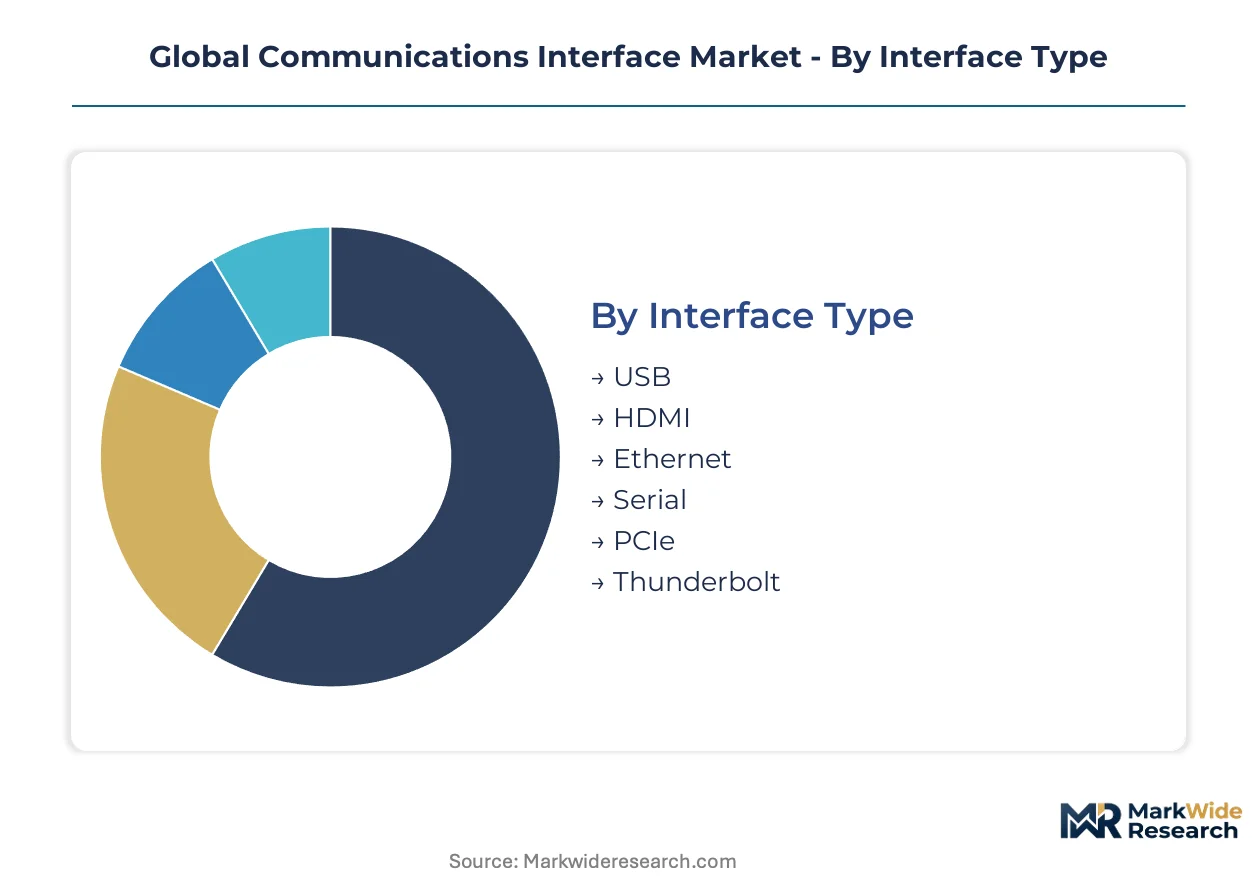
Communications interface procurement diverges sharply across application environments, with data center operators prioritizing bandwidth density while industrial buyers emphasize deterministic latency. Segmentation reveals how substitution pressures between wired and wireless architectures reshape vendor roadmaps and certification investments.
Interface Type:
Ethernet and PCIe face the most intense substitution pressure from optical interconnects in hyperscale facilities, while USB and HDMI defend entrenched positions in consumer and enterprise peripheral markets.
- Ethernet:Copper and optical physical layer variants dominate server rack interconnects and campus backbone infrastructure. Hyperscale operators in the United States and Germany are standardizing on 400 Gbps and 800 Gbps optical Ethernet for AI training clusters, compressing procurement cycles.
- PCIe:High-speed serial expansion bus protocol governs CPU-to-accelerator and storage device connectivity within server platforms. Data center operators in China are deploying PCIe Gen5 and Gen6 interfaces to support GPU memory bandwidth requirements.
- USB:Universal serial bus retains mass-market dominance for peripheral connectivity and charging applications.
- HDMI:High-definition multimedia interface controls consumer display and professional AV equipment signal transmission.
- Serial:RS-232 and RS-485 variants persist in industrial automation and legacy telecommunications equipment.
- Thunderbolt:Intel-licensed protocol converges PCIe and DisplayPort for high-performance workstation and external GPU enclosures.
Ethernet anchors the volume base while PCIe gains share at the steepest rate.
Protocol:
Protocol selection stratifies across power budgets, with battery-constrained edge deployments driving divergence from mains-powered infrastructure.
- Bluetooth:Short-range wireless protocol dominates audio streaming, mobile peripherals, and building automation sensor networks. Zigbee faces displacement from Bluetooth Low Energy in predictive maintenance sensors across German industrial sites due to simplified stack implementation.
- Zigbee:Mesh networking protocol targets home automation, smart lighting, and industrial sensor grids requiring extended range. FCC and MIIT GB certification divergence is fragmenting module supplier strategies for mainland China versus North American deployments.
- I2C:Two-wire serial bus connects low-speed peripherals to processors in embedded systems.
- SPI:Synchronous serial interface serves flash memory, display drivers, and sensor communication in microcontroller applications.
- CAN:Controller area network protocol underpins automotive and heavy machinery control systems.
- NFC:Near-field communication enables contactless payment and access control transactions.
Bluetooth commands the largest installed base while Zigbee expands most quickly in industrial mesh applications.
End User Industry:
Customer concentration among hyperscale operators compresses pricing power for module vendors serving data center and telecom verticals.
- Data Centers:Hyperscale facility operators in the United States, China, and Germany account for dominant share of 400 Gbps+ optical port demand. Direct strategic supplier relationships are displacing distributor channels, forcing component vendors to align roadmaps with AI workload deployment timelines.
- Telecom Operators:Mobile and fixed-line carriers in France and Germany are accelerating interface replacement cycles to meet EU AI Act cross-border data certification mandates.
- Network Equipment Vendors:Router and switch manufacturers source high-volume Ethernet and optical modules for enterprise and service provider markets.
- Consumer Electronics Makers:Smartphone, laptop, and peripheral manufacturers drive USB-C and wireless protocol integration.
- Aerospace Systems Integrators:Avionics bus and ruggedized interconnect suppliers serve deterministic latency requirements for flight control and mission systems.
Data Centers anchor the volume base while Telecom Operators drive replacement demand at the sharpest rate.
Deployment Mode:
Deployment architecture selection reflects power constraints, distance requirements, and electromagnetic interference tolerance across operating environments.
- Optical:Fiber-based transmission carries premium positioning in data center spine fabrics and metro transport networks. Co-packaged silicon photonics integration with switch ASICs is marginalizing traditional pluggable transceiver vendors in high-density applications.
- Wired:Copper Ethernet and serial interfaces retain cost advantages in short-reach enterprise and industrial deployments.
- Wireless:Unlicensed spectrum protocols serve mobile and battery-constrained sensor applications.
- Hybrid:Wired-wireless convergence architectures capture smart manufacturing environments requiring deterministic latency with installation flexibility.
- Satellite:Orbital and high-altitude platform links serve remote and maritime connectivity requirements.
- Infrared:Line-of-sight optical transmission persists in short-range control and sensing applications.
Wired deployment anchors the volume base while Optical gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale operators in the United States show the least price elasticity for 800 Gbps optical interconnects, while Indian telecom vendors face acute margin pressure on copper Ethernet modules under PLI scheme cost targets.
United States
Amazon Web Services, Microsoft Azure, and Google Cloud drive dominant share of 400 Gbps+ port procurement for AI training clusters. FCC equipment authorization rules shape market access for radio-frequency interfaces. Direct strategic supplier relationships in Northern Virginia and Dallas-Fort Worth data center corridors are displacing traditional distributor channels.
Germany
Telecom operators in Frankfurt and Munich are accelerating interface replacement cycles to meet EU AI Act cross-border data certification mandates. ECHA REACH directives constrain substance composition in connector plating and cable sheathing. Siemens anchors ruggedized Ethernet and serial interface production from its embedded automation facilities in Bavaria and Baden-Württemberg.
China
MIIT enforces domestic GB standards for wireless protocol certification, creating parallel compliance tracks for mainland network equipment vendors. Data center operators in Beijing and Shanghai deploy PCIe Gen5 and Gen6 interfaces to support GPU memory bandwidth requirements. Yangtze River Delta and Pearl River Delta clusters concentrate optical module assembly capacity for hyperscale facility expansion.
India
PLI scheme subsidies for electronics manufacturing attract interface module assembly capacity to serve domestic telecom and industrial automation demand. TRAI spectrum allocation frameworks shape wireless protocol deployment in smart city infrastructure. Tamil Nadu and Karnataka industrial corridors host emerging production facilities targeting battery-constrained Bluetooth Low Energy sensor modules.
South Korea
Samsung and domestic hyperscale operators anchor demand for high-bandwidth memory interfaces in AI semiconductor packaging. METI-aligned standards influence electromagnetic compatibility testing protocols for export markets. Seoul Capital Area and Busan-Ulsan clusters concentrate advanced SerDes validation talent for 112 Gbps PAM4 signal integrity engineering.
Global Communications Interface Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the communications interface market. Semiconductor vendors with captive SerDes IP concentrate high-speed signal integrity engineering scarce talent, while contract manufacturers in Asia-Pacific capture scale economies in module assembly. Two strategic archetypes dominate: integrated platform vendors controlling proprietary protocol stacks, and specialized component suppliers focusing on ruggedized industrial-grade certification. Competitive moves concentrate on silicon photonics co-packaging partnerships and geographic diversification of testing capacity to satisfy multi-jurisdiction certification requirements.
Among integrated platform vendors, Cisco Systems and Intel exemplify archetypes anchoring enterprise networking and server connectivity respectively. Siemens occupies a position representing industrial automation specialists with embedded expertise in factory-floor interface modules. These three companies illustrate how competitive positioning stratifies between protocol-stack control, silicon-level integration, and mission-critical certification depth.
| Leading Market Players |
|---|
| Siemens |
| Qualcomm |
| Cisco Systems |
| IBM |
| Intel |
| ZTE |
| Juniper Networks |
| Oracle |
| Samsung |
| Others |
Supply & Pricing Matrix
Scale economies in 800 Gbps optical transceiver production concentrate cost advantages among semiconductor vendors with captive SerDes IP, compressing price floors for mid-tier module houses while elevating entry barriers for new competitors. This concentration simultaneously tightens supply chain leverage for hyperscale buyers and squeezes margin recovery for contract manufacturers serving fragmented industrial accounts.
Pricing Analysis
EU AI Act compliance mandates dictate the pricing tier structure across the Global Communications Interface Market, separating premium-certified optical modules from standard-grade copper alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with CE-marked industrial Ethernet commanding substantial premiums over consumer-grade USB variants. Cost compression in copper-based serial interfaces is intensifying because Chinese rare earth processing concentration feeds raw material volatility. Telecom operators in Germany and France show the least price sensitivity for AI Act-compliant cross-border data interfaces, while Indian PLI-scheme beneficiaries face acute margin pressure meeting domestic cost targets.
Supply Chain Analysis
Strategic stockpiling of connector plating materials and optical subcomponents dominates inventory strategy among module vendors hedging against Chinese rare earth export volatility. Manufacturing gravity centers on the Yangtze River Delta and Pearl River Delta for optical module assembly, with South Korea anchoring advanced SerDes validation capacity and Germany retaining ruggedized industrial-grade production. Supply chains draw from concentrated gallium arsenide wafer sources and specialized cable sheathing compounds subject to ECHA REACH reformulation cycles. Single-source vulnerability in 112 Gbps PAM4 signal integrity engineering talent constrains design velocity for emerging suppliers. Distribution runs through direct strategic relationships with hyperscale operators, displacing traditional distributor channels in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Communications Interface Market rewards players who control scarce high-speed signal integrity engineering capabilities, with talent concentration among semiconductor vendors creating persistent bottlenecks for module house expansion. This capability scarcity stratifies competitive returns between integrated platform owners and component specialists.
For Market Incumbents: Fortify control over proprietary protocol stacks and chassis-level integration to defend against silicon photonics co-packaging disruption from cloud operator direct sourcing. Deepen backward integration into optical subcomponent supply to mitigate Chinese rare earth processing concentration. Prioritize certification investment for EU AI Act compliance to capture replacement cycle premiums in German and French telecom infrastructure. For New Entrants and Emerging Players: Lead with deterministic wireless convergence architectures targeting smart manufacturing latency-critical applications where hybrid wired-wireless deployment remains underpenetrated. Establish localized testing partnerships in Shenzhen and Beijing to satisfy MIIT GB standard divergence from FCC and CE tracks. Pursue white-label module assembly contracts under India's PLI scheme subsidies to build scale before brand establishment. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among industrial automation specialists with embedded factory-floor certification depth, offering superior cash flow predictability than commodity optical module vendors. Target acquisition archetypes combining ruggedized Ethernet expertise with 5G private network integration capabilities. Watch hyperscale operator capex commitment timing as the inflection signal for 800 Gbps optical demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Co-Packaging Partnership | Cloud operators deploying GPU clusters standardize on co-packaged optics to reduce switch power consumption. |
| Multi-Jurisdiction Testing Capacity Expansion | Foreign module suppliers establish Shenzhen and Beijing partnerships to satisfy MIIT GB standard divergence. |
| Industrial-Grade Certification Investment | Siemens leverages embedded automation expertise to dominate ruggedized Ethernet for factory floors. |
| Direct Strategic Supplier Relationships | Hyperscale operators in Northern Virginia displace distributor channels for 400 Gbps+ port procurement. |
| Deterministic Wireless Convergence Development | Time-Sensitive Networking over 5G private networks opens hybrid architectures for smart manufacturing. |
Research Methodology
A spread of perspectives from data center procurement officers, industrial automation engineers, semiconductor R&D directors, and telecom infrastructure planners converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation drawing from FCC equipment authorization databases, ECHA REACH substance restriction filings, MIIT GB standard publications, and hyperscaler capex disclosure reports. Bottom-up module shipment tracking and top-down infrastructure investment analysis were triangulated to anchor volume estimates.
Segmentation dimensions modeled include interface type, protocol family, deployment mode, end-user industry vertical, and regional regulatory cluster across the projection horizon. CAGRs were derived from installed base growth rates, replacement cycle compression, and AI workload-driven bandwidth demand acceleration. Industry-specific forecast inputs incorporated GPU cluster scaling timelines and EU AI Act compliance deadline pacing.
Underlying assumptions cover hyperscale facility expansion continuity, rare earth supply stability, and certification regime alignment, with deviation risk concentrated in electromagnetic compatibility standard divergence and signal integrity engineering talent availability. Revision becomes warranted when hyperscale operator capex commitment timing or Chinese processing facility export controls cross thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Services
Global Critical Communication Market
Communication Services
Meeting Solutions Market
Communication Services
Consumer Communication Services Market
Communication Services
Global Enterprise Media Gateway Market
Communication Services
Voice Commerce Market
Communication Services
Push-To-Talk Market
Communication Services
Managed Communication Services Market
Communication Services
Dispatch Console Market
Communication Services
IP Multimedia Subsystem (IMS) Services Market
Communication Services
Communication Platform-As-A-Service (Cpaas) Market
Communication Services
Voip Services Market
Communication Services
Video Managed Services Market
Communication Services
Global Call Center Platform Market
Communication Services
Cloud Communication Platform Market
Communication Services
Advanced Television Systems Committee (ATSC) Broadcast Systems and Services Market
Communication Services
Postal Services Market